
 Asia-Pacific Security Screening Market | 2026-2036
Asia-Pacific Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Security Screening Market Outlook
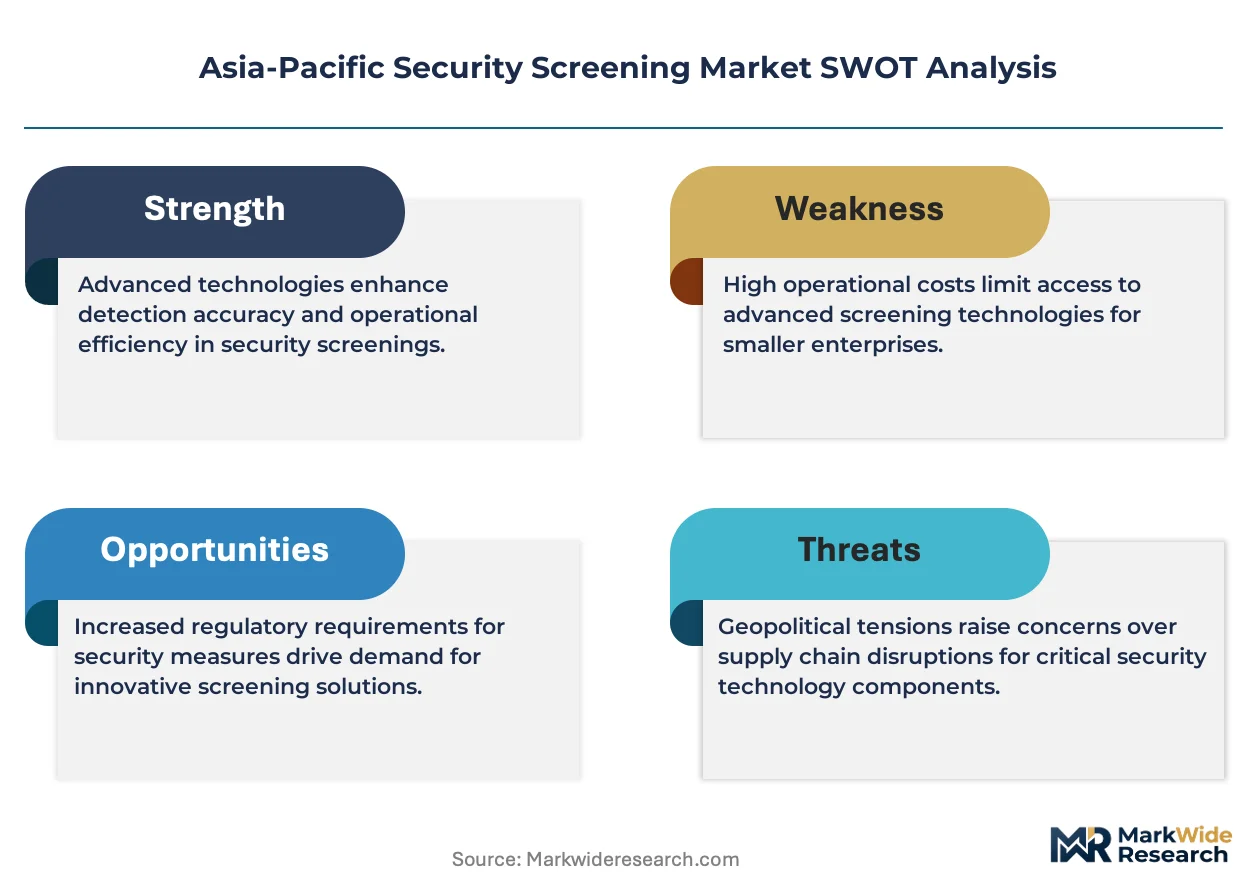
Buyer concentration among airport operators is shifting as secondary aviation hubs across Southeast Asia and South Asia procure independent screening fleets rather than relying on centralized national procurement. OSI Systems leverages its installed base of baggage inspection systems to sustain recurring maintenance contracts across Australian terminals. Nuctech Company Limited anchors its position through manufacturing scale and cost-competitive X-ray platforms tailored to budget-constrained border agencies. Smiths Detection Inc. differentiates via advanced threat detection algorithms that reduce false alarm rates at high-throughput checkpoints.
Security screening encompasses the automated inspection of persons, baggage, cargo, and vehicles using electromagnetic, acoustic, chemical, or biometric sensing modalities to detect weapons, explosives, contraband, or unauthorized access; systems typically operate at throughput rates exceeding 1,800 items per hour with detection thresholds measured in parts per billion for trace explosives. X-ray technology dominates installed volume across aviation checkpoints, though biometric modalities are gaining share where governments mandate identity verification at immigration control. Metal detectors remain mature with thin margin pools, while explosive detectors command premium positioning due to specialized sensor arrays and certification complexity.
China's MIIT enforces GB standards for radiation-emitting equipment, while India's BIS mandates electromagnetic compatibility certification for imported detection systems; Australia's TGA-equivalent infrastructure regulator imposes additional calibration protocols for critical transport nodes. Japan's METI coordinates voluntary JIS alignment with international IEC standards to facilitate cross-border equipment acceptance. Stakeholders must monitor evolving certification reciprocity agreements between national regulators to anticipate procurement eligibility shifts.
Market Dynamics
China's MIIT is tightening GB certification timelines for explosive detection systems, forcing manufacturers to accelerate sensor recalibration cycles while airport authorities across Southeast Asia and India front-load procurement ahead of anticipated standard upgrades.
Growth Catalysts
- India's metro rail expansion:The Delhi Metro Rail Corporation and Bengaluru Metro are deploying multi-layer screening arches at interchange stations, creating sustained demand for walk-through metal detectors with integrated facial recognition.
- MIIT GB standard enforcement:China's Ministry of Industry and Information Technology now mandates third-party validation for trace explosive detectors deployed at high-speed rail hubs, expanding the addressable market for certified equipment suppliers.
- Biometric convergence:Immigration checkpoints across Singapore, Thailand, and Vietnam are fusing fingerprint and iris capture with baggage screening workflows, requiring hardware upgrades at legacy terminals.
Market Restraints
- Sensor component concentration:Scintillator crystals for gamma-ray detection concentrate among Japanese and Chinese specialty chemical suppliers, exposing integrators to allocation risk during demand surges.
- Certification reciprocity gaps:India's BIS electromagnetic compatibility testing lacks mutual recognition with Australia's infrastructure regulator, forcing dual validation for equipment deployed across Commonwealth procurement frameworks.
- False-positive operational drag:Explosive trace detectors without machine-learning classification generate elevated alarm rates that choke throughput at India's congested Tier-2 airports.
Strategic Opportunities
- Indonesia's secondary aviation hubs:Yogyakarta International Airport and Kertajati International Airport are building independent screening fleets rather than relying on Jakarta-centric procurement, opening direct vendor relationships.
- Philippines smart city checkpoints:Davao and Cebu are integrating vehicle screening with urban traffic management systems, creating demand for under-vehicle inspection systems with automated license plate linkage.
- Japan METI-JIS alignment:METI's coordination of voluntary JIS standards with IEC frameworks is reducing technical barriers for Australian and Korean suppliers entering Japanese rail and port security tenders.
Industry Challenges
- Field service technician scarcity:X-ray tube replacement and detector array calibration require certified personnel that India's technical institutes are not producing at replacement rates.
- Legacy analog integration friction:Australian terminals with 1990s-era baggage lines face fiber-optic retrofit complexity when upgrading to digital threat-image projection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Security Screening Market |
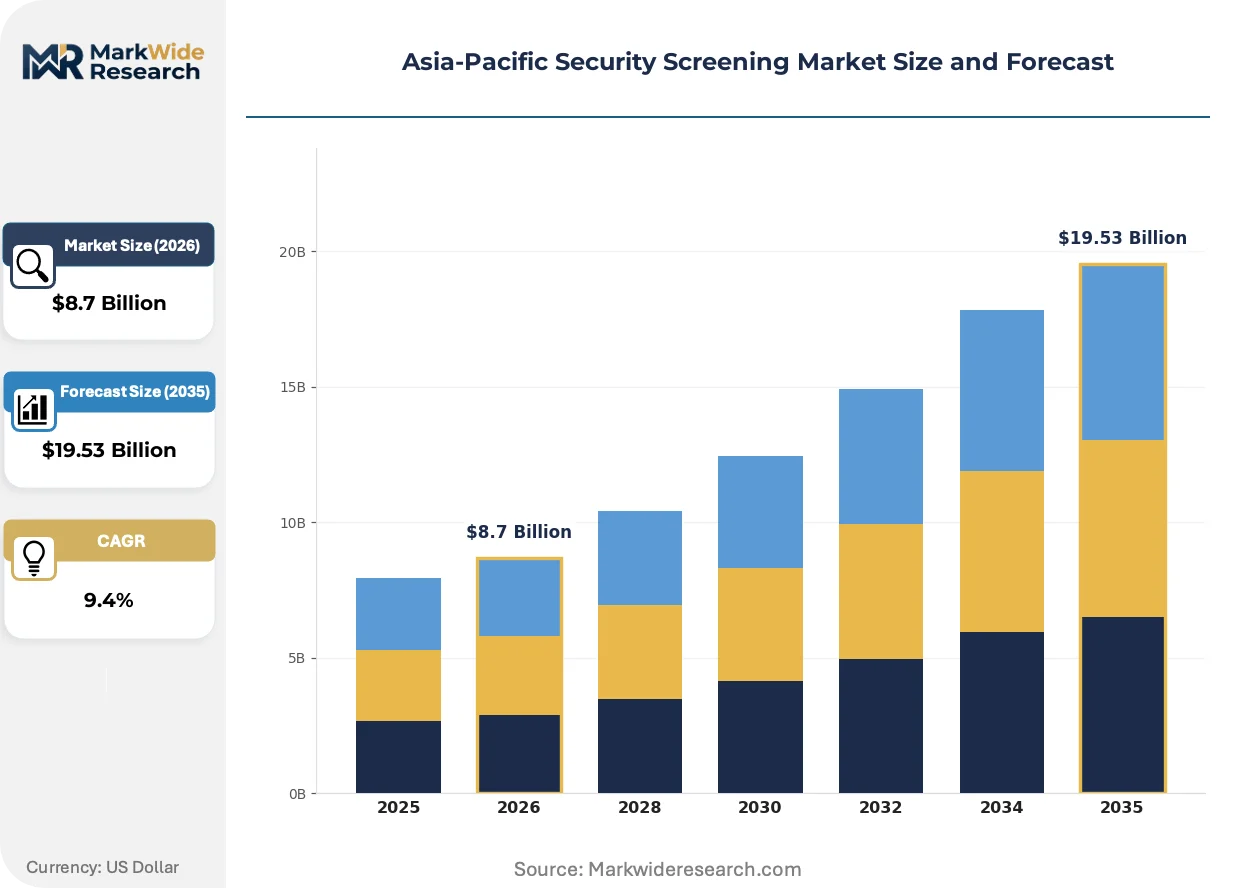
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, X-Ray, Metal Detectors, Explosive Detectors End User: Aviation, Government, Border Security, Critical Infrastructure Application: Public Safety, Event Security, Transportation, Cybersecurity Service Type: Consulting, Implementation, Maintenance, Training |
| Companies Covered | OSI Systems Inc., Analogic Corporation, L-3 Security and Detection Systems Inc., 3DX-Ray Ltd, Astrophysics Inc., Smiths Detection Inc., Nuctech Company Limited, Teledyne ICM SA, CEIA SpA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Security Screening Market Strategic Shifts
Computed tomography is penetrating aviation checkpoints at an accelerated pace, compressing the installed base of conventional dual-view X-ray systems while biometric fusion redefines passenger processing architectures across the region's hub airports.
Computed tomography baggage screening is absorbing market share from projection-based X-ray systems by delivering volumetric reconstruction that eliminates manual bag repositioning. Changi Airport and Sydney Kingsford Smith are deploying CT-enabled lanes at central security checkpoints, reducing passenger processing time by removing secondary inspection triggers for laptops and liquids. This technology is absorbing the premium segment of airport procurement budgets while relegating dual-view systems to regional and cargo applications.
China's MIIT is accelerating GB standard harmonization with IEC 62463 for radiation-emitting equipment, compressing the validation window for imported detection systems. Manufacturers must now submit scintillator performance data and dose-rate measurements to designated Chinese laboratories before rail hub deployment eligibility. Japanese suppliers with existing JIS certifications are leveraging METI-facilitated technical equivalence declarations to streamline MIIT approvals.
Airport authorities are consolidating screening equipment procurement under outcome-based service agreements rather than capital purchase models. Incheon International Airport and Hong Kong International Airport now contract for guaranteed throughput rates and false-alarm ceilings, transferring operational risk to system integrators. This shift is most visible in Southeast Asia, where budget-constrained secondary hubs prefer fixed monthly fees over upfront capital commitments that strain municipal financing capacity.
Asia-Pacific Security Screening Market Segmentation
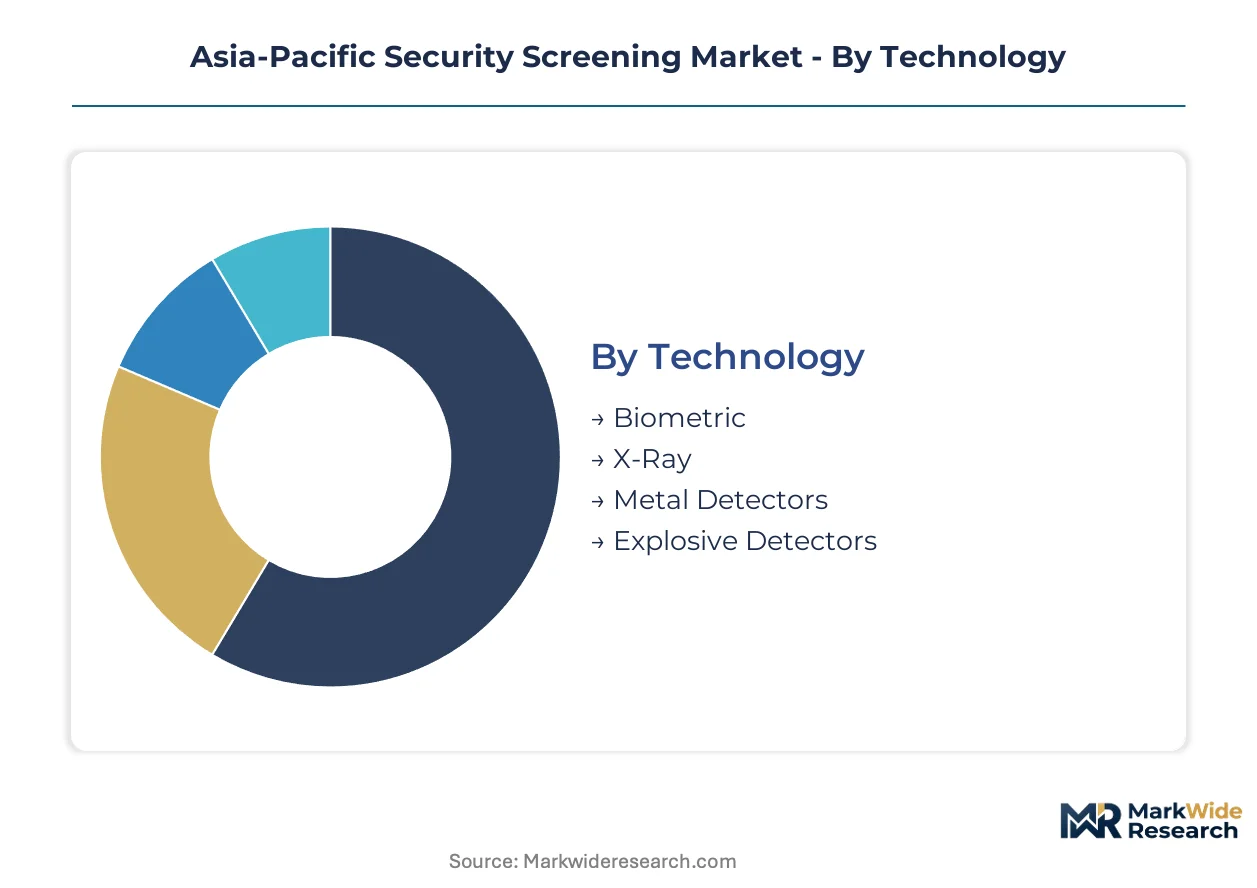
Technology choices in Asia-Pacific security screening reflect divergent procurement priorities across aviation hubs, rail networks, and smart city deployments. End-user concentration and application requirements dictate hardware specifications, certification complexity, and service attach rates.
Technology:
Buyers differentiate by detection modality, throughput requirements, and regulatory certification burden rather than unit cost alone.
- X-Ray:Dual-view and computed tomography systems dominate aviation checkpoints with volumetric reconstruction capabilities. Changi Airport and Sydney Kingsford Smith are absorbing CT-enabled lanes at central security checkpoints, compressing demand for conventional projection systems. X-Ray leads volumes today; Biometric is gaining share fastest.
- Biometric:Fingerprint, iris, and facial recognition modalities fuse with baggage screening at immigration control points. Singapore, Thailand, and Vietnam are mandating identity verification integration, forcing hardware upgrades at legacy terminals.
- Metal Detectors:Walk-through arches with integrated facial recognition serve metro rail interchanges in Delhi and Bengaluru. These systems command thin margin pools due to mature supply chains and minimal sensor differentiation.
- Explosive Detectors:Trace and bulk detection platforms deploy specialized scintillator arrays for parts-per-billion sensitivity. China's MIIT mandates third-party GB standard validation, expanding the addressable market for certified suppliers.
Cost tier separation is pronounced: explosive detectors capture premium positioning while metal detectors compete on replacement cycle efficiency.
End User:
Procurement authority concentrates differently across centralized national frameworks versus independent municipal operators.
- Aviation:Airport authorities across Southeast Asia and India front-load screening fleet procurement ahead of traffic recovery and anticipated standard upgrades. Secondary hubs in Indonesia and the Philippines are building independent capabilities rather than relying on Jakarta-centric or Manila-centralized purchasing.
- Border Security:Customs and immigration agencies in Australia, Singapore, and Hong Kong contract for guaranteed throughput rates and false-alarm ceilings under outcome-based service agreements.
- Government:Smart city checkpoints in Davao and Cebu integrate vehicle screening with urban traffic management systems, creating demand for under-vehicle inspection with automated license plate linkage.
- Critical Infrastructure:Rail hubs and power generation facilities across China and India deploy radiation-emitting detection systems under MIIT GB and BIS electromagnetic compatibility mandates.
Aviation commands the largest procurement budgets; Government applications are expanding most quickly through smart city integration.
Application:
Deployment context determines sensor configuration, environmental hardening requirements, and integration complexity with existing command infrastructure.
- Transportation:High-throughput checkpoints at rail terminals and airports require detection thresholds measured in parts per billion with operational rates exceeding 1,800 items per hour. India's congested Tier-2 airports struggle with false-positive operational drag from legacy explosive trace detectors.
- Public Safety:Urban surveillance networks and emergency response coordination centers demand mobile screening platforms with rapid deployment capabilities.
- Event Security:Temporary venues and international summits drive rental and short-term service contracts with accelerated installation timelines.
- Cybersecurity:Digital threat detection for screening system networks and data integrity protection at connected checkpoints represents an emerging overlay category.
Transportation absorbs the dominant share of hardware procurement; Cybersecurity is climbing the fastest as checkpoint digitization accelerates.
Service Type:
Revenue model preferences are shifting from capital purchase toward operational risk transfer and guaranteed performance metrics.
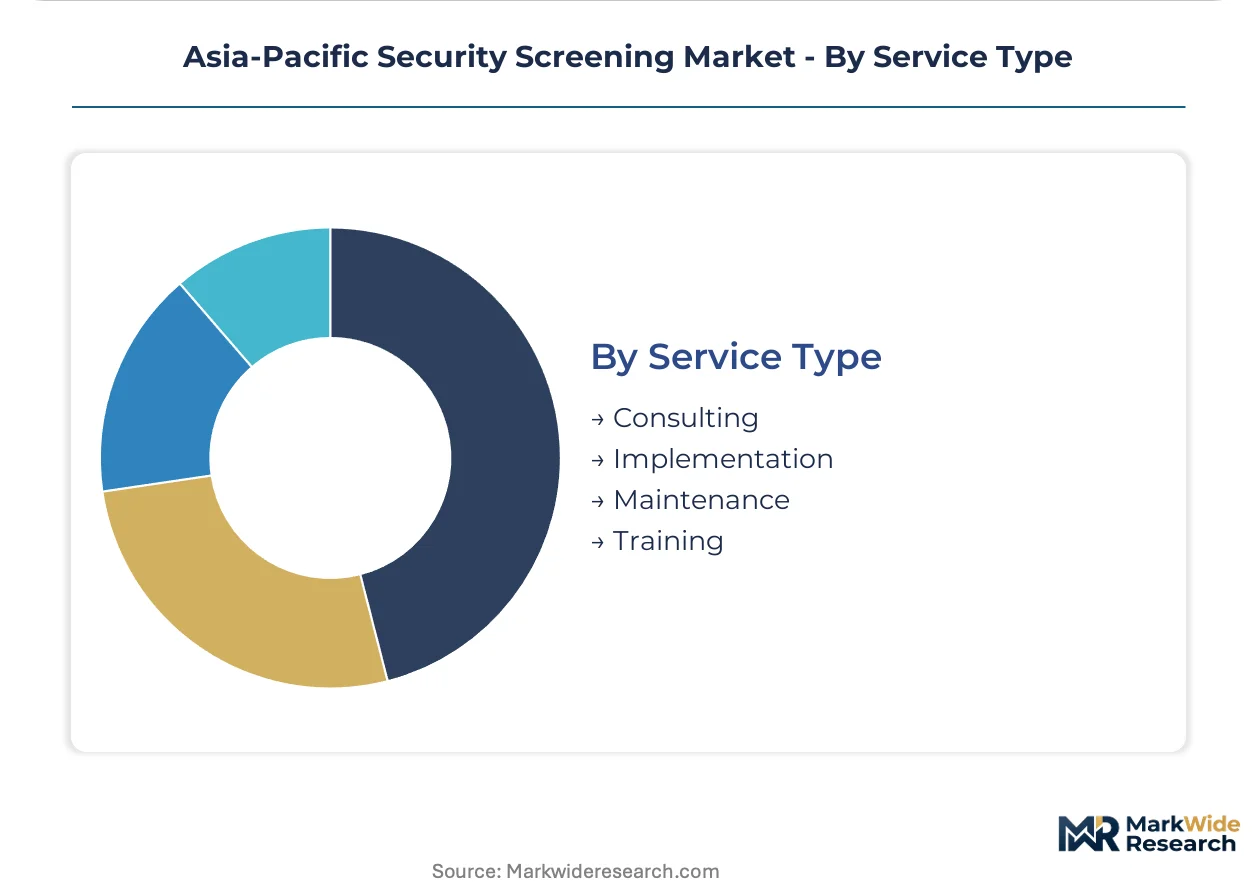
- Maintenance:Recurring service contracts for X-ray tube replacement and detector array calibration sustain vendor relationships across Australian terminals. Field service technician scarcity in India constrains expansion capacity.
- Implementation:System integration and legacy analog retrofit services address fiber-optic complexity at Australian terminals upgrading to digital threat-image projection.
- Consulting:Regulatory navigation support helps manufacturers manage MIIT GB certification timelines and BIS electromagnetic compatibility testing requirements.
- Training:Operator certification and recalibration protocol education addresses capability gaps in India's technical institute pipeline.
Maintenance represents the most mature revenue stream; Implementation services show the steepest expansion trajectory as digital upgrade cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification mandates are compressing deployment timelines for explosive detection systems, while India's metro rail authorities front-load procurement ahead of network expansion deadlines. Both countries anchor distinct demand vectors—regulatory compliance in China versus infrastructure build-out in India—shaping divergent procurement patterns across the region.
China
High-speed rail hubs in Beijing, Shanghai, and Guangzhou drive demand for radiation-emitting detection systems under MIIT's GB standard enforcement. The ministry now mandates third-party validation for trace explosive detectors, expanding the addressable market for certified equipment suppliers. Yangtze River Delta rail terminals are accelerating sensor recalibration cycles to maintain deployment eligibility.
India
The Delhi Metro Rail Corporation and Bengaluru Metro are deploying multi-layer screening arches at interchange stations, creating sustained demand for walk-through metal detectors with integrated facial recognition. BIS electromagnetic compatibility certification for imported detection systems adds validation complexity. Tier-2 airports in Hyderabad and Pune struggle with false-positive operational drag from legacy explosive trace detectors.
Japan
METI coordinates voluntary JIS alignment with international IEC standards to facilitate cross-border equipment acceptance for rail and port security tenders. Kanto region airports are consolidating screening equipment procurement under outcome-based service agreements with guaranteed throughput rates. Tokyo's technical equivalence declarations streamline approvals for suppliers with existing JIS certifications.
Australia
Sydney Kingsford Smith and Melbourne Tullamarine are deploying CT-enabled lanes at central security checkpoints, reducing passenger processing time by removing secondary inspection triggers. The country's infrastructure regulator imposes additional calibration protocols for critical transport nodes. OSI Systems leverages its installed base of baggage inspection systems to sustain recurring maintenance contracts across Australian terminals.
Indonesia
Yogyakarta International Airport and Kertajati International Airport are building independent screening fleets rather than relying on Jakarta-centric procurement, opening direct vendor relationships. Secondary aviation hubs across Java and Sumatra prefer fixed monthly fees over upfront capital commitments that strain municipal financing capacity. Customs agencies are fusing biometric capture with baggage screening workflows at immigration checkpoints.
Asia-Pacific Security Screening Market Competitive Environment
Chinese producers anchor one tier through manufacturing scale and cost-competitive platforms; US and European specialists hold premium positioning via advanced threat detection algorithms and established service networks. The vendor base stratifies across three tiers: integrated system houses with full modality portfolios, component specialists focused on sensor arrays and scintillator crystals, and regional fabricators serving budget-constrained procurement frameworks. Dominant competitive moves include outcome-based service contracting that transfers operational risk to integrators, and accelerated certification reciprocity navigation to secure MIIT and BIS approvals.
Within the integrated system tier, OSI Systems Inc., Smiths Detection Inc., and Nuctech Company Limited occupy anchor positions. OSI Systems exemplifies the maintenance-recurring model through sustained service contracts across Australian terminals. Smiths Detection represents premium-tier differentiation via algorithmic capabilities that reduce false alarm rates at high-throughput checkpoints. Nuctech anchors the scale-driven segment through manufacturing breadth and cost positioning tailored to budget-constrained border agencies across Southeast Asia.
| Leading Market Players |
|---|
| OSI Systems Inc. |
| Analogic Corporation |
| L-3 Security and Detection Systems Inc. |
| 3DX-Ray Ltd |
| Astrophysics Inc. |
| Smiths Detection Inc. |
| Nuctech Company Limited |
| Teledyne ICM SA |
| CEIA SpA |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals and associated green manufacturing mandates gate qualified supply for radiation-emitting detection systems, restricting premium-tier pricing access to manufacturers with verified low-carbon scintillator sourcing and MIIT-compliant calibration protocols.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing corridor are reshaping price floors for X-ray baggage inspection systems, compressing margins for legacy dual-view platforms while CT-enabled lanes command three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on GB certification tier and after-sales service bundling, with airport authorities in Southeast Asia exhibiting highest price sensitivity due to municipal financing constraints. Pricing pressure stems from Nuctech's manufacturing scale, forcing mid-tier vendors toward outcome-based service contracts to defend positioning.
Supply Chain Analysis
Field service technician scarcity across India's technical institute pipeline constrains expansion capacity for detector array calibration and X-ray tube replacement networks. Scintillator crystal production concentrates in Japan and China, while final system integration anchors in China's Pearl River Delta and South Korea's Incheon cluster. Supply chain risk centers on single-source vulnerability for gamma-ray detection arrays. Distribution runs through direct procurement relationships with airport authorities and national rail operators, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific security screening market reads as a late-cycle quality story, with procurement shifting toward CT-enabled platforms and biometric-fusion specifications that favor certified integrators over commodity hardware suppliers.
For Market Incumbents: Anticipate margin compression from Chinese manufacturing scale by deepening service attach rates at Australian terminals and accelerating JIS-MIIT certification reciprocity navigation. Prioritize backward integration into scintillator sourcing to offset allocation risk during demand surges at Indian rail hubs. For New Entrants and Emerging Players: Indonesia's secondary aviation hubs represent the most penetrable buyer archetype, with Yogyakarta and Kertajati airports building independent screening fleets outside Jakarta-centric procurement. Target outcome-based service contracting as the go-to-market angle, offering fixed monthly fees that align with municipal financing constraints. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because field technician scarcity and legacy retrofit complexity create captive revenue streams at Australian terminals. Focus acquisition screening on firms with MIIT GB validation and established maintenance contracts. Watch for BIS-recognition reciprocity agreements as the inflection signal for cross-border procurement eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CT Platform Migration | Changi Airport's deployment eliminates secondary inspection triggers, resetting throughput benchmarks. |
| Outcome-Based Service Contracting | Incheon International Airport transfers operational risk to integrators via guaranteed false-alarm ceilings. |
| Biometric Fusion Integration | Singapore's immigration checkpoints mandate fingerprint-iris capture with baggage screening workflows. |
| GB Certification Investment | MIIT's third-party validation requirement expands addressable market for certified explosive detector suppliers. |
| Backward Integration into Scintillators | Japanese specialty chemical suppliers leverage allocation control during demand surges at Chinese rail hubs. |
Study Parameters
Coverage spans China, India, Japan, Australia, and Southeast Asia, with primary inputs from each regional cluster combining interviews with airport procurement directors, rail authority technical officers, customs agency operations heads, and MIIT certification consultants. Secondary validation draws from BIS electromagnetic compatibility filings, MIIT GB standard publications, airport authority tender documents, and rail network expansion announcements. Bottom-up equipment deployment tracking triangulates against top-down national security infrastructure budgets.
Granularity-level modeling addresses technology modality, end-user procurement authority, application environment, and service revenue model across the projection horizon. CAGRs derive from unit deployment trajectories and average system pricing by certification tier. Industry-specific forecast inputs include high-speed rail hub construction timelines and smart city checkpoint integration mandates.
Inputs from Chinese regulatory filings and Indian metro rail procurement databases were available through the study window; gaps in real-time BIS testing queue data introduce uncertainty bands around India deployment timelines. Forecasts reflect assumptions on certification reciprocity progress and scintillator supply allocation stability. Material deviation in MIIT enforcement intensity or BIS-Australia mutual recognition negotiations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Global Contraband Detector Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Security Product Integration Services Market