
 Infrastructure Protection Market | 2026-2036
Infrastructure Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Infrastructure Protection Market Foresight
Modular security bundling is recalibrating how infrastructure operators evaluate vendor proposals, shifting procurement from standalone devices toward integrated platforms that combine detection, analytics, and response. BAE Systems leverages its defense heritage to anchor high-assurance government contracts across the United Kingdom and allied nations. Honeywell International sustains broad manufacturing scale in building automation and extends that footprint into critical facility protection. Thales competes on encrypted communications integration, positioning its offerings for transport and energy clients that require sovereign-data pathways.
Infrastructure protection encompasses the technologies, systems, and services designed to safeguard critical physical assets against deliberate attack, accidental damage, and natural disruption, incorporating hardened materials, redundant sensor networks, and real-time command interfaces that maintain operational continuity under stress. The category serves national security objectives, urban resilience planning, and commercial risk management across interconnected transport, energy, and communications grids. Video surveillance and AI analytics command the largest current revenue pools as municipalities and utilities prioritize automated threat recognition over human-monitored feeds. Cloud-based security represents the fastest-expanding technology segment, though margin concentration remains stronger in biometric systems where certification barriers limit vendor entry.
The U.S. Department of Homeland Security and the EU Critical Entities Resilience Directive shape compliance baselines for cross-border infrastructure operators, mandating risk assessments and minimum resilience standards that filter market access. NIST cybersecurity frameworks and ISO 27001 derivatives extend these requirements into digital-physical convergence zones where IoT sensors and control systems intersect. Stakeholders must weigh sovereign-data mandates against cloud-economy scale when selecting architecture partners for multi-decade asset protection programs.
Market Dynamics
AI-enabled threat detection platforms are compressing procurement cycles as utilities and transport operators replace reactive perimeter systems with predictive analytics that anticipate intrusion patterns before physical breach occurs.
Growth Catalysts
- EU Critical Entities Resilience Directive:Mandates risk assessments and minimum resilience standards for cross-border infrastructure operators, filtering vendor market access and elevating certified system integrators.
- Cloud-based security architectures:Municipalities in the United States and Germany are migrating video analytics and access control to sovereign-cloud environments, reducing on-premise hardware footprints.
- Aging utility network modernization:India's central electricity authority is driving replacement of analog grid protection systems with digital-physical convergence platforms that unify cyber and physical monitoring.
Market Restraints
- Semiconductor supply concentration:Specialized sensor chip fabrication concentrates in East Asian foundries, exposing perimeter hardware vendors to geopolitical disruption and extended lead times.
- Sovereign-data compliance friction:Operators must architect dual-stack systems satisfying both GDPR data-localization requirements and cloud-economy scale efficiencies, inflating integration costs.
- Legacy system interoperability:Decades-old SCADA and building management protocols lack native API connectivity, forcing expensive protocol-translation gateways for unified command interfaces.
Strategic Opportunities
- Underpenetrated Indian urban transit:Metro rail expansions in Mumbai, Bangalore, and Delhi lack integrated platform-vehicle-perimeter security, creating greenfield deployment opportunities for turnkey vendors.
- Biometric access convergence:Fusion of facial recognition with behavioral gait analysis is opening new contract categories at German nuclear facilities and UK critical national infrastructure sites.
- Outcome-based maintenance contracts:US municipal utilities are piloting performance-guarantee models where vendors assume uptime risk for integrated detection-response systems.
Industry Challenges
- Cyber-physical systems engineering talent scarcity:Vendors struggle to recruit specialists fluent in both OT network security and hardened physical perimeter design, delaying project delivery timelines.
- Multi-jurisdiction certification complexity:Products must sequentially obtain NIST cybersecurity framework validation, CE marking under EU machinery directives, and BIS certification for Indian deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrastructure Protection Market |
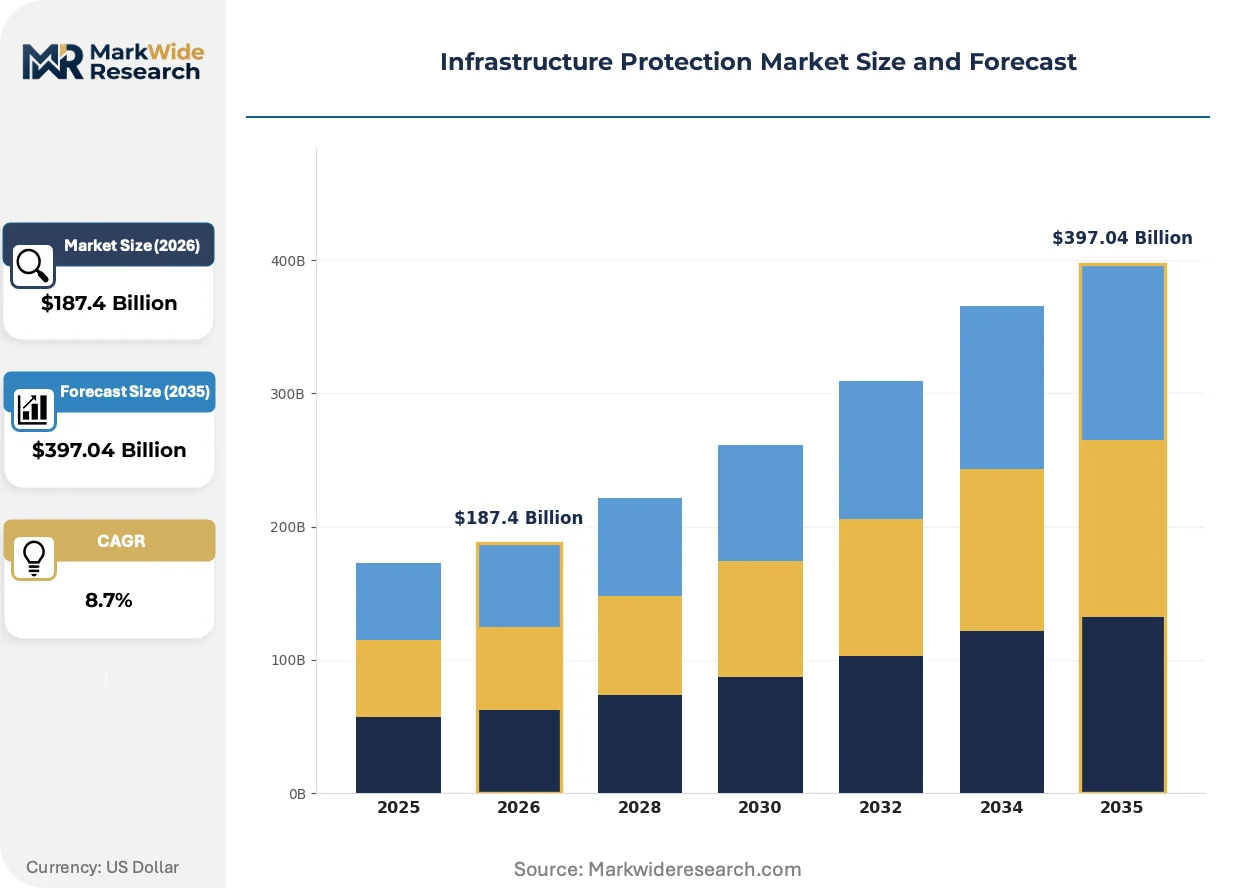
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
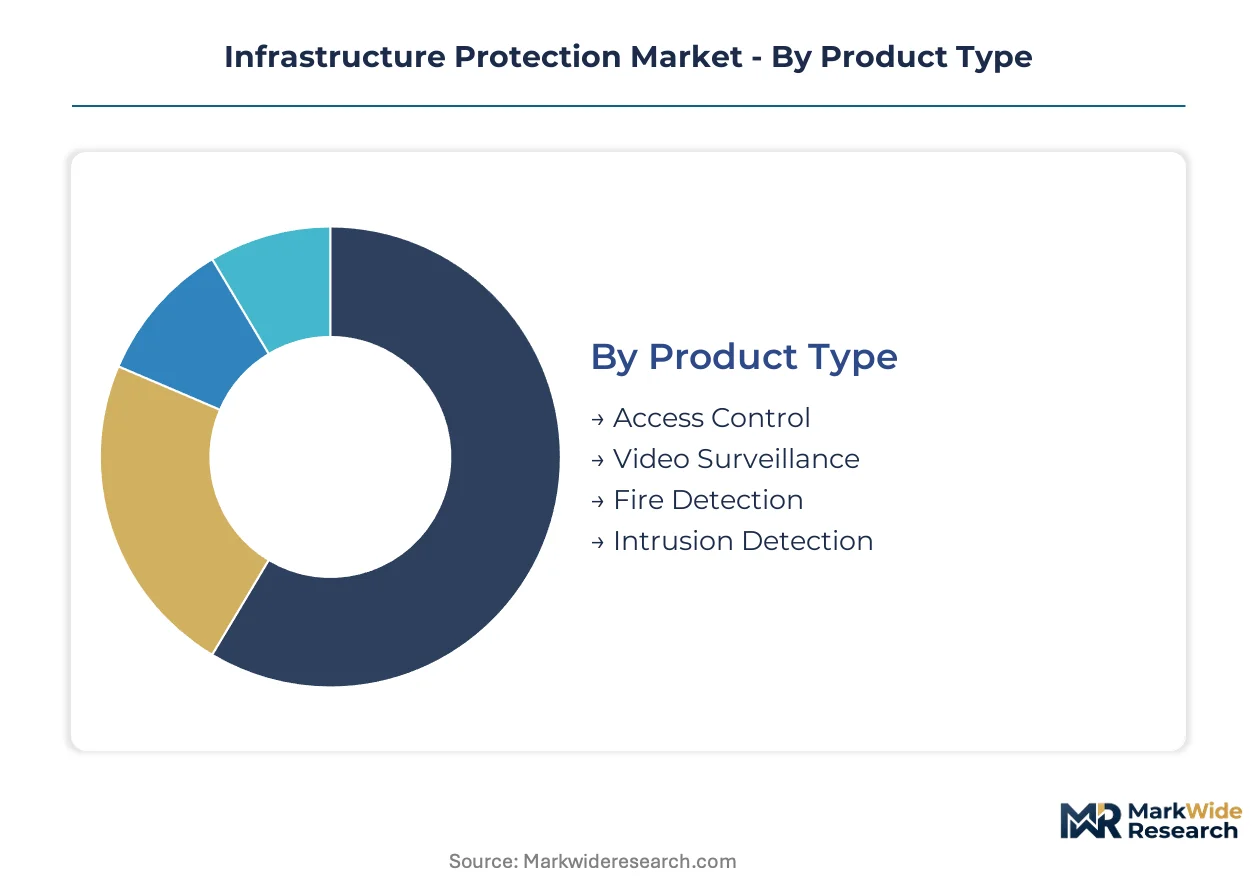
| Segmentation | Product Type: Access Control, Video Surveillance, Fire Detection, Intrusion Detection Application: Transportation, Utilities, Government, Commercial Buildings End User: Public Sector, Private Sector, Healthcare, Education Technology: IoT Solutions, AI Analytics, Biometric Systems, Cloud-based Security |
| Companies Covered | BAE Systems, Honeywell International, Lockheed Martin, General Dynamics, Northrop Grumman, Thales, Raytheon Technologies, Johnson Controls, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrastructure Protection Market Shifts & Advancements
Edge computing architectures are redistributing processing load from centralized data centers to field-deployed sensors, enabling sub-second threat response while reducing backhaul bandwidth requirements for distributed infrastructure networks.
Millimeter-wave radar combined with thermal imaging is electrifying perimeter detection capabilities at German chemical facilities and US power substations. Operators are replacing legacy fence-mounted vibration sensors with passive electronic scanning arrays that classify intruder type before physical contact. The technology is compressing false-alarm rates and reducing guard-force deployment density.
REACH chemical restrictions and RoHS substance limitations are forcing hardened enclosure manufacturers to reformulate coating and sealing compounds. European transport agencies are now specifying cradle-to-cradle material passports for security hardware deployed in tunnel and bridge environments. German rail operators have accelerated supplier audits to verify compliance with extended producer responsibility frameworks.
Buyers are unbundling installation from long-term service agreements, compressing vendor switching cycles. US state transportation departments now separate design-build contracts from ten-year maintenance performance bonds, enabling mid-term technology refresh without full system replacement. This pattern is most visible in California and Texas tollway authorities, where modular procurement templates allow component-level competitive rebidding.
Infrastructure Protection Market Segmentation
Infrastructure protection procurement diverges sharply by asset criticality and threat exposure. Operators match product tiers to consequence-of-failure calculations, creating distinct margin pools across hardened government installations versus commercial building retrofits.
Product Type:
Capital intensity concentrates in perimeter hardening and centralized command infrastructure, with wide variance between sensor-only deployments and integrated response systems.
- Access Control:Multi-factor credentialing systems with biometric readers and encrypted credential databases. Demand clusters at German nuclear facilities and Indian metro rail stations where CEA and BIS certification mandates drive specification rigor.
- Video Surveillance:IP camera networks with edge analytics and thermal fusion capabilities. US municipal utilities and UK critical national infrastructure sites are replacing analog coaxial systems with AI-enabled recognition platforms that compress false-alarm rates.
- Fire Detection:Aspiration sensors and linear heat detection for tunnel and substation environments.
- Intrusion Detection:Millimeter-wave radar and fence-mounted fiber-optic sensors for perimeter classification.
Video surveillance absorbs the bulk of installed capacity; access control is expanding most quickly.
Application:
End-use concentration follows sovereign spending patterns, with government-mandated resilience standards filtering vendor participation unevenly across sectors.
- Transportation:Integrated platform-vehicle-perimeter systems for rail, aviation, and tollway networks. Mumbai, Bangalore, and Delhi metro expansions lack unified security architectures, creating greenfield opportunities for turnkey vendors.
- Utilities:Converged cyber-physical monitoring for power generation, transmission, and water treatment. India's central electricity authority is driving analog-to-digital grid protection replacement, while German operators navigate REACH chemical restrictions on hardened enclosures.
- Government:High-assurance facilities requiring sovereign-data pathways and encrypted communications integration.
- Commercial Buildings:Scalable access and surveillance for multi-tenant office and retail complexes.
Utilities command the steepest expansion trajectory; transportation offers the largest untapped deployment base.
End User:
Procurement authority splits between centralized government budgets and distributed private capital, shaping contract scale and payment security.
- Public Sector:National infrastructure, defense installations, and municipal assets funded through sovereign budgets. US Department of Homeland Security grants and EU Critical Entities Resilience Directive compliance baselines elevate certified system integrators.
- Private Sector:Corporate campuses, data centers, and industrial facilities with risk-transfer insurance requirements.
- Healthcare:Hospital campuses with HIPAA-aligned access control and pharmaceutical cold-chain monitoring.
- Education:University and K-12 campuses balancing open access with emergency response protocols.
Public sector absorbs the bulk of installed capacity; healthcare is gaining share fastest.
Technology:
Architecture decisions pivot on data sovereignty requirements versus cloud-economy scale, creating dual-stack deployment patterns.
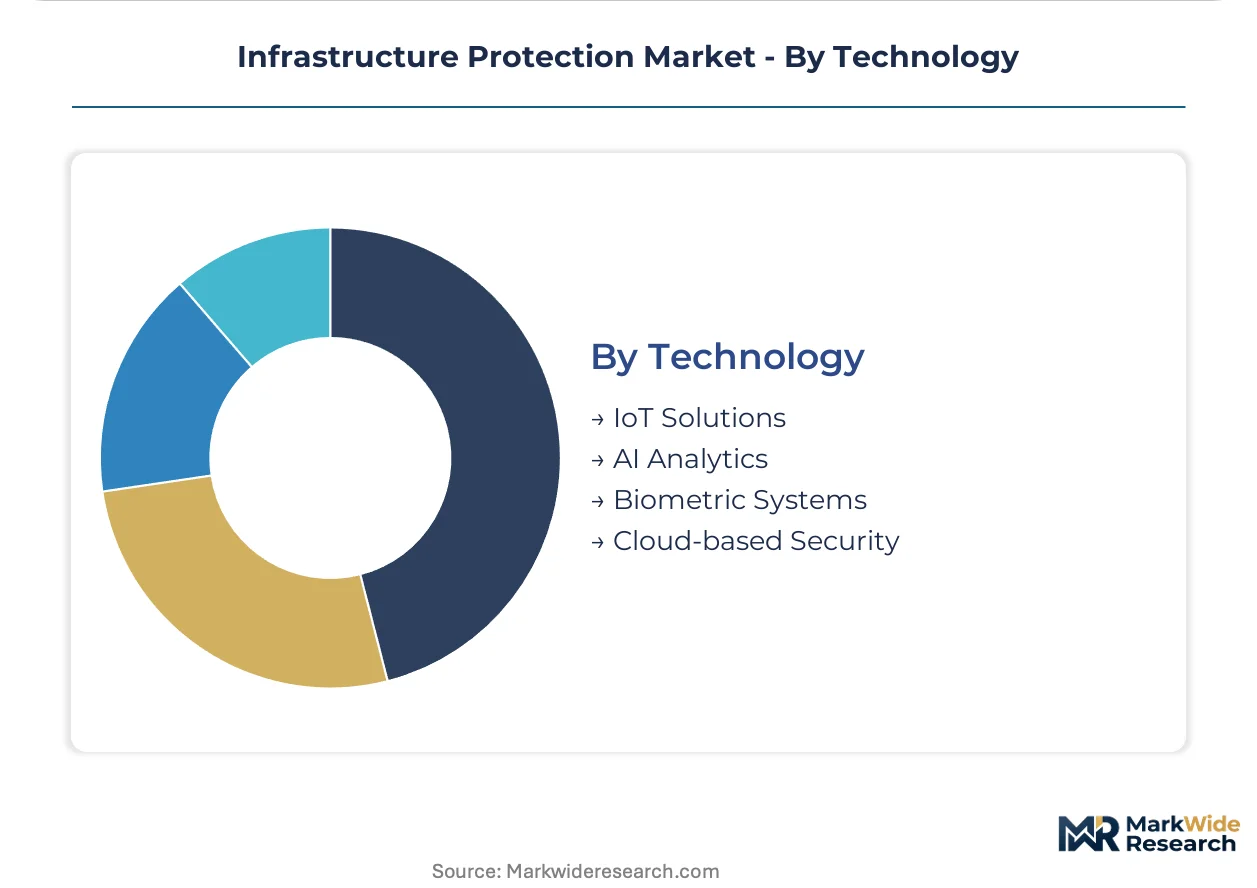
- IoT Solutions:Distributed sensor networks with low-power wide-area connectivity for remote substation and pipeline monitoring. German chemical facilities deploy millimeter-wave radar nodes with sub-second edge response capabilities.
- AI Analytics:Predictive threat recognition platforms that compress procurement cycles by replacing reactive perimeter systems. US state transportation departments pilot outcome-based maintenance contracts with performance guarantees.
- Biometric Systems:Facial recognition and behavioral gait analysis with certification barriers limiting vendor entry.
- Cloud-based Security:Sovereign-cloud video analytics and access control reducing on-premise hardware footprints.
IoT solutions absorb the bulk of installed capacity; cloud-based security is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of hardened perimeter systems and AI-enabled detection hardware concentrates in Germany, the United States, and Japan, while deployment demand clusters in India, the United Kingdom, and the United Arab Emirates as these markets modernize aging critical infrastructure against converged physical-cyber threats.
United States
Department of Homeland Security grants accelerate municipal utility modernization and tollway authority security upgrades. NIST cybersecurity frameworks mandate risk assessments for operators of critical infrastructure spanning power grids and transport networks. California and Texas state transportation departments pilot modular procurement templates that separate design-build contracts from long-term maintenance performance bonds.
Germany
Rail operators and chemical facilities drive demand for millimeter-wave radar and sovereign-data pathway solutions. REACH chemical restrictions and RoHS substance limitations force hardened enclosure manufacturers to reformulate coating compounds and verify extended producer responsibility compliance. Bavarian nuclear facilities and North Rhine-Westphalia transport hubs specify biometric access systems with behavioral gait analysis fusion.
India
Central Electricity Authority mandates drive replacement of analog grid protection with digital-physical convergence platforms across transmission and distribution networks. BIS certification requirements filter vendor participation in metro rail expansions. Mumbai, Bangalore, and Delhi metro systems lack integrated platform-vehicle-perimeter security, creating greenfield deployment opportunities for turnkey system integrators.
United Kingdom
Critical national infrastructure sites prioritize encrypted communications integration and sovereign-data compliance for transport and energy clients. Government-mandated resilience standards elevate certified integrators for high-assurance facility protection. London and Southeast England clusters concentrate demand for AI-enabled video analytics replacing analog coaxial surveillance systems.
United Arab Emirates
Smart city initiatives and critical facility expansions generate procurement for converged cyber-physical monitoring across power generation and water treatment assets. Data localization requirements intersect with cloud-economy scale efficiencies, forcing dual-stack architecture decisions. Dubai and Abu Dhabi municipal authorities specify cradle-to-cradle material passports for security hardware deployed in tunnel and bridge environments.
Infrastructure Protection Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels, creating a market structure where scale-driven building automation vendors intersect with defense heritage system integrators. Tier-one positions concentrate among entities with sovereign security clearances and multi-decade government contract track records. Three archetypes dominate: defense contractors leveraging classified program experience, industrial conglomerates extending manufacturing scale into facility protection, and encrypted communications specialists positioning for transport and energy data-pathway contracts. Consolidation pressure manifests through strategic partnerships bridging cyber-physical capability gaps and portfolio diversification into predictive analytics platforms.
Among defense heritage integrators, BAE Systems and Lockheed Martin occupy positions anchored by high-assurance government contract relationships across the United Kingdom, United States, and allied nations. Thales represents the encrypted communications archetype, with French S.A. structure indicating European sovereign-data pathway positioning for transport and energy sector clients. Honeywell International exemplifies the diversified industrial model, extending building automation manufacturing scale into critical facility protection through American Inc. corporate form.
| Leading Market Players |
|---|
| BAE Systems |
| Honeywell International |
| Lockheed Martin |
| General Dynamics |
| Northrop Grumman |
| Thales |
| Raytheon Technologies |
| Johnson Controls |
| Hexagon AB |
| Others |
Supply & Pricing Matrix
Backward integration into sensor chip fabrication anchors pricing power for perimeter hardware vendors serving critical infrastructure operators in the United States and Germany. This upstream control over specialized semiconductor inputs buffers margin pressure from East Asian foundry concentration while enabling premium positioning for AI-enabled detection platforms.
Pricing Analysis
Margin tightening in biometric access systems reflects REACH chemical compliance costs and BIS certification requirements that limit vendor entry. Three-tier pricing structure across certified-integrator, standard-system, and commodity-sensor levels separates sovereign-data pathway solutions from municipal utility deployments. Cost-down pressure on video analytics accelerates because German rail operators and US state transportation departments unbundle installation from long-term service agreements. Public sector buyers exhibit lowest price sensitivity given DHS grant funding and EU Critical Entities Resilience Directive compliance mandates; commercial building operators show highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Specialized sensor chip fabrication rests on Taiwanese, South Korean, and Japanese foundry capacity. Millimeter-wave radar components, thermal imaging arrays, and encrypted communications modules draw from German precision manufacturing and US defense-tier suppliers. Single-source vulnerability concentrates in advanced node semiconductor fabrication exposed to geopolitical disruption. Distribution runs through certified system integrators with sovereign security clearances rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cyber-physical systems engineering talent scarcity props pricing for integrated detection-response platforms. Capacity constraints in dual-competency workforce development sustain vendor margin premiums across the analysis window.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Pursue sequential NIST cybersecurity framework validation, CE marking under EU machinery directives, and BIS certification to filter competitor market access. Deepen backward integration into edge computing chip design to reduce East Asian foundry dependency. Counter modular procurement unbundling by anchoring ten-year maintenance performance bonds with technology refresh guarantees. For New Entrants and Emerging Players: Launch via outcome-based maintenance contracts piloted by US municipal utilities. Target underpenetrated Indian urban transit expansions in Mumbai, Bangalore, and Delhi metro systems lacking integrated platform-vehicle-perimeter security. Penetrate through turnkey system integration partnerships rather than component-only sales. For Investors and Strategic Acquirers: Exit pathways concentrate in defense heritage integrators with classified program experience and encrypted communications specialists positioning for sovereign-data pathway contracts. Long-term viability favors entities bridging cyber-physical capability gaps through strategic partnerships. Watch biometric access convergence adoption at German nuclear facilities and UK critical national infrastructure sites as inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Sequential NIST, CE, and BIS validation filters competitor access across US, EU, and Indian procurement channels. |
| Backward Integration into Edge Silicon | In-house sensor chip design reduces Taiwanese foundry exposure and compresses sub-second threat response latency. |
| Sovereign-Cloud Partnership Formation | Alliances with German and US sovereign-cloud operators satisfy GDPR localization without sacrificing analytics scale. |
| Biometric-Gait Fusion Development | Behavioral analysis integration opens contract categories at Bavarian nuclear facilities and UK critical infrastructure sites. |
| Outcome-Based Contract Piloting | Performance-guarantee models where vendors assume uptime risk align with California and Texas tollway procurement templates. |
Research Methodology
Document review covered customs and trade data for hardened perimeter equipment, SEC filings from diversified industrial conglomerates, EU Critical Entities Resilience Directive implementation guidelines, and Indian Central Electricity Authority grid modernization directives, complemented by interviews with critical infrastructure security directors, municipal utility procurement officers, system integration engineers, and sovereign-cloud architecture specialists. Secondary validation drew from NIST cybersecurity framework documentation, BIS certification registries, and REACH chemical restriction enforcement records. Bottom-up deployment estimates triangulated against top-down sovereign budget allocations.
Historical procurement patterns cross-referenced against expert panel input on AI-enabled threat detection platform adoption rates. Segmentation dimensions modeled include product type, application sector, end-user category, and technology architecture across the projection horizon. CAGRs derived from slope analysis of utility modernization spending curves and transport agency security upgrade cycles. Forecast inputs incorporated analog-to-digital grid protection replacement timelines and metro rail expansion security procurement schedules.
Geopolitical semiconductor supply disruption, regulatory certification timeline extensions, and sovereign-data mandate reinterpretation are the dominant revision risks for perimeter hardware deployment forecasts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market