
 Baby Food Packaging Market | 2026-2036
Baby Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Food Packaging Market Intelligence
The ISO 22000 food safety certification requirement is collapsing the distinction between food-grade and medical-grade polymer suppliers. Amcor leverages its global manufacturing footprint to serve multinational infant nutrition brands. In parallel, Mondi Group specializes in flexible paper-based solutions for the organic baby food segment, while Tetra Pak dominates the aseptic carton space for liquid formulas.
Baby food packaging encompasses primary containers engineered for the safe storage and dispensing of infant nutrition. These materials must provide a high oxygen and moisture barrier to preserve nutrient integrity and prevent microbial contamination. Flexible pouches represent the fastest-growing packaging type, displacing traditional glass jars in Stage 2 and Stage 3 food applications. While plastic holds the largest material share, paperboard and biodegradable polymers are gaining traction, driven by sustainability demands from parents and online retailers.
Regulations from the US FDA and the European Food Safety Authority (EFSA) mandate strict testing for material migration and contaminants like BPA. In China, national GB standards dictate material composition and labeling, shaping market access for all packaging formats. The critical decision for converters is how to invest in recyclable mono-material pouch technologies without compromising on shelf life or product safety.
Market Dynamics
The central tension shaping the baby food packaging market is the need to reconcile intense consumer demand for sustainable, eco-friendly materials with the non-negotiable safety and barrier-property mandates dictated by global food safety regulators.
Growth Catalysts
- Online Retail Channels:The expansion of e-commerce and subscription services for baby products creates demand for lightweight, durable, and single-serve formats like flexible pouches, which are more efficient for shipping than traditional glass or metal containers.
- Advanced Polymer Science:The commercialization of high-barrier biodegradable and bio-based polymers provides a pathway for brands to meet parental demand for sustainability without compromising on the critical oxygen and moisture protection required for nutrient preservation.
- Premiumization in Asia:Rising disposable incomes and a focus on infant nutrition in markets like China are fueling demand for premium and organic baby food, which in turn requires sophisticated packaging that signals safety and quality.
Market Restraints
- Material Qualification Costs:The significant investment and long timelines required to test and certify new polymers for food-contact safety, particularly for vulnerable infant populations, act as a barrier to rapid material innovation and adoption.
- Regulatory Fragmentation:Divergent standards for material composition and contaminant testing between the US FDA, European EFSA, and China's GB standards create compliance complexity and increase costs for manufacturers operating globally.
- Recyclability-Performance Tradeoff:Current mono-material structures designed for easier recycling often do not provide the same level of barrier protection or shelf life as established multi-material laminates, posing a technical hurdle for converters.
Strategic Opportunities
- Smart Packaging Integration:Incorporating QR codes for supply chain traceability or thermochromic inks that indicate temperature integrity offers a way to build consumer trust and differentiate products on the basis of safety and transparency.
- Circular Economy Models:Developing closed-loop collection and recycling programs specifically for baby food pouches presents an opportunity for brands to demonstrate environmental leadership and capture value from post-consumer waste streams.
- Aseptic Carton Formats:Expanding the use of aseptic paperboard cartons for liquid and semi-solid baby foods offers a recyclable alternative to plastic tubs and pouches, appealing to sustainability-focused consumer segments.
Industry Challenges
- Food-Grade Recyclate Scarcity:A primary operational hurdle is securing a consistent and verifiable supply of post-consumer recycled (PCR) plastics that meet the stringent purity standards required for direct contact with infant nutrition products.
- Capital-Intensive Line Conversion:Shifting production from traditional glass jar filling lines to flexible pouch or aseptic carton systems requires significant capital expenditure and retooling, slowing the transition for many manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Food Packaging Market |
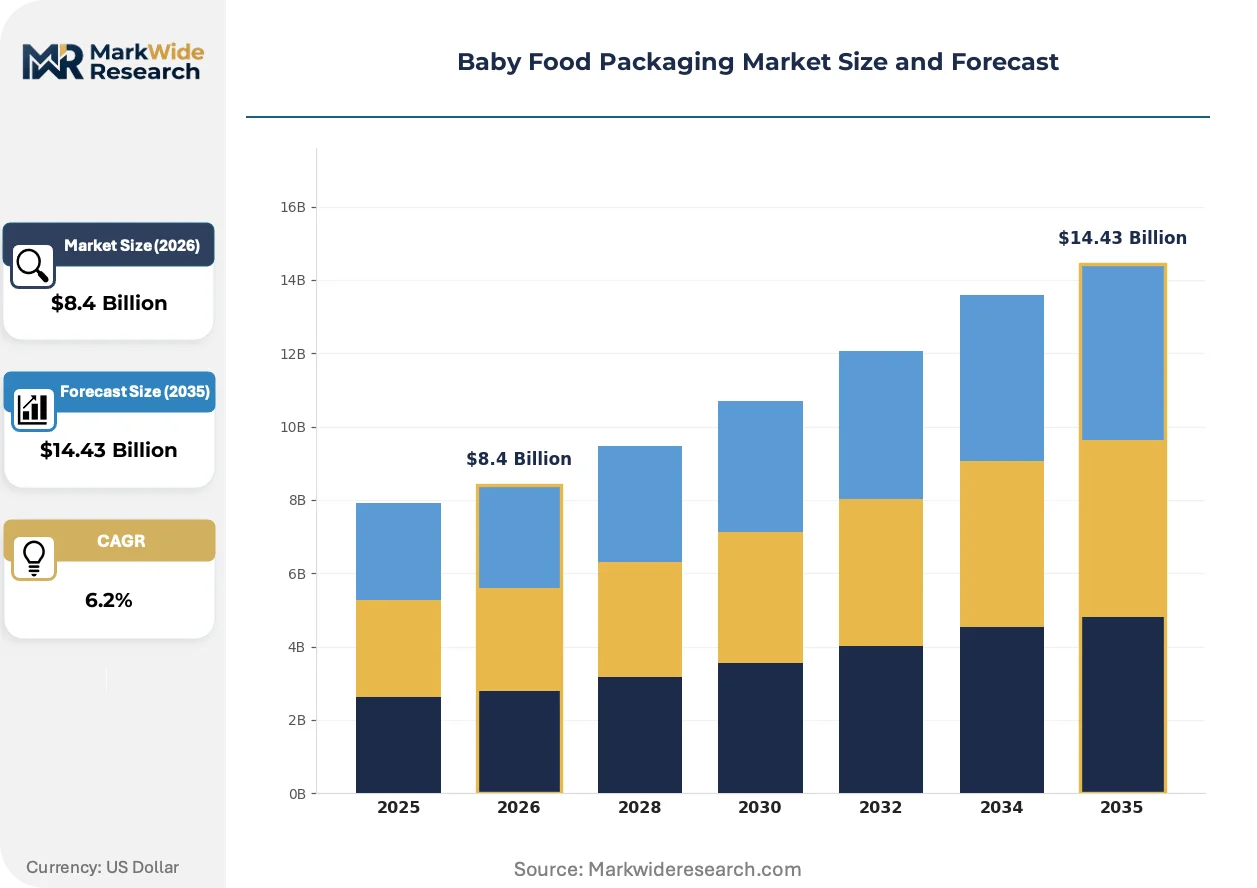
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Aluminum, Paperboard, Biodegradable Polymers Packaging Type: Jars, Pouches, Bottles, Cans, Trays Application: Infant Formula, Stage 1 Baby Food, Stage 2 Baby Food, Stage 3 Baby Food, Organic Baby Food End User: Parents, Childcare Centers, Specialty Retailers, Online Retailers, Pediatric Clinics |
| Companies Covered | Winpak Ltd, Greiner Packaging, Amcor, Mondi Group, Huhtamaki, Tetra Pak, Printpack, Ardagh Group, Sonoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Food Packaging Market Strategic Shifts & Innovations
Material science innovation is converging with tightening regulatory frameworks around circularity. This dynamic forces packaging converters and food brands to re-evaluate the entire product lifecycle, from polymer sourcing to end-of-life recyclability, balancing convenience with new environmental mandates.
High-barrier mono-material films, based on polyethylene or polypropylene, are engineered to offer a recyclable alternative to the unrecyclable mixed-polymer laminates common in flexible pouches. Major infant nutrition brands are cautiously piloting these new films for Stage 2 and Stage 3 foods. The slow but steady adoption of these materials is bifurcating the pouch segment into premium, fully recyclable offerings and legacy, lower-cost formats.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) proposal is a significant regulatory driver. It introduces stringent targets for recyclability and minimum recycled content, directly impacting packaging design for products sold in the EU. This is compelling pouch and lidstock manufacturers to accelerate investment in mono-material solutions and chemical recycling technologies to ensure future market compliance.
A pronounced shift toward direct-to-consumer (DTC) and subscription-based delivery models is altering packaging requirements. This channel bypasses physical retail shelves, reducing the need for rigid packaging and favoring lightweight, mail-friendly formats like spouted pouches and small cartons. The trend is most visible in North American and Western European markets, where parents increasingly purchase organic baby food through online platforms.
Baby Food Packaging Market Segmentation
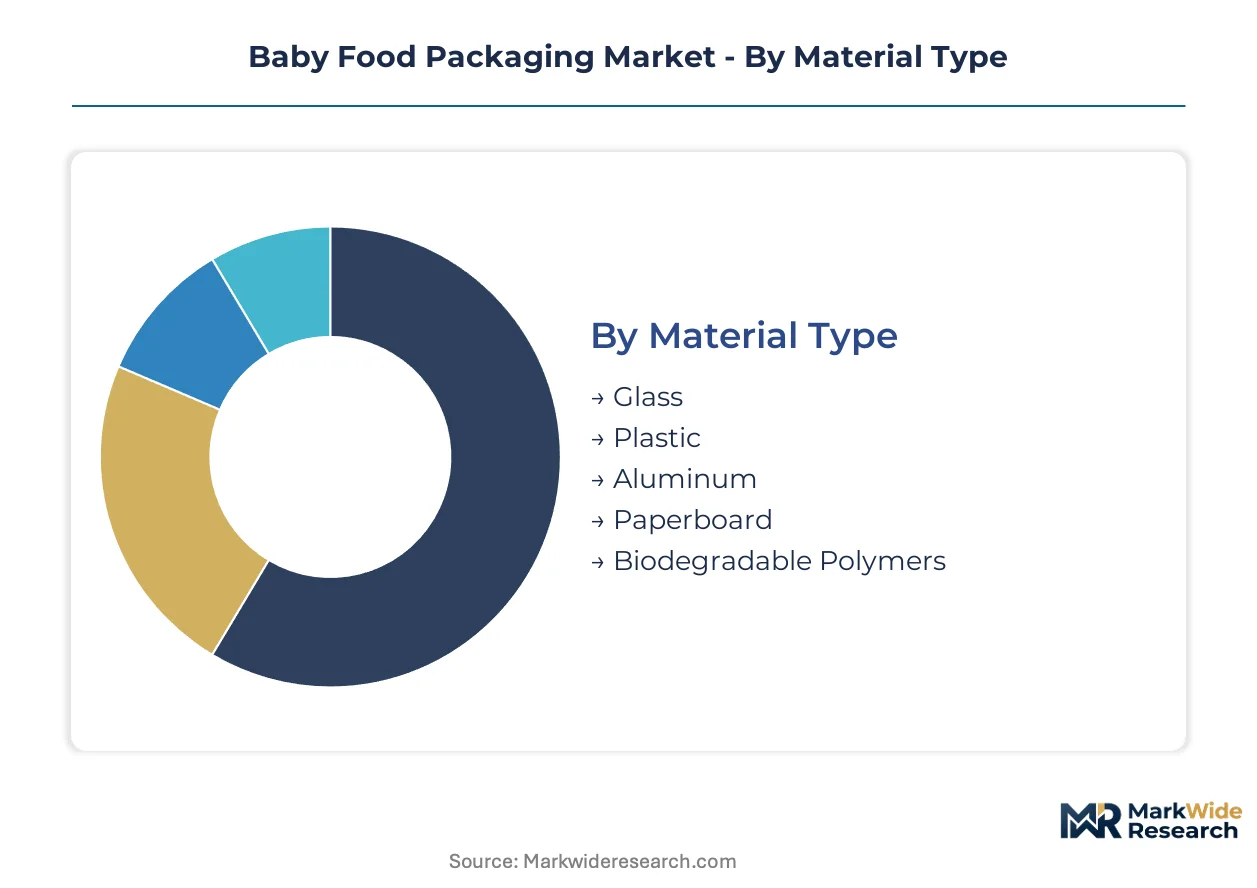
Market segmentation provides a granular view of the baby food packaging landscape, highlighting distinct opportunities and challenges across material types, packaging formats, applications, and end-user demands. Understanding these segments is critical for manufacturers to align product development and market penetration strategies with evolving consumer preferences and regulatory mandates.
Material Type:
The selection of packaging materials often dictates the shelf life and distribution channels for baby food products.
- Plastic:This material offers versatility and cost-effectiveness, providing essential barrier properties for many baby food products. Demand for plastic packaging is concentrating in online retail channels due to its lightweight nature and durability during shipping.
- Biodegradable Polymers:Engineered for sustainability, these advanced materials provide high oxygen and moisture barriers while reducing environmental impact. Consumer demand for eco-friendly options, particularly from parents in Europe, drives the adoption of these innovative polymers.
- Glass:Traditional glass jars offer excellent barrier protection and a premium perception for baby food, often favored by parents seeking inert packaging for purees.
- Paperboard:Used primarily for dry infant formula and some snack items, paperboard appeals to sustainability-conscious consumers and is gaining traction in markets like Germany.
- Aluminum:Aluminum cans provide robust protection against light and oxygen for powdered formulas, ensuring product integrity during extended storage and global distribution.
By volume, Plastic leads. By growth pace, Biodegradable Polymers are ahead.
Packaging Type:
Packaging formats are evolving to meet diverse consumer needs, particularly for convenience and portability across various feeding stages.
- Pouches:Flexible pouches, often with spouts, offer convenience and reduced weight, making them ideal for on-the-go consumption and Stage 2 and 3 baby foods. Their demand is driven by modern parents seeking easy-to-use, single-serve portions for their infants.
- Bottles:Primarily used for liquid infant formula and some purees, bottles require robust sealing and material integrity to prevent contamination. Innovations in aseptic filling technology are expanding their use for extended shelf life without refrigeration, appealing to global markets.
- Jars:Glass jars remain a staple for Stage 1 pureed baby foods, offering transparency and a perception of freshness for consumers in North America.
- Cans:Metal cans are widely employed for powdered infant formula, providing an airtight and moisture-proof environment crucial for preserving nutritional value.
- Trays:Multi-compartment trays are designed for toddler meals, offering portion control and separate components for more advanced feeding stages.
The market's structural evolution is heavily influenced by consumer preference for convenience and sustainability.
Application:
The specific nutritional requirements and feeding stages of infants dictate the specialized packaging solutions required for each application.
- Infant Formula:This application demands the highest safety and barrier standards to protect sensitive powdered or liquid formulations from oxygen, moisture, and contaminants. Manufacturers prioritize aseptic packaging and hermetic seals to ensure product integrity for newborns.
- Organic Baby Food:Products in this segment require packaging that reinforces their premium, natural image, often utilizing bio-based or recyclable materials. Demand for organic baby food is particularly strong in markets like China, where parents prioritize perceived safety and quality.
- Stage 1 Baby Food:Typically smooth purees, these products often utilize glass jars or simple pouches suitable for initial feeding.
- Stage 2 Baby Food:Featuring thicker textures and more complex flavors, this stage increasingly uses flexible pouches for ease of feeding and portability.
- Stage 3 Baby Food:Designed for toddlers, these products include finger foods and chunkier purees, frequently packaged in spouted pouches or small trays for self-feeding.
Brand differentiation strategies often center on packaging innovations within this segment.
End User:
Packaging requirements vary significantly depending on the purchasing entity and the consumption environment for baby food products.
- Parents:As the primary purchasers, parents demand convenient, safe, and easy-to-use packaging for home consumption and on-the-go feeding. Features like resealable closures and clear labeling are highly valued by parents in the US.
- Online Retailers:This segment requires lightweight, durable, and space-efficient packaging to optimize shipping costs and minimize damage during transit. Flexible pouches are particularly favored by e-commerce platforms and subscription services in Europe.
- Childcare Centers:These institutions often purchase in bulk, requiring sturdy packaging that facilitates easy dispensing and portion control for multiple children.
- Specialty Retailers:Focusing on premium and niche brands, these outlets prioritize aesthetically pleasing and sustainable packaging that aligns with their brand image.
- Pediatric Clinics:While not direct consumers, clinics often receive samples or promotional materials, requiring small, hygienic packaging formats for distribution.
The shift in purchasing habits towards direct channels significantly impacts packaging design for these end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union’s Packaging and Packaging Waste Regulation (PPWR) proposal is compelling packaging manufacturers globally to accelerate investment in sustainable solutions for baby food. This regulatory pressure, combined with evolving consumer preferences, drives regional packaging innovations and market dynamics. Each region exhibits distinct demand drivers and regulatory environments influencing material choices and format adoption.
United States
Parents in the United States prioritize convenience and safety, driving robust demand for flexible pouches and transparent glass jars for baby food. The US FDA mandates strict testing for material migration and contaminants in all infant nutrition packaging to ensure product integrity. New Jersey and California are centers for advanced packaging material development, focusing on high-barrier films and sustainable solutions for the industry.
China
Rising disposable incomes and a strong focus on infant nutrition fuel demand for premium and organic baby food, requiring sophisticated packaging solutions. China's national GB standards dictate material composition and labeling, shaping market access for all packaging formats. Shanghai's packaging industry is investing heavily in high-barrier mono-material films for infant formula and purees, catering to discerning consumers.
Germany
Consumers in Germany increasingly favor paperboard and biodegradable polymers for their strong sustainability credentials in baby food packaging. The EU Green Deal and PPWR proposal significantly influence packaging design, promoting circular economy models. Bavaria's food packaging sector is developing aseptic carton formats for liquid baby foods, catering to eco-conscious parents and retailers.
India
E-commerce expansion and rapid urbanization boost demand for lightweight, durable, and single-serve baby food formats across India. The FSSAI sets stringent food contact material standards to ensure infant safety and product integrity for packaged foods. The Delhi-NCR region sees significant investment in flexible packaging lines for baby food products, supporting online distribution channels.
Brazil
A growing middle class drives demand for convenient and affordable baby food packaging solutions, particularly spouted pouches for on-the-go consumption. ANVISA regulations govern the safety of food contact materials, including those for infant nutrition, emphasizing product protection. São Paulo's industrial cluster focuses on developing sustainable plastic alternatives and recyclable solutions for baby food.
Baby Food Packaging Market Key Industry Players
Player mix skews toward large, globally diversified packaging manufacturers alongside specialized flexible packaging providers. The market exhibits a tiered structure, with established players and innovative material science companies driving new solutions. Strategic archetypes include integrated solutions providers, sustainable material specialists, and aseptic packaging innovators. Dominant competitive moves involve strategic partnerships for advanced polymer development and capacity expansion into high-growth e-commerce channels.
Within the global diversified packaging tier, Amcor exemplifies a multinational presence, leveraging its extensive manufacturing footprint to serve major infant nutrition brands worldwide. Mondi Group, a European-based company, occupies a position as a specialist in flexible paper-based solutions, particularly appealing to the organic baby food segment and its sustainability demands. Tetra Pak, a Swedish-Swiss multinational, anchors the aseptic carton space for liquid and semi-solid formulations, providing critical packaging for extended shelf life products in global markets. These companies collectively demonstrate the varied approaches to meeting the complex demands of baby food packaging.
| Leading Market Players |
|---|
| Winpak Ltd |
| Greiner Packaging |
| Amcor |
| Mondi Group |
| Huhtamaki |
| Tetra Pak |
| Printpack |
| Ardagh Group |
| Sonoco |
Cost & Logistics Intelligence
Three-month lead times for high-barrier mono-material films often shape supply chain configurations and influence pricing power for specialized packaging converters. This dynamic creates pressure on brands to forecast demand accurately or risk supply disruptions for critical infant nutrition products.
Pricing Analysis
Certification level (ISO 22000, FDA-grade, EFSA-compliant) creates the primary spread in baby food packaging pricing. Contract-based long-term offtake agreements dominate for established brands, ensuring consistent supply and price stability. Price differentiation stems from material innovation, such as biodegradable polymers, and specialized barrier properties. Pricing softness reflects intense competition among flexible packaging converters seeking to secure large-volume contracts. Online retailers and subscription services represent the most price-sensitive buyer segments, while premium organic baby food brands exhibit lower price sensitivity.
Supply Chain Analysis
China and Germany anchor the global supply of specialized polymers and advanced packaging machinery for baby food. Raw material dependencies include polyethylene, polypropylene, and various bio-based feedstocks. A structural supply chain risk is single-source vulnerability for niche high-barrier films, particularly those requiring complex certification. Distribution runs through a blend of direct sales to multinational infant nutrition brands and indirect channels via regional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with integrated packaging design and material qualification services expanding faster than basic container sales. Brands seek comprehensive support to navigate complex regulatory landscapes and sustainability mandates.
For Market Incumbents: Consolidate market share by investing in advanced mono-material film production capabilities and securing long-term supply agreements for bio-based polymers. This defends against emerging sustainable packaging specialists and tightening regulatory mandates like the EU PPWR. Leverage global manufacturing footprints to offer localized production and reduce logistics costs for multinational infant nutrition brands.
For New Entrants and Emerging Players: Anchor in niche segments such as biodegradable pouches or aseptic cartons for organic baby food, particularly in European markets. Target specialized material science companies offering novel high-barrier solutions that meet evolving sustainability demands. A direct-to-consumer go-to-market angle can bypass established distribution channels and build brand loyalty with eco-conscious parents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core assets or specialized material science firms with patented sustainable polymer technologies. The long-term viability of the baby food packaging market remains strong due to non-discretionary consumer demand and stringent safety requirements. A signal to watch is the widespread commercial adoption of chemical recycling technologies for food-grade plastics.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-Material Film Production | Ensures compliance with future recycling mandates and reduces environmental impact for flexible packaging. |
| Secure Bio-Based Polymer Supply | Addresses consumer demand for sustainable materials and diversifies feedstock sources for packaging converters. |
| Expand Aseptic Carton Capacity | Offers a recyclable alternative for liquid baby foods, appealing to sustainability-focused consumer segments. |
| Integrate Smart Packaging Technologies | Builds consumer trust through enhanced traceability and product integrity verification for infant nutrition. |
| Develop Closed-Loop Recycling Programs | Demonstrates environmental leadership and captures value from post-consumer waste streams for packaging brands. |
Research Approach
Operator-level perspectives from packaging designers, infant nutrition brand managers, material scientists, and regulatory compliance officers anchored the qualitative base. This primary research was triangulated with secondary validation from national food safety authority reports, trade association publications, and company financial filings. The approach combined bottom-up market sizing with top-down validation to ensure comprehensive coverage.
Sensitivity analysis framed the forecast framework, evaluating market dynamics under varying regulatory and technological adoption scenarios across the analysis window. Segmentation dimensions modeled included material type, packaging format, application, and end-user demands, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data trends and projected shifts in consumer preferences and material science advancements. Key forecast inputs included the commercialization timeline for new biodegradable polymers and the expansion rate of online retail channels.
Material uncertainties — such as unforeseen regulatory shifts or breakthroughs in alternative packaging technologies — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research, acknowledging the inherent volatility of raw material costs. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
US Pet Food Packaging Market