
 Canada Bunker Fuel Market | 2026-2036
Canada Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Bunker Fuel Market Insights
High-sulfur fuel oil specification tiers is collapsing as post-IMO 2020 compliance standards reshape procurement across Canadian waters. Shell plc leverages its integrated supply chain to dominate bunkering operations at Vancouver's Inner Harbour. Chevron Corporation anchors its position through specialized MGO distribution networks serving the British Columbia ferry fleet. TotalEnergies SE competes aggressively on low-sulfur IFO380 supply contracts with major transpacific shipping lines.
Bunker fuel denotes heavy residual oil products refined for marine propulsion systems, with IFO380 requiring viscosity control at 380 centistokes and MGO meeting strict sulfur content thresholds below 0.10% for emission control areas. These fuels power commercial shipping engines, auxiliary generators, and boiler systems across cargo, passenger, and industrial marine fleets. IFO180 retains mature volume leadership in deep-sea commercial shipping routes due to cost efficiency on long-haul voyages. MGO captures expanding share among cruise operators and coastal ferry services where port emission restrictions tighten fastest. Direct sales channels concentrate margin pools through long-term supply agreements with tier-one shipping lines, while broker networks fragment pricing transparency across smaller offshore vessel operators.
Health Canada and PMRA enforce environmental compliance protocols aligned with federal marine protection standards, while Transport Canada administers the Vessel Pollution and Dangerous Chemicals Regulations governing fuel quality at Canadian ports. The International Maritime Organization's Annex VI framework shapes product specifications through emission control area designations covering the North American coast. Stakeholders must monitor scrubber technology deployment rates and alternative fuel pilot programs to anticipate shifts in residual fuel demand versus distillate substitution across Canadian bunkering hubs.
Market Dynamics
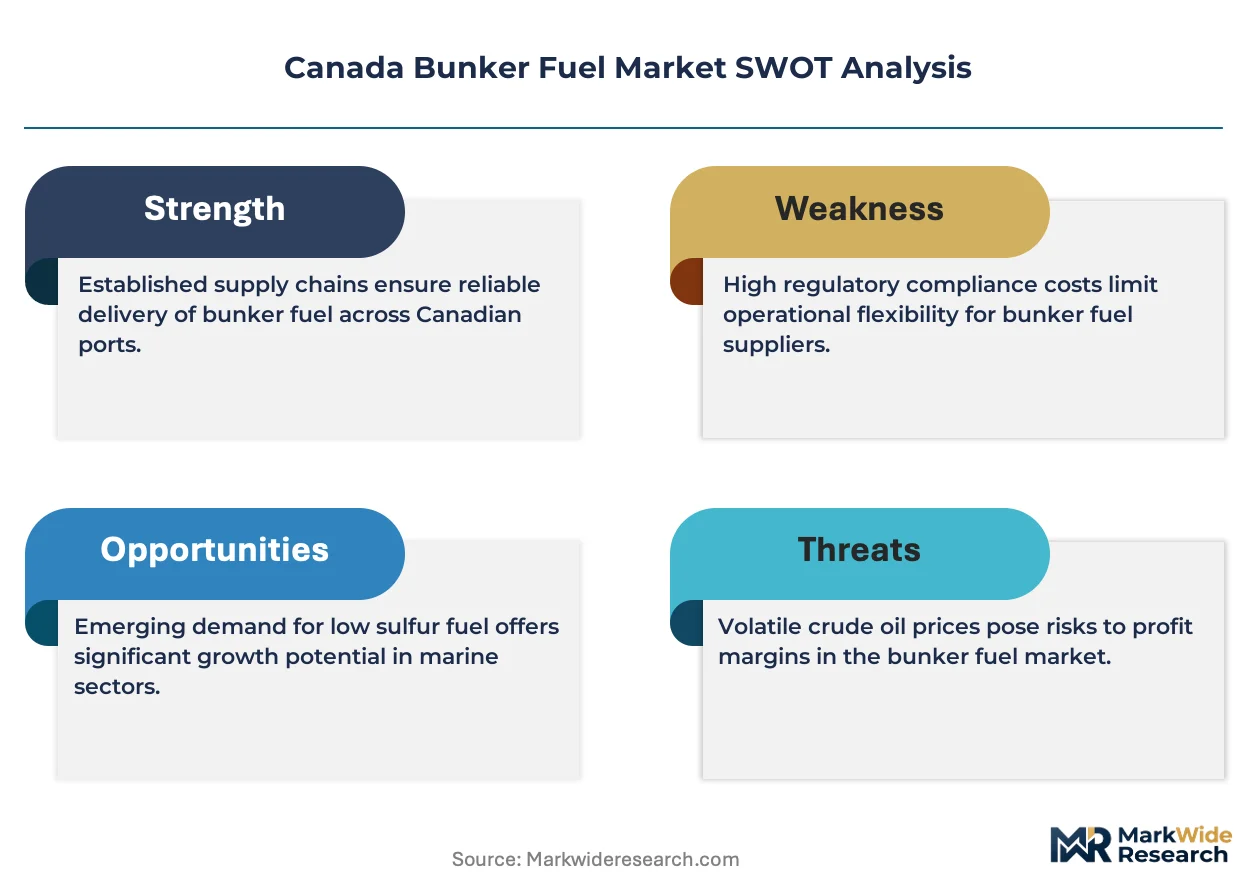
The International Maritime Organization's sulfur cap regulations are compressing demand for high-sulfur residual fuels while accelerating scrubber retrofits and distillate substitution across Canadian ports.
Growth Catalysts
- IMO Annex VI Compliance:The emission control area designation covering British Columbia waters mandates ultra-low sulfur marine gas oil for coastal operations, forcing fleet upgrades at Vancouver and Prince Rupert.
- Asia-Pacific Transshipment:Container volumes from Shanghai, Busan, and Yokohama are expanding refueling calls at Vancouver's Inner Harbour, concentrating bunkering demand in the Pacific corridor.
- Scrubber Technology Deployment:Open-loop and hybrid scrubber installations on deep-sea vessels allow continued high-sulfur fuel oil consumption outside emission control areas, preserving residual fuel demand at Halifax.
Market Restraints
- Crude Price Volatility:Heavy fuel oil and marine gas oil prices track Brent crude movements, compressing supplier margins during supply shocks and refining disruptions.
- Refinery Concentration Risk:Western Canadian refiners in Edmonton and Sarnia dominate residual fuel production, creating geographic supply vulnerability for Atlantic ports dependent on rail and barge distribution.
- Electrification Substitution:Shore power infrastructure at Vancouver's Canada Place and Victoria's Ogden Point enables cold-ironing for cruise and ferry fleets, displacing auxiliary generator fuel consumption.
Strategic Opportunities
- Biofuel Blending Mandates:British Columbia's Low Carbon Fuel Standard creates regulatory pull for B24 and B30 marine biofuel trials with major transpacific shipping lines.
- Arctic Route Development:Northern shipping lanes through Canada's Northwest Passage offer underpenetrated bunkering potential as ice-class vessel traffic expands seasonally.
- LNG Bunkering Infrastructure:FortisBC's Tilbury LNG facility and Seaspan's dual-fuel newbuilds are converging to establish Vancouver as a North American liquefied natural gas marine fuel hub.
Industry Challenges
- Marine Engineer Shortage:Scrubber maintenance and dual-fuel engine operation require specialized technical skills that Canadian maritime training programs are struggling to supply at scale.
- Compliance Documentation Burden:Transport Canada's fuel quality sampling and bunker delivery note verification protocols add administrative overhead to every port call.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Bunker Fuel Market |
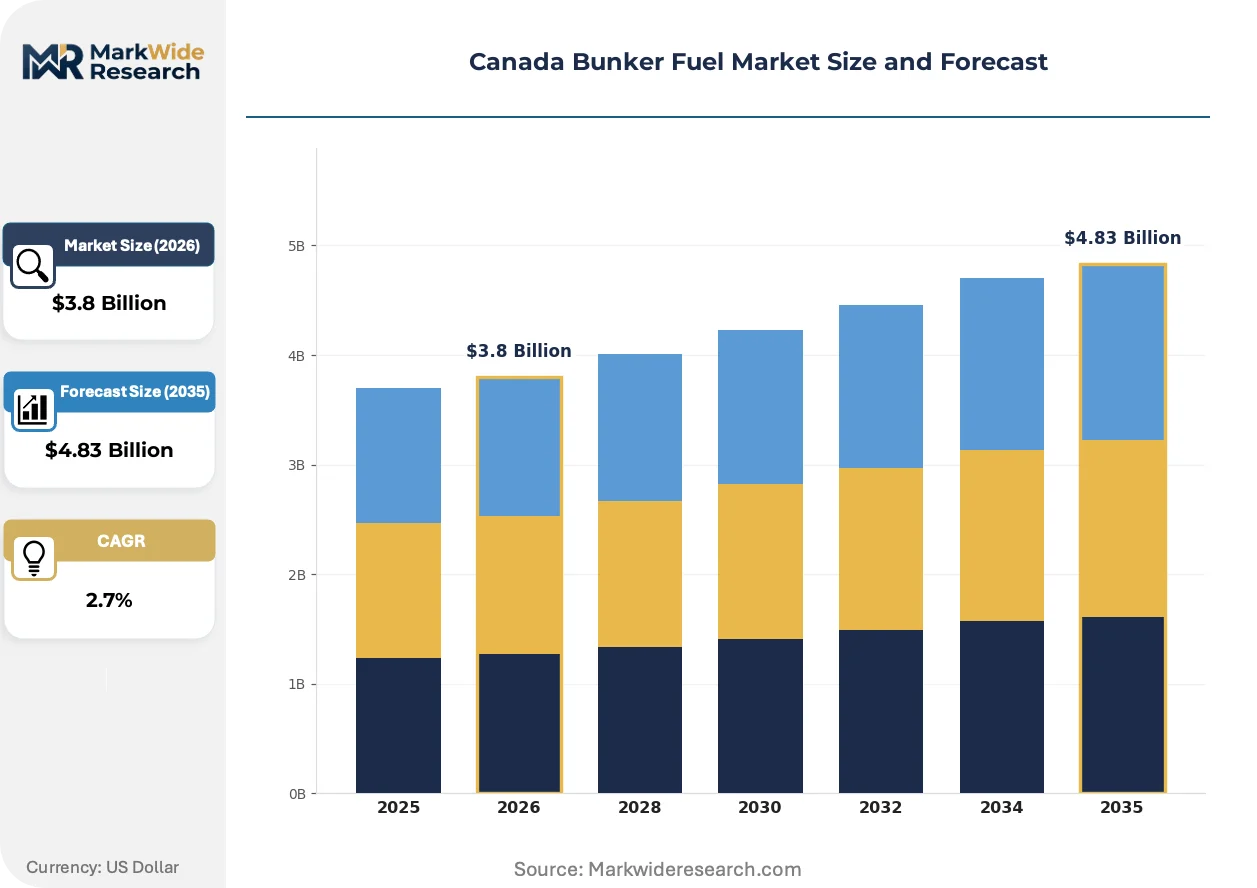
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IFO380, IFO180, MGO, MDO End User: Shipping Lines, Offshore Vessels, Fishing Industry, Cruise Operators Distribution Channel: Direct Sales, Bunker Fuel Suppliers, Brokers, Retail Application: Commercial Shipping, Recreational Boating, Industrial Use, Marine Tourism |
| Companies Covered | PetroChina Company Limited, TotalEnergies SE, Peninsula Petroleum Ltd, A.P. Møller – Maersk AS, World Kinect Corporation, BP p.l.c., Shell plc, Exxon Mobil Corporation, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Bunker Fuel Market Trends and Innovations
Digital fuel management systems and alternative fuel pilots are reconfiguring how vessel operators procure, verify, and consume marine energy across Canadian waters.
Exhaust gas cleaning systems for high-sulfur fuel oil are miniaturizing as manufacturers develop compact hybrid scrubber designs for medium-sized container vessels and roll-on/roll-off carriers. Coastal ferry operators at BC Ferries and Marine Atlantic are piloting these reduced-footprint units to extend vessel service life without drydock extension. The technology is compressing the capital cost barrier that previously limited scrubber adoption to only the largest ocean-going fleets.
Health Canada and PMRA are tightening environmental compliance protocols for fuel storage and transfer operations at marine terminals, aligning with federal marine protection standards under the Oceans Act. Transport Canada's Vessel Pollution and Dangerous Chemicals Regulations now require enhanced spill response planning for low-sulfur fuel oil blends with altered combustion properties. British Columbia's port cluster is responding with upgraded containment infrastructure and real-time water quality monitoring systems.
Long-term supply agreements are displacing spot market purchases as tier-one container lines seek price certainty and dedicated berth access at Vancouver and Halifax. Direct sales channels concentrate margin pools with integrated suppliers, while smaller offshore operators fragment across broker networks with limited pricing transparency. The shift is most visible among transpacific shipping lines operating fixed-schedule services through the Suez Canal route.
Canada Bunker Fuel Market Segmentation
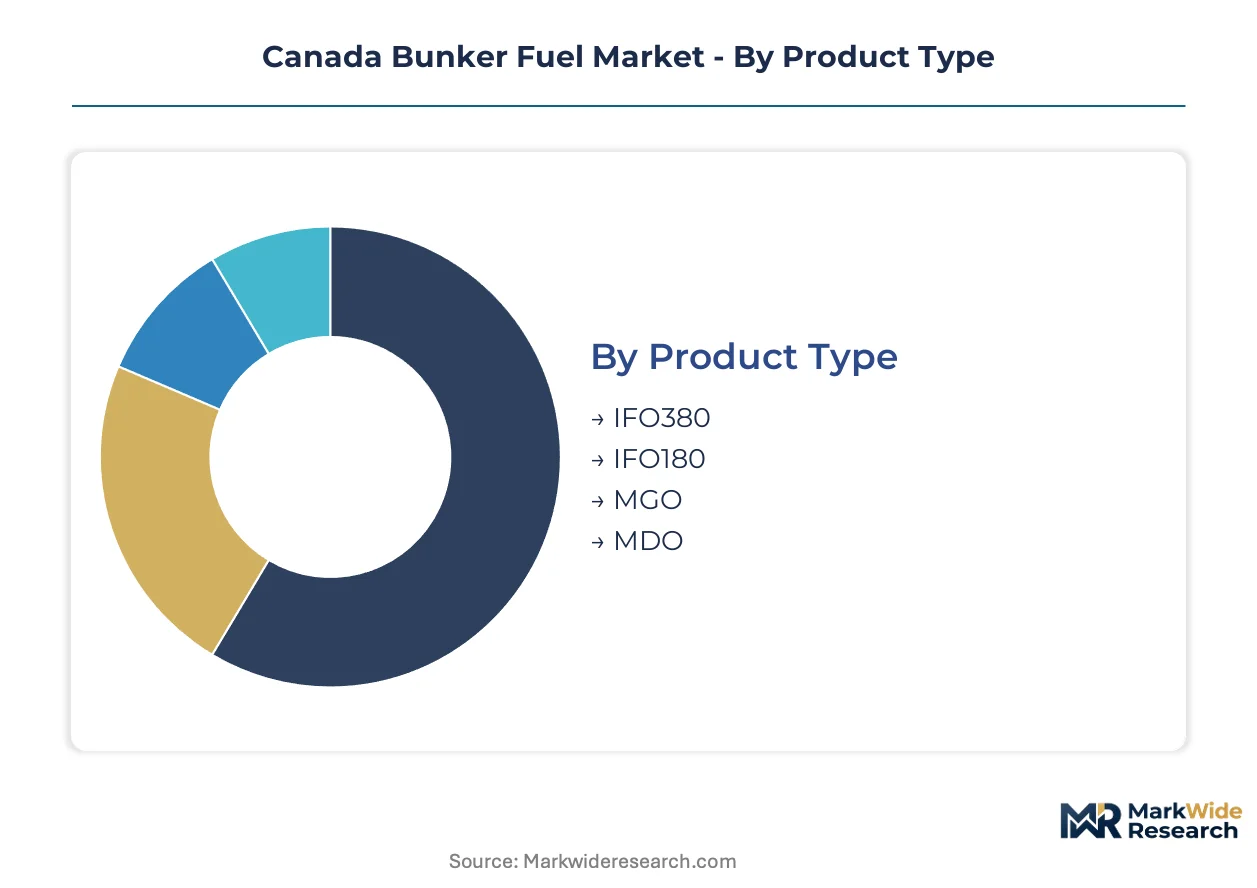
Marine fuel procurement in Canada splits across product specifications, vessel categories, and sales channels that each concentrate margin pools differently. Understanding these segment boundaries clarifies where integrated suppliers defend position versus where broker networks fragment pricing power.
Product Type:
Channel-mix patterns vary sharply across fuel grades, with direct sales agreements dominating residual fuel movements while distillates flow through more fragmented supplier networks.
- IFO380:High-viscosity residual fuel oil requiring heating systems for proper injection into large two-stroke marine engines. Demand concentrates at Vancouver's Inner Harbour among transpacific container lines running scrubber-equipped vessels, though Transport Canada's fuel quality sampling adds administrative overhead to every delivery.
- MGO:Ultra-low sulfur distillate meeting emission control area specifications through hydrotreating and blending operations. Coastal ferry services at BC Ferries and cruise operators at Victoria's Ogden Point anchor demand, with British Columbia's Low Carbon Fuel Standard creating regulatory pull for biofuel blending trials.
- IFO180:Lower-viscosity residual grade serving medium-speed four-stroke engines on regional cargo routes.
- MDO:Marine diesel oil bridging residual and distillate properties for auxiliary generators and smaller propulsion systems.
IFO380 dominates installed base tonnage. MGO is where expansion concentrates as emission control area boundaries tighten.
End User:
Cost tier stratification separates capital-intensive fleet operators pursuing long-term supply agreements from price-sensitive seasonal users transacting on spot markets.
- Shipping Lines:Tier-one container operators and bulk carriers with dedicated berth contracts and integrated supplier relationships. Transpacific services through Vancouver anchor volume, with fixed-schedule operators prioritizing price certainty over spot market flexibility.
- Cruise Operators:Seasonal demand concentrated at Vancouver's Canada Place and Victoria's Ogden Point, where shore power infrastructure enables cold-ironing and displaces auxiliary generator fuel consumption during port calls.
- Offshore Vessels:Supply boats and seismic survey craft operating from Halifax and St. John's with fragmented procurement through broker networks.
- Fishing Industry:Small-scale operators across Atlantic and Pacific coasts with limited storage capacity and high price sensitivity.
Shipping Lines anchor annual volume commitments. Cruise Operators represent the steepest expansion trajectory as passenger vessel traffic rebuilds.
Distribution Channel:
Geographic concentration of Canadian refining and port infrastructure shapes which channels can service which demand clusters.
- Direct Sales:Long-term supply agreements between integrated refiners and tier-one shipping lines, concentrating margin pools at Vancouver and Halifax through dedicated berth access and volume commitments.
- Bunker Fuel Suppliers:Specialized distributors with storage terminal access and barge fleets serving mid-size operators without credit capacity for direct refiner relationships.
- Brokers:Price discovery intermediaries fragmenting smaller offshore vessel and fishing fleet procurement with limited transparency and higher transaction friction.
- Retail:Small-volume shore-side sales to recreational and commercial fishing operators through marina fuel docks.
Direct Sales captures premium margin pools. Brokers face compression as larger operators consolidate procurement.
Application:
Volume scale separates applications where fuel management systems justify digital investment from those remaining on manual procurement processes.
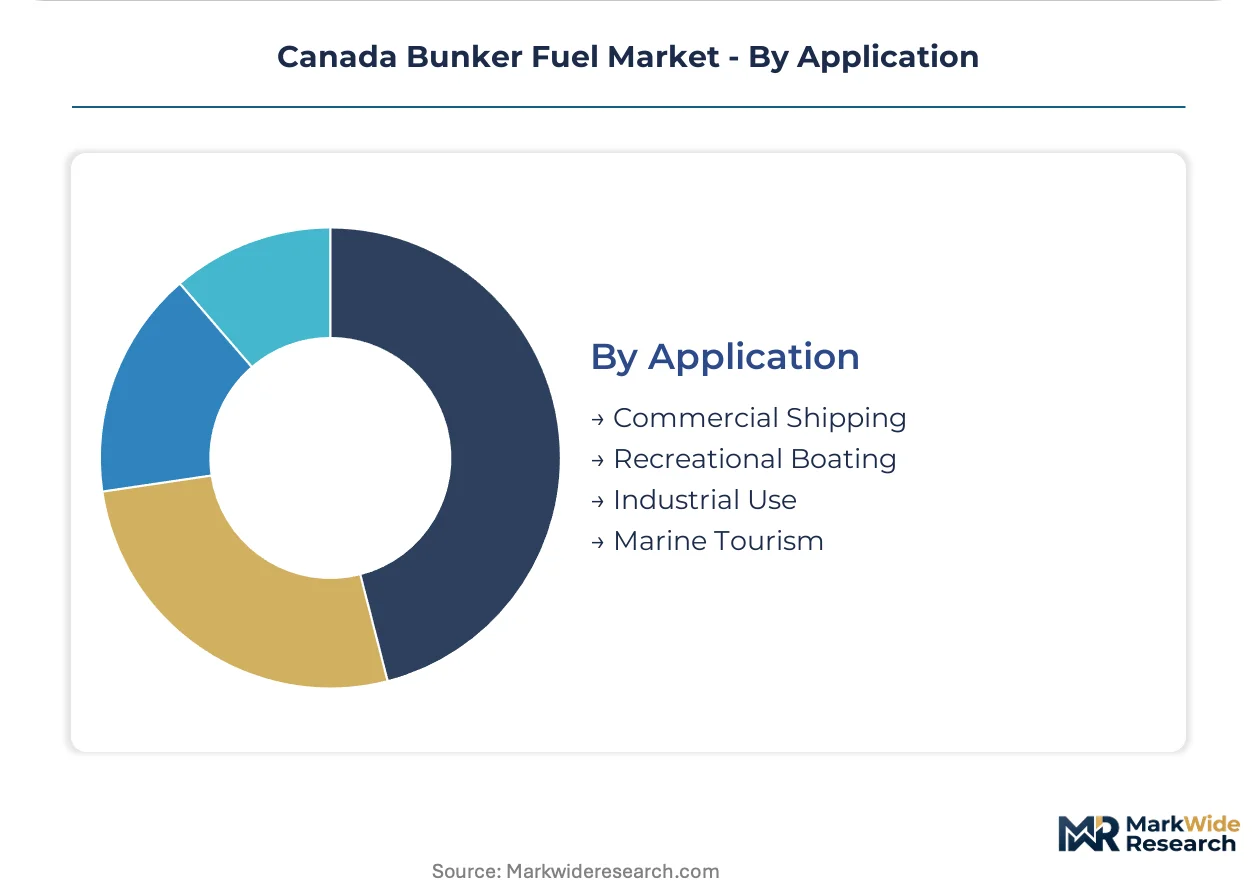
- Commercial Shipping:Deep-sea cargo, container, and bulk operations consuming residual fuels at scale with scrubber economics determining IFO380 versus MGO selection.
- Marine Tourism:Cruise and expedition vessel operations with seasonal demand spikes and stringent port emission requirements driving distillate preference.
- Industrial Use:Offshore platform supply, tugboat, and workboat fleets with mixed fuel specifications based on operating area emission designations.
- Recreational Boating:Pleasure craft and yacht segments with small lot sizes and high sensitivity to retail price spreads.
Commercial Shipping dominates throughput volumes. Marine Tourism is where fuel specification upgrades concentrate fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific container traffic flowing into North American markets concentrates bunkering demand at Canada's Pacific gateway ports. British Columbia's port cluster processes the dominant share of transpacific refueling volumes.
British Columbia
Vancouver's Inner Harbour anchors Pacific corridor bunkering activity as transpacific shipping lines expand refueling schedules. Transport Canada's Vessel Pollution and Dangerous Chemicals Regulations mandate strict fuel quality sampling protocols at marine terminals. The Port of Prince Rupert is developing expanded storage capacity to capture transshipment volumes from northern Asia-Pacific trade routes.
Ontario
Great Lakes shipping operations and St. Lawrence Seaway transits sustain residual fuel demand for lake freighters and international cargo vessels. Federal marine protection standards under the Oceans Act govern fuel transfer operations at Thunder Bay and Sarnia. The Sarnia refining corridor supplies IFO380 and MGO products through pipeline networks serving eastern Canadian ports.
Quebec
Montreal's container terminal expansion is attracting Mediterranean and European shipping lines with dedicated berth agreements. Health Canada and PMRA environmental compliance protocols align with provincial marine protection requirements for fuel storage facilities. The Port of Quebec is upgrading bunker barge fleets to handle low-sulfur fuel oil blends for cruise and cargo operations.
Nova Scotia
Halifax serves as the Atlantic corridor's primary bunkering hub for Europe-bound container services and offshore supply vessels. The International Maritime Organization's Annex VI emission control area designation influences fuel specification requirements for coastal operations. Imperial Oil's Dartmouth terminal infrastructure supports deep-water refueling for scrubber-equipped vessels on transatlantic routes.
Newfoundland and Labrador
Offshore oil platform supply vessels and fishing fleets anchor seasonal fuel demand at St. John's and Argentia. The Canadian Coast Guard's marine safety regulations govern fuel quality verification for vessels operating in harsh North Atlantic conditions. Ice-class vessel traffic through the Strait of Belle Isle is expanding bunkering requirements for Arctic route development.
Canada Bunker Fuel Market Competitive Landscape
Listed leaders compete with private specialists across integrated supply chain control, with integrated oil majors commanding dedicated berth access while independent distributors fragment spot market pricing. The market structure concentrates margin pools with vertically integrated refiners holding long-term supply agreements with tier-one shipping lines. Three archetypes dominate: integrated majors with captive refining, independent bunker suppliers with terminal and barge assets, and broker-intermediaries serving price-sensitive smaller operators. Competitive moves center on scrubber technology partnerships and biofuel blending infrastructure investments.
Within the integrated major tier, Shell plc and Chevron Corporation exemplify supply chain control through dedicated Vancouver terminal operations and specialized marine gas oil distribution networks. TotalEnergies SE occupies a position among European-headquartered competitors aggressively pursuing low-sulfur IFO380 contracts with transpacific carriers. Among independent suppliers, Peninsula Petroleum Ltd represents the specialist archetype with focused bunkering terminal and barge fleet operations. World Kinect Corporation anchors the energy management and logistics intermediary segment, connecting fragmented demand with supplier networks.
| Leading Market Players |
|---|
| PetroChina Company Limited |
| TotalEnergies SE |
| Peninsula Petroleum Ltd |
| A.P. Møller – Maersk AS |
| World Kinect Corporation |
| BP p.l.c. |
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term supply agreements between integrated refiners and tier-one shipping lines lock in dedicated berth access at Vancouver and Halifax while compressing spot market visibility for smaller operators. These contractual structures concentrate pricing power with vertically integrated suppliers and fragment price discovery across broker-served offshore fleets.
Pricing Analysis
Scrubber-equipped versus non-scrubber vessel pricing gaps are widening as emission control area compliance costs reshape procurement economics. Three-tier pricing structure across premium low-sulfur IFO380, standard MGO, and economy high-sulfur residual grades differentiates based on sulfur certification tier and volume commitment scale. Pricing pressure stems from crude price volatility tracking Brent movements, with fishing fleet operators exhibiting highest price sensitivity and transpacific container lines showing lowest due to fuel surcharge pass-through mechanisms.
Supply Chain Analysis
Canada and the United States anchor North American residual fuel production through Edmonton and Sarnia refining corridors serving Atlantic and Pacific port clusters. Western Canadian refineries draw from oil sands bitumen and conventional crude feedstocks, with marine fuel blending operations resting on viscosity modifier and cutter stock supplies. Single-source vulnerability concentrates in rail and barge distribution links to Halifax, while distribution runs through integrated terminal-barge networks at Vancouver and broker-fragmented channels at St. John's.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bunker fuel procurement is shifting toward platform-mediated contracting as digital fuel management systems enable real-time quality verification and automated bunker delivery note compliance, creating interoperability economies between vessel operators and integrated suppliers.
For Market Incumbents: Fortify terminal infrastructure at Prince Rupert and Halifax through dedicated storage capacity additions that preempt competitor berth access. Secure scrubber maintenance partnerships with transpacific shipping lines to lock in residual fuel offtake against MGO substitution threats from British Columbia's Low Carbon Fuel Standard mandates. For New Entrants and Emerging Players: Differentiate on biofuel blending certification by securing B24 and B30 marine biofuel supply agreements with BC Ferries and coastal cruise operators ahead of mandated carbon intensity reductions. Target Arctic route bunkering at Churchill and Iqaluit as ice-class vessel traffic expands seasonally through the Northwest Passage. For Investors and Strategic Acquirers: Capital is best deployed toward independent bunker suppliers with captive terminal assets and barge fleets serving mid-tier shipping lines without integrated refiner relationships. Monitor scrubber technology deployment rates as the inflection signal for residual fuel demand durability versus distillate substitution acceleration across Canadian waters.| Strategic Initiative | Industry Significance |
|---|---|
| LNG Bunkering Infrastructure Buildout | FortisBC's Tilbury facility positions Vancouver as a North American liquefied natural gas marine fuel hub. |
| Backward Integration into Biofuel Supply | Low Carbon Fuel Standard compliance creates regulatory pull for B24 and B30 marine biofuel blending capacity. |
| Scrubber Technology Partnership | Hybrid scrubber installations on medium-sized vessels preserve high-sulfur fuel oil demand outside emission control areas. |
| Arctic Route Storage Expansion | Ice-class vessel traffic through the Northwest Passage demands seasonal bunkering infrastructure at underpenetrated northern ports. |
| Digital Fuel Management Platform | Real-time quality verification and automated compliance documentation reduce administrative overhead under Transport Canada regulations. |
Research Methodology
Desk research of customs trade data, refinery production disclosures, and Transport Canada regulatory filings preceded structured interviews with marine fuel procurement managers, scrubber technology suppliers, and port authority operations directors. Primary fieldwork with shipping line bunker desks and independent fuel distributors was cross-validated against secondary sources including Port of Vancouver traffic statistics and Health Canada environmental compliance records. Bottom-up volume estimates from individual terminal throughput figures were triangulated against top-down market sizing derived from national marine fuel consumption aggregates.
Variance decomposition across product type, end user, and distribution channel segments shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating scrubber retrofit penetration curves, emission control area boundary expansions, and alternative fuel substitution elasticities. Forecast inputs included transpacific container volume projections and British Columbia Low Carbon Fuel Standard carbon intensity reduction schedules.
Material uncertainties — crude price volatility, scrubber technology cost curves, and biofuel blending mandate timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and shipping line fleet renewal patterns. Recalibration cycles align with material shifts in International Maritime Organization emission standards and Arctic route ice-class vessel traffic volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hydrogen Tube Trailer Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Liquid Propellants Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
High Octane Racing Fuel Market
Fuels
LPG Tanker Market
Fuels
United States Coal Market
Fuels
Coal Gasification Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Europe Coal Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Aboveground Fuel Storage Market
Fuels
China LNG Bunkering Market
Fuels
Renewable Heating Fuels Market