
 India Petrol Station Market | 2026-2036
India Petrol Station Market Size, Share, and Industry Trends Forecast 2026-2036
India Petrol Station Market Foresight
Dealer-operated networks across India's fuel retail landscape is fragmenting as private entrants and public sector incumbents redraw territorial control. Nayara Energy leverages its Vadinar refinery integration to sustain margin capture across western India. Indian Oil Corporation Limited anchors national coverage through its IndianOil SKY brand and rural pump expansion. Reliance Industries Limited competes via Jio-bp's electric mobility crossover at select highway locations.
India petrol stations comprise fixed retail fuel dispensing facilities equipped with underground storage tanks, vapor recovery systems, and flow meters calibrated for petroleum product measurement, serving as the terminal node of downstream hydrocarbon supply chains. Full-service operations still dominate tier-2 and tier-3 towns where labor costs remain low, while automated dispensing is displacing manual operations along the Delhi-Mumbai and Chennai-Bengaluru industrial corridors. Compressed Natural Gas infrastructure is expanding fastest among fuel types as city gas distribution mandates widen, though petrol retains the deepest margin pool due to volume throughput at established outlets.
BIS certification governs pump metrology accuracy, while the Petroleum and Natural Gas Regulatory Board oversees city gas network licensing that shapes CNG dispenser placement. The CEA coordinates electrical safety standards for EV charging integration at existing forecourts. Stakeholders must monitor how ethanol storage compatibility requirements and blending ratio mandates reshape tank farm capex decisions across state-level dealer networks.
Market Dynamics
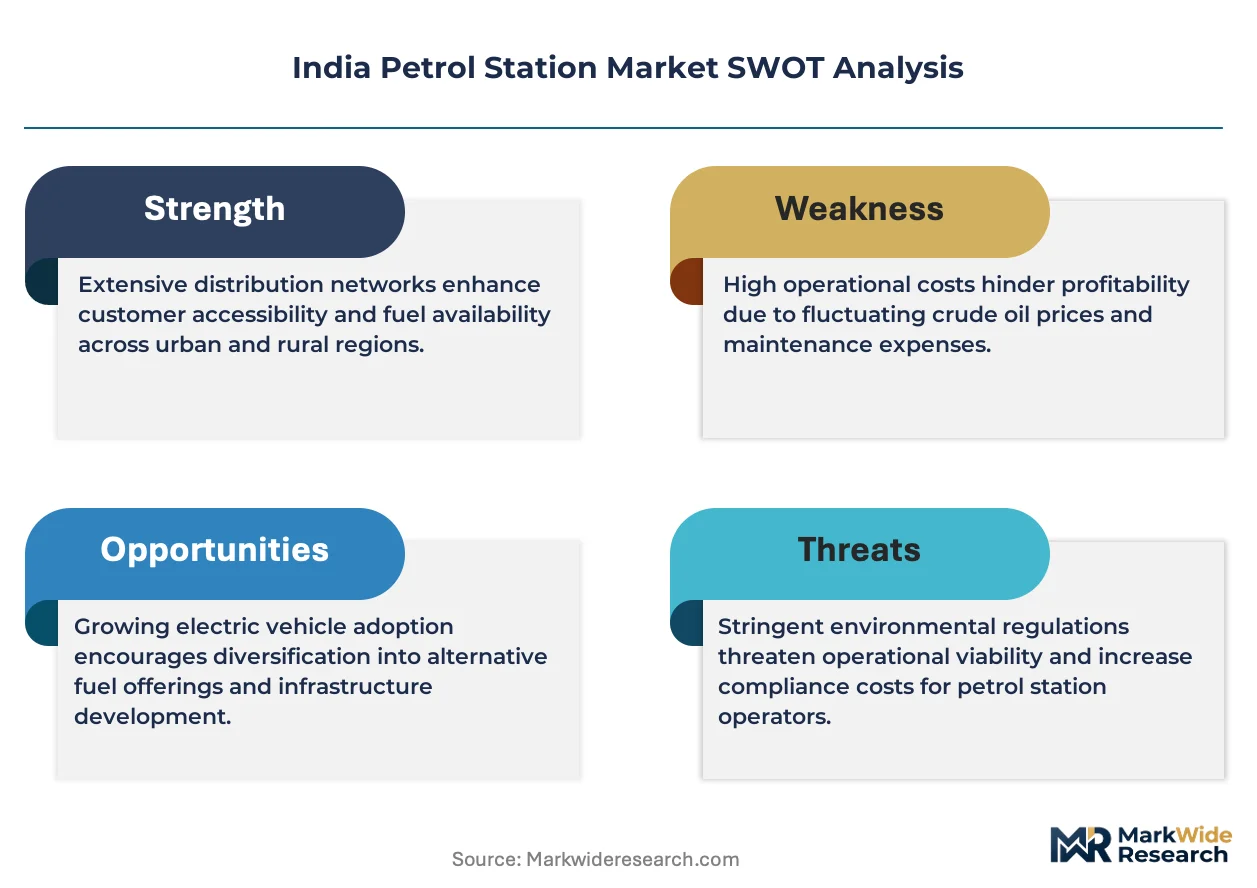
India's petrol station landscape is restructuring around the National Biofuel Policy's ethanol-blending mandate, which forces capital redeployment from conventional fuel infrastructure toward tank farm retrofits and vapor recovery upgrades. This regulatory compression is redrawing competitive boundaries between state-owned incumbents and private refiners.
Growth Catalysts
- Ethanol-blending mandates:The National Biofuel Policy's 20% blending target is accelerating pump infrastructure investment across Maharashtra and Gujarat.
- Highway corridor expansion:Commercial fleet operators are extending fuel procurement networks along the Delhi-Mumbai and Chennai-Bengaluru industrial corridors.
- City gas distribution rollout:Petroleum and Natural Gas Regulatory Board licensing mandates are widening CNG dispenser placement in urban clusters.
Market Restraints
- Steel and cement input volatility:Underground storage tank construction faces cost pressure from commodity price swings.
- Refinery supply concentration:Western India pump networks depend heavily on Vadinar and Jamnagar refinery output.
- Ethanol storage incompatibility:Existing fiberglass tanks require replacement to handle higher-blend fuels, creating stranded asset risk.
Strategic Opportunities
- Tamil Nadu logistics clusters:Industrial corridor density around Chennai and Coimbatore offers underpenetrated fleet-card penetration.
- EV charging convergence:Central Electricity Authority standards are enabling DC fast-charger retrofit at established forecourts.
- Rural pump digitization:IndianOil SKY's rural expansion creates white space for automated dispensing in tier-3 towns.
Industry Challenges
- Skilled technician scarcity:Vapor recovery system calibration requires certified personnel that dealer networks struggle to retain.
- BIS metrology recertification:Flow meter accuracy audits impose downtime costs that squeeze throughput at high-volume outlets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Petrol Station Market |
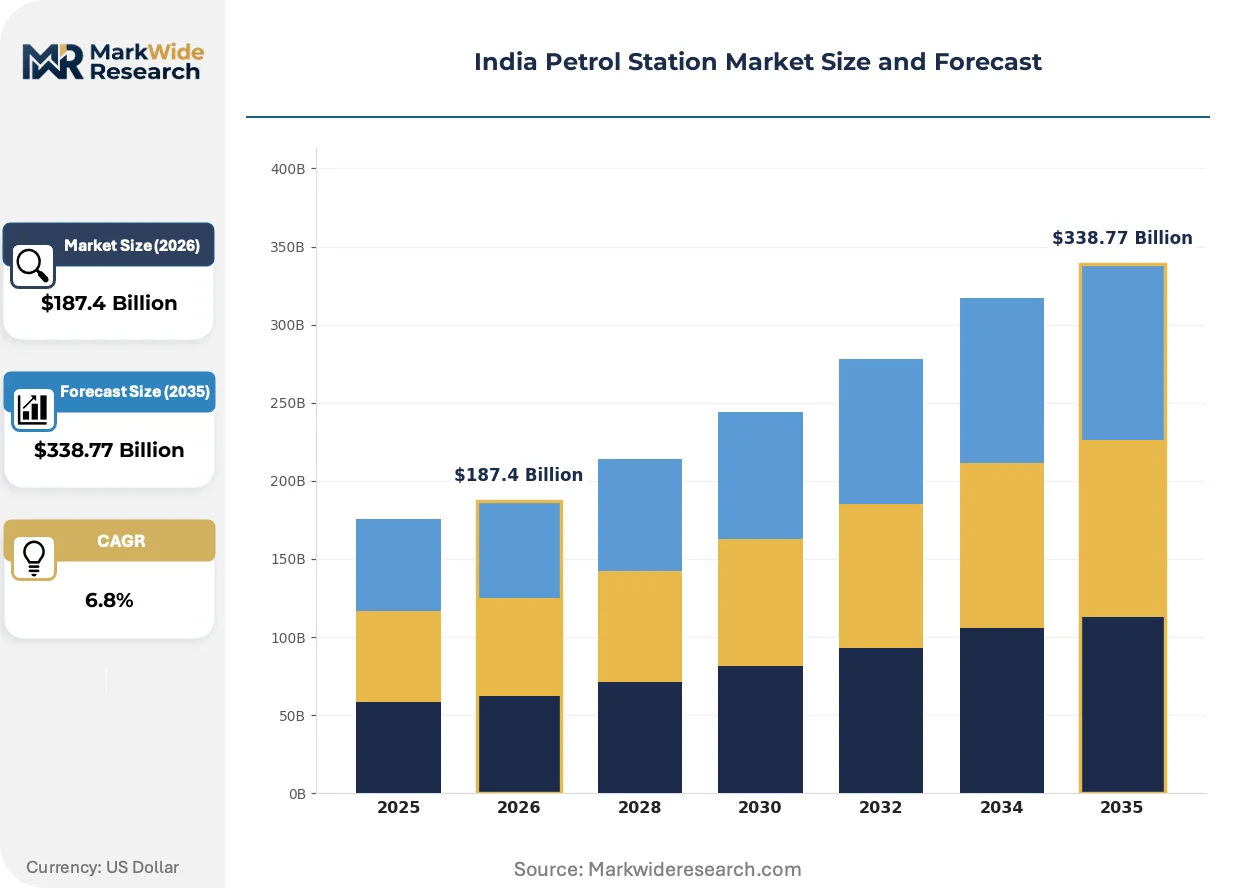
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service, Self-Service, Automated, Mobile Fueling Fuel Type: Petrol, Diesel, Compressed Natural Gas, Biofuel Customer Type: Private Vehicle Owners, Commercial Fleet Operators, Government Agencies, Ride-Sharing Services Technological Integration: Smart Pumps, Mobile Payment Systems, Telematics, Customer Loyalty Programs |
| Companies Covered | Nayara Energy Limited, Oil and Natural Gas Corporation, Indian Oil Corporation Limited, Oil India Limited, Cairn India, Bharat Petroleum Corporation Limited, Reliance Industries Limited, Royal Dutch Shell, Hindustan Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Petrol Station Market Shifts & Advancements
Digital infrastructure is virtualizing core fuel retail operations, compressing the traditional dealer-operated service model while enabling new revenue streams at the forecourt edge. Three forces are actively restructuring competitive positioning.
Cloud-based fleet management platforms are virtualizing procurement workflows for commercial transport operators. Large logistics companies in Gujarat and Maharashtra are adopting these systems fastest. The technology is virtualizing manual reconciliation processes that previously tied fleet managers to specific pump networks.
The Petroleum and Natural Gas Regulatory Board's city gas distribution mandates are forcing CNG infrastructure co-location at existing petrol stations. This regulatory compression requires electrical safety recertification under Central Electricity Authority guidelines. Tamil Nadu pump operators are responding fastest due to Chennai's compressed natural gas vehicle density.
Fleet-card penetration is consolidating purchasing power among commercial transport buyers. Aggregator platforms are displacing direct dealer relationships for volume fuel procurement. This shift is most visible along the Delhi-Mumbai highway corridor where logistics operators centralize billing across multiple state jurisdictions.
India Petrol Station Market Segmentation
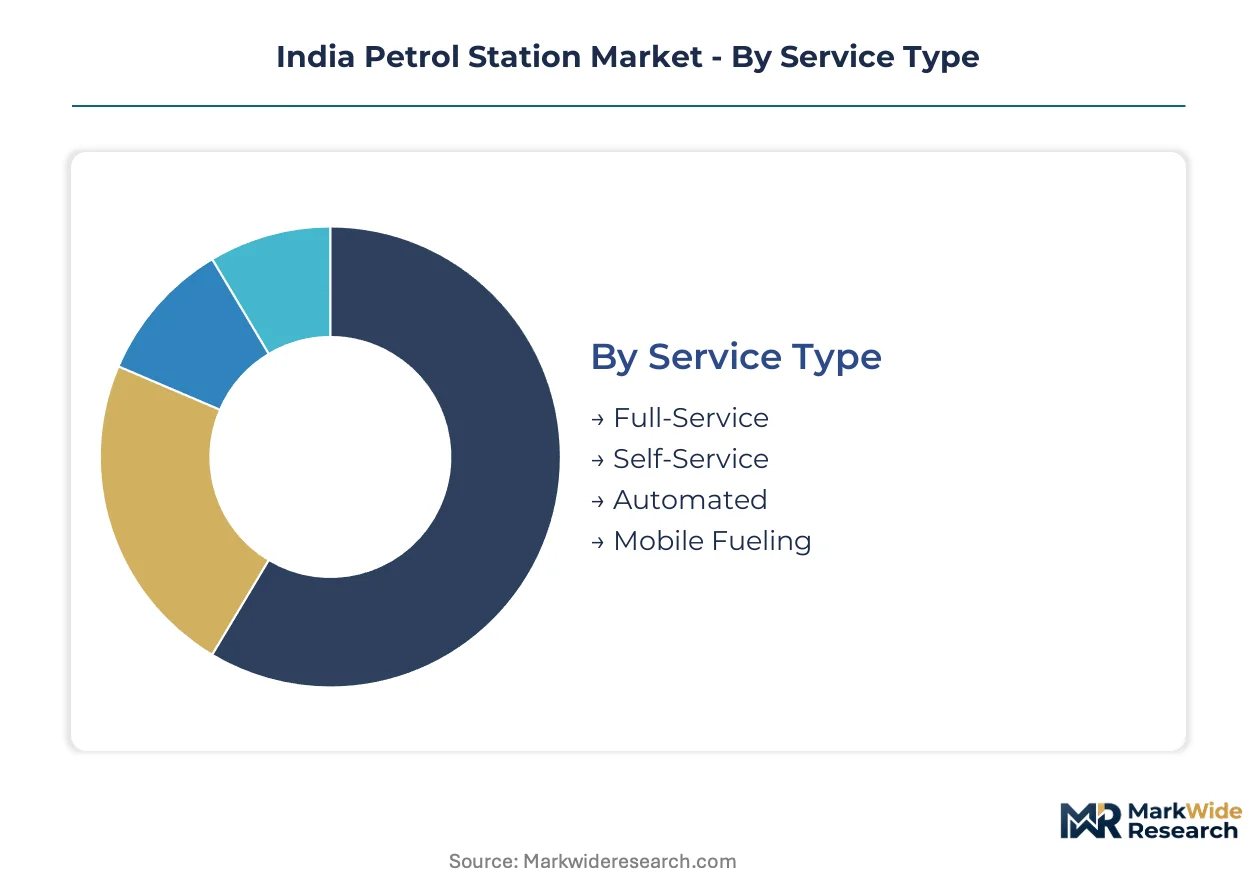
India's petrol station market segments around divergent operational economics and regulatory mandates. Service models, fuel types, customer profiles, and technology stacks each command distinct capital deployment strategies and margin structures across state-level dealer networks.
Service Type:
Operational labor intensity spans from high-touch attendant service to fully unmanned dispensing infrastructure.
- Full-Service:Attendant-operated fuel dispensing with windshield cleaning and air pressure checks bundled into the transaction. Demand concentrates in tier-2 and tier-3 towns across Uttar Pradesh and Madhya Pradesh where labor costs remain structurally low and consumer preference for assisted service persists.
- Self-Service:Customer-operated pumps with minimal staff presence for payment processing and safety oversight. Adoption accelerates along the Delhi-Mumbai Industrial Corridor where commercial fleet operators prioritize throughput speed over ancillary services.
- Automated:Unmanned dispensing islands with integrated payment kiosks and remote monitoring capabilities. Deployments cluster around Gujarat's logistics hubs where 24-hour fleet access requirements outstrip conventional staffing models.
- Mobile Fueling:Tanker-mounted dispensing units serving construction sites, mining operations, and agricultural zones beyond fixed retail infrastructure. Regulatory constraints under Petroleum and Explosives Safety Organisation licensing limit expansion to industrial captive use cases.
The dominant share belongs to Full-Service, while Automated is closing the gap fastest.
Fuel Type:
Margin pools diverge sharply based on regulatory blending mandates and infrastructure retrofit requirements.
- Petrol:Spark-ignition fuel with established storage compatibility across existing fiberglass and steel tank farms. Volume throughput remains deepest at established highway outlets serving private vehicle owners and ride-sharing operators.
- Diesel:Compression-ignition fuel commanding premium pricing for commercial fleet procurement. Demand concentrates in Tamil Nadu's Coimbatore-Salem industrial belt where logistics operators maintain centralized fuel contracts.
- Compressed Natural Gas:Methane-based transport fuel requiring high-pressure storage and specialized dispenser infrastructure. City gas distribution mandates under Petroleum and Natural Gas Regulatory Board licensing are accelerating co-location at existing forecourts in Delhi and Mumbai metropolitan regions.
- Biofuel:Ethanol-blended gasoline subject to National Biofuel Policy ratio requirements. Storage compatibility challenges with legacy tank materials are forcing capital redeployment toward corrosion-resistant infrastructure across Maharashtra refinery supply zones.
Petrol retains the largest volume base, though Compressed Natural Gas is expanding most quickly.
Customer Type:
Purchasing behavior fragments across payment reliability, volume scale, and route predictability dimensions.
- Private Vehicle Owners:Individual consumers purchasing on spot-price terms with high price elasticity and low loyalty stickiness. Concentration tracks passenger vehicle registration density in Bengaluru and Hyderabad urban agglomerations.
- Commercial Fleet Operators:Corporate transport buyers negotiating volume contracts with centralized billing and route-optimized procurement. Fleet-card penetration is deepest among Gujarat-based logistics companies operating across multiple state jurisdictions.
- Government Agencies:Public sector undertakings with mandated procurement quotas and extended payment cycles. Demand clusters around defense establishment locations and state transport corporation depots.
- Ride-Sharing Services:Platform-coordinated driver networks with high-frequency, low-margin transactions requiring seamless payment integration. Adoption of mobile payment systems is densest in Delhi NCR where aggregator platform concentration overlaps with digital infrastructure maturity.
Private Vehicle Owners account for the highest transaction count, while Commercial Fleet Operators are gaining share fastest.
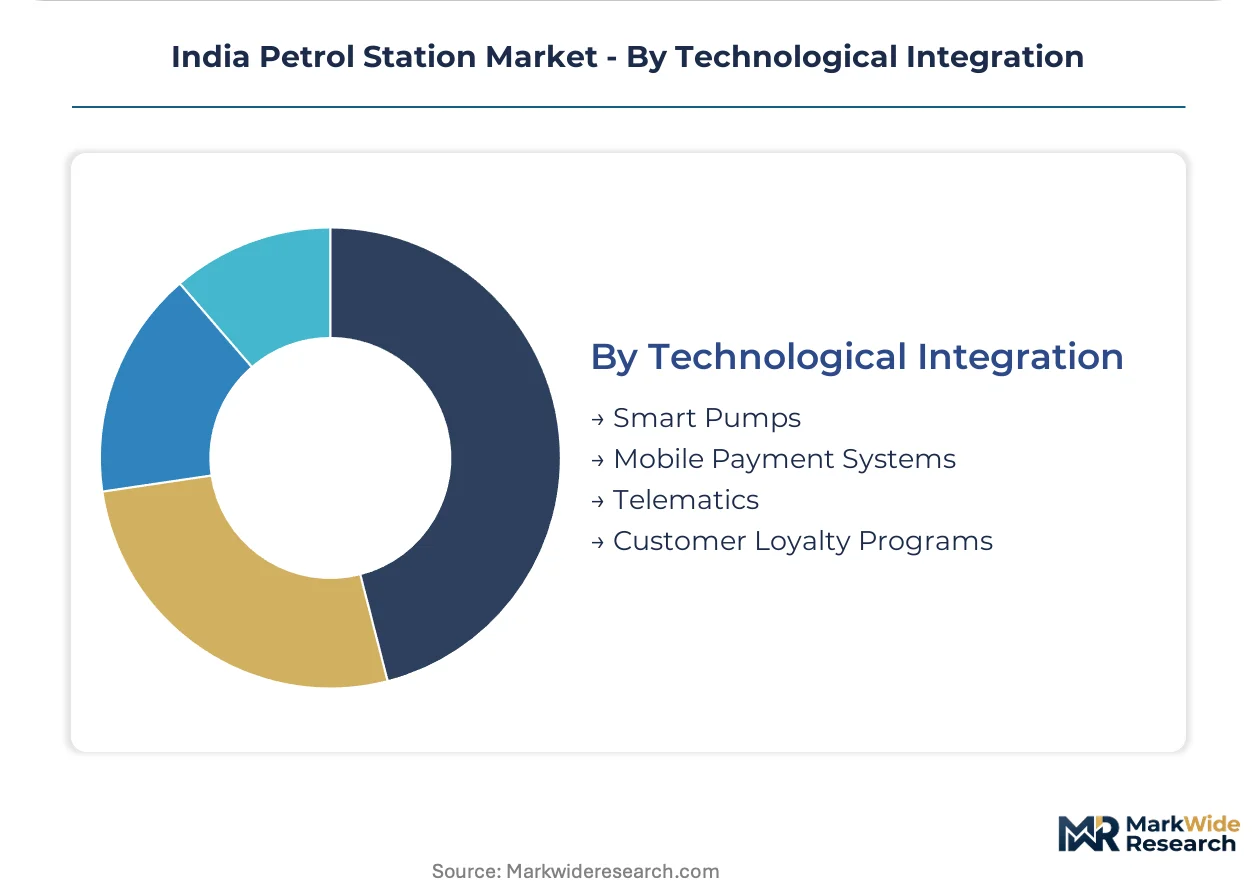
Technological Integration:
Digital infrastructure investments stratify by customer interface priority and back-office efficiency targets.
- Smart Pumps:Internet-connected dispensing units with real-time inventory monitoring and dynamic pricing capabilities. Deployment concentrates at IndianOil SKY branded outlets where centralized network management justifies connectivity expenditure.
- Mobile Payment Systems:QR-code and NFC-enabled transaction processing eliminating cash handling overhead. Penetration is highest in tier-1 cities where urban consumer digital literacy reduces adoption friction.
- Telematics:GPS-integrated fleet tracking combined with fuel consumption analytics for commercial operators. Uptake tracks logistics company technology adoption in Maharashtra and Karnataka highway corridors.
- Customer Loyalty Programs:Points-based retention systems with fuel-linked rewards and partner merchant tie-ins. Program density mirrors organized retail network concentration rather than independent dealer operations.
Smart Pumps hold the installed base lead, while Mobile Payment Systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands pricing power over Tamil Nadu due to Mumbai's refinery adjacency and denser logistics corridor throughput. Gujarat's Jamnagar-Vadinar supply cluster compresses procurement costs below southern markets. Karnataka and Telangana occupy intermediate positions shaped by pipeline distance and highway density differentials.
Maharashtra
Mumbai-Pune logistics clusters and Thane industrial belt drive fleet-card procurement volume. The state's ethanol storage retrofit mandate under National Biofuel Policy compliance deadlines forces tank farm capital redeployment. Nashik-Aurangabad highway corridors witness automated pump installation acceleration for 24-hour commercial access.
Gujarat
Vadinar refinery integration and Mundra port throughput anchor western India's deepest fuel margin pool. Petroleum and Natural Gas Regulatory Board city gas distribution licensing accelerates CNG dispenser co-location at existing forecourts. Ahmedabad-Surat industrial corridor hosts India's densest automated dispensing infrastructure for logistics operators.
Tamil Nadu
Chennai-Coimbatore-Salem manufacturing belt concentrates commercial diesel demand from textile and automotive supply chains. Central Electricity Authority electrical safety standards enable EV charging retrofit at established highway outlets. Sriperumbudur-Oragadam automotive cluster generates concentrated fleet procurement contracts with centralized billing requirements.
Karnataka
Bengaluru urban agglomeration drives ride-sharing platform fuel demand with high-frequency, low-margin transaction density. State-level dealer network digitization lags Maharashtra and Gujarat, creating white space for mobile payment system penetration. Mysuru-Mangaluru highway corridor expansion attracts new pump licensing applications from private entrants.
Delhi-NCR
Supreme Court-mandated CNG conversion timelines for commercial vehicles compress CNG infrastructure deployment schedules. Haryana-Rajasthan border highway nodes concentrate inter-state logistics procurement with multi-jurisdictional fleet-card billing complexity. Ghaziabad-Faridabad industrial zones sustain diesel throughput despite air quality regulatory pressure on older pump infrastructure.
India Petrol Station Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on storage and dispensing hardware. The market structures around three tiers: state-owned incumbents with national coverage mandates, private refiners with captive supply integration, and international oil companies with premium positioning. Strategic archetypes include refinery-anchored network operators, dealer-network aggregators, and mobility-service crossovers. Dominant competitive moves involve CNG infrastructure co-location partnerships and ethanol-compatible tank farm retrofits.
Within the refinery-integrated tier, Nayara Energy Limited and Reliance Industries Limited occupy positions shaped by Vadinar and Jamnagar supply proximity. Indian Oil Corporation Limited anchors the state-owned incumbent archetype through rural network density. Among international entrants, Royal Dutch Shell exemplifies premium-tier positioning focused on highway corridor nodes and fleet-service differentiation.
| Leading Market Players |
|---|
| Nayara Energy Limited |
| Oil and Natural Gas Corporation |
| Indian Oil Corporation Limited |
| Oil India Limited |
| Cairn India |
| Bharat Petroleum Corporation Limited |
| Reliance Industries Limited |
| Royal Dutch Shell |
| Hindustan Petroleum Corporation Limited |
| Others |
Supply & Pricing Matrix
The Delhi-Mumbai Industrial Corridor freight cost dynamics compress supply concentration around Gujarat's refinery clusters while enabling downstream price differentiation between highway-adjacent premium outlets and rural standard-tier stations.
Pricing Analysis
The customization-premium spread separates configured-to-order fleet-card contracts from standard retail spot pricing. Three-tier pricing structure across premium, standard, and economy levels captures volume scale and after-sales bundling as primary differentiation drivers. Price differentiation stems from BIS certification tier and geographic delivery cost to highway corridor nodes. Commercial fleet operators in Maharashtra exhibit lowest price sensitivity due to route-optimized procurement contracts, while private vehicle owners in tier-3 towns show highest elasticity to spot price movements.
Supply Chain Analysis
Upstream feedstock availability draws from Jamnagar, Vadinar, and Kochi refinery output zones. Crude oil, ethanol blends, and CNG feedstock constitute the primary input dependencies. Single-source vulnerability concentrates around western India refinery supply, with pipeline distance to Tamil Nadu and Karnataka creating logistics chokepoint exposure. Distribution runs through state-level dealer networks with IndianOil SKY, Nayara Energy, and Jio-bp branded terminals anchoring downstream throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The National Biofuel Policy's 20% ethanol-blending mandate constitutes a regulatory inflection forcing infrastructure disruption across India's fuel retail landscape.
For Market Incumbents: Entrench ethanol-compatible tank farm capacity ahead of compliance deadlines to neutralize stranded asset risk from legacy fiberglass storage. Capture CNG dispenser co-location rights under Petroleum and Natural Gas Regulatory Board licensing to lock out private refiner expansion along priority highway nodes. For New Entrants and Emerging Players: Pursue automated dispensing infrastructure deployment in Karnataka's tier-3 towns where state-level digitization lags Maharashtra and Gujarat. Fleet-card platform integration offers the most penetrable go-to-market angle for logistics operators seeking centralized billing across multi-jurisdictional routes. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned oil marketing companies seeking to monetize underperforming rural pump assets. Long-term viability hinges on ethanol storage retrofit completion and EV charging convergence readiness. Watch Petroleum and Natural Gas Regulatory Board city gas distribution licensing velocity as the signal indicating CNG infrastructure deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Ethanol-Compatible Tank Retrofit | BIS certification compliance under National Biofuel Policy mandates prevents stranded asset exposure. |
| CNG Dispenser Co-location Partnership | Petroleum and Natural Gas Regulatory Board licensing creates defensive positioning against private refiner expansion. |
| Fleet-Card Platform Integration | Aggregator procurement consolidation displaces direct dealer relationships across Delhi-Mumbai corridor logistics. |
| Automated Pump Infrastructure Deployment | 24-hour unmanned dispensing captures commercial fleet access requirements in Gujarat logistics hubs. |
| EV Charging Forecourt Retrofit | Central Electricity Authority standards enable DC fast-charger integration at established highway outlets. |
Research Methodology
Desk research of Petroleum and Natural Gas Regulatory Board licensing records, BIS certification databases, and state-level dealer network filings preceded structured interviews with pump operations managers, petroleum logistics coordinators, and fleet procurement officers. Primary fieldwork with IndianOil SKY network administrators and Nayara Energy supply chain leads combined with secondary validation against Central Electricity Authority infrastructure disclosures and Ministry of Petroleum and Natural Gas policy circulars. Bottom-up outlet-level throughput estimates triangulated against top-down refinery output allocation data.
Assumptions held fixed include National Biofuel Policy blending ratio trajectories and Petroleum and Natural Gas Regulatory Board city gas distribution licensing timelines, while ethanol import parity pricing and CNG feedstock availability were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, fuel type, customer profile, and technological integration tier alongside regional highway density differentials. CAGRs were derived from outlet expansion rates and throughput per pump projections calibrated against historical refinery supply allocation patterns and fleet-card penetration curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil import costs, rupee-dollar exchange volatility, or commercial vehicle sales cycles would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against Ministry of Road Transport and Highways vehicle registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
United States Bunker Fuel Market
Fuels
Brazil LNG Market
Fuels
North America LNG Bunkering Market
Fuels
Marine Fuel Optimization Market
Fuels
Aerospace Aviation Fuels Market
Fuels
South America Bunker Fuel Market
Fuels
Anthracite Coal Mining Market
Fuels
UAE Chemical Logistics Market
Fuels
Saudi Arabia Chemical Logistics Market
Fuels
Electric Fuel Heater Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Smart Gas Solutions Market
Fuels
Europe Bunker Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Underground Coal Gasification Market
Fuels
Australia Coal Market