
 Aerospace Aviation Fuels Market | 2026-2036
Aerospace Aviation Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Aviation Fuels Market Analysis
Middle East refinery expansions in Saudi Arabia and the United Arab Emirates are rewriting regional supply dynamics for kerosene-based jet fuel. Exxon Mobil Corporation leverages integrated upstream-downstream assets to sustain cost-competitive Jet A-1 output across multiple continents. BP p.l.c. anchors its position through dedicated sustainable aviation fuel partnerships with European and Asia-Pacific carriers. Neste competes aggressively on hydroprocessed esters and fatty acids capacity, differentiating through renewable feedstock security rather than conventional crude dependency.
Aerospace aviation fuels comprise refined petroleum products and synthetic alternatives formulated to meet strict energy density, freeze point, and thermal stability specifications for turbine and piston engines. Jet A-1, the dominant civil aviation grade, delivers a maximum freeze point of minus 47 degrees Celsius and flash point above 38 degrees Celsius to ensure safe high-altitude operation. Commercial Aviation commands the largest volume share among application segments as passenger traffic rebuilds and fleet utilization rates normalize. Military Aviation maintains premium pricing power through specialized JP-8 and JP-5 formulations with enhanced thermal oxidative stability for supersonic and carrier-based operations. Sustainable aviation fuel variants within fuel type segmentation attract disproportionate capital allocation as airlines face binding carbon intensity reduction obligations.
FAA certification standards under ASTM D7566 govern alternative jet fuel pathways in the United States, while EASA enforces comparable sustainability criteria across European Union member states. ICAO Carbon Offsetting and Reduction Scheme for International Aviation binds cross-border carriers to emissions monitoring and offset purchase requirements that reshape procurement priorities. ReFuelEU Aviation mandates progressively increase blending obligations for synthetic and biomass-derived fuels. Stakeholders must track feedstock availability, offtake agreement structures, and refinery co-processing retrofit economics to align capital deployment with evolving compliance thresholds.
Market Dynamics
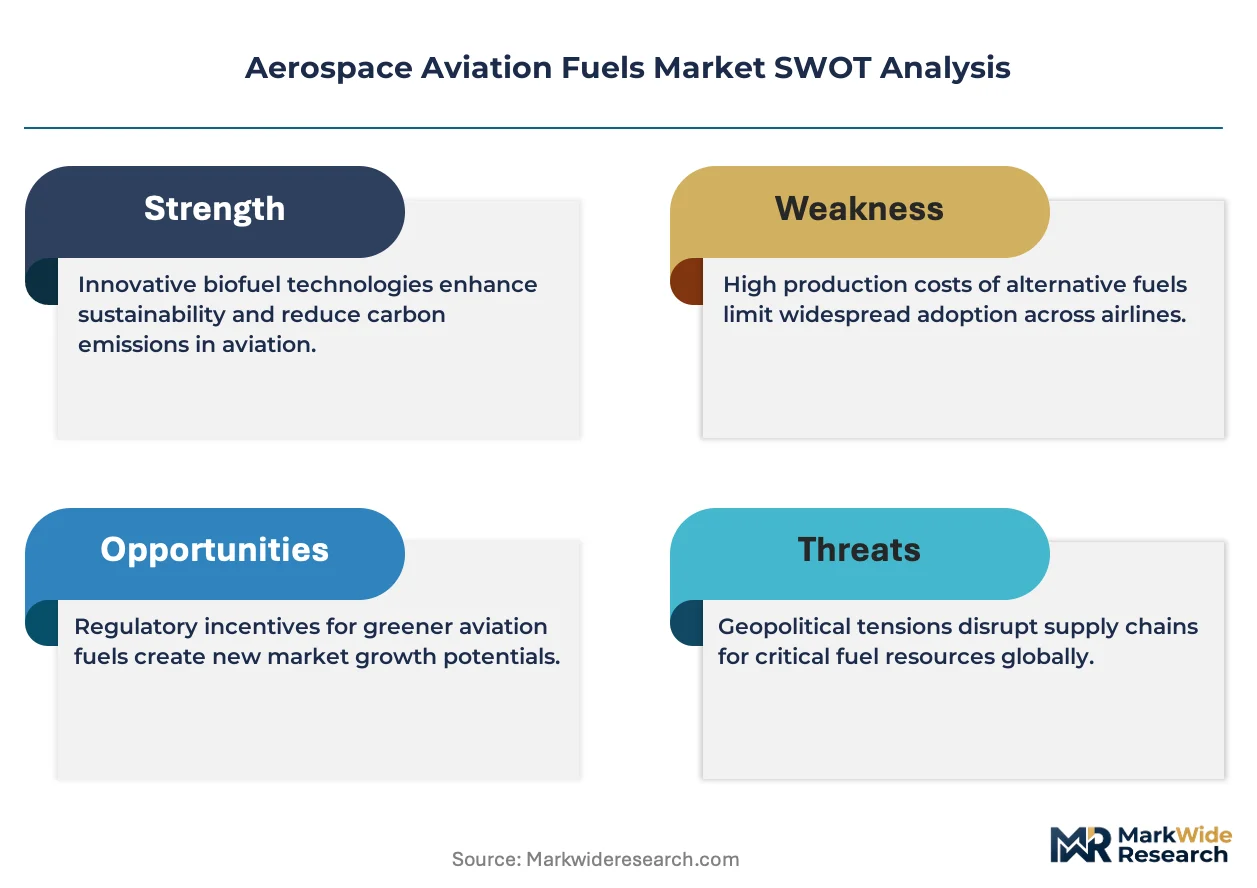
ReFuelEU Aviation mandates are compressing the timeline for sustainable aviation fuel integration, forcing refiners to reconfigure hydroprocessing units and airlines to rewrite procurement contracts before binding blending thresholds take effect.
Growth Catalysts
- EU Green Deal enforcement:Binding carbon intensity reduction obligations under the EU Green Deal are compelling European carriers to lock in long-term sustainable aviation fuel offtake agreements.
- Commercial fleet expansion:Long-haul fleet growth at major carriers is sustaining procurement volumes for Jet A-1 fuel across North American and Asia-Pacific routes.
- Defense logistics networks:Military aviation demand for JP-8 and JP-5 formulations is anchoring premium-grade fuel consumption in the United States through sustained defense procurement cycles.
Market Restraints
- Feedstock cost volatility:Used cooking oil and animal fat prices fluctuate with agricultural commodity cycles, squeezing margins for hydroprocessed esters and fatty acids producers.
- Refinery concentration risk:Middle East expansions in Saudi Arabia and the United Arab Emirates are concentrating kerosene-based jet fuel supply in a narrow geographic corridor vulnerable to regional disruptions.
- ASTM D7566 pathway limitations:FAA certification standards restrict alternative jet fuel production to seven approved pathways, blocking novel conversion technologies from commercial scale.
Strategic Opportunities
- Asia-Pacific SAF deployment:Japan and South Korea lack binding sustainable aviation fuel mandates, creating first-mover advantages for suppliers establishing regional blending infrastructure.
- Co-processing retrofits:Existing petroleum refineries can add renewable feedstock capability without greenfield construction, unlocking capital-efficient capacity expansion.
- Power-to-liquid synthetic fuels:Electrofuel production using renewable hydrogen and captured carbon dioxide qualifies for ReFuelEU Aviation synthetic fuel sub-targets.
Industry Challenges
- ASTM certification timelines:Novel sustainable aviation fuel pathways face multi-year approval processes at ASTM International, delaying commercial deployment.
- Book-and-claim accounting complexity:Airlines struggle to verify carbon intensity reductions across fragmented supply chains where physical fuel and environmental attributes separate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Aviation Fuels Market |
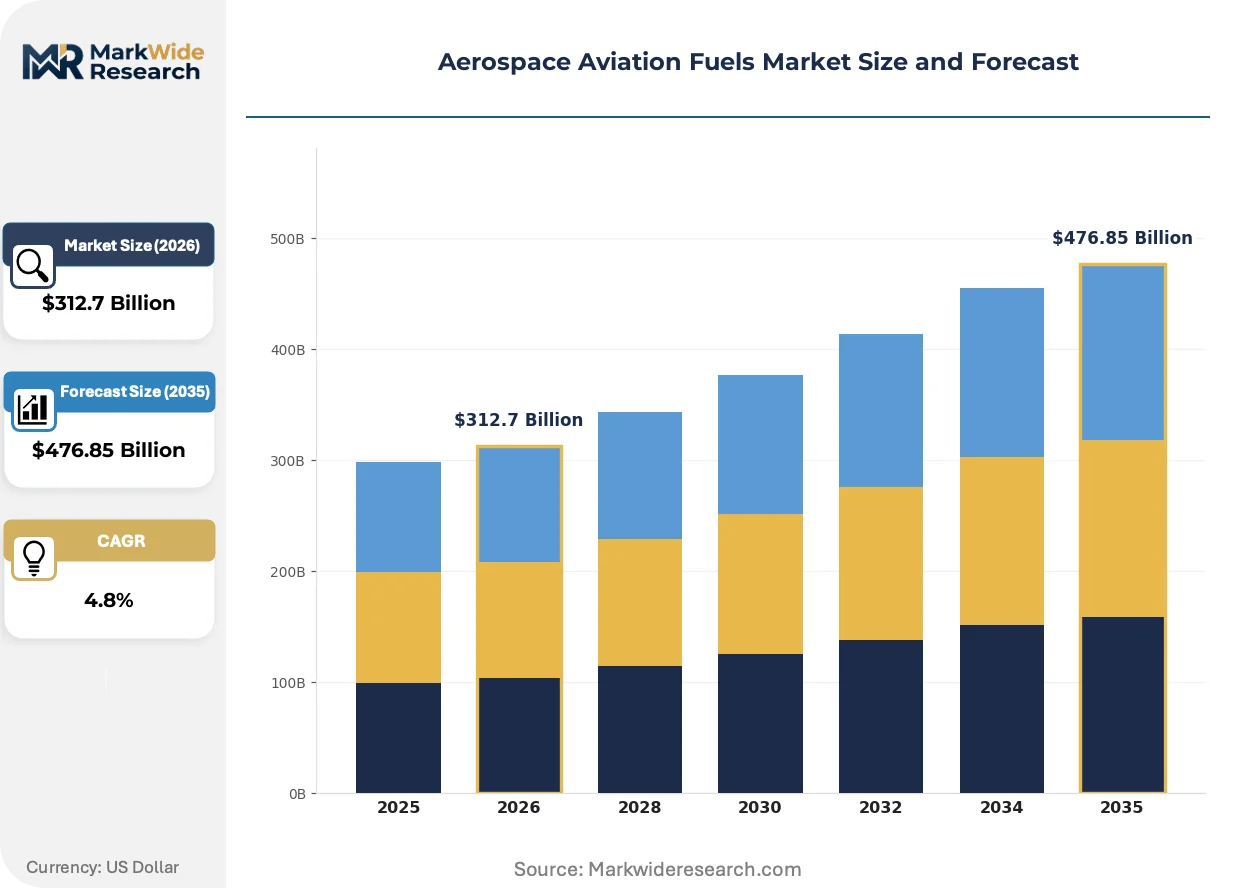
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Aviation Gasoline Application: Commercial Aviation, Military Aviation, General Aviation, Cargo Transport Distribution Channel: Direct Sales, Distributor, Retail, Online Platforms End User: Airlines, Private Operators, Military Forces, Cargo Companies |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, BP p.l.c., Shell, TotalEnergies, Neste, Valero Energy Corporation, World Energy, Indian Oil Corporation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Aviation Fuels Market Emerging Trajectories
Digital integration is transforming how fuel properties are monitored from refinery gate to aircraft wing, compressing quality assurance cycles and enabling real-time blending optimization.
Advanced sensor networks embedded in fuel storage and distribution infrastructure are digitizing custody transfer documentation. Major ground handlers at hub airports are deploying these systems to replace manual sampling protocols. The technology is digitizing compliance verification, collapsing the time between batch certification and aircraft uplift from hours to minutes.
ReFuelEU Aviation mandates progressively tighten sustainable aviation fuel blending obligations through 2035 and beyond. Refiners must now engineer co-processing capabilities that handle both petroleum-derived and biomass-derived feedstocks simultaneously. European Union member states are responding with national support schemes for refinery retrofits, while carriers renegotiate supply contracts to include price adjustment clauses tied to certificate values.
Fuel buyers are consolidating procurement through structured offtake agreements rather than spot market purchases. Long-haul carriers are locking in ten to fifteen year contracts with penalty clauses for supply shortfalls, displacing the traditional tender-based purchasing model. This pattern is most visible in the United States, where major network carriers have announced multi-billion dollar sustainable aviation fuel commitments with specific delivery schedules.
Aerospace Aviation Fuels Market Segmentation
Segmentation in aerospace aviation fuels reveals how procurement patterns, regulatory requirements, and operational specifications diverge across user types and distribution pathways. Understanding these divisions exposes where margin compression and premium capture opportunities concentrate.
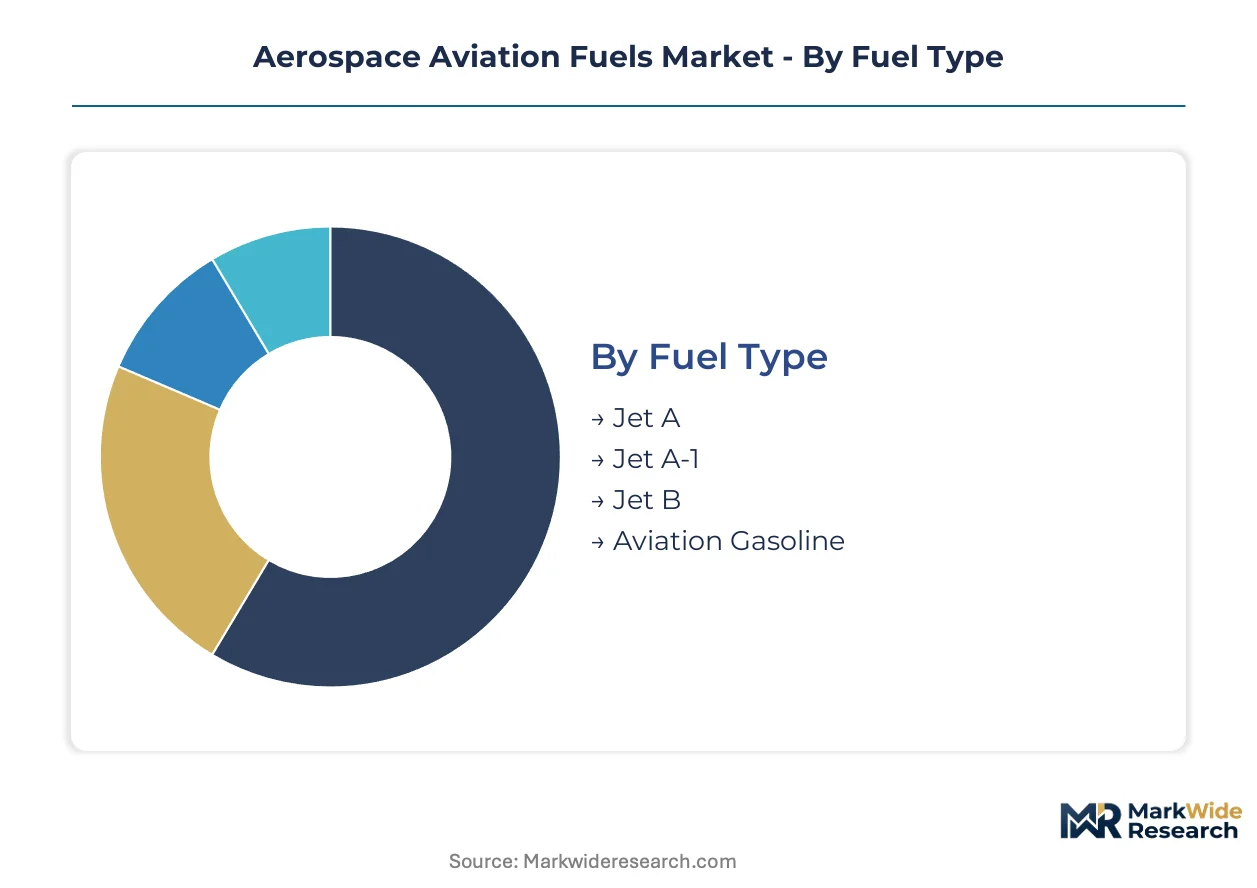
Fuel Type:
Cost tier differentiation separates commodity kerosene grades from specialized high-performance formulations and emerging synthetic alternatives.
- Jet A:A kerosene-based turbine fuel with freeze point of minus 40 degrees Celsius, primarily supplied to domestic United States routes where cold-weather performance demands are less severe. Demand concentrates with domestic carriers operating from southern hub airports where thermal specifications can be relaxed.
- Jet A-1:The dominant civil aviation grade delivering minus 47 degrees Celsius freeze point and enhanced thermal stability for long-haul operations. International carriers operating transatlantic and transpacific routes anchor procurement volumes, driven by ICAO fuel standards harmonization and cross-border operational requirements.
- Jet B:A wide-cut gasoline-kerosene blend formulated for extreme cold climates with freeze point below minus 50 degrees Celsius. Military operations in Arctic regions and select northern Canadian airports sustain niche demand.
- Aviation Gasoline:High-octane piston engine fuel for general aviation aircraft with lower energy density than turbine grades. Private flight schools and recreational pilots in the United States maintain steady offtake despite electrification pressures.
Jet A-1 commands the established base. The steepest expansion runs through synthetic and biomass-derived alternatives qualifying under ReFuelEU Aviation mandates.
Application:
Volume concentration and margin structure diverge sharply between scheduled passenger services, defense procurement, and fragmented general aviation operations.
- Commercial Aviation:Scheduled passenger and cargo services operating turbine aircraft on fixed routes. Fleet utilization normalization at major United States network carriers and Middle Eastern hub operators sustains the largest absolute fuel consumption segment.
- Military Aviation:Defense forces operating specialized JP-8 and JP-5 formulations with enhanced thermal oxidative stability. United States defense logistics networks anchor premium-grade consumption through multi-year procurement cycles insulated from commercial price volatility.
- General Aviation:Private and business aircraft operations outside scheduled airline services. Fragmented ownership across the United States and Europe limits contract scale, forcing reliance on spot market purchases and FBO retail pricing.
- Cargo Transport:Dedicated freighter operations and belly-hold cargo on passenger flights. E-commerce fulfillment networks at United States integrators and Asia-Pacific express carriers drive night-hub fueling demand with distinct temporal patterns from passenger operations.
Commercial Aviation absorbs the greatest volume. Military Aviation captures the highest margin per liter through specialized formulation requirements.
Distribution Channel:
Channel selection reflects contract scale, operational integration depth, and regulatory custody transfer complexity.
- Direct Sales:Refiner-to-airline contracts with dedicated pipeline or hydrant delivery at hub airports. Major United States network carriers and European flag carriers leverage volume concentration to negotiate long-term offtake agreements with price adjustment clauses tied to certificate values.
- Distributor:Independent fuel suppliers aggregating demand across multiple operators. Regional carriers in fragmented United States markets and emerging Asia-Pacific aviation clusters rely on distributor networks for supply security without capital-intensive infrastructure investment.
- Retail:Fixed-base operators and airport fuel farms selling to walk-up customers. General aviation pilots and charter operators at United States regional airports purchase through this channel, facing spot price exposure and limited contract protection.
- Online Platforms:Digital procurement interfaces for spot market transactions and sustainability certificate trading. Early adoption concentrates among European carriers managing ReFuelEU Aviation compliance documentation and book-and-claim accounting.
Direct Sales lock in the largest contract values. Online Platforms are gaining share fastest as compliance documentation requirements digitize.
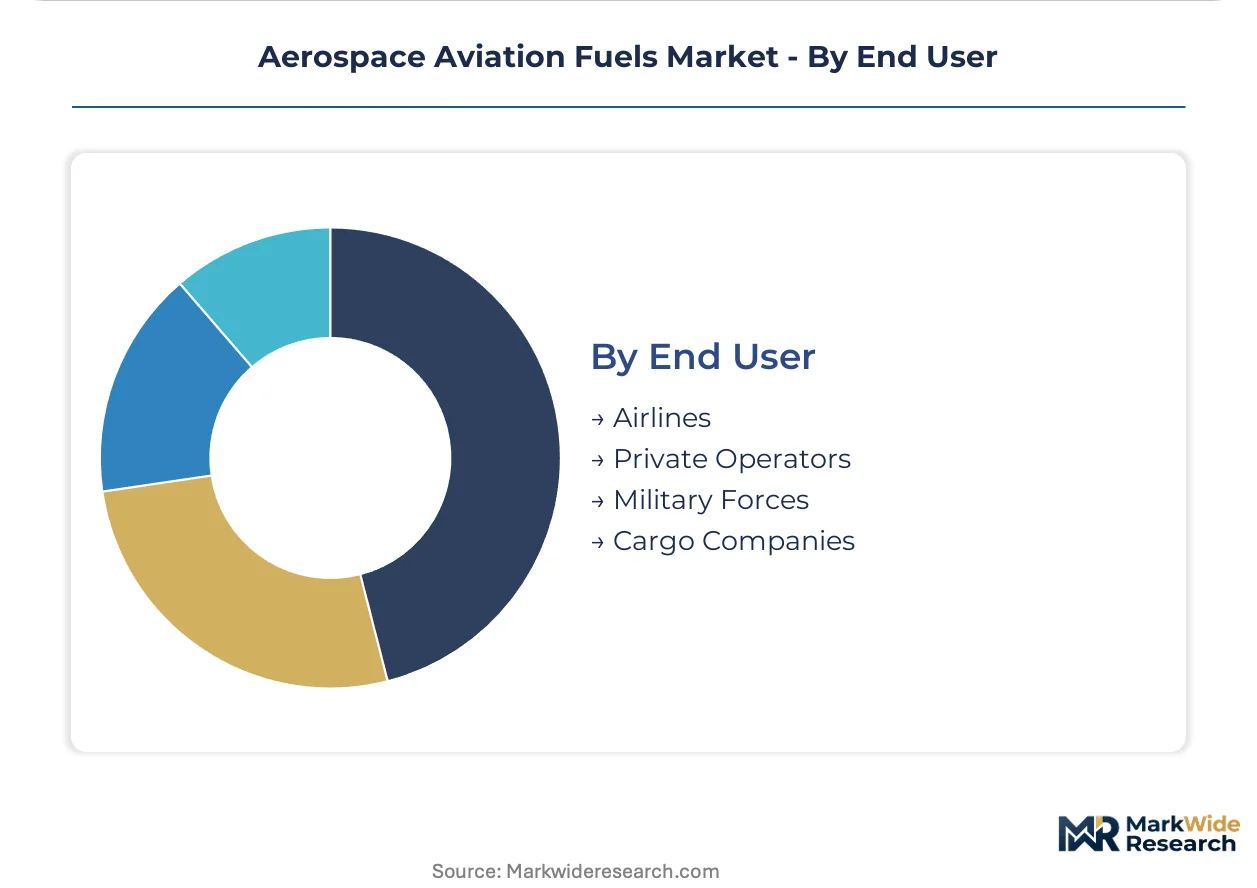
End User:
Customer type determines contract structure, sustainability obligation exposure, and supply security requirements.
- Airlines:Scheduled passenger and cargo carriers with fleet-scale procurement operations. United States major carriers and European network operators face binding ReFuelEU Aviation and ICAO CORSIA compliance obligations reshaping long-term supply agreements.
- Private Operators:Corporate flight departments, charter services, and fractional ownership programs. Fragmented demand across the United States limits negotiating leverage, forcing acceptance of distributor pricing and spot market exposure.
- Military Forces:Defense ministries with specialized fuel specifications and strategic stockpile requirements. United States defense logistics networks operate separate procurement systems with thermal stability standards exceeding commercial grades.
- Cargo Companies:Dedicated freight operators and express integrators with hub-and-spoke network structures. United States-based e-commerce fulfillment carriers sustain overnight fueling demand distinct from passenger airline schedules.
Airlines generate the greatest procurement volume. Cargo Companies are expanding offtake most quickly as e-commerce air freight volumes climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification standards under ASTM D7566 govern alternative jet fuel pathways in the United States, anchoring regulatory influence across the dominant geography. EASA enforces comparable sustainability criteria across European Union member states. ICAO Carbon Offsetting and Reduction Scheme for International Aviation binds cross-border carriers to emissions monitoring requirements that reshape procurement priorities worldwide.
United States
Major network carriers and defense logistics networks anchor national consumption patterns for Jet A-1 and military-grade formulations. FAA mandates under ASTM D7566 restrict alternative jet fuel production to seven approved pathways, blocking novel conversion technologies from commercial scale. The Gulf Coast refinery corridor concentrates kerosene-based jet fuel production, with integrated upstream-downstream assets sustaining cost-competitive output.
Germany
Binding carbon intensity reduction obligations under the EU Green Deal compel carriers to lock in long-term sustainable aviation fuel offtake agreements. ReFuelEU Aviation mandates progressively increase blending obligations for synthetic and biomass-derived fuels through 2035. The Leuna refinery complex and Hamburg aviation hub are reconfiguring hydroprocessing units to handle renewable feedstocks simultaneously with petroleum-derived inputs.
United Arab Emirates
Middle East refinery expansions are rewriting regional supply dynamics for kerosene-based jet fuel with concentrated new capacity coming online. The country's national petroleum regulator oversees product quality standards aligned with ICAO fuel specifications. Jebel Ali and Abu Dhabi industrial zones host integrated refining and export infrastructure serving Asia-Pacific and African aviation markets.
Japan
The absence of binding sustainable aviation fuel mandates creates first-mover advantages for suppliers establishing regional blending infrastructure. METI coordinates national energy transition frameworks that incentivize power-to-liquid synthetic fuel pilot projects. The Chubu/Nagoya industrial corridor and Tokyo Bay logistics clusters are emerging as early deployment sites for electrofuel production using renewable hydrogen.
Saudi Arabia
Refinery expansion programs are concentrating kerosene-based jet fuel supply capacity in a narrow geographic corridor vulnerable to regional disruptions. The country's national petroleum regulator maintains product specifications for export markets across Asia and Europe. The Eastern Province industrial zone around Jubail is adding hydroprocessing capacity targeting aviation fuel yield optimization.
Aerospace Aviation Fuels Market Vendor Landscape
Integrated petroleum majors and specialized renewable fuel producers split the market between conventional refinery dominance and emerging sustainable aviation fuel capacity. The competitive structure reflects a tiered hierarchy where upstream-integrated players leverage crude access against hydroprocessed esters and fatty acids specialists competing on feedstock security. Two strategic archetypes define positioning: legacy refiners with co-processing retrofit capabilities, and pure-play renewable producers with dedicated biomass supply chains. Dominant competitive moves include refinery co-processing retrofits for renewable feedstock handling, and long-term offtake agreements with penalty clauses for supply shortfalls.
Among integrated petroleum majors, Exxon Mobil Corporation and BP p.l.c. exemplify divergent strategic postures within the same archetype. Neste occupies a distinct position representing the renewable-specialist tier with hydroprocessed esters and fatty acids capacity differentiated through feedstock security rather than conventional crude dependency. These three companies illustrate how competitive positioning separates legacy refinery integration from biomass-derived fuel specialization.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP p.l.c. |
| Shell |
| TotalEnergies |
| Neste |
| Valero Energy Corporation |
| World Energy |
| Indian Oil Corporation Ltd. |
| Others |
Supply Flow & Price Mechanics
Jebel Ali's concentrated refinery capacity expansion directly amplifies pricing leverage for Middle East kerosene suppliers negotiating long-term offtake terms with Asia-Pacific carriers. The Gulf Coast corridor's integrated upstream-downstream assets sustain cost-competitive Jet A-1 output that anchors North American pricing benchmarks.
Pricing Analysis
Geographic price spreads between the United States Gulf Coast and Singapore trading hubs compress during Middle East capacity ramp-ups while widening during regional supply disruptions. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by volume scale and ReFuelEU Aviation certificate values. Cost compression in sustainable aviation fuel tiers is intensifying because used cooking oil and animal fat feedstock costs fluctuate with agricultural commodity cycles. Cargo companies show highest price sensitivity due to thin e-commerce freight margins, while military aviation buyers accept premium pricing for JP-8 thermal stability specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for electrofuel component sourcing. Production concentrates in the United States, Saudi Arabia, and the United Arab Emirates, with raw material dependencies on crude oil, renewable hydrogen, and captured carbon dioxide. Single-source vulnerability in hydroprocessed esters and fatty acids feedstock markets threatens margin stability for European renewable fuel specialists. Distribution runs through dedicated pipeline and hydrant systems at hub airports, supplemented by distributor networks serving fragmented regional carrier demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. ReFuelEU Aviation's binding blending thresholds erect compliance barriers that favor incumbents with certified co-processing capabilities.
For Market Incumbents: Build regulatory moats by accelerating ASTM D7566 certification for novel conversion technologies before competitors clear multi-year approval timelines. Deepen backward integration into renewable feedstock supply chains to offset agricultural commodity volatility squeezing hydroprocessed esters and fatty acids margins. Secure long-term offtake agreements with penalty clauses that lock out emerging SAF specialists from airline procurement portfolios. For New Entrants and Emerging Players: Pursue Asia-Pacific SAF deployment opportunities in Japan and South Korea where binding mandates remain absent and first-mover infrastructure advantages await. Target power-to-liquid synthetic fuel production qualifying for ReFuelEU Aviation synthetic sub-targets, leveraging METI pilot project incentives in the Chubu industrial corridor. Establish co-processing retrofit partnerships with petroleum refineries seeking capital-efficient renewable capacity without greenfield construction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydroprocessed esters and fatty acids specialists with secured feedstock supply chains over conventional refinery operators facing stranded asset risk. Long-term viability across the analysis window hinges on ReFuelEU Aviation compliance threshold enforcement and ICAO CORSIA carbon offset pricing trajectories. Watch for ASTM International certification timeline acceleration as the inflection signal indicating novel pathway commercialization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Co-Processing Retrofit | Enables simultaneous petroleum and biomass feedstock handling at Leuna and Hamburg complexes under EU Green Deal support schemes. |
| Long-Term SAF Offtake Agreement | Locks in ten to fifteen year supply commitments with United States network carriers displacing tender-based purchasing models. |
| Power-to-Liquid Pilot Deployment | Qualifies for ReFuelEU Aviation synthetic fuel sub-targets through electrofuel production using renewable hydrogen at Chubu corridor sites. |
| ASTM D7566 Pathway Certification | Clears FAA approval barriers blocking novel conversion technologies from commercial scale in United States aviation markets. |
| Feedstock Supply Chain Integration | Secures used cooking oil and animal fat streams against agricultural commodity cycle volatility squeezing HEFA producer margins. |
Methodological Framework
Cross-validation between trade flow databases and refinery capacity disclosures anchors the qualitative findings on Middle East supply expansion dynamics. Primary interviews with refinery operations managers, airline fuel procurement directors, sustainable aviation fuel technology specialists, and defense logistics procurement officers combined with secondary validation against EIA data, IEA reports, SEC 10-K filings, and customs/trade records. Bottom-up segmentation modeling and top-down macroeconomic calibration triangulate volume and value estimates.
Calibration against historical capacity utilization rates and announced refinery expansion timelines shapes the projection framework across the analysis window. Segmentation dimensions include fuel type tier, application segment, distribution channel structure, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points including ReFuelEU Aviation threshold implementation. Forecast inputs incorporate airline fleet delivery schedules and electrofuel pilot project commissioning timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play renewable producers with dedicated biomass supply chains would shift outcomes. Forecasts reflect assumptions on ASTM certification timeline durations and feedstock cost correlation stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
China LNG Bunkering Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
Turbine Drip Oil Market
Fuels
Global Fuel Ethanol Market
Fuels
Fuel Quality Testing Market
Fuels
Methane Market
Fuels
Wood Pellet Market
Fuels
High Octane Racing Fuel Market
Fuels
Emulsified Fuel Market
Fuels
Bunker Fuel Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Fuel Conditioning System Market
Fuels
Gas Hydrates Market