
 LPG Cylinder Manufacturing Market | 2026-2036
LPG Cylinder Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
LPG Cylinder Manufacturing Market Foresight
LPG cylinder distribution through national oil company retail networks is reconfiguring across South Asia and Latin America. Confidence Petroleum India Limited leverages its bottling plant network to anchor rural penetration in India. Hexagon Ragasco AS specializes in composite cylinder technology for advanced markets. Shandong Huanri Group Co. Ltd. dominates steel cylinder exports through manufacturing scale and cost positioning.
LPG cylinder manufacturing encompasses the industrial production of pressure vessels designed to store and transport liquefied petroleum gas under pressures typically ranging from 8 to 30 bar, with wall thickness and seam integrity governed by ISO 22991 and national welding certification standards. These containers serve residential cooking, commercial heating, and automotive fuel systems where safe containment of propane-butane mixtures remains critical. Steel cylinders retain volume leadership across developing markets due to lower unit cost and established requalification infrastructure, while composite cylinders command premium positioning in recreational marine and camping segments where weight reduction drives substitution. The residential end user category absorbs the largest share of output as government subsidy programs expand LPG access in rural households.
India's BIS certification and China's GB 5842 standard enforce hydrostatic testing protocols and periodic revalidation cycles that sustain replacement demand and bar uncertified imports. The EU F-Gas Regulation and REACH compliance frameworks in Europe impose material traceability requirements on cylinder coatings and valve assemblies. Stakeholders must monitor composite material cost curves and national distribution tender structures to calibrate capacity allocation between steel and advanced polymer offerings.
Market Dynamics
Composite cylinder technology is forcing capacity reallocation across steel-dominant production bases, as weight-sensitive applications in marine and outdoor recreation pull manufacturing investment toward polymer-wrapped pressure vessels.
Growth Catalysts
- India's PMUY LPG Access Program:Government subsidy structures under the Pradhan Mantri Ujjwala Yojana mandate cylinder distribution to rural households, sustaining replacement demand cycles and domestic manufacturing load.
- ISO 22991 Standard Harmonization:Unified international testing protocols for seam integrity and hydrostatic validation enable cross-border cylinder trade and reduce requalification friction for exporters.
- Automotive LPG Conversion:Fleet operators in Brazil and Turkey adopt gaseous fuel systems for cost arbitrage against gasoline, expanding cylinder demand beyond residential cooking into transportation fuel storage.
Market Restraints
- Steel Scrap Price Volatility:Hot-rolled coil input costs swing with Chinese export policy and energy-intensive production curbs, compressing margin predictability for welded cylinder fabricators.
- Requalification Infrastructure Concentration:Hydrostatic testing and valve replacement capacity clusters in urban centers, leaving rural distributors with extended turnaround times and working capital tied up in cylinder float.
- Composite Material Cost Premium:Glass-fiber and epoxy resin formulations command 3-4x steel equivalent pricing, limiting substitution to weight-critical niches despite safety advantages.
Strategic Opportunities
- Indonesia's Pertamina Distribution Tender Restructuring:National oil company procurement decentralization opens bottling plant partnerships for independent cylinder suppliers previously locked out of state channels.
- Smart Cylinder IoT Integration:Embedded weight sensors and GPS tracking converge with valve telemetry to enable pay-per-use billing models and theft prevention in last-mile LPG delivery.
- EU F-Gas Regulation Material Traceability:Coating and sealant documentation requirements create premium positioning for certified European manufacturers serving REACH-compliant industrial gas segments.
Industry Challenges
- Welder Certification Pipeline Shortage:ISO 9606-qualified pressure vessel welders retire faster than vocational programs replenish qualified labor, extending production lead times for seam-critical cylinder orders.
- BIS Type Approval Timeline Compression:India's Bureau of Indian Standards factory audit and sample testing cycles stretch 8-14 months, delaying market entry for new composite cylinder entrants against incumbent steel suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LPG Cylinder Manufacturing Market |
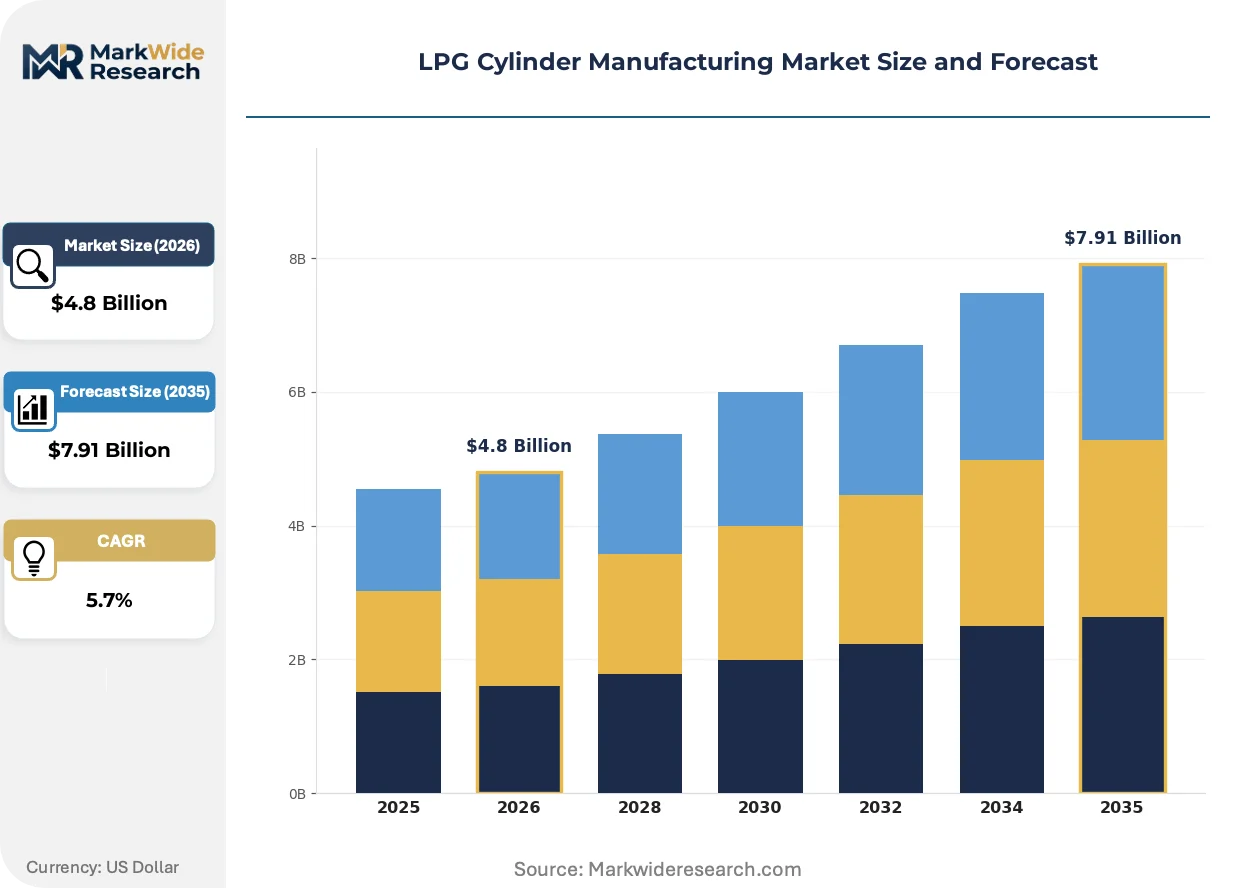
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refillable Cylinders, Disposable Cylinders, Portable Cylinders, Composite Cylinders Material: Steel, Aluminum, Composite, Plastic Manufacturing Technique: Welding, Forging, Casting, Machining End User: Residential, Commercial, Industrial, Automotive |
| Companies Covered | Aygaz A.S., Confidence Petroleum India Limited, ECP Industries Limited, Hexagon Ragasco AS, Manchester Tank, Mauria Udyog Ltd., Sahamitr Pressure Container PLC, Satyasai Pressure Vessels Group, Shandong Huanri Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LPG Cylinder Manufacturing Market Shifts & Advancements
Material science advances and regulatory digitization are restructuring how cylinders are certified, tracked, and monetized across residential and industrial gas distribution networks.
Filament-wound composite pressure vessels are hybridizing steel and polymer architectures to capture safety and weight benefits without full material substitution. Camping equipment retailers and marine fuel system integrators adopt these hybrid constructions for portable LPG storage. The technology is hybridizing product segmentation, compressing the addressable market for conventional steel cylinders in premium outdoor recreation channels.
Europe's F-Gas Regulation imposes granular material traceability on cylinder coatings, valve elastomers, and sealant compounds used in refrigerant and industrial gas containment. Manufacturers must document substance volumes through supply chain tiers to ECHA reporting standards. Composite cylinder producers serving Nordic marine markets face accelerated compliance timelines as national regulators front-load enforcement ahead of 2027 review cycles.
Pay-per-use cylinder leasing models displace outright purchase in urban Indian and Brazilian household segments, transferring ownership risk to distributors and bundling maintenance into recurring fees. National oil company retail networks pilot subscription pricing through mobile payment integration. Maharashtra and São Paulo metropolitan clusters show fastest adoption where digital wallet penetration enables automated refill scheduling and deposit-free cylinder exchanges.
LPG Cylinder Manufacturing Market Segmentation
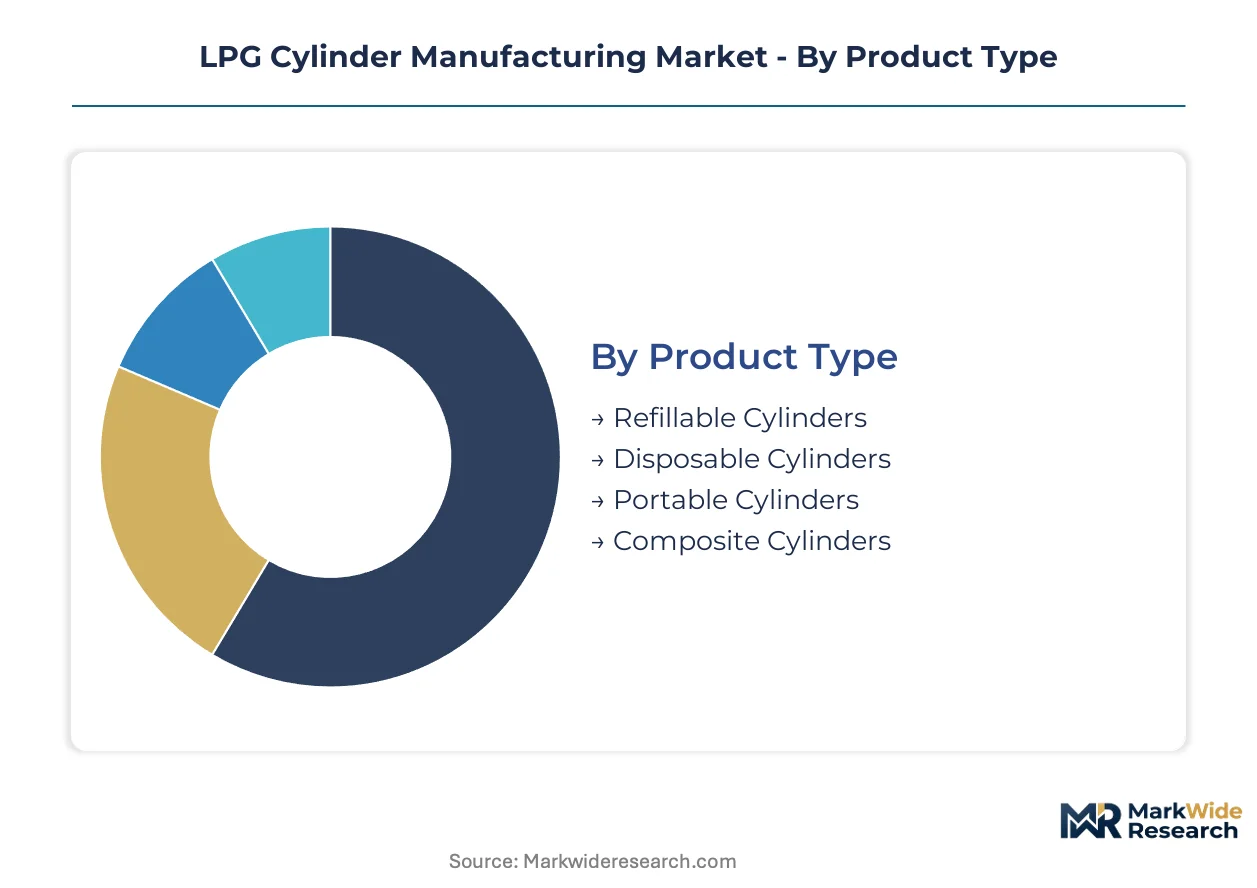
LPG cylinder manufacturing segments reflect divergent cost structures and regulatory tolerances across pressure vessel applications. Product type and material selection determine certification pathways, requalification cycles, and geographic market access for fabricators.
Product Type:
Mature refillable systems dominate installed base economics while emerging composite formats capture weight-sensitive niches.
- Refillable Cylinders:Seam-welded steel vessels designed for 10-year service life with periodic hydrostatic revalidation under ISO 22991 protocols. India's PMUY distribution network and Brazil's national oil company retail channels concentrate demand for 14.2kg and 13kg domestic formats.
- Composite Cylinders:Filament-wound glass-fiber epoxy pressure vessels with polymer liners achieving 50-70% weight reduction versus steel equivalents. Marine fuel systems and premium camping equipment in Nordic markets absorb output despite 3-4x cost premium.
- Disposable Cylinders:Single-use steel canisters for portable cooking and torch applications.
- Portable Cylinders:Compact 3-5kg formats targeting outdoor recreation and mobile food vending.
Refillable cylinders handle the majority of throughput; composite formats are expanding most quickly in recreational marine channels.
Material:
Cost tier stratification separates commodity steel from performance-optimized aluminum and polymer composites.
- Steel:Hot-rolled coil construction with longitudinal seam welding dominates volume production. Indian and Chinese fabricators leverage scrap metal integration and scale economies to supply Africa, Southeast Asia, and Latin America.
- Composite:Glass-fiber and carbon-fiber reinforced epoxy systems enabling non-corrosive, translucent-wall designs. EU F-Gas Regulation material traceability requirements and REACH coating compliance favor certified European producers.
- Aluminum:Extruded and spun alloy vessels for aviation and specialty transport.
- Plastic:Polymer-lined barrier constructions for low-pressure camping applications.
Steel absorbs the dominant share of unit volume; composite materials show steepest expansion trajectory in regulated industrial gas segments.
Manufacturing Technique:
Application requirements dictate process selection from high-volume welding to precision forging for critical seams.
- Welding:Automated MIG and submerged arc processes for longitudinal and circumferential seams on steel cylinders. ISO 9606-qualified welder scarcity extends lead times for pressure-certified orders.
- Forging:Seamless construction for high-pressure automotive and industrial gas cylinders.
- Casting:Valve boss and foot ring components.
- Machining:Precision finishing for threaded connections and safety valve seats.
Welding underpins most residential cylinder output; forging commands premium positioning in automotive fuel system supply.
End User:
Customer type segmentation separates subsidized household access programs from self-funding commercial and fleet conversion demand.
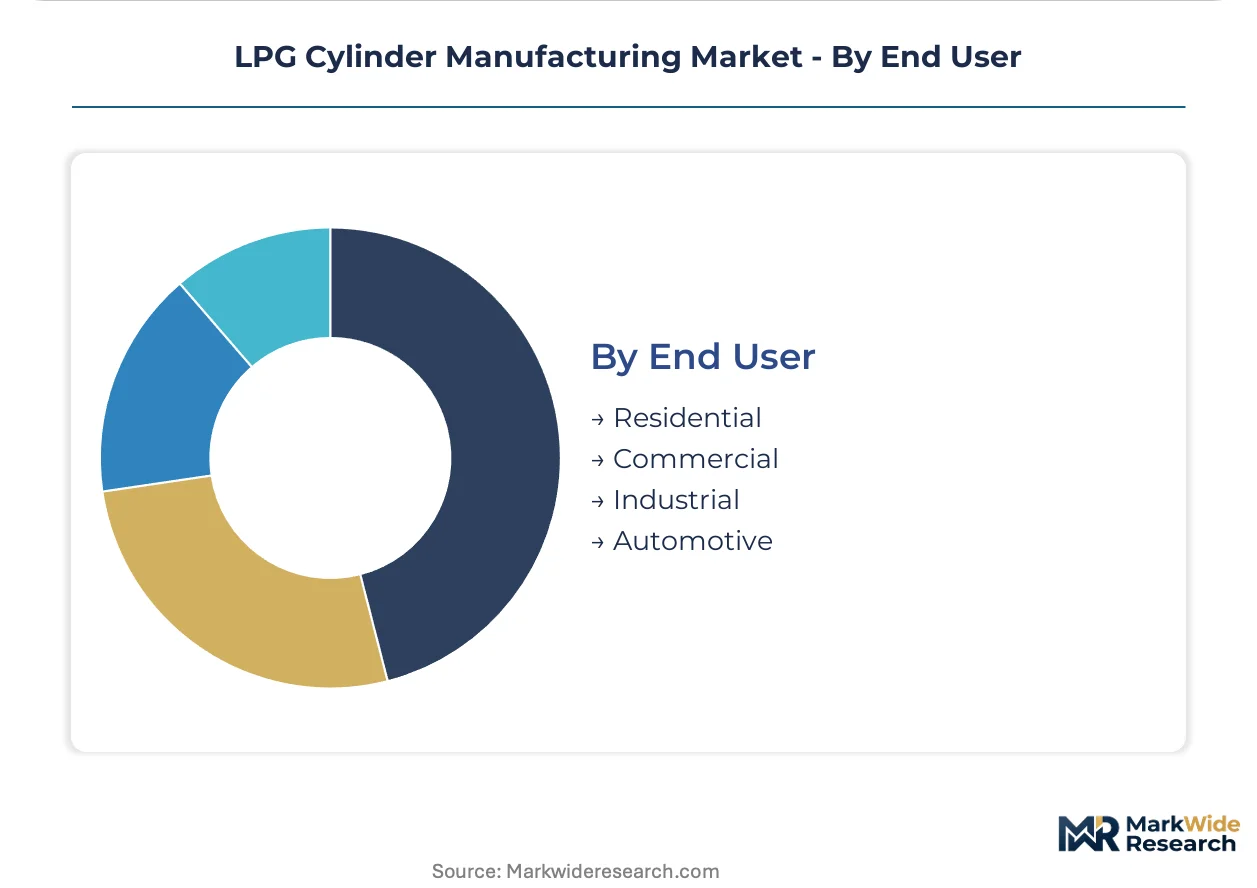
- Residential:Government subsidy programs in India, Indonesia, and Brazil drive cylinder distribution to rural households. BIS certification and national oil company tender structures shape supplier eligibility.
- Automotive:LPG conversion kits for taxi and delivery fleets in Turkey and Brazil create cylinder demand for toroidal and cylindrical tank configurations.
- Commercial:Restaurants, hotels, and institutional kitchens.
- Industrial:Forklift fuel systems and metal cutting applications.
Residential channels anchor volume demand; automotive conversion represents the fastest share gainer among end-use categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hazira Port complex on India's western seaboard anchors the largest steel cylinder export corridor to Africa and Southeast Asia, with dedicated bulk handling infrastructure for pressure vessel logistics.
India
Rural household penetration under PMUY drives cylinder demand across Bihar, Uttar Pradesh, and Odisha. BIS certification mandates 14.2kg domestic formats with hydrostatic revalidation cycles. The Jamshedpur-Rourkela steel belt feeds raw material to fabrication clusters in Maharashtra and Gujarat.
China
GB 5842 standard enforcement sustains replacement demand for welded steel vessels across domestic and export channels. Shandong Province concentrates hot-rolled coil processing and longitudinal seam welding capacity. Qingdao port infrastructure handles bulk cylinder shipments to Latin America and Africa.
Brazil
Automotive LPG conversion programs in São Paulo and Rio de Janeiro expand toroidal tank demand beyond residential cooking. ANVISA alignment with ISO 22991 enables cross-border trade with Argentine and Uruguayan distributors. The ABC Paulista industrial corridor hosts valve assembly and coating facilities.
Indonesia
Pertamina's decentralized procurement restructuring opens bottling plant partnerships for independent suppliers in Java and Sumatra. National 3kg subsidy program targets household access in Eastern provinces. Surabaya manufacturing clusters serve the archipelago's inter-island distribution network.
Turkey
Fleet conversion to autogas systems in Istanbul and Ankara sustains cylindrical and toroidal tank demand from taxi operators. Alignment with EU F-Gas Regulation traceability requirements positions exporters for Nordic marine markets. The Kocaeli industrial zone concentrates forging and machining capacity for high-pressure automotive applications.
LPG Cylinder Manufacturing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and precision machining. The vendor base stratifies across three tiers: national oil company-aligned distributors with bottling network control, export-focused steel fabricators leveraging scale economies, and composite technology specialists serving premium weight-sensitive niches. Dominant competitive moves include capacity expansion into government tender channels and backward integration into hot-rolled coil processing to defend margin positions against scrap volatility.
Among India-based entities, Confidence Petroleum India Limited occupies a position within the distribution-integrated tier, while Mauria Udyog Ltd. represents the domestic fabrication archetype. Hexagon Ragasco AS exemplifies the composite specialization vector serving Nordic marine and outdoor recreation channels. Shandong Huanri Group Co. Ltd. anchors the export-scale segment with China-based steel cylinder production.
| Leading Market Players |
|---|
| Aygaz A.S. |
| Confidence Petroleum India Limited |
| ECP Industries Limited |
| Hexagon Ragasco AS |
| Manchester Tank |
| Mauria Udyog Ltd. |
| Sahamitr Pressure Container PLC |
| Satyasai Pressure Vessels Group |
| Shandong Huanri Group Co. Ltd. |
| Others |
Supply & Pricing Matrix
Hot-rolled coil concentration in China's Shandong and Hebei provinces feeds margin compression downstream, as steel cylinder fabricators in India and Brazil absorb input cost volatility while national oil company tender structures cap pass-through pricing power. The resulting margin pool concentrates with distributors controlling bottling plant networks and requalification infrastructure, not with commodity vessel producers.
Pricing Analysis
Volume-discount tiering structures dominate national oil company procurement, with 14.2kg domestic formats in India and 13kg standards in Brazil priced by lot size and requalification bundling. Price differentiation hinges on BIS certification grade and geographic delivery radius to rural distributors. Cost compression in steel-welded segments is intensifying because Chinese export policy swings disrupt scrap metal arbitrage. National oil company retail networks show lowest price sensitivity; independent rural distributors face highest working capital pressure from cylinder float requirements.
Supply Chain Analysis
Upstream feedstock flows draw from Chinese hot-rolled coil mills, Indian scrap metal integration clusters, and Brazilian flat steel producers. Raw material dependencies center on seam welding wire, valve brass forgings, and epoxy resin systems for composite liners. Single-source vulnerability concentrates in ISO 9606-qualified welder pools, where vocational program output lags retirement rates. Distribution runs through national oil company retail networks in India, Pertamina channels in Indonesia, and independent bottling plant partnerships in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national oil company procurement offices, as India's PMUY program and Indonesia's Pertamina tender restructuring concentrate cylinder offtake under fewer decision-makers with standardized specification authority.
For Market Incumbents: Pre-empt composite cylinder substitution in marine and camping channels by securing filament-wound capacity partnerships before BIS type approval timelines lock out new entrants. Backward integration into hot-rolled coil processing defends margin positions against Chinese scrap volatility. Channel control through bottling plant network expansion anchors rural penetration where requalification infrastructure scarcity extends distributor lock-in. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's decentralized Pertamina procurement restructuring, where independent bottling plant partnerships previously locked out of state channels now access national distribution. Composite cylinder white space in Nordic marine fuel systems offers penetrable premium positioning despite EU F-Gas Regulation traceability requirements. Go-to-market through marine equipment integrators bypasses incumbent steel cylinder distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward composite technology specialists with certified European manufacturing and REACH-compliant coating documentation, positioned for EU F-Gas Regulation enforcement acceleration ahead of review cycles. Long-term viability across the analysis window favors hybrid material architectures capturing weight reduction without full polymer substitution. The signal to watch is BIS type approval timeline compression for new composite entrants against incumbent steel suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hot-Rolled Coil Processing | Captive steel supply shields Indian fabricators from Chinese scrap export policy swings. |
| Composite Cylinder BIS Type Approval Investment | Early certification completion captures PMUY tender eligibility before incumbent lock-in solidifies. |
| Smart Cylinder IoT Integration Partnership | Embedded weight sensors enable pay-per-use billing through India's UPI digital wallet infrastructure. |
| Bottling Plant Network Expansion in Eastern Indonesia | Surabaya manufacturing clusters serve Pertamina's 3kg subsidy program in underpenetrated provinces. |
| EU F-Gas Regulation Compliance Certification | REACH-compliant coating documentation opens Nordic marine fuel system channels to Asian exporters. |
Research Methodology
Operator-level perspectives from plant managers at steel cylinder fabrication facilities, procurement leads at national oil company retail networks, and technical directors at composite pressure vessel specialists anchored the qualitative base. Secondary validation drew from BIS certification registries, GB 5842 standard documentation, ISO 22991 testing protocol records, and customs trade data for pressure vessel exports. Bottom-up unit economics across welding, forging, and filament-winding processes were triangulated against top-down national LPG distribution program targets.
Scenario-bracketing framed low, base, and high cases across the projection horizon by stress-testing PMUY household penetration rates, composite material cost curves, and welder certification pipeline replenishment. Segmentation dimensions modeled include product type, material composition, manufacturing technique, and end-user category. CAGRs were derived from installed base replacement cycles, government subsidy program expansion trajectories, and automotive LPG conversion fleet adoption patterns.
Stress conditions across steel scrap price volatility, BIS audit timeline variability, and composite resin supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about national oil company tender structures and regulatory harmonization progress. Cross-checking against national LPG distribution program budget allocations and actual household connection data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Emulsified Fuel Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Global Gas Cylinder Market
Fuels
Hydrogen Cylinder Market
Fuels
India Coal Market
Fuels
Oil Dispenser Market
Fuels
Wood Pellet Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Solid Fuel Tablet Market
Fuels
Coal Trading Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Gasoline As a Fuel Market
Fuels
Brazil LNG Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Gas Feed System Market