
 Gas Feed System Market | 2026-2036
Gas Feed System Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Feed System Market Insights
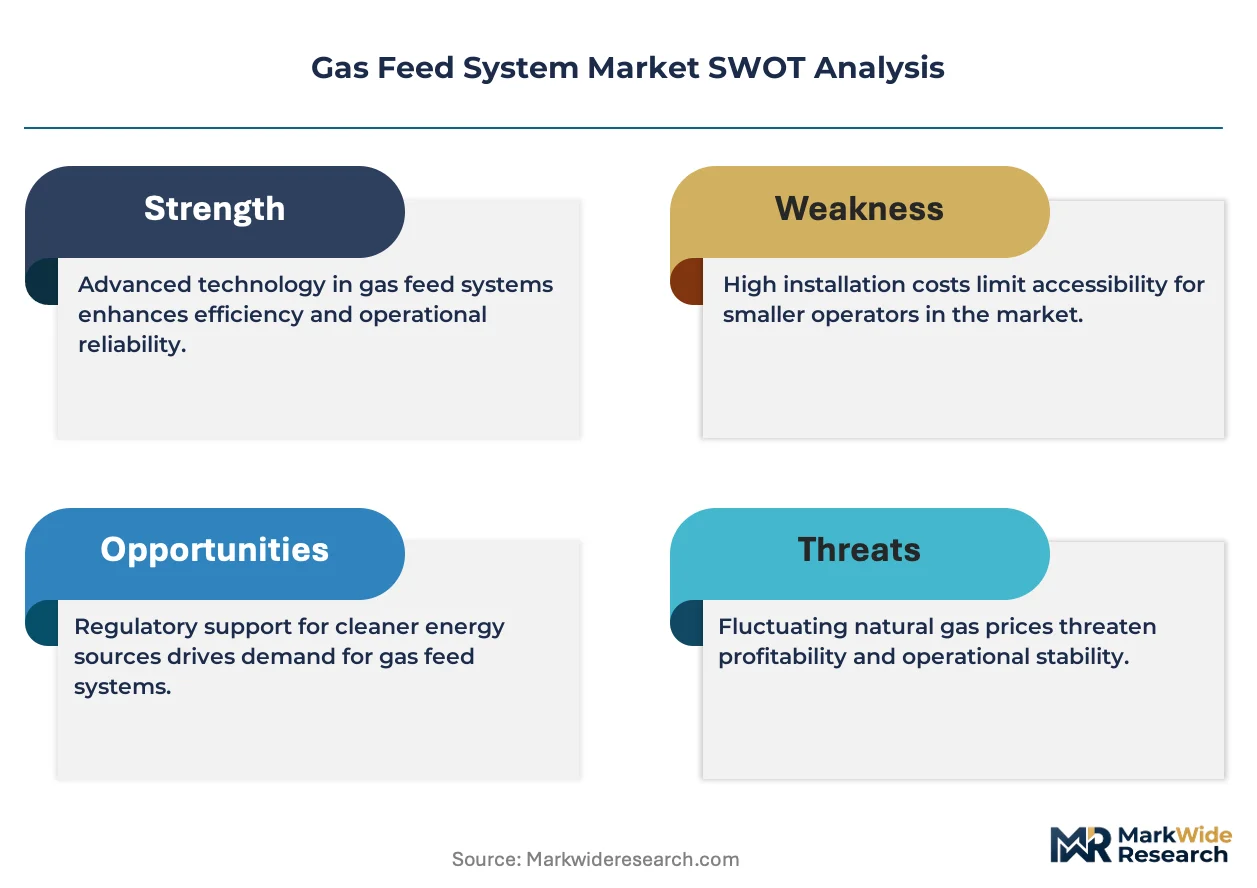
Premium gas feed system performance is decoupling from commodity hardware as semiconductor-grade purity requirements diverge from standard industrial specifications. Linde plc leverages its cryogenic engineering heritage to anchor high-purity gas delivery architectures. Messer Group GmbH competes through regional production density in Central European chemical corridors. Matheson Tri-Gas specializes in ultra-high-purity systems for advanced electronics manufacturing, sustaining technical differentiation against price-driven competitors.
Gas feed systems comprise pressure-controlled networks of regulators, manifolds, purifiers, and monitoring instrumentation engineered to deliver process gases at specified flow rates, purity levels, and pressures to industrial consumption points; stainless steel construction with electropolished surfaces achieves sub-ppb contamination control required by semiconductor and pharmaceutical protocols. Storage tanks and regulators command durable replacement cycles in mature chemical processing installations, while smart systems with predictive diagnostics capture expanding margin pools in pharmaceutical and research end uses where unplanned downtime carries catastrophic cost. Integrated solutions are consolidating mixing stations and purification stages into skid-mounted packages, displacing site-assembled conventional configurations in greenfield power generation and hydrogen fueling projects.
EPA mandates under the Clean Air Act and OSHA process safety management standards govern gas containment and leak detection protocols in United States industrial facilities, while the EU F-Gas Regulation phases down fluorinated greenhouse gases and redirects investment toward recovery and reclamation infrastructure. China's GB standards and MIIT industrial policy directives shape domestic procurement specifications and import substitution trajectories for gas handling equipment. Stakeholders must monitor regulatory divergence between jurisdictions as compliance architectures fragment and certification costs become a decisive factor in supplier selection and geographic market entry.
Market Dynamics
Semiconductor fabs in South Korea and Taiwan are demanding sub-ppb purity levels that obsolete legacy gas distribution architectures, forcing suppliers to reengineer surface electropolishing protocols and purge cycle automation.
Growth Catalysts
- EPA Clean Air Act enforcement:Tightening emissions standards for fluorinated process gases compel chemical processors to upgrade leak detection infrastructure and recovery systems.
- Hydrogen fueling infrastructure:National hydrogen strategies in Germany and Japan mandate high-pressure gas feed networks for mobility applications.
- Electropolished stainless steel surfaces:Advanced surface finishing techniques enable contamination control thresholds required by pharmaceutical aseptic manufacturing protocols.
Market Restraints
- Nickel alloy supply concentration:Specialty 316L stainless steel sourcing clusters in Chinese and Indian foundries expose equipment fabricators to raw material volatility.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases compress addressable market for conventional gas recovery equipment serving refrigeration and semiconductor etching.
- Ultra-high-purity certification timelines:SEMI standards compliance testing extends product qualification cycles by months, delaying revenue recognition for new system launches.
Strategic Opportunities
- Green hydrogen projects in Saudi Arabia:NEOM and similar developments require integrated gas feed and compression skids for electrolysis and ammonia synthesis.
- Modular skid-mounted systems:Pre-integrated packages displace field-assembled configurations in power generation and hydrogen fueling deployments.
- OSHA process safety management alignment:Compliance consulting bundled with hardware creates recurring revenue streams among US chemical processors.
Industry Challenges
- Welding technician scarcity:Orbital welding certification for electropolished stainless steel systems limits production scaling for specialized fabricators.
- Legacy system integration:Retrofitting predictive diagnostics into existing gas distribution networks requires custom engineering without standardized interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Feed System Market |
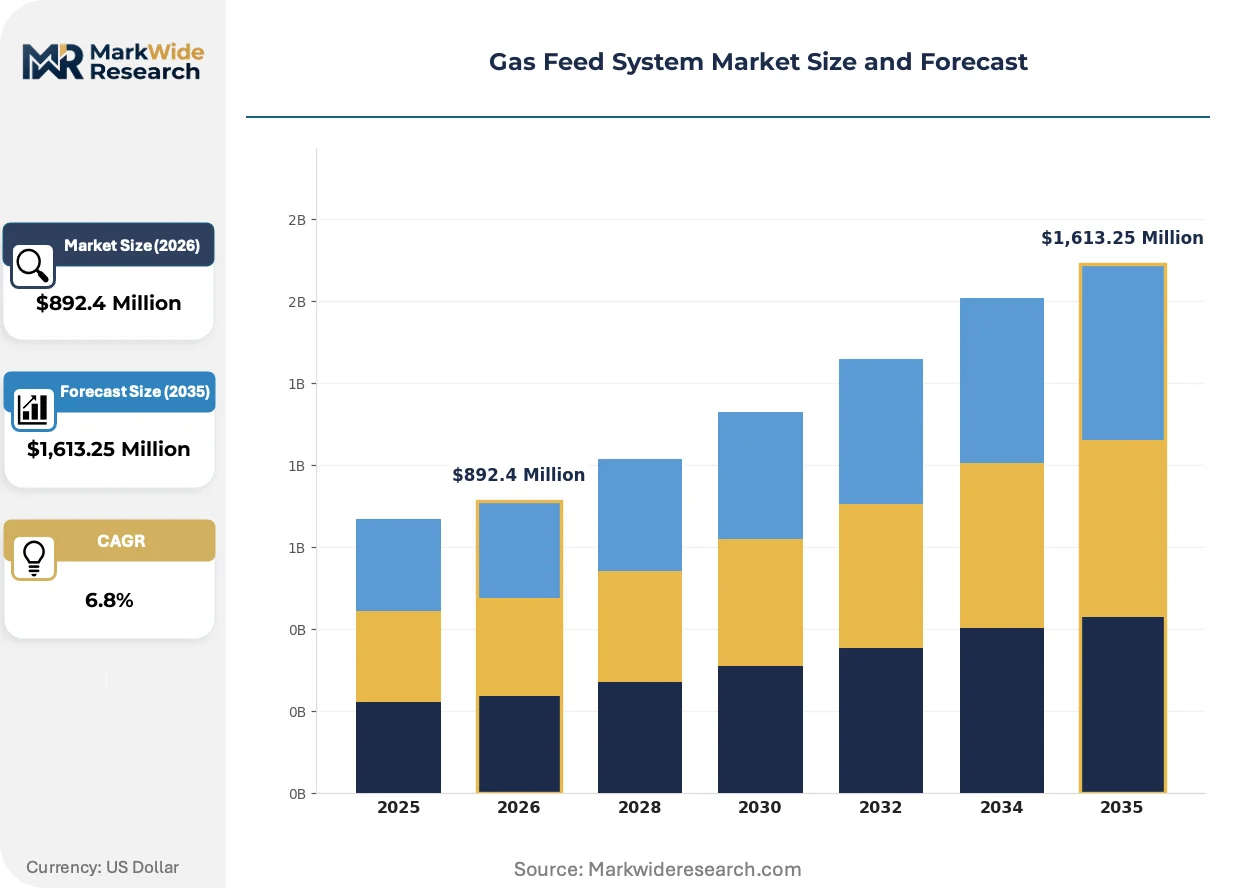
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry Systems, Mixing Stations, Storage Tanks, Regulators Application: Chemical Processing, Power Generation, Food Processing, Pharmaceuticals End User: Manufacturers, Energy Producers, Research Institutions, Hospitals Technology: Conventional Systems, Integrated Solutions, Smart Systems, Modular Units |
| Companies Covered | Linde plc, Messer Group GmbH, Matheson Tri-Gas, Inc., Iwatani Corporation, Taiyo Nippon Sanso Corporation, SIAD Group, Airgas, Inc., Universal Industrial Gases, Inc., Evoqua Water Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Feed System Market Trends and Innovations
Gas feed architecture is converging with digital instrumentation and predictive analytics, compressing maintenance cycles and enabling remote purity verification that alters site staffing models.
AI-driven contamination prediction algorithms are rewriting maintenance economics for high-purity gas distribution. Semiconductor fabs in Taiwan and South Korea deploy machine learning models that forecast molecular sieve degradation and filter replacement needs. This capability compresses unplanned downtime windows from days to hours, shifting supplier relationships toward performance-guaranteed service contracts.
The EU F-Gas Regulation mandates fluorinated gas recovery and reclamation infrastructure, redirecting capital toward closed-loop handling systems. Chemical processors in Germany and France face compliance deadlines that accelerate replacement of vented manifolds with sealed recovery architectures. Equipment suppliers are bundling reclamation modules with feed systems to capture margin from regulatory-driven upgrades.
Buyers in pharmaceutical manufacturing now unbundle hardware procurement from validation services, selecting specialized commissioning firms independent of equipment vendors. This fragmentation compresses vendor margins on installation while expanding third-party service markets. The pattern is most pronounced in North American and Western European facilities where FDA and EMA audit readiness requirements drive documentation rigor.
Gas Feed System Market Segmentation
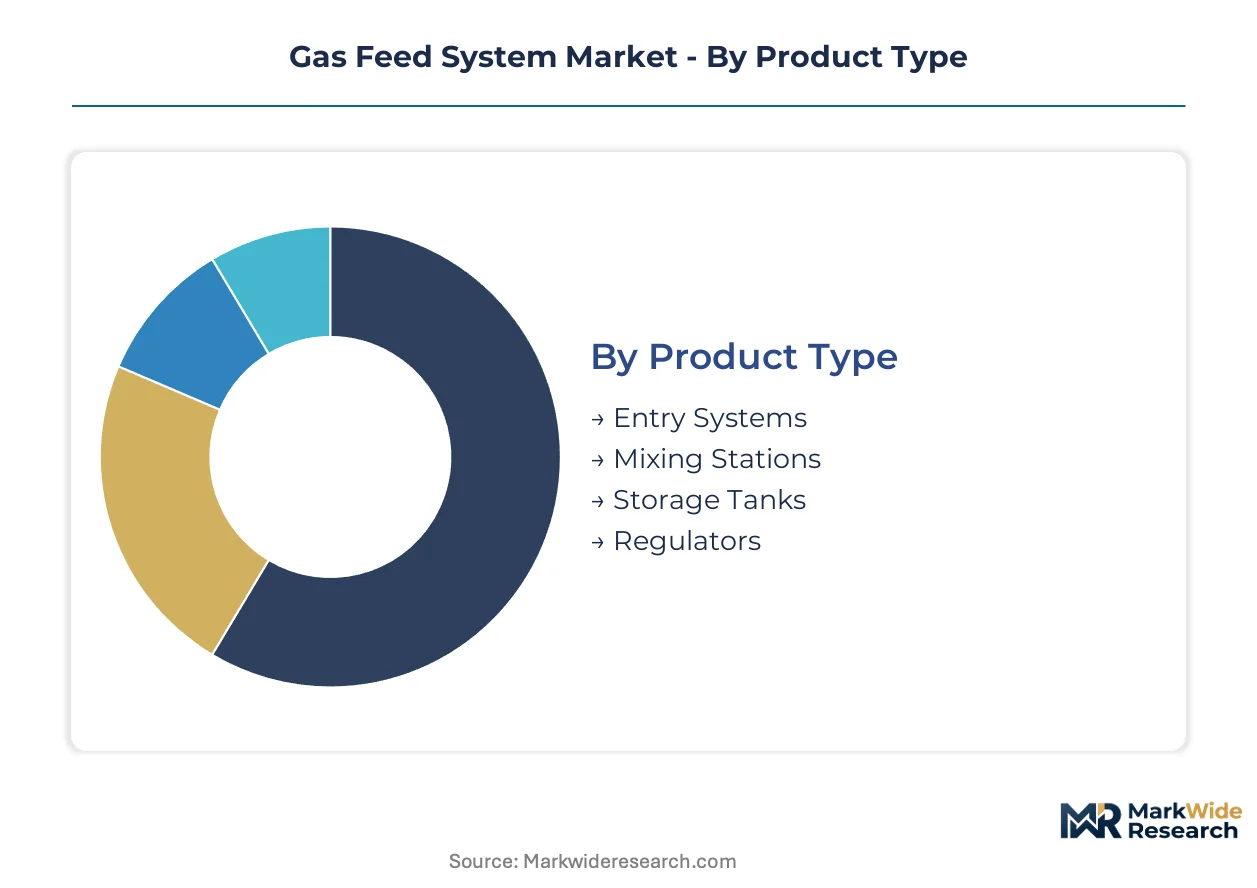
Gas feed system architectures diverge sharply between standalone installations and embedded process trains. Semiconductor fabs demand integrated purity chains while chemical plants run modular retrofits alongside legacy infrastructure.
Product Type:
Entry systems and mixing stations anchor standalone deployments where site assembly dominates, while storage tanks and regulators embed more deeply into continuous process lines.
- Entry Systems:These comprise point-of-use panels and gas cabinets that condition incoming supply streams through filtration and pressure reduction. South Korean semiconductor fabs specify these for bulk specialty gas delivery, driven by sub-ppb contamination protocols that obsolete conventional manifold designs.
- Mixing Stations:Precision blending skids combine multiple gas streams at controlled ratios for synthetic atmosphere generation. German chemical processors deploy these for hydrogen-nitrogen mixtures in metal treatment, constrained by EU F-Gas Regulation phase-down timelines that compress project windows.
- Storage Tanks:Cryogenic vessels and high-pressure cylinders buffer supply against demand spikes in continuous operations.
- Regulators:Pressure control devices step down cylinder pressure to process requirements across distributed networks.
Volume placements concentrate in storage tanks and regulators; the faster expansion belongs to mixing stations.
Application:
Application segments stratify by purity tolerance, with pharmaceutical and semiconductor-adjacent chemical processing commanding premium specifications against bulk industrial uses.
- Chemical Processing:Petrochemical crackers and specialty chemical reactors consume the largest gas volumes through centralized distribution headers. Chinese coastal complexes drive capacity additions, though EPA enforcement on fluorinated emissions redirects US investment toward recovery-integrated architectures.
- Pharmaceuticals:Aseptic manufacturing mandates electropolished surfaces and automated purge cycles for sterile gas delivery. FDA inspection readiness requirements in North American facilities extend validation timelines, compressing hardware margins while expanding third-party commissioning markets.
- Power Generation:Gas turbines and fuel cells require moisture-controlled hydrogen and natural gas feeds.
- Food Processing:Modified atmosphere packaging and cryogenic freezing deploy nitrogen and carbon dioxide systems with standard industrial specifications.
Revenue gravity sits with chemical processing; pharmaceuticals climb the fastest.
End User:
End user categories separate volume buyers with internal engineering capabilities from specification-driven purchasers outsourcing integration complexity.
- Manufacturers:Electronics and automotive component fabricators operate captive gas distribution networks with dedicated maintenance teams. Taiwan-based semiconductor foundries represent the most demanding subset, specifying predictive diagnostics and remote purity verification that alter supplier contracting models.
- Research Institutions:National laboratories and university facilities purchase specialized configurations for experimental apparatus. NIH and DOE funding cycles in US facilities create lumpy procurement patterns with extended qualification requirements.
- Energy Producers:Utility-scale hydrogen and natural gas operators deploy field-erected systems with long replacement cycles.
- Hospitals:Medical gas pipeline systems serve anesthesia and respiratory therapy with life-safety redundancy requirements.
Installed base concentrates among manufacturers; research institutions expand most quickly.
Technology:
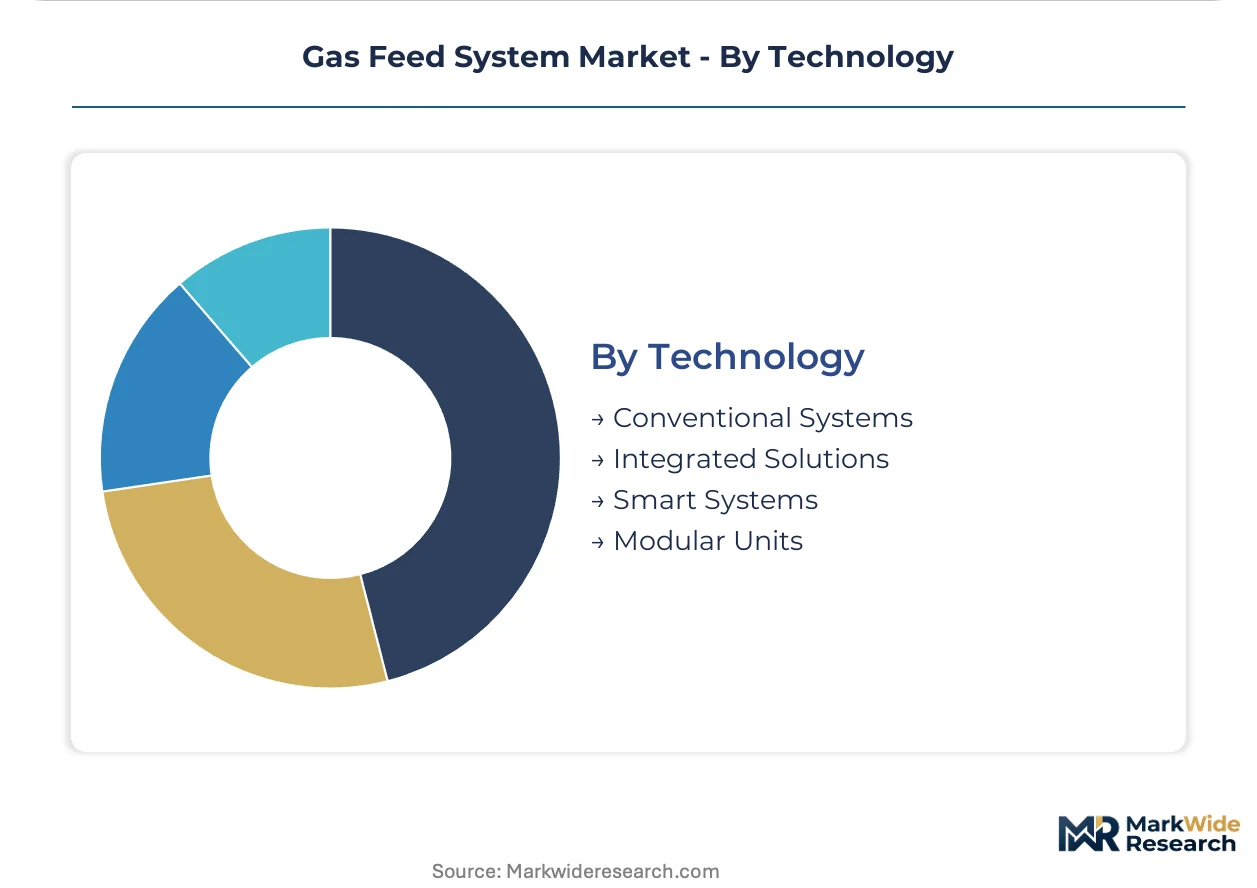
Technology segments track the migration from site-built assemblies toward pre-engineered packages with embedded intelligence.
- Smart Systems:Sensor-integrated architectures transmit pressure, flow, and purity data to centralized monitoring platforms. South Korean fab operators deploy machine learning models on these data streams to forecast filter degradation, compressing unplanned downtime from days to hours and shifting supplier relationships toward performance-guaranteed service contracts.
- Modular Units:Factory-built skids integrate purification, mixing, and control functions for rapid site installation. Saudi green hydrogen projects at NEOM specify these for electrolysis feed conditioning, constrained by welding technician scarcity that limits fabrication scaling.
- Conventional Systems:Field-assembled regulators, manifolds, and piping dominate mature chemical plant retrofits.
- Integrated Solutions:Turnkey packages bundle hardware with validation documentation for regulated industries.
Shipments concentrate in conventional systems; modular units gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hwaseong's Samsung semiconductor complex drives South Korean demand for sub-ppb purity gas distribution, while EPA enforcement and China's hydrogen strategy reshape procurement patterns across three continents.
United States
Chemical processors along the Gulf Coast upgrade leak detection infrastructure under tightening EPA Clean Air Act mandates for fluorinated process gases. OSHA process safety management standards govern containment protocols at Houston-area petrochemical clusters. Texas and Louisiana facilities concentrate replacement demand for recovery-integrated architectures.
Germany
Ruhr Valley chemical corridors face compressed project windows from EU F-Gas Regulation phase-down timelines for fluorinated greenhouse gases. EMA audit readiness requirements extend validation timelines for pharmaceutical gas systems at Ludwigshafen and Leverkusen manufacturing hubs. BASF and Bayer facilities drive demand for sealed recovery manifolds replacing vented configurations.
China
Coastal petrochemical complexes at Ningbo and Dalian expand capacity under MIIT industrial policy directives promoting import substitution. GB standards shape domestic procurement specifications for hydrogen fueling infrastructure along the Yangtze River Delta. National hydrogen strategies redirect capital toward high-pressure gas feed networks for mobility applications.
Saudi Arabia
NEOM green hydrogen development requires integrated gas feed and compression skids for electrolysis and ammonia synthesis at the northwestern megaproject site. The country's national industrial regulator mandates closed-loop handling systems for carbon-intensive processes. Red Sea coastal zones concentrate fabrication demand for modular skid-mounted packages.
South Korea
Semiconductor fabs in Pyeongtaek and Yongin specify predictive diagnostics and remote purity verification that alter supplier contracting models. MFDS pharmaceutical manufacturing standards drive electropolished surface requirements for sterile gas delivery. Seoul Capital Area facilities represent the most demanding subset for machine learning-enabled contamination prediction.
Gas Feed System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor landscape where cryogenic engineering heritage separates premium positioning from commodity fabrication. The market consolidates around three strategic archetypes: integrated gas majors leveraging vertical supply chains, regional specialists optimizing production density, and ultra-high-purity technicians serving semiconductor protocols. Dominant competitive moves include capacity expansion in hydrogen infrastructure corridors and technology licensing partnerships for predictive diagnostics platforms.
Within the integrated gas major tier, Linde plc and Messer Group GmbH exemplify divergent geographic anchoring strategies, with the former representing Anglo-German cryogenic engineering consolidation and the latter occupying a position in Central European chemical corridor density. Matheson Tri-Gas, Inc. sits within the ultra-high-purity specialist archetype, its technical differentiation sustained against price-driven competitors through semiconductor-grade certification depth.
| Leading Market Players |
|---|
| Linde plc |
| Messer Group GmbH |
| Matheson Tri-Gas, Inc. |
| Iwatani Corporation |
| Taiyo Nippon Sanso Corporation |
| SIAD Group |
| Airgas, Inc. |
| Universal Industrial Gases, Inc. |
| Evoqua Water Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
Backward integration into electropolished stainless steel fabrication anchors pricing power for Linde plc and Messer Group GmbH, while outsourced component sourcing exposes mid-tier suppliers to nickel alloy volatility from Chinese and Indian foundries. This integration choice separates premium gas feed system vendors commanding sub-ppb certification premiums from commodity fabricators competing on standard industrial specifications.
Pricing Analysis
Uptime-guaranteed service contracts anchor value-based pricing for semiconductor-grade gas feed systems, with Taiwan and South Korean fabs paying premiums for predictive diagnostics that compress unplanned downtime. Three-tier pricing structure across premium, standard, and economy levels stratifies by SEMI certification depth, with pharmaceutical manufacturers least price-sensitive due to FDA validation costs dwarfing hardware expenditure. Cost compression in standard industrial tiers intensifies because Chinese petrochemical buyers prioritize volume scale over surface finish protocols.
Supply Chain Analysis
Refurbishment flows for cryogenic storage vessels and regulator networks extend asset lifecycles in mature chemical processing installations, creating secondary parts markets alongside primary equipment procurement. Specialty 316L stainless steel sourcing concentrates in Chinese and Indian foundries, with electropolished surface finishing equipment clustering in Germany and Japan. Single-source vulnerability for orbital welding certification limits production scaling for modular skid manufacturers. Distribution runs through integrated gas majors' captive service networks for premium tiers, while independent distributors serve standard industrial replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital welding technician scarcity props pricing for electropolished gas feed systems, constraining supply expansion despite semiconductor fab demand acceleration. This capacity bottleneck sustains margin premiums for certified fabricators against price-pressured commodity competitors.
For Market Incumbents: Lock in semiconductor foundry relationships through predictive diagnostics bundling, defending against emerging AI-driven contamination prediction specialists. Prioritize backward integration into electropolished stainless steel fabrication to secure raw material access against Chinese foundry volatility. Expand orbital welding training pipelines in South Korea and Taiwan to relieve production scaling constraints. For New Entrants and Emerging Players: Modular skid-mounted system pre-integration offers entry into Saudi green hydrogen and German hydrogen fueling infrastructure where welding certification scarcity blocks incumbent capacity expansion. Target pharmaceutical third-party validation services in North America, where FDA audit readiness requirements fragment vendor relationships. Pursue technology licensing partnerships with Taiwanese machine learning platforms for remote purity verification capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated gas majors seeking semiconductor-grade certification depth. Five-to-ten year viability favors ultra-high-purity specialists with SEMI standards compliance infrastructure over commodity fabricators facing Chinese import substitution. Monitor EPA Clean Air Act enforcement intensity for fluorinated process gases as inflection indicator for US chemical processor replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Platform Development | Machine learning-enabled contamination forecasting rewrites service contract economics for Taiwan semiconductor fabs. |
| Orbital Welding Certification Expansion | Training pipeline investments in South Korea relieve technician scarcity constraining modular skid fabrication scaling. |
| Electropolished Surface Finishing Integration | Backward integration into 316L stainless steel processing secures sub-ppb contamination control against Chinese foundry volatility. |
| EU F-Gas Regulation Compliance Bundling | Reclamation module integration captures German chemical processor upgrade cycles driven by fluorinated gas phase-down timelines. |
| Green Hydrogen Infrastructure Partnerships | NEOM and Saudi coastal project alliances establish foothold in electrolysis feed conditioning for ammonia synthesis. |
Research Methodology
Independent corroboration across plant engineers at semiconductor fabrication facilities, procurement leads at petrochemical complexes, and aftermarket service heads at integrated gas majors underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and technical R&D directors at specialty gas suppliers combined with secondary validation from SEC 10-K filings, customs and trade data, and ACC industry reports. Bottom-up demand modeling across application segments triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition across the analysis window segments growth by product architecture, purity grade tier, end-use industry, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, greenfield capacity addition pipelines, and technology substitution curves for smart system penetration. Forecast inputs incorporate SEMI standards evolution timelines, EPA enforcement intensity trajectories, and national hydrogen strategy capital commitment announcements without year-specific anchoring.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Chinese stainless steel sourcing, breakthrough contamination control technologies obsoleting electropolished surface protocols, and pandemic-scale disruptions to semiconductor fab construction schedules. Practitioners should monitor EPA Clean Air Act settlement patterns, EU F-Gas Regulation phase-down acceleration proposals, and South Korean fab equipment import licensing delays for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
South Africa Bunker Fuel Market
Fuels
Emulsified Fuel Market
Fuels
Industrial Fuel Filter Market
Fuels
Diesel As Fuel Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Diesel Fuel Market
Fuels
Global Chemical Logistics Market
Fuels
Italy Chemical Logistics Market
Fuels
United States Bunker Fuel Market
Fuels
White Coal Market
Fuels
South Korea LNG Bunkering Market
Fuels
Multifuel Gas Turbine Market
Fuels
India Retail Fuel Market
Fuels
UAE Chemical Logistics Market
Fuels
Bituminous Coal Market
Fuels
Global Steam Coal Market