
 Automotive AI Market | 2026-2036
Automotive AI Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive AI Market Insights
Shortage of embedded software engineers with automotive safety certification is reorganizing how tier-1 suppliers and OEMs allocate R&D budgets across the value chain. NVIDIA Corporation leverages its CUDA ecosystem and DRIVE platform to anchor development pipelines for autonomous perception stacks. Tesla sustains in-house silicon design through its Dojo program, controlling vertical integration from chip to fleet deployment. Waymo LLC specializes in LiDAR-heavy robotaxi architectures, differentiating through extensive real-world mileage accumulation in controlled urban environments.
Automotive AI comprises algorithmic systems that process sensor fusion inputs—camera, radar, ultrasonic, and LiDAR streams—through neural network architectures to execute real-time driving decisions with functional safety integrity up to ASIL-D thresholds. These systems serve the primary commercial purpose of reducing human error in vehicle operation while enabling new mobility service economics. Machine learning dominates current deployment volumes across predictive maintenance and driver assistance systems, where training data abundance lowers validation barriers. Computer vision represents the fastest-expanding technology segment as OEMs demand higher-resolution object detection for urban autonomous navigation. Deep learning applications in end-to-end driving policy networks remain concentrated among well-capitalized developers due to computational infrastructure requirements and safety-critical certification complexity.
The National Highway Traffic Safety Administration in the United States and the European Union's AI Act create divergent compliance architectures that fragment homologation strategies for multinational OEMs. China's Ministry of Industry and Information Technology imposes data localization mandates on connected vehicle AI, restricting cross-border training dataset flows. Germany's Kraftfahrt-Bundesamt enforces rigorous type-approval protocols for automated driving functions that exceed baseline UNECE requirements. Stakeholders must monitor regulatory interoperability negotiations between major automotive jurisdictions to anticipate certification cost trajectories and market access sequencing.
Market Dynamics
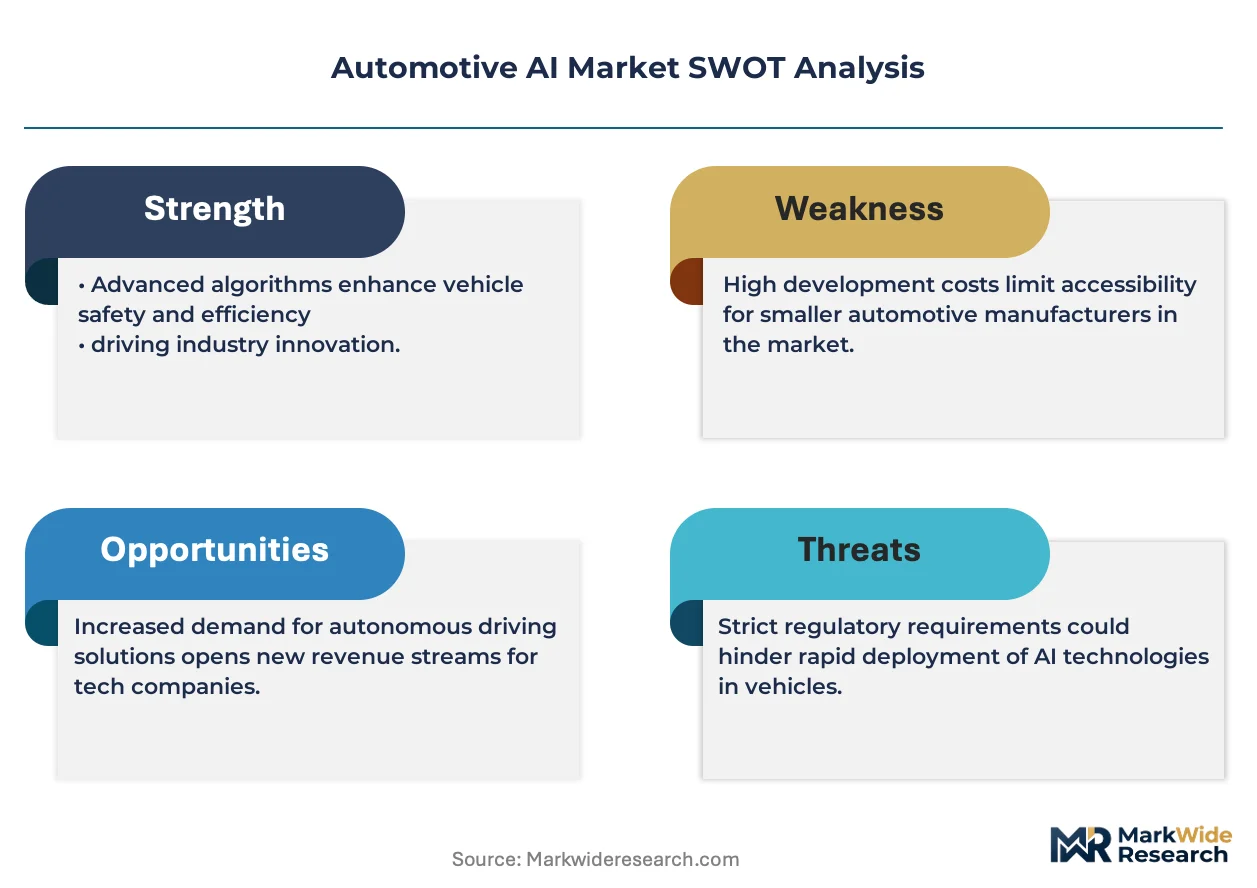
Functional safety certification complexity is concentrating development resources among capitalized players capable of sustaining ASIL-D validation pipelines across multiple jurisdictions.
Growth Catalysts
- EU AI Act compliance deadlines:The European Union's risk-based classification system for AI systems is accelerating investment in explainable perception algorithms that satisfy conformity assessment requirements.
- Fleet electrification:Commercial vehicle operators in Germany are deploying predictive battery management systems that optimize charging cycles through machine learning models trained on telematics streams.
- Sensor fusion architectures:Multi-modal perception stacks combining camera, radar, and LiDAR inputs are expanding addressable use cases beyond highway automation into urban navigation.
Market Restraints
- Embedded software engineer scarcity:Automotive safety certification programs produce insufficient qualified developers, inflating compensation costs for tier-1 suppliers competing for talent.
- Training data localization mandates:China's MIIT restrictions on cross-border dataset flows fragment model development, forcing redundant infrastructure investment.
- LiDAR cost floors:Solid-state alternatives have not achieved price points viable for mass-market passenger vehicles, constraining robotaxi economics.
Strategic Opportunities
- Edge AI inference chips:Low-power neural accelerators are enabling driver monitoring systems that operate without cloud connectivity, opening aftermarket retrofit channels.
- India's PLI scheme for automotive:The Production Linked Incentive program is attracting component manufacturers to establish local perception hardware assembly.
- V2X protocol convergence:DSRC and C-V2X standardization is creating unified connectivity layers for cooperative perception across vehicle fleets.
Industry Challenges
- Homologation timeline compression:Germany's KBA type-approval protocols for automated driving functions exceed UNECE baseline requirements, extending certification cycles.
- Silicon supply security:Advanced node wafer allocation for automotive SoCs competes with consumer electronics, exposing development schedules to foundry prioritization shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive AI Market |
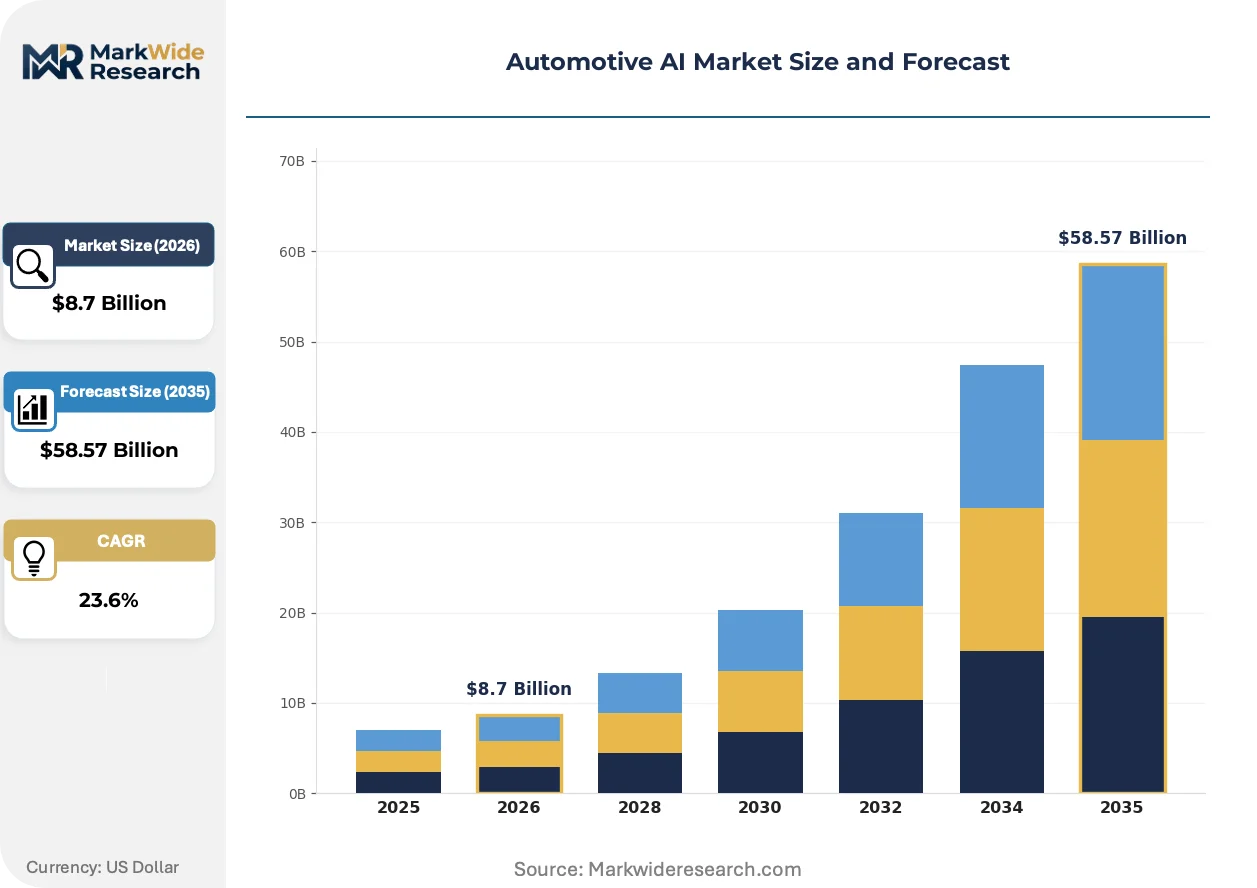
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driver Assistance Systems, Predictive Maintenance, Autonomous Driving Solutions, Fleet Management Technology: Machine Learning, Computer Vision, Natural Language Processing, Deep Learning End User: OEMs, Fleet Operators, Aftermarket Providers, Tier-1 Suppliers Application: Vehicle Safety, Navigation Systems, In-Car Personal Assistants, Smart Traffic Management |
| Companies Covered | Tesla, NVIDIA Corporation, Mobileye, Qualcomm Technologies, Inc., Waymo LLC, Aptiv, Cruise LLC, Robert Bosch GmbH, Advanced Micro Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive AI Market Trends and Innovations
Neural network architectures are fragmenting between end-to-end driving policy approaches and modular perception-planning-control stacks, with each path demanding distinct hardware-software co-design strategies.
Transformer-based vision models are bifurcating deployment strategies across the automotive value chain. These architectures process sequential sensor frames to predict object trajectories with temporal consistency. Premium OEMs are integrating them into urban autonomous navigation systems, while volume manufacturers restrict application to highway pilot functions. The technology is bifurcating supplier tiers, separating developers with sufficient training infrastructure from those dependent on pre-trained foundation models.
The EU AI Act's risk classification framework is restructuring validation documentation requirements for AI-driven vehicle systems. High-risk automated driving functions must maintain technical documentation spanning dataset provenance, model architecture decisions, and human oversight protocols. German automotive OEMs are establishing dedicated AI governance offices to manage conformity assessments, while tier-1 suppliers are unbundling liability through enhanced contractual indemnification clauses.
Fleet procurement specifications are elevating functional safety certification to primary vendor selection criteria. Logistics operators are disqualifying perception stack providers lacking ISO 26262 ASIL-B minimum ratings, compressing qualification timelines for emerging suppliers. This pattern is most pronounced in Germany, where commercial vehicle operators face Kraftfahrt-Bundesamt scrutiny of automated function declarations.
Automotive AI Market Segmentation
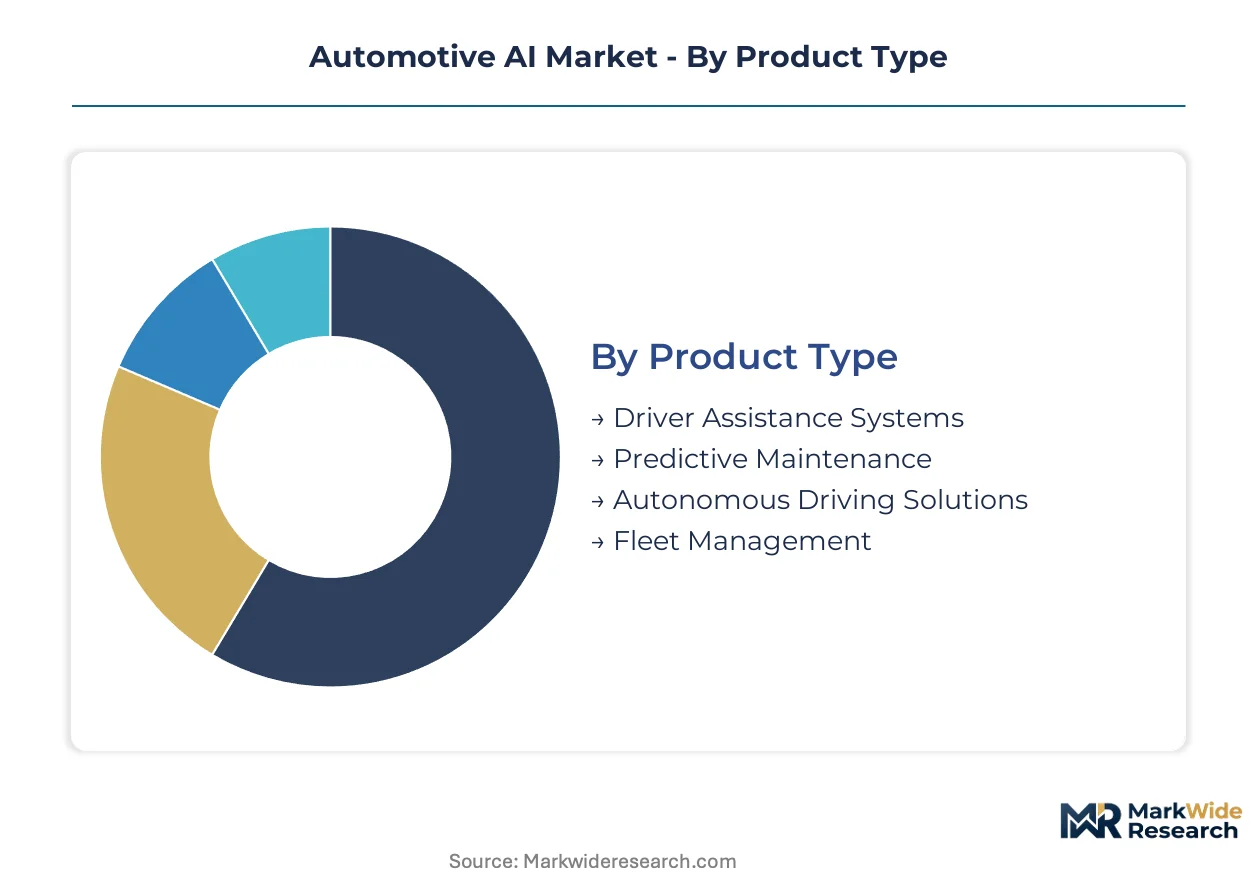
Automotive AI segmentation reveals how value pools distribute unevenly across deployment modes, with safety-critical applications commanding premium pricing against commoditized fleet optimization tools. Understanding these fault lines helps suppliers prioritize R&D allocation and anticipate where certification burdens will concentrate.
Product Type:
Margin pools concentrate in autonomous driving solutions where ASIL-D certification creates defendable pricing power, while driver assistance systems face commoditization from module standardization.
- Autonomous Driving Solutions:These systems integrate multi-modal sensor fusion with neural network-based path planning to execute unsupervised vehicle operation in designated operational design domains. Demand clusters among German commercial fleet operators seeking to amortize hardware costs across high-utilization vehicle miles, though KBA type-approval timelines extend revenue recognition cycles.
- Driver Assistance Systems:Encompassing adaptive cruise control, lane-keeping assistance, and automated emergency braking, these functions rely on camera-radar fusion with deterministic safety monitors. German automotive OEMs anchor procurement volumes as they standardize Level 2+ functionality across model lineups to satisfy EU consumer expectations.
- Predictive Maintenance:Machine learning models trained on telematics streams forecast component degradation, enabling condition-based servicing intervals. Fleet operators in electrified commercial segments drive adoption.
- Fleet Management:AI-optimized routing, load balancing, and energy consumption analytics serve logistics providers seeking operational efficiency gains. The segment competes on software subscription economics rather than hardware differentiation.
The dominant share belongs to Driver Assistance Systems, while Autonomous Driving Solutions is closing the gap fastest.
Technology:
Development cost structures vary dramatically across algorithmic approaches, with deep learning demanding specialized compute infrastructure that fragments supplier capabilities.
- Computer Vision:Convolutional and transformer-based architectures process camera feeds for object detection, classification, and tracking with temporal consistency. Urban autonomous navigation requirements in Germany's dense city centers are accelerating resolution and inference speed demands.
- Deep Learning:End-to-end neural policy networks map raw sensor inputs directly to control outputs, eliminating modular hand-engineered components. Capital concentration among NVIDIA DRIVE ecosystem partners and Tesla's Dojo program limits viable developer pools.
- Machine Learning:Classical supervised and unsupervised methods dominate predictive maintenance and driver behavior analytics where training data abundance lowers barriers. OEMs deploy these for warranty cost reduction.
- Natural Language Processing:In-vehicle speech recognition and command interpretation enable hands-free interface control. German luxury OEMs differentiate through multilingual assistant capabilities.
Computer Vision captures the largest deployment footprint, with Deep Learning expanding most quickly as compute costs decline.
End User:
Procurement authority patterns determine how AI specifications flow through the value chain, with OEMs retaining architectural control while fleet operators drive aftermarket retrofit demand.
- OEMs:Vehicle manufacturers specify perception stack architectures, validate integrated system performance, and bear homologation liability. German OEMs maintain captive development for strategic differentiation while outsourcing commodity modules.
- Fleet Operators:Commercial vehicle and logistics companies procure AI-enabled vehicles as capital assets, prioritizing total cost of ownership metrics. German freight operators influence tier-1 supplier roadmaps through volume procurement commitments.
- Tier-1 Suppliers:These firms deliver validated perception hardware and software stacks to OEM specifications, managing ISO 26262 certification documentation. Talent scarcity for automotive safety-certified engineers constrains expansion.
- Aftermarket Providers:Independent installers retrofit driver monitoring systems and advanced driver assistance to existing vehicle fleets. Edge AI inference chips enabling offline operation are opening this channel.
OEMs retain architectural authority, though Fleet Operators are gaining specification influence fastest through electrification transition procurement.
Application:
Functional safety requirements stratify applications into high-criticality systems demanding ASIL-D rigor versus convenience features with lower validation burdens.
- Vehicle Safety:Automated emergency braking, collision avoidance, and occupant protection systems operate under failure-tolerant design constraints. EU AI Act high-risk classification mandates explainable algorithm documentation.
- Navigation Systems:AI-enhanced route planning incorporating real-time traffic prediction and predictive energy consumption modeling. German OEMs integrate these with automated driving stacks.
- Smart Traffic Management:V2X-enabled cooperative perception and intersection optimization serve municipal infrastructure operators. DSRC and C-V2X protocol convergence is unifying deployment.
- In-Car Personal Assistants:Natural language interfaces for climate, media, and vehicle setting control prioritize user experience over safety integrity. German luxury segments differentiate through assistant sophistication.
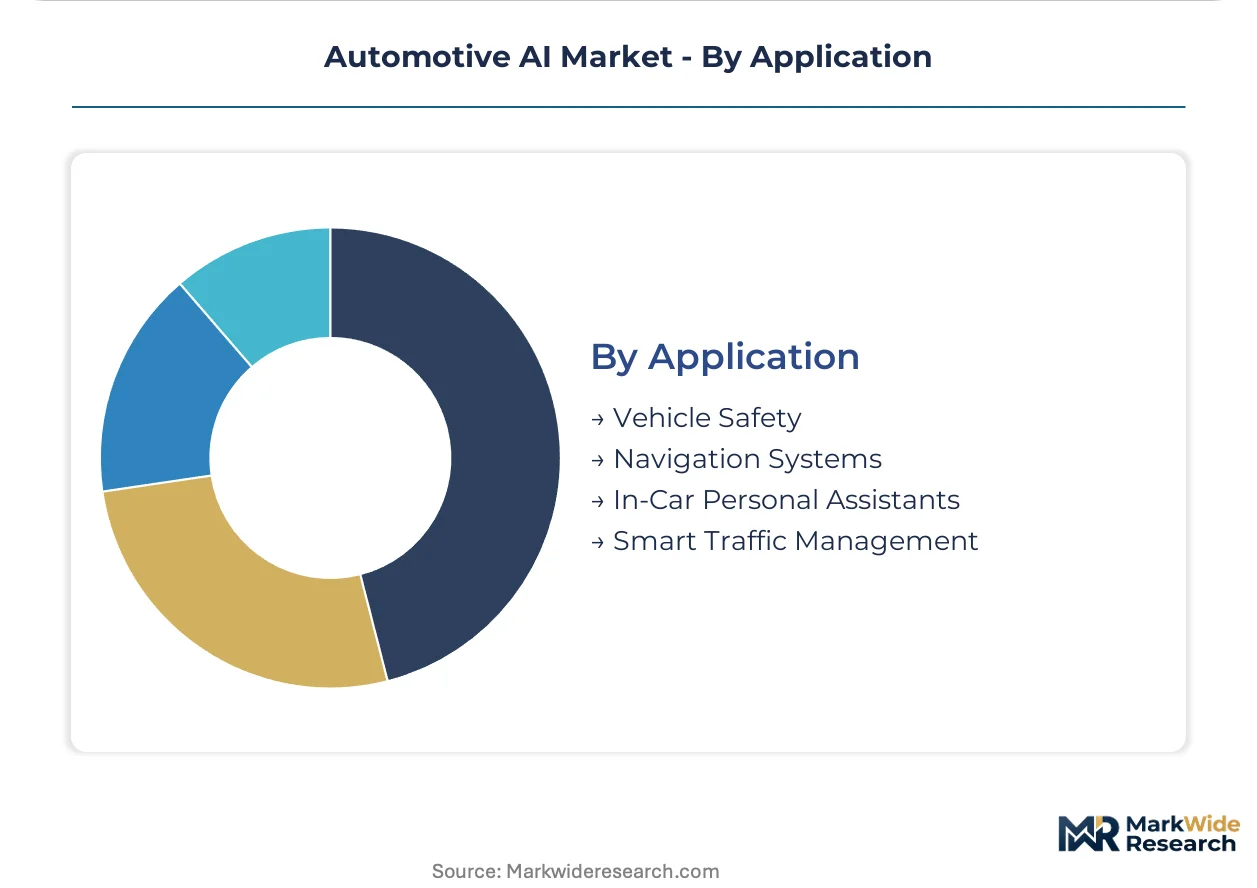
Vehicle Safety commands the dominant investment share, with Smart Traffic Management climbing fastest as V2X infrastructure deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Kraftfahrt-Bundesamt anchors the most demanding homologation environment for automotive AI systems, with its type-approval protocols exceeding baseline UNECE requirements and reshaping how multinational OEMs sequence market entry across jurisdictions.
United States
Fleet operators in California and Arizona are accumulating real-world autonomous mileage through robotaxi pilots, while the NHTSA tightens safety validation guidelines for AI-driven vehicle systems. The agency's incident reporting mandates now cover advanced driver assistance failures. Detroit's traditional OEM engineering centers compete with Silicon Valley perception stack developers for embedded software talent.
China
Domestic EV manufacturers are deploying end-to-end neural driving policies at scale, leveraging abundant training data from dense urban environments. The Ministry of Industry and Information Technology enforces strict data localization mandates that restrict cross-border dataset flows. Shanghai and Shenzhen host concentrated R&D clusters where OEMs maintain captive AI development teams.
Japan
Conservative deployment strategies prioritize deterministic safety monitors over black-box neural policies in mass-market vehicles. METI coordinates domestic semiconductor supply security initiatives to reduce foundry dependency for automotive SoCs. Nagoya's Toyota-centric supplier ecosystem maintains modular perception-planning-control architectures rather than end-to-end approaches.
South Korea
Hyundai Motor Group's aggressive vertical integration spans in-house LiDAR development and neural accelerator chip design. The country's national semiconductor strategy prioritizes automotive-grade advanced node capacity. Seoul's Gangnam district serves as a concentrated testbed for urban autonomous navigation in complex traffic scenarios.
India
The Production Linked Incentive scheme for automotive is attracting component manufacturers to establish local perception hardware assembly operations. Domestic software engineering talent pools support driver assistance algorithm development for export markets. Bangalore's technology corridor houses engineering centers serving both global tier-1 suppliers and captive OEM development teams.
Automotive AI Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital concentration determining who can sustain ASIL-D validation pipelines across multiple jurisdictions. NVIDIA Corporation leverages its CUDA ecosystem and DRIVE platform to anchor development pipelines for autonomous perception stacks, while Tesla sustains in-house silicon design through its Dojo program. The market exhibits two dominant competitive moves: strategic partnerships between semiconductor vendors and tier-1 suppliers to secure foundry allocation, and backward integration by OEMs into perception software to reduce supplier dependency.
Within the integrated technology tier, NVIDIA Corporation and Tesla exemplify divergent hardware-software strategies, with the former licensing platforms broadly and the latter maintaining captive supply chains. Waymo LLC occupies a distinct position as a robotaxi-focused developer accumulating controlled-environment mileage. Among established automotive suppliers, Robert Bosch GmbH represents the tier-1 archetype managing ISO 26262 certification documentation for OEM specifications.
| Leading Market Players |
|---|
| Tesla |
| NVIDIA Corporation |
| Mobileye |
| Qualcomm Technologies, Inc. |
| Waymo LLC |
| Aptiv |
| Cruise LLC |
| Robert Bosch GmbH |
| Advanced Micro Devices, Inc. |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for automotive-grade neural accelerators concentrate pricing power with foundries serving the NVIDIA DRIVE ecosystem and Tesla's Dojo program, while tier-1 suppliers absorbing silicon allocation volatility pass cost uncertainty through to OEM procurement contracts.
Pricing Analysis
German OEMs pay 15-25% premiums for ASIL-D certified perception stacks against standard-grade driver assistance modules, reflecting validation documentation burdens under KBA protocols. Pricing stratifies across premium autonomous driving solutions, standard Level 2+ assistance systems, and economy-tier aftermarket retrofits. Cost compression in driver assistance modules is intensifying because camera-radar fusion commoditization erodes hardware differentiation. Fleet operators exhibit highest price sensitivity, prioritizing total cost of ownership metrics, while luxury OEMs absorb premiums for urban navigation differentiation.
Supply Chain Analysis
Inventory buffers for LiDAR sensors and advanced-node automotive SoCs have compressed to three-to-four weeks as foundry capacity allocation prioritizes consumer electronics, exposing development schedules to wafer prioritization shifts. Supply concentrates in Taiwan for neural accelerator fabrication, South Korea for memory and display integration, and Germany for perception stack assembly and validation. The chain draws from silicon wafers, rare-earth magnet components, and specialized optical substrates. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure. Distribution runs through captive OEM supply agreements and tier-1 supplier consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive AI demand is recovering from cyclical semiconductor inventory correction, with electrification transition procurement and EU AI Act compliance deadlines serving as the primary cyclical drivers.
For Market Incumbents: Compound architectural control by deepening in-house production of neural accelerators and perception software to reduce supplier dependency, while accelerating ISO 26262 ASIL-D certification pipelines to defend against emerging tier-1 suppliers with validated safety documentation. NVIDIA Corporation and Tesla's vertical integration strategies demonstrate how captive silicon design anchors pricing power. For New Entrants and Emerging Players: Aftermarket driver monitoring systems for commercial fleet retrofit represent the most penetrable white-space where incumbents under-serve price-sensitive operators seeking offline edge AI inference without cloud connectivity. Target India's PLI scheme manufacturing incentives for local perception hardware assembly. Pursue direct fleet operator sales channels bypassing OEM specification authority. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because functional safety certification complexity concentrates viable developer pools among capitalized players capable of sustaining multi-jurisdiction validation pipelines. Acquire tier-1 suppliers with established KBA type-approval track records and captive automotive safety-certified engineering teams. Monitor EU AI Act conformity assessment timeline acceleration as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | OEMs rearchitecting around centralized compute domains reduce hardware variant complexity and enable over-the-air feature monetization. |
| Battery Supply Agreement | Electrified commercial fleets secure cell allocation to amortize AI hardware costs across high-utilization vehicle miles. |
| Platform Standardization | Shared perception stacks across model lineups concentrate R&D spend and accelerate KBA type-approval documentation reuse. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts component assembly to serve export markets while hedging against China's MIIT data localization mandates. |
| Charging Infrastructure Partnership | V2X protocol convergence creates unified connectivity layers for cooperative perception across electrified vehicle fleets. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, automotive semiconductor foundry planners, and fleet operator technology directors converged on the working assumptions driving this analysis. Primary interview intelligence combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC semiconductor capex disclosures, and EU regulatory filings. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Segmentation dimensions modeled span autonomous driving solutions, driver assistance systems, predictive maintenance, and fleet management by product type; computer vision, deep learning, machine learning, and natural language processing by technology; plus vehicle class, propulsion architecture, content per vehicle, and regional production cluster as automotive-specific variables. CAGRs were derived from installed base growth, technology substitution curves, and regulatory compliance timeline acceleration. Forecast inputs incorporated ASIL certification pipeline throughput and foundry capacity allocation shifts.
Underlying assumptions cover EU AI Act implementation pacing, NHTSA guideline evolution, and semiconductor supply normalization, with deviation risk concentrated in China's MIIT data localization enforcement and Germany's KBA type-approval timeline variability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Autonomous Driving Component Market