
 Self-Driving Bus Market | 2026-2036
Self-Driving Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Bus Market Analysis
Modular sensor-suite bundling is expanding buyer choice as transit agencies mix LiDAR, radar, and computer vision components to match route complexity and budget constraints. Waymo leverages its mapping data infrastructure to anchor long-term fleet contracts. WeRide competes through all-weather sensor fusion stacks optimized for dense Asian urban corridors. Pony.ai specializes in regulatory-first deployment strategies that prioritize closed-loop validation before open-road expansion.
A self-driving bus is a ground vehicle operating without human driver intervention, utilizing LiDAR point-cloud mapping, radar obstacle detection, and neural-network-based computer vision to navigate predefined or dynamic routes with passenger capacity exceeding eight seats. Its primary commercial purpose is to reduce per-kilometer operating costs while extending transit service hours in labor-constrained markets. Sensor fusion dominates hardware configuration decisions because single-modality systems fail under adverse weather, while shuttle bus and mini bus vehicle types attract the densest pilot investment due to lower speed requirements and controlled operational envelopes. Fixed route deployment models currently occupy the most mature margin pool, though on-demand service architectures are capturing disproportionate R&D allocation from private operators seeking to replicate ride-hail economics at higher vehicle density.
NHTSA in the United States, the EU's type-approval framework under UNECE R157 extensions, and China's MIIT connected-vehicle standards collectively determine where autonomous buses gain commercial operating permits. These regulators shape demand by mandating specific fallback-driver protocols, cybersecurity architectures, and geofencing validation thresholds that vendors must embed before revenue service. Stakeholders must monitor which jurisdiction first relaxes attendant-vehicle requirements for low-speed shuttle corridors, as that shift will redirect capital deployment and pilot program geography.
Market Dynamics
Transit authorities are compressing operator headcount through sensor fusion architectures that eliminate attendant-vehicle mandates in low-speed corridors. This labor substitution dynamic is redirecting capital from traditional fleet renewal toward autonomous shuttle procurement.
Growth Catalysts
- NHTSA attendant-relaxation pilots:US municipal transit agencies in Arizona and Texas are expanding revenue service without human safety drivers. This regulatory latitude accelerates procurement cycles for closed-campus deployments.
- LiDAR cost deflation:Solid-state sensor manufacturing scale is collapsing per-unit hardware expenses. Transit operators previously priced out of multi-modality stacks can now specify redundant perception layers.
- Singapore's Punggol Digital District:The city-state's dedicated autonomous vehicle zone is validating geofenced shuttle networks at scale. Successful pilots are establishing template procurement specifications across Southeast Asian smart city programs.
Market Restraints
- LiDAR supply concentration:High-performance sensor fabrication concentrates among three specialist manufacturers. Transit OEMs face allocation risk when scaling beyond pilot volumes.
- UNECE R157 geofencing thresholds:European type-approval mandates restrict autonomous bus operation to pre-mapped corridors. This technical limitation prevents dynamic route expansion and on-demand service architectures.
- Fallback-driver training costs:Jurisdictions retaining attendant-vehicle protocols impose specialized certification requirements. These labor obligations preserve operating cost structures that automation was designed to eliminate.
Strategic Opportunities
- India's smart city mission:The country's urban renewal program is funding last-mile connectivity pilots. Autonomous shuttle corridors at educational campuses and industrial parks are attracting technology transfer partnerships.
- V2X infrastructure convergence:Integration of vehicle-to-everything communication with 5G edge computing is enabling predictive traffic negotiation. This technology pairing supports higher-speed autonomous bus operation on open roads.
- EU Green Deal procurement mandates:Public transit fleet renewal rules are prioritizing zero-emission autonomous vehicles. Electric drivetrain-shuttle combinations qualify for accelerated tender processes.
Industry Challenges
- Sensor fusion engineering scarcity:Transit system integrators cannot source sufficient perception-stack specialists. Compensation premiums for LiDAR-radar-computer vision integration talent are compressing project margins.
- ISO 26262 functional safety certification:Autonomous bus platforms require ASIL-D validation for public road deployment. Documentation and testing timelines extend 18-24 months beyond prototype completion.
- Legacy transit management system integration:Existing fleet dispatch and passenger information architectures lack API compatibility. Middleware development for real-time autonomous vehicle coordination imposes unbudgeted integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Bus Market |
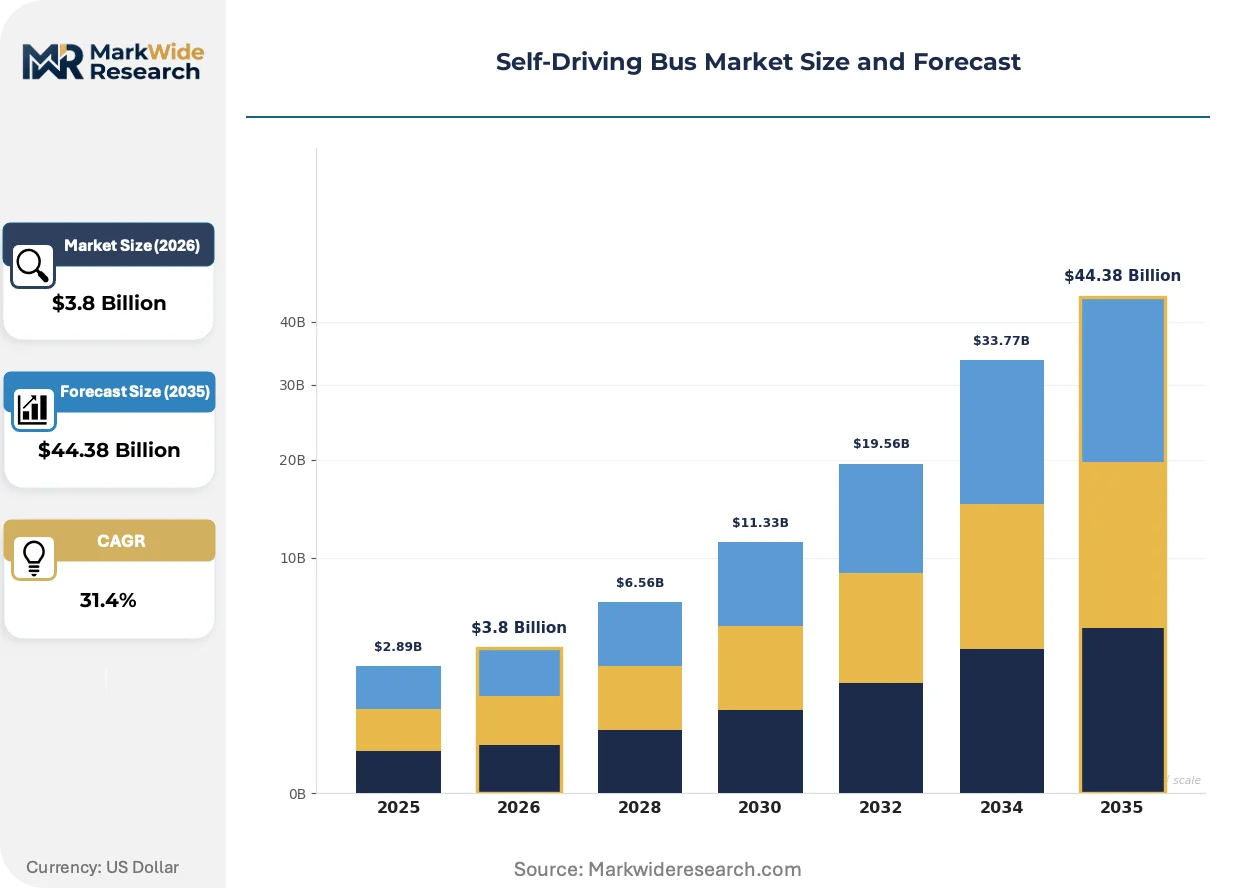
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Computer Vision, Sensor Fusion Vehicle Type: Shuttle Bus, Transit Bus, Coach, Mini Bus End User: Public Transit Authorities, Private Operators, Universities, Corporations Deployment Model: On-Demand Service, Fixed Route, Shuttle Service, Pilot Programs |
| Companies Covered | Zoox, GetUgo, Waymo, EVIE Autonomous, Mozee, WeRide, Avride, Nuro, Pony.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Bus Market Emerging Trajectories
Edge computing migration is relocating perception processing from vehicle-mounted hardware to roadside infrastructure. This architectural shift is collapsing onboard compute costs while introducing new dependency relationships between transit agencies and telecommunications providers.
Solid-state LiDAR is absorbing the obstacle-detection function previously distributed across mechanical scanning units. Tier-1 automotive suppliers are integrating these compact sensors into standardized front-module assemblies. Transit fleet operators are specifying solid-state configurations for reduced maintenance intervals and improved all-weather reliability.
China's MIIT connected-vehicle standards are mandating cybersecurity architectures for autonomous bus type-approval. Domestic manufacturers must embed intrusion detection and over-the-air update capabilities before commercial deployment. This regulatory pressure is accelerating supplier consolidation around integrated telematics platforms.
Performance-based service contracting is displacing traditional capital procurement for autonomous shuttle networks. Municipal buyers are transferring operational risk to vendors through per-passenger-mile pricing structures. Germany's regional transit authorities are piloting these arrangements for airport-campus connector services.
Self-Driving Bus Market Segmentation
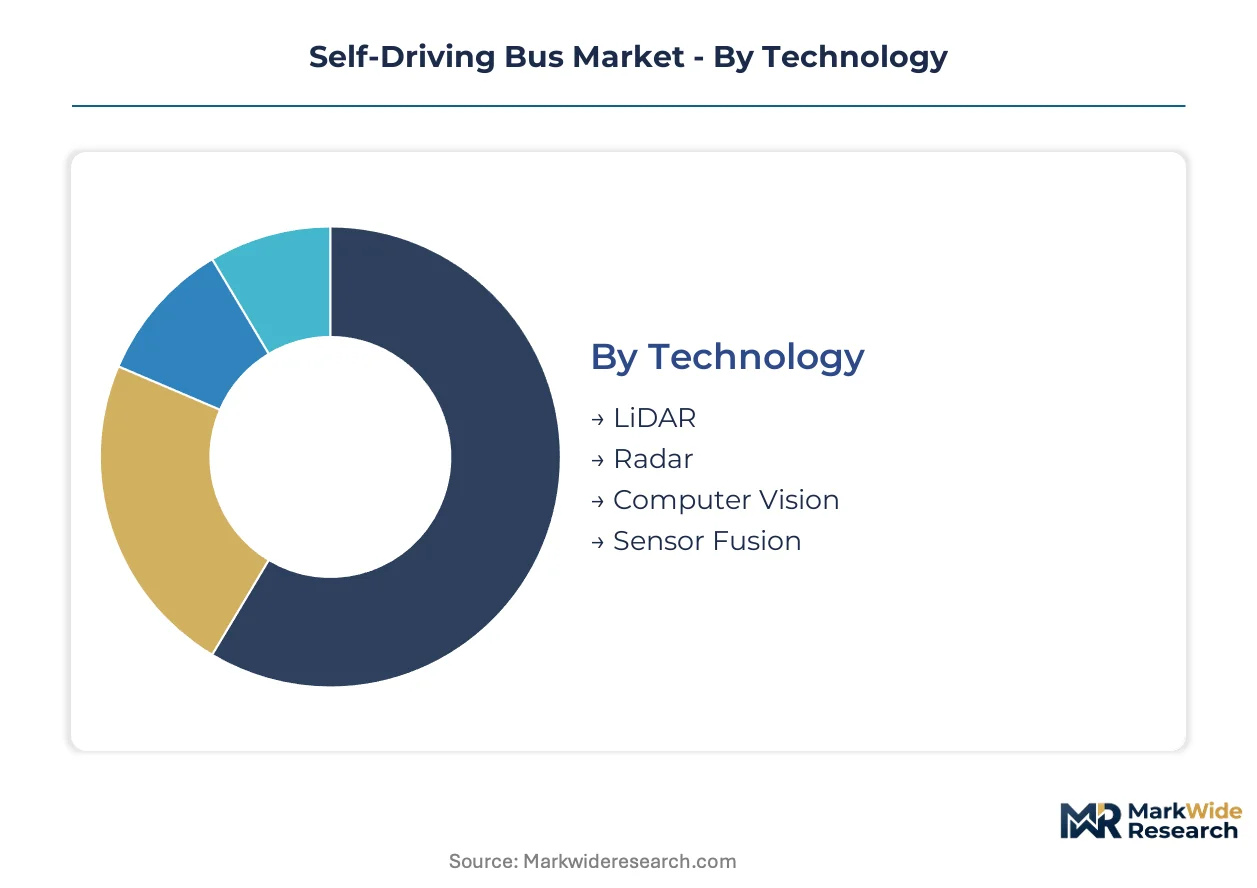
Technology choices in autonomous buses determine regulatory approval pathways and operating cost structures. Procurement specifications diver sharply between closed-campus deployments and open-road transit corridors.
Technology:
Sensor supply concentrates among three specialist manufacturers, creating allocation bottlenecks for fleet-scale deployments.
- LiDAR:Solid-state units emit pulsed laser beams to generate 3D point-cloud maps of surrounding terrain. Singapore's Punggol Digital District and Germany's regional transit pilots specify LiDAR as the primary perception layer for geofenced corridors. NHTSA attendant-relaxation trials in Arizona and Texas rely on LiDAR redundancy for safety-driver elimination.
- Sensor Fusion:Multi-modality stacks integrate LiDAR, radar, and computer vision through neural network arbitration. China's MIIT connected-vehicle standards mandate fusion architectures for type-approval, concentrating demand among domestic manufacturers seeking public transit contracts.
- Radar:Frequency-modulated continuous-wave sensors penetrate precipitation and fog where optical systems fail. Radar serves as the fallback perception layer in European deployments constrained by UNECE R157 geofencing thresholds.
- Computer Vision:Convolutional neural networks process camera feeds for lane-keeping and traffic signal recognition. Vision-dominant configurations reduce hardware costs for budget-constrained university campus pilots.
Sensor Fusion absorbs the bulk of installed capacity; LiDAR is expanding most quickly as solid-state manufacturing scales.
Vehicle Type:
Speed requirements and passenger capacity dictate which vehicle classes attract autonomous retrofit investment.
- Shuttle Bus:Low-floor designs with 8-15 passenger capacity operate at sub-25 km/h speeds in controlled environments. Dubai's Expo City and Singapore's university campuses deploy shuttle buses exclusively for last-mile connectivity.
- Mini Bus:Compact footprints navigate narrow campus roadways and pedestrian-dense zones. India's smart city mission funds mini bus pilots at educational institutions and industrial parks under technology transfer partnerships.
- Transit Bus:Standard 40-foot configurations serve high-volume urban corridors with 60+ passenger capacity. NHTSA guidelines and EU type-approval frameworks restrict transit bus autonomy to fixed-route corridors with attendant-vehicle protocols.
- Coach:Intercity configurations with luggage compartments and highway-speed capability. Coach autonomy remains pre-commercial due to ISO 26262 ASIL-D certification timelines extending 18-24 months beyond prototype validation.
Shuttle Bus dominates current procurement volumes; Mini Bus is climbing the fastest as campus deployments multiply.
End User:
Budget cycles and risk tolerance separate early adopters from mainstream procurement.
- Public Transit Authorities:Municipal agencies in Germany, Singapore, and the United Arab Emirates issue tender specifications requiring ISO 26262 functional safety certification. Labor substitution economics drive headcount reduction targets in revenue service contracts.
- Universities:Closed-campus environments with controlled access points enable pilot programs without open-road regulatory complexity. Stanford, Carnegie Mellon, and Nanyang Technological University operate research partnerships with technology vendors.
- Private Operators:Airport-campus connector services and corporate shuttle networks pursue performance-based service contracting. Germany's regional transit authorities pilot per-passenger-mile pricing structures with private fleet managers.
- Corporations:Industrial park deployments at technology campuses and logistics facilities. Corporate buyers prioritize 5G-V2X infrastructure integration for predictive traffic negotiation.
Public Transit Authorities absorb the bulk of installed capacity; Universities are gaining share fastest through research partnerships.
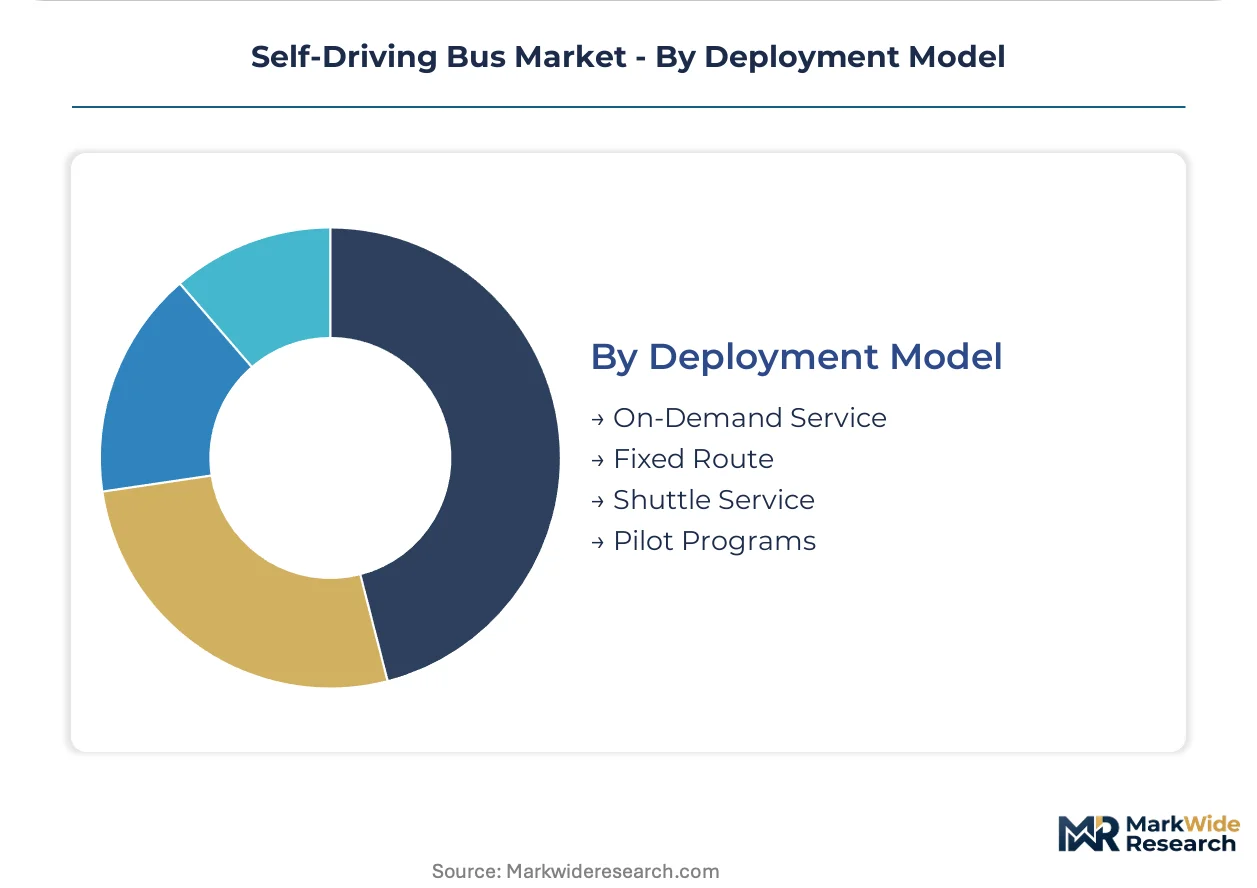
Deployment Model:
Regulatory maturity and revenue certainty determine which service architectures attract capital allocation.
- Fixed Route:Pre-mapped corridors with established stops and published schedules. Fixed route deployments occupy the most mature margin pool with proven operational envelopes and predictable maintenance cycles.
- Pilot Programs:Time-bounded trials with defined passenger volumes and geographic boundaries. China's MIIT mandates pilot completion before commercial type-approval, concentrating vendor resources in domestic corridors.
- On-Demand Service:Dynamic routing algorithms respond to real-time passenger requests via mobile applications. On-demand architectures capture disproportionate R&D allocation from private operators seeking ride-hail economics at higher vehicle density.
- Shuttle Service:Circulator routes connecting transit hubs to final destinations within defined zones. Shuttle service specifications dominate Singapore's Punggol Digital District and Dubai's autonomous vehicle zones.
Fixed Route absorbs the bulk of installed capacity; On-Demand Service shows the steepest expansion trajectory as algorithmic routing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of autonomous bus perception hardware while the United States and Germany absorb the dominant share of pilot deployment contracts. Production concentrates in Asian electronics corridors; consumption spreads across municipal transit authorities seeking labor substitution.
United States
Arizona and Texas municipal agencies operate revenue service without human safety drivers under NHTSA attendant-relaxation protocols. NHTSA guidelines shape procurement specifications for closed-campus deployments. Phoenix anchors the densest cluster of pilot programs, with regional transit authorities expanding shuttle corridors across university and airport zones.
Germany
Regional transit authorities pilot performance-based service contracting for airport-campus connectors. UNECE R157 type-approval extensions mandate geofenced corridors with pre-mapped operational envelopes. Hamburg and Bavaria concentrate validation programs, with KBA oversight determining commercial permit timelines for autonomous shuttle networks.
Singapore
Punggol Digital District validates geofenced shuttle networks at scale for Southeast Asian smart city replication. The Land Transport Authority specifies procurement templates for last-mile autonomous connectivity. Nanyang Technological University operates research partnerships testing sensor fusion architectures in controlled campus environments.
China
Domestic manufacturers seek public transit contracts under MIIT connected-vehicle standards mandating cybersecurity architectures. MIIT type-approval requires pilot completion before commercial deployment. Beijing-Tianjing-Hebei and Yangtze River Delta clusters concentrate R&D allocation for dense urban corridor optimization.
United Arab Emirates
Dubai's Expo City deploys autonomous shuttles exclusively for last-mile connectivity in controlled operational zones. MOHAP and federal transport regulators coordinate permitting for low-speed corridor validation. The emirate's autonomous vehicle zones attract technology transfer partnerships targeting Middle East smart city programs.
Self-Driving Bus Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists for procurement contracts across transit authority tenders. The vendor base organizes around three strategic archetypes: technology developers with mapping data infrastructure, sensor fusion specialists optimizing for all-weather reliability, and regulatory-first operators prioritizing closed-loop validation. Dominant competitive moves include strategic partnerships with telecommunications providers for V2X integration and portfolio diversification into performance-based service contracting.
Among the technology developer tier, Waymo leverages mapping data infrastructure to anchor long-term fleet contracts. WeRide occupies a position exemplifying all-weather sensor fusion optimization for dense Asian urban corridors. Pony.ai sits within the regulatory-first archetype, prioritizing closed-loop validation protocols before open-road expansion.
| Leading Market Players |
|---|
| Zoox |
| GetUgo |
| Waymo |
| EVIE Autonomous |
| Mozee |
| WeRide |
| Avride |
| Nuro |
| Pony.ai |
| Others |
Supply Flow & Price Mechanics
Sensor fusion engineering talent concentration in Germany's automotive corridor and California's Bay Area feeds directly into pricing-tier spreads across autonomous bus procurement contracts. Labor-cost differentials between these specialist pools and emerging engineering centers in India and Eastern Europe create three distinct pricing bands for perception-stack integration services.
Pricing Analysis
Margin tightening in mid-tier sensor configurations reflects solid-state LiDAR manufacturing scale and redundant perception-layer commoditization. Three-tier pricing structure across premium ASIL-D certified, standard geofenced-shuttle, and economy campus-pilot levels separates buyers by certification grade and volume commitment. Cost-down pressure on economy-tier hardware accelerates because university procurement offices prioritize capital expenditure minimization over functional safety redundancy. Public transit authorities exhibit lowest price sensitivity due to labor-substitution economics, while private campus operators demand aggressive per-unit discounts.
Supply Chain Analysis
Freight cost volatility for solid-state LiDAR modules shipped from Chinese manufacturing clusters to German and US assembly plants compresses landed-cost margins for Tier-1 integrators. Supply concentrates in China for LiDAR emitters, Germany for radar front-end modules, and Taiwan for edge-computing silicon. Raw material dependencies span indium phosphide wafers, gallium nitride substrates, and automotive-grade copper interconnects. Single-source vulnerability around high-performance LiDAR fabrication creates allocation risk when fleet-scale deployments exceed pilot volumes. Distribution runs through automotive Tier-1 suppliers to OEM platform integrators, with direct procurement emerging for large transit authority tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor fusion engineering scarcity and ISO 26262 certification timelines are forcing consolidation among perception-stack vendors unable to sustain 18-24 month validation cycles. Weaker players without captive LiDAR supply or regulatory-first deployment track records face acquisition or exit.
For Market Incumbents: Extend mapping data infrastructure advantages into long-term fleet service contracts before WeRide and Pony.ai replicate Waymo's anchor-tenant positioning. Secure backward integration into solid-state LiDAR fabrication through exclusive supplier partnerships to defend against allocation risk when Singapore and Germany scale pilot programs. Prioritize ASIL-D certification investment over feature expansion to maintain premium-tier pricing power. For New Entrants and Emerging Players: Launch via performance-based service contracting models targeting India's smart city mission last-mile corridors, where technology transfer partnerships lower regulatory entry barriers. Campus shuttle deployments at Nanyang Technological University and Dubai Expo City represent the most penetrable white-space segments due to controlled operational envelopes and simplified geofencing requirements. Lead with V2X-5G integration capabilities to differentiate from established sensor-fusion specialists. For Investors and Strategic Acquirers: The window for entry favors regulatory-first operators with closed-loop validation protocols and existing NHTSA or KBA commercial permits. Long-term viability hinges on vertical integration into perception hardware and recurring revenue from performance-based service contracts rather than discrete vehicle sales. Watch for the first jurisdiction relaxing attendant-vehicle mandates for low-speed shuttle corridors as the signal for accelerated capital deployment and valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Talent Acquisition | Secures scarce LiDAR-radar-computer vision integration specialists ahead of German transit authority tender cycles. |
| ASIL-D Certification Fast-Tracking | Accelerates ISO 26262 functional safety validation to meet Singapore Land Transport Authority procurement specifications. |
| LiDAR Supply Partnership | Locks in solid-state sensor allocation from Chinese manufacturers before Dubai and UAE scale autonomous vehicle zones. |
| V2X Infrastructure Integration | Enables predictive traffic negotiation for higher-speed operation on China's MIIT-mandated connected-vehicle corridors. |
| Performance-Based Contracting Pivot | Transfers operational risk to vendors through per-passenger-mile pricing aligned with Germany's regional transit pilot structures. |
Methodological Framework
Regulatory filings from NHTSA, KBA, and Singapore's Land Transport Authority, MIIT connected-vehicle standards documentation, and EU UNECE R157 extension proposals formed the secondary backbone for deployment timeline validation. Primary interviews with transit authority procurement directors, autonomous vehicle platform engineers, Tier-1 sensor supplier account managers, and university research partnership leads combined with bottom-up fleet deployment tracking and top-down municipal budget allocation analysis. SEC filings from disclosed autonomous vehicle programs and tender documentation from Germany, Singapore, and Dubai provided contract value and specification benchmarks.
Historical trendline analysis of pilot program expansion rates, regulatory approval velocity, and sensor cost deflation trajectories established baseline growth assumptions across the projection horizon. Segmentation modeling incorporated technology tier, vehicle class, end-user budget cycle, and deployment model regulatory maturity. CAGRs derived from installed base accumulation curves and replacement-demand forecasting for municipal fleet renewal programs. Industry-specific inputs encompassed LiDAR unit cost decline slopes and attendant-vehicle mandate relaxation probability assessments by jurisdiction.
Regulatory reversal on geofencing thresholds, LiDAR supply chain disruption, and fallback-driver training cost persistence are the dominant revision risks to forecast outputs. Forecasts reflect documented assumptions regarding NHTSA guideline evolution and EU type-approval pathway timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Spain Autonomous Navigation Market