
 Global Driverless Car Market | 2026-2036
Global Driverless Car Market Size, Share, and Industry Trends Forecast 2026-2036
Global Driverless Car Market Analysis
Logistics providers is repositioning fleet procurement toward autonomous commercial trucks. Waymo LLC leverages its LiDAR-first stack to dominate robotaxi operations in dense urban corridors. Tesla Inc. sustains consumer-facing autonomy through camera-only computer vision architectures. Baidu Inc. anchors its position in China through deep integration with municipal smart-city infrastructure.
Driverless cars integrate sensor fusion platforms combining LiDAR point clouds, RADAR returns, and camera feeds with neural-network-based perception stacks to navigate without human intervention. These systems execute path planning, obstacle avoidance, and real-time decision-making across variable traffic conditions. Passenger vehicles currently occupy the largest revenue pool, while ride-hailing services represent the fastest-growing application as operators seek to eliminate driver costs. LiDAR technology leads on safety-critical redundancy, though computer vision gains ground through lower hardware bills of materials.
The NHTSA in the United States and the EU AI Act in Europe impose divergent testing and liability frameworks that fragment homologation pathways for OEMs. China's MIIT and SAMR enforce GB standards and data-localization rules that shape how foreign suppliers access domestic roads. Stakeholders must monitor which regulatory bloc first achieves cross-border mutual recognition for autonomous vehicle type approval.
Market Dynamics
Sensor fusion architectures are forcing a recalibration of procurement priorities across automotive OEMs, as LiDAR cost curves and compute density requirements reshape bill-of-materials structures for production-scale autonomy.
Growth Catalysts
- EU AI Act safety protocols:The framework's mandatory pre-deployment validation creates de facto standards that reduce regulatory uncertainty for cross-border fleet operators.
- Robotaxi fleet economics:Ride-hailing operators eliminating driver labor costs achieve unit economics that justify accelerated autonomous vehicle procurement cycles.
- Municipal smart-city integration:China's GB standard-compliant V2X infrastructure investments enable real-time traffic coordination that reduces edge-case incident rates.
Market Restraints
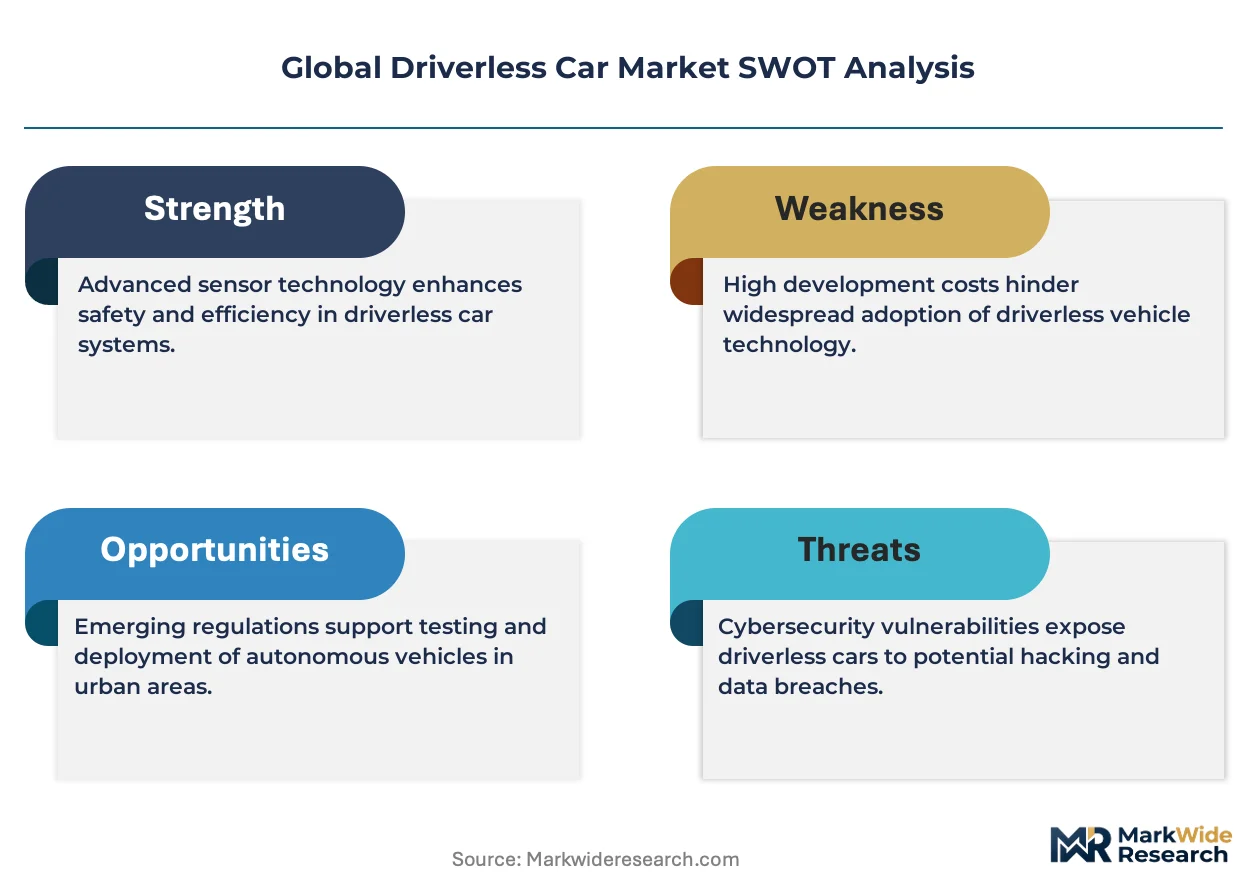
- LiDAR supply concentration:High-performance solid-state sensor production clusters in select East Asian manufacturing hubs, creating single-source vulnerability for Western OEMs.
- NHTSA-FCC spectrum allocation friction:Dedicated short-range communications band uncertainty delays V2X deployment timelines for US market entrants.
- Camera-only perception limitations:Adverse weather performance gaps in pure computer vision stacks sustain demand for costly redundant sensing layers.
Strategic Opportunities
- German industrial corridor automation:Dense freight routes between Bavarian manufacturing clusters and North Sea ports present high-utilization commercial deployment scenarios.
- India PLI scheme localization:Domestic component manufacturing incentives enable cost-competitive sensor assembly for price-sensitive fleet markets.
- HD mapping plus edge computing convergence:Real-time map updates processed at roadside infrastructure reduce onboard compute requirements for entry-level autonomy tiers.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262-certified systems architects command premium compensation that strains R&D budgets for mid-tier suppliers.
- Cross-border type approval reciprocity gaps:Divergent NHTSA, EU AI Act, and MIIT validation protocols force redundant testing expenditures for global platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Driverless Car Market |
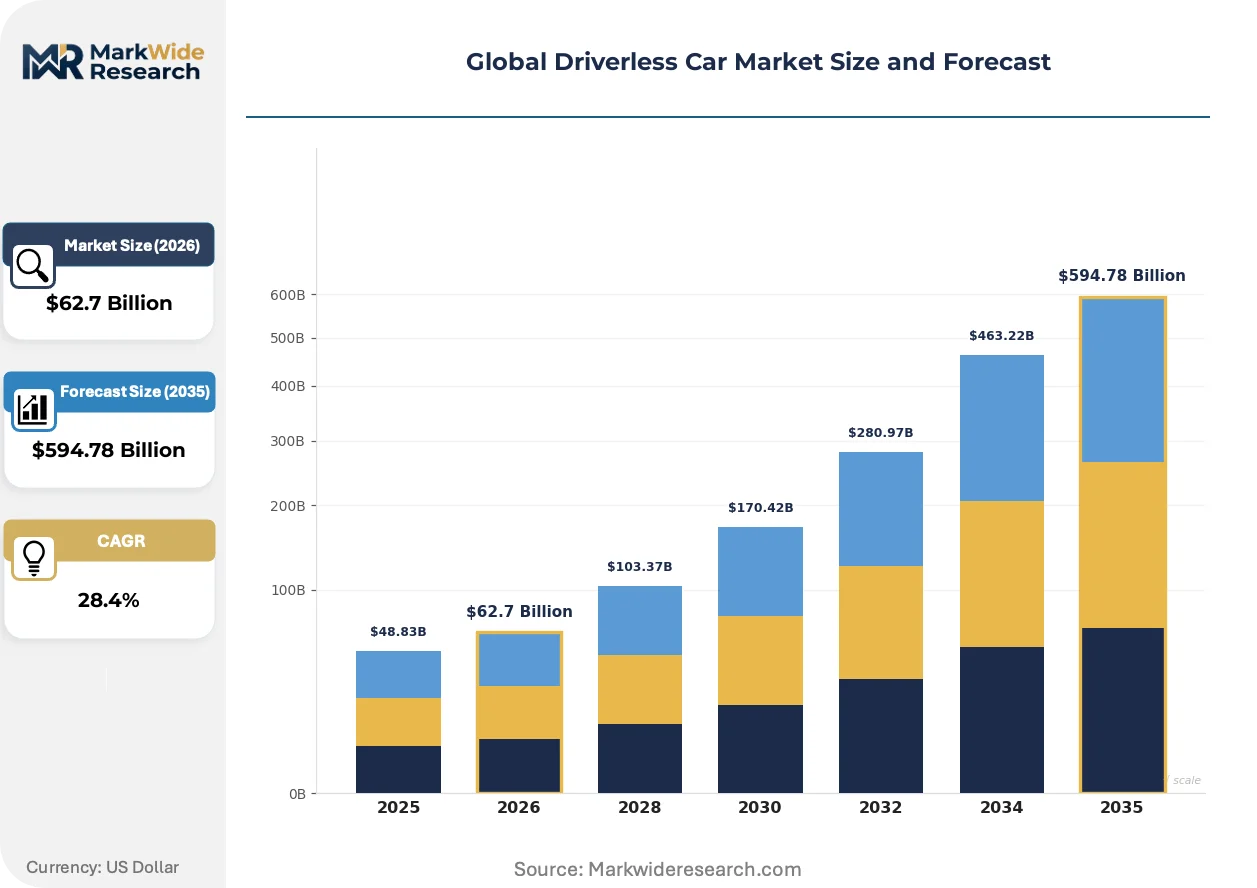
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $594.78 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Trucks, Delivery Vans, Ride-Hailing Services Technology: LiDAR, Computer Vision, RADAR, V2X Communication End User: OEMs, Ride-Sharing Companies, Logistics Providers, Public Transport Authorities Application: Urban Mobility, Freight Transportation, Autonomous Delivery, Personal Use |
| Companies Covered | Waymo LLC, Tesla Inc., General Motors Company, Zoox Inc., Baidu Inc., Pony.ai Inc., Mobileye Global Inc., Volkswagen AG, Mercedes-Benz Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Driverless Car Market Emerging Trajectories
Autonomous vehicle development is pivoting from hardware-centric differentiation toward software-defined architectures that enable post-deployment capability expansion through over-the-air updates.
Occupancy grid mapping is converging with neural radiance field techniques to reduce HD map maintenance costs for urban robotaxi operators. Tier 1 suppliers in Japan and Germany are integrating these methods into production perception stacks. The compression of map update latency from weeks to hours is converging with municipal open-data policies to accelerate geographic expansion.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on autonomous vehicle systems that process biometric data. OEMs must demonstrate algorithmic transparency and human oversight protocols to achieve CE marking. Passenger vehicle categories face the most stringent documentation requirements, prompting manufacturers to establish dedicated AI governance functions.
Fleet procurement committees now mandate total cost of ownership calculations that incorporate residual value risk from technology obsolescence. Leasing structures with embedded upgrade pathways are displacing traditional purchase models for commercial operators. This pattern is most pronounced in California and Texas, where early robotaxi deployments have exposed depreciation volatility in first-generation autonomous platforms.
Global Driverless Car Market Segmentation
Segmentation in the driverless car market exposes divergent technology maturity curves across deployment contexts. Procurement patterns fragment sharply between consumer-facing platforms and commercial fleet operators with distinct redundancy requirements.
Product Type:
Supply concentration in solid-state LiDAR fabs and high-performance compute modules favors scaled OEMs with multi-year procurement commitments.
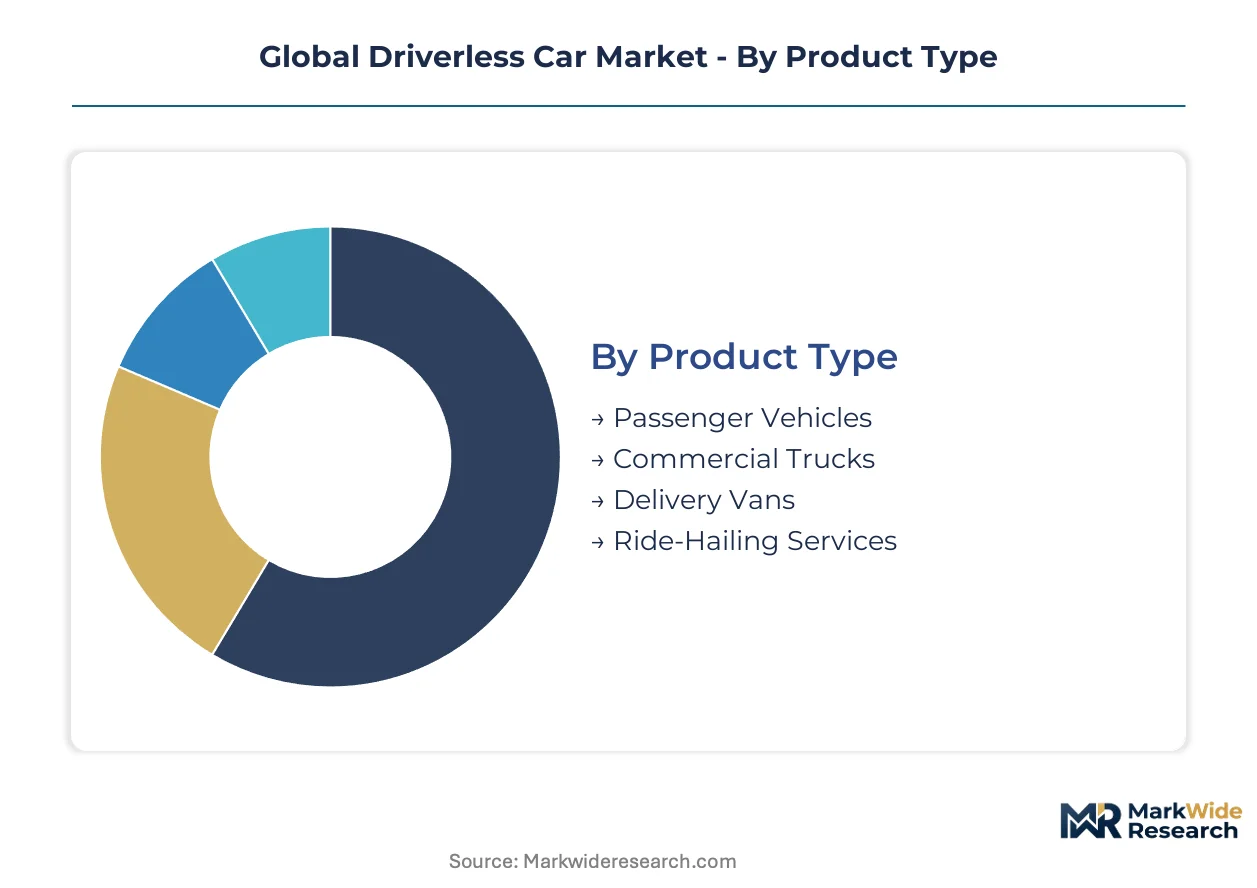
- Passenger Vehicles:These platforms integrate full sensor fusion stacks with redundant braking and steering actuators to satisfy NHTSA Level 4 validation protocols. Demand clusters among premium OEMs in Germany and the United States where regulatory clarity supports consumer liability frameworks.
- Commercial Trucks:Long-haul freight configurations prioritize highway-speed automation with simplified operational design domains. Logistics providers in the German industrial corridor between Bavaria and North Sea ports are advancing pilot deployments to capture driver cost elimination.
- Delivery Vans:Last-mile urban configurations emphasize low-speed maneuverability over highway performance. China's municipal smart-city infrastructure in Shenzhen and Beijing enables constrained geofenced operations.
- Ride-Hailing Services:Robotaxi fleets demand 24/7 operational uptime with minimal maintenance windows. Waymo LLC and Baidu Inc. dominate deployed capacity through integrated vehicle-operator technology stacks.
Passenger vehicles absorb the bulk of installed capacity; ride-hailing services are expanding most quickly.
Technology:
Cost tier stratification separates premium redundancy configurations from entry-level perception systems targeting price-sensitive fleet markets.
- LiDAR:Solid-state and mechanical spinning variants generate dense 3D point clouds for obstacle detection at 200+ meter ranges. Production concentrates in select East Asian manufacturing hubs, creating procurement bottlenecks for Western OEMs seeking dual-source strategies.
- Computer Vision:Camera-only architectures leverage neural network inference on proprietary silicon to reduce hardware bills of materials. Tesla Inc. sustains this approach despite performance degradation in adverse weather conditions that sustain demand for sensor fusion alternatives.
- RADAR:Frequency-modulated continuous-wave sensors provide velocity measurement and all-weather penetration at lower resolution than LiDAR. Tier 1 suppliers in Germany and Japan dominate 77GHz and 79GHz component supply.
- V2X Communication:Cellular vehicle-to-everything protocols enable real-time coordination with traffic infrastructure and nearby vehicles. China's GB standard-compliant deployments in Shanghai and Guangzhou lead operational density.
LiDAR retains the dominant share of safety-critical installations; computer vision is climbing the fastest on cost-driven fleet procurement.
End User:
Customer type determines validation burden and liability exposure, with public sector procurement imposing the most stringent documentation requirements.
- OEMs:Vehicle manufacturers integrate autonomous systems into production platforms with full homologation responsibility. EU AI Act conformity assessments for biometric data processing impose dedicated AI governance functions.
- Ride-Sharing Companies:Fleet operators prioritize total cost of ownership calculations incorporating residual value risk from technology obsolescence. Leasing structures with embedded upgrade pathways displace traditional purchase models in California and Texas.
- Logistics Providers:Freight operators target predictable highway corridors with simplified edge-case exposure. The NHTSA-FCC spectrum allocation friction delays V2X deployment timelines for US market entrants.
- Public Transport Authorities:Municipal operators face heightened scrutiny on safety transparency and algorithmic accountability. CE marking under EU AI Act risk-based classification imposes the most stringent documentation requirements.
OEMs command the largest procurement volumes; ride-sharing companies are gaining share fastest on unit economics justification.
Application:
Geography shapes deployment feasibility through regulatory readiness and infrastructure investment intensity.
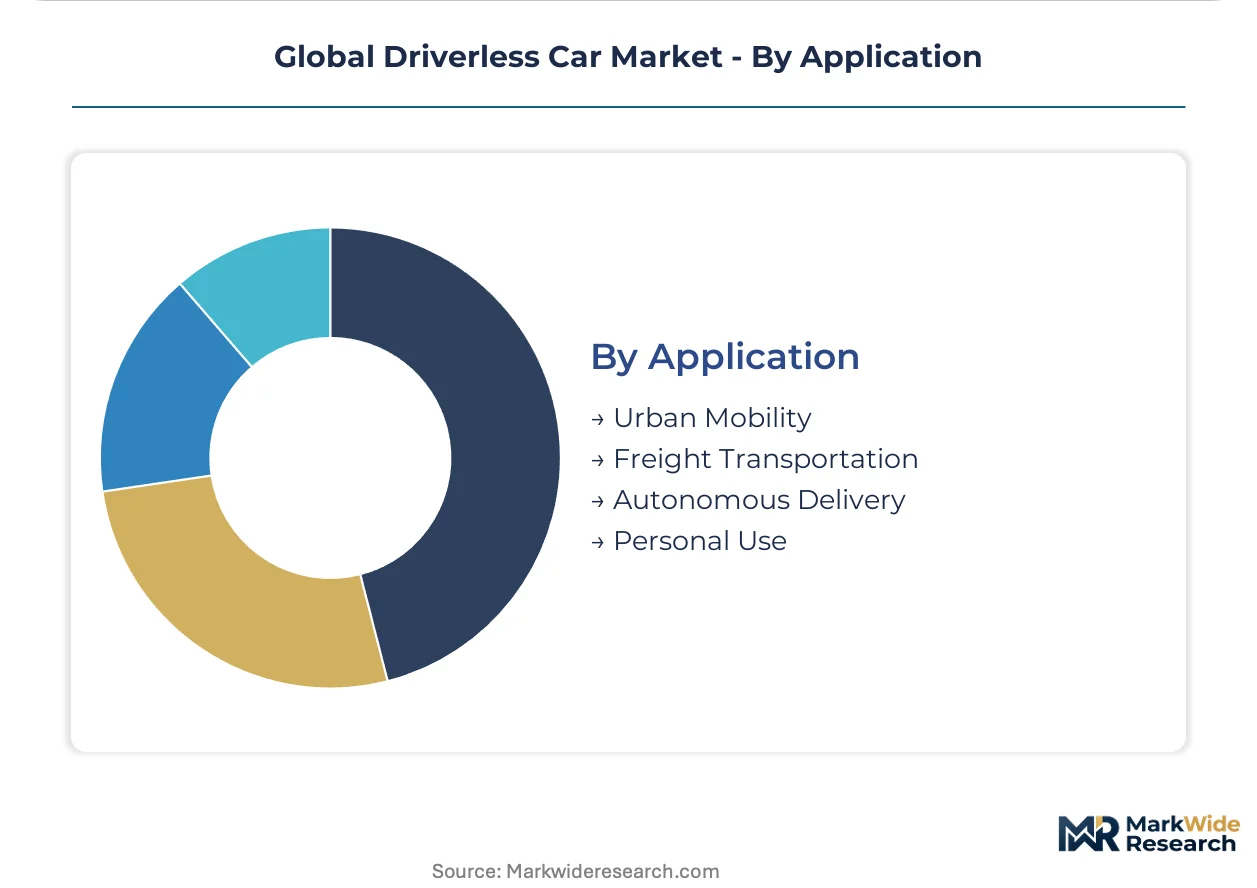
- Urban Mobility:Dense city environments require real-time pedestrian and cyclist detection with centimeter-level localization. HD mapping plus edge computing convergence at roadside infrastructure reduces onboard compute requirements.
- Freight Transportation:Hub-to-hub highway routes offer the simplest operational design domains for initial commercial scaling. German manufacturing clusters to North Sea ports present high-utilization deployment scenarios.
- Autonomous Delivery:Low-speed last-mile configurations operate within constrained geofences with remote teleoperation fallback. China's MIIT and SAMR enforcement of data-localization rules shapes foreign supplier market access.
- Personal Use:Consumer-owned vehicles face the highest liability exposure and regulatory validation burdens. ISO 26262-certified systems architect scarcity strains R&D budgets for mid-tier suppliers.
Urban mobility captures the dominant deployment count; autonomous delivery is expanding most quickly on e-commerce fulfillment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lingang Special Area and Shenzhen's Qianhai zone concentrate autonomous vehicle R&D through tax abatements and streamlined testing permits. These designated zones anchor the geographic distribution of driverless car development.
United States
Arizona and California host the densest robotaxi deployments, with Phoenix and San Francisco permitting commercial operations without safety drivers. The NHTSA maintains divergent validation protocols from European counterparts, fragmenting homologation pathways for OEMs seeking cross-border approval. Waymo LLC operates extensively across these states.
China
Shenzhen and Beijing municipal governments deploy GB standard-compliant V2X infrastructure that enables real-time traffic coordination. The MIIT and SAMR enforce data-localization rules requiring foreign suppliers to process sensor data within domestic servers. Baidu Inc. anchors operations through deep smart-city integration in these clusters.
Germany
Bavarian manufacturing corridors between Munich and Ingolstadt generate freight automation demand along dense industrial routes. The KBA administers type approval under EU AI Act risk-based classifications that mandate algorithmic transparency documentation. Mercedes-Benz Group AG validates systems across these highways.
Japan
Chubu region around Nagoya concentrates Tier 1 RADAR component manufacturing at 77GHz and 79GHz frequencies. METI coordinates national standards alignment with ISO 26262 functional safety requirements. Automotive suppliers cluster production in Aichi Prefecture for export to Western OEMs.
South Korea
Sejong and Daejeon host government-funded autonomous proving grounds with simulated urban environments. The MFDS and national standards bodies accelerate regulatory sandbox approvals for domestic technology validation. Hyundai Motor Group tests commercial truck automation on expressways connecting these cities.
Global Driverless Car Market Vendor Landscape
Top-tier vendors anchor integrated technology stacks, while mid-tier specialists concentrate on discrete sensor modules or software layers. The competitive structure stratifies between full-stack robotaxi operators and component suppliers selling into OEM procurement programs. Three archetypes dominate: LiDAR-first urban mobility providers, camera-only consumer vehicle platforms, and sensor fusion Tier 1 integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure manufacturing commitments and municipal deployment rights.
Within the full-stack operator tier, Waymo LLC and Baidu Inc. exemplify divergent geographic concentration strategies, with the former anchored in United States regulatory environments and the latter integrated with Chinese municipal infrastructure. Tesla Inc. occupies a distinct position through camera-only architectures that reduce hardware bills of materials despite weather-performance trade-offs. These three entities represent the primary competitive anchors shaping procurement patterns across passenger and commercial vehicle segments.
| Leading Market Players |
|---|
| Waymo LLC |
| Tesla Inc. |
| General Motors Company |
| Zoox Inc. |
| Baidu Inc. |
| Pony.ai Inc. |
| Mobileye Global Inc. |
| Volkswagen AG |
| Mercedes-Benz Group AG |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR sensor production concentrates in Taiwan, South Korea, and Japan, compressing component costs for scaled OEMs while fragmenting procurement leverage for smaller fleet operators seeking dual-source strategies.
Pricing Analysis
Short lead-time premiums for automotive-grade LiDAR modules sustain pricing stratification across premium, standard, and economy tiers, with contract-based long-term offtake agreements dominating procurement for robotaxi operators. Certification level under ISO 26262 and NHTSA validation status drive price differentiation, while cost compression in camera-only perception stacks intensifies pricing pressure on redundant sensor fusion configurations. Ride-sharing companies exhibit the highest price sensitivity due to fleet-scale procurement volumes, whereas premium German OEMs prioritize validation documentation over unit cost.
Supply Chain Analysis
Refurbishment flows for decommissioned autonomous vehicle compute modules are emerging as secondary supply sources for testing fleets and academic research programs. Raw material dependencies span gallium nitride substrates for LiDAR emitters, high-purity silicon for neural network accelerators, and rare-earth elements for electric drive motors. Single-source vulnerability in solid-state LiDAR fabs creates structural risk for Western OEMs. Distribution runs through Tier 1 integrators in Germany and Japan before final assembly at OEM plants in China, the United States, and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state LiDAR fab capacity constraints prop pricing power for incumbent suppliers, constraining fleet operator procurement flexibility across the projection horizon.
For Market Incumbents: Deepen backward integration into LiDAR emitter substrate production to neutralize gallium nitride supply concentration in East Asian foundries. Expand captive supply of high-performance compute modules through capacity addition in Arizona and Bavaria. Camera-only perception stacks from Tesla Inc. threaten to commoditize redundant sensing layers. For New Entrants and Emerging Players: Begin with last-mile delivery van autonomy in Shenzhen and Beijing, where municipal V2X infrastructure reduces onboard sensor requirements. India's PLI scheme localization incentives enable cost-competitive sensor assembly for price-sensitive fleet markets. Partner with Tier 1 RADAR suppliers in Japan for integrated perception stack licensing. For Investors and Strategic Acquirers: NHTSA-EU AI Act mutual recognition announcements are the leading indicator that cross-border type approval reciprocity is achievable, unlocking global platform strategies. Target acquisition archetypes include ISO 26262-certified functional safety engineering boutiques with embedded automotive OEM relationships. Monitor MIIT data-localization enforcement intensity as the signal for foreign supplier market access contraction in China.| Strategic Initiative | Industry Significance |
|---|---|
| LiDAR Supply Agreement | Secures emitter substrate allocation from Taiwan foundries for scaled production. |
| Software-Defined Vehicle Investment | Enables post-deployment autonomy expansion through over-the-air updates on Tesla Inc. competing platforms. |
| Geographic Manufacturing Footprint | Positions final assembly in Germany to satisfy EU AI Act conformity assessment proximity requirements. |
| Smart-City Infrastructure Partnership | Integrates with Shenzhen V2X deployment to reduce edge-case incident rates for robotaxi operations. |
| Functional Safety Certification Program | Accelerates ISO 26262 compliance for mid-tier suppliers facing engineer scarcity premiums. |
Methodological Framework
Independent corroboration across NHTSA validation filings, EU AI Act conformity assessments, and MIIT GB standard registrations underwrites the qualitative findings. Primary interviews with autonomous vehicle platform engineers, Tier 1 supplier procurement directors, municipal smart-city infrastructure planners, and fleet operator technology strategists were combined with secondary validation from vehicle production databases, SEC 10-K R&D disclosures, and IHS Markit registration data. Bottom-up unit deployment estimates and top-down market sizing triangulate volume outputs.
Rate-of-change decomposition across vehicle class, propulsion architecture, sensor technology tier, and regional regulatory cluster shapes the analytical framework. CAGRs derive from segment-level adoption curve modeling calibrated against infrastructure investment trajectories and homologation timeline assumptions. Forecast inputs incorporate LiDAR cost curve elasticity and V2X spectrum allocation resolution scenarios.
Underlying measurement precision varies by segment; ride-hailing fleet deployment counts carry tighter precision than consumer vehicle autonomy penetration. Forecasts reflect assumptions on regulatory sandbox expansion velocity and cross-border type approval reciprocity progress. Practitioners should monitor NHTSA-FCC spectrum allocation decisions and EU AI Act enforcement consistency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Self Driving Car Market