
 Marine Base Steering Gear Market | 2026-2036
Marine Base Steering Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Base Steering Gear Market Foresight
South Korean shipyard expansion is fragmenting the supplier landscape for large-capacity steering gear systems. Wärtsilä leverages its integrated propulsion portfolio to bundle steering solutions with main engine contracts. Hyundai Heavy Industries anchors domestic demand through captive sourcing for its own newbuild programs. Kongsberg Gruppen competes on automated navigation integration, positioning its steering systems within broader bridge-to-propeller control architectures.
Marine base steering gear comprises the mechanical, hydraulic, or electromechanical assemblies that translate helm commands into rudder movement, typically rated for torque outputs exceeding 1,000 kNm on commercial vessels and designed to meet Lloyd's Register or DNV classification rules for redundancy under single-failure conditions. Its primary purpose is to ensure directional control reliability across all operating speeds and sea states while interfacing with dynamic positioning and autopilot systems. Hydraulic configurations retain dominance in deep-sea commercial shipping due to proven load-bearing capacity, though electric and hybrid segments are capturing share in coastal and ferry applications where energy recovery and reduced maintenance intervals justify premium positioning. Recreational yachts represent a concentrated margin pool for compact integrated installations, while military ships sustain demand for shock-qualified manual override mechanisms.
The International Maritime Organization enforces steering gear redundancy standards through SOLAS Chapter II-1, compelling dual-power-source architectures on vessels above defined tonnage thresholds. DNV and Lloyd's Register classification societies layer additional fatigue-testing protocols that extend product development cycles but create barriers against uncertified entrants. Flag-state administrations in major maritime nations incorporate these rules into national construction standards, shaping procurement specifications across commercial fleets. Stakeholders must monitor how pending amendments to cyber-resilience guidelines reshape interface requirements between automated steering and integrated bridge systems.
Market Dynamics
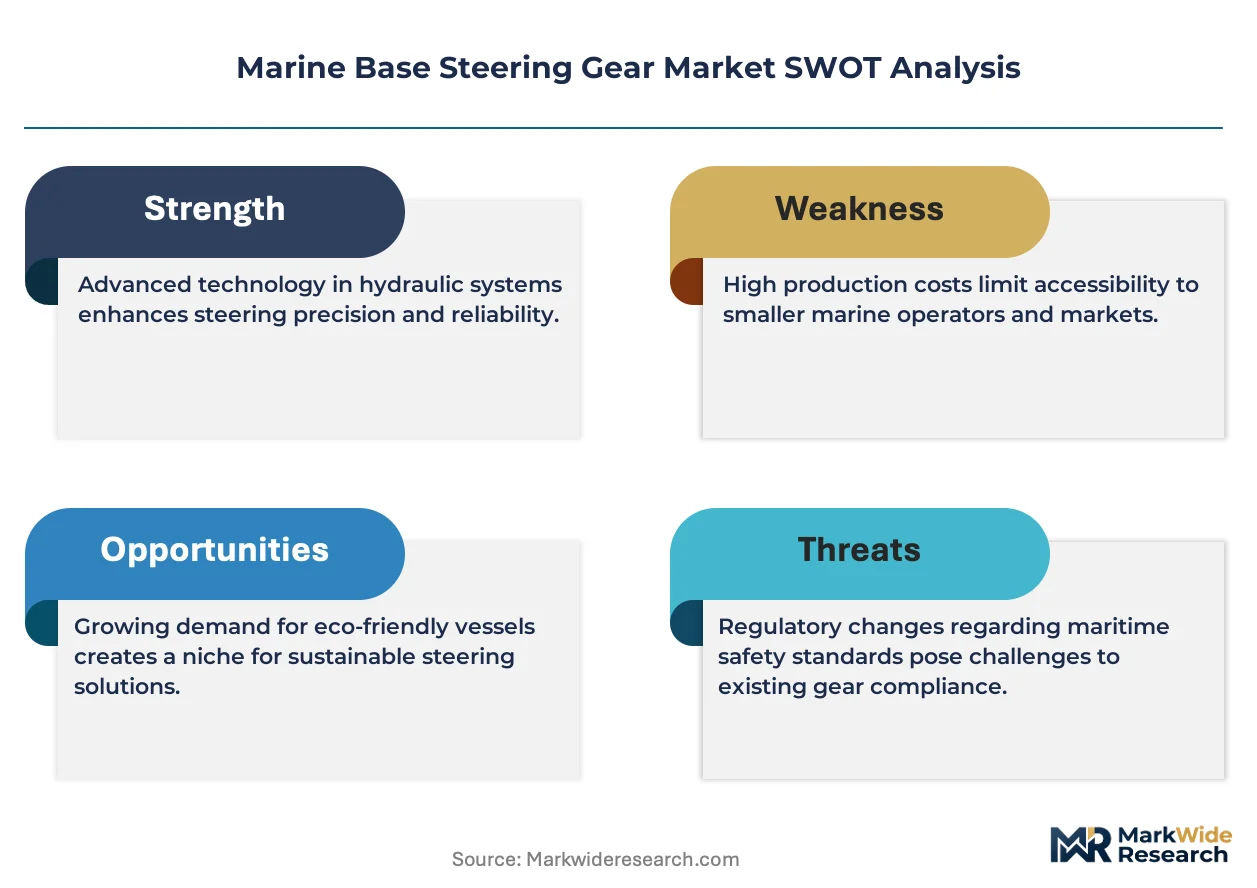
Dual-power-source architectures mandated by SOLAS Chapter II-1 are forcing shipyards to redesign steering gear integration timelines, compressing supplier qualification windows while elevating certification costs for uncertified entrants.
Growth Catalysts
- IMO Carbon Intensity Regulations:Revised CII metrics are accelerating fleet renewal programs among container and LNG carrier operators, directing capital toward electric and hybrid steering configurations that reduce auxiliary power draw during maneuvering operations.
- South Korean Shipyard Concentration:Elevated order books for large-capacity vessels at Ulsan and Geoje facilities are sustaining demand for torque-rated systems exceeding 2,000 kNm, with captive sourcing relationships locking in multi-year procurement cycles.
- Dynamic Positioning Integration:Offshore support vessels and drillships require steering gear architectures that interface with DP-2 and DP-3 redundancy standards, expanding addressable market for electromechanical actuation with millisecond response precision.
Market Restraints
- Specialized Alloy Input Volatility:Nickel-molybdenum steel plate prices fluctuate with mining output disruptions, squeezing margin on high-torque ram cylinders where material costs represent 35-40% of finished assembly value.
- Classification Society Concentration:Lloyd's Register and DNV control 70% of commercial vessel certification volume, creating bottleneck risk when either entity revises fatigue-testing protocols or extends approval timelines.
- Hydraulic System Entrenchment:Deep-sea operators resist electric conversion due to proven load-bearing capacity in heavy-weather conditions, slowing penetration of maintenance-reduced alternatives despite lifecycle cost advantages.
Strategic Opportunities
- Coastal Ferry Electrification:Norwegian and Danish short-sea routes are mandating zero-emission propulsion by 2030, creating first-mover advantage for suppliers offering regenerative-braking steering systems with energy recovery to vessel battery banks.
- Autonomous Navigation Convergence:Bridge-to-propeller control architectures integrating steering gear with AI-powered collision avoidance are opening specification windows for vendors with software-hardware co-design capabilities.
- Aftermarket Service Unbundling:Independent maintenance providers are capturing seal replacement and hydraulic fluid analysis contracts from OEM service networks, particularly in Singapore and Rotterdam hub ports.
Industry Challenges
- Marine Cyber-Resilience Certification:Pending IMO guidelines on networked steering system security are forcing suppliers to re-engineer CAN bus architectures and remote diagnostics portals without finalized compliance benchmarks.
- Skilled Hydraulic Technician Scarcity:Aging workforce demographics in European and Japanese ship repair facilities are extending dry-dock intervals for steering gear overhaul, degrading reliability metrics and insurance risk assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Base Steering Gear Market |
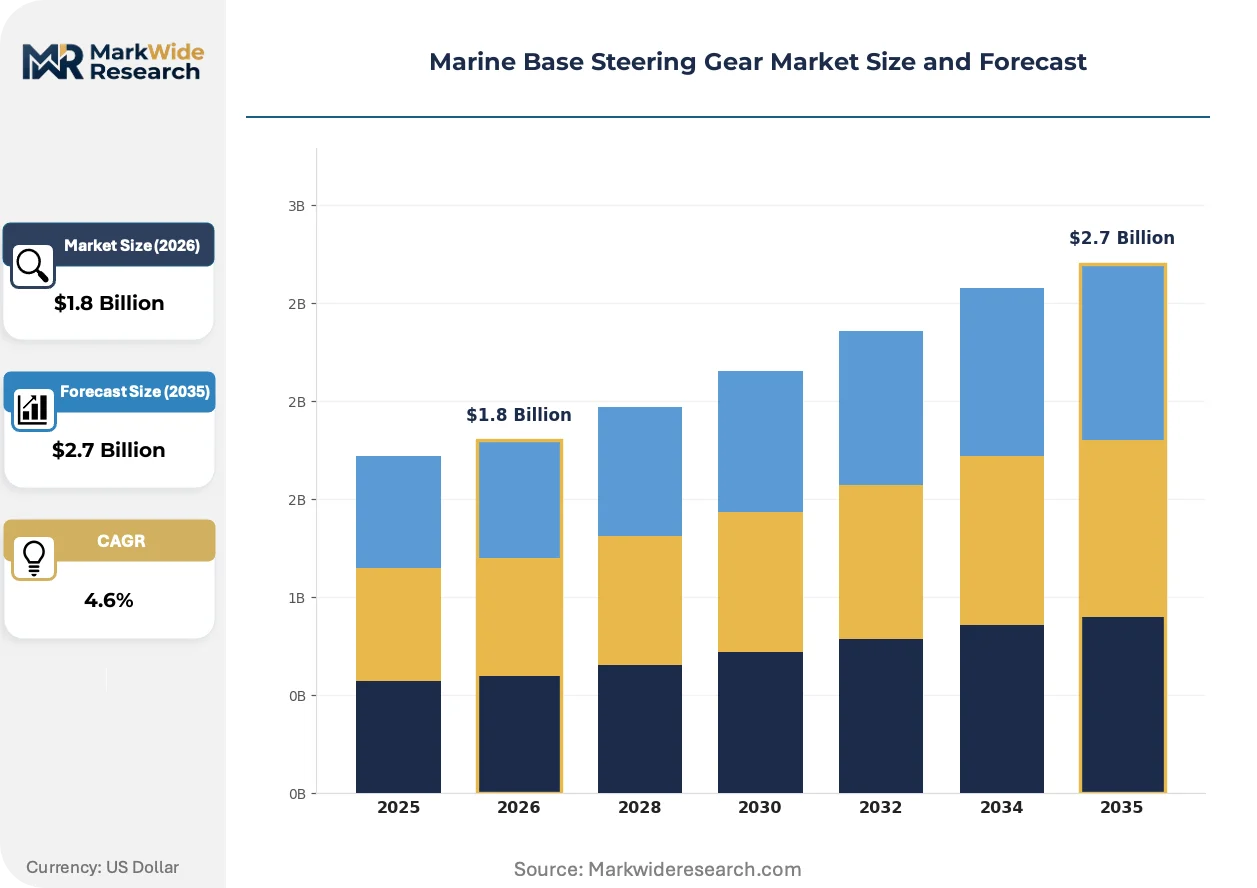
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Hydraulic, Electric, Hybrid End User: Commercial Vessels, Fishing Boats, Military Ships, Recreational Yachts Installation Type: Inboard, Outboard, Integrated, Standalone Operating Mechanism: Manual, Automated, Remote-Controlled, Assisted |
| Companies Covered | Wärtsilä, Rolls-Royce Marine, Kongsberg Gruppen, Kawasaki Heavy Industries, Hyundai Heavy Industries, Jastram Engineering, Nakashima Propeller, ZF Marine, Thrustmaster of Texas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Base Steering Gear Market Shifts & Advancements
Steering gear architectures are converging with vessel-wide automation platforms, compressing the boundary between mechanical actuation and digital command layers while redistributing value capture toward integrated system vendors.
Electromechanical servo-actuation is digitizing rudder response calibration through real-time torque feedback loops and predictive wear algorithms. Coastal ferry operators in Scandinavia are adopting these configurations fastest, driven by maintenance interval reduction targets. The technology is digitizing traditional hydraulic maintenance schedules into condition-based intervention models that collapse unplanned downtime.
EU Cyber-Resilience Act implementation timelines are extending product development cycles for steering systems with networked bridge interfaces. Manufacturers must now embed security-by-design protocols into firmware architectures before CE marking approval. Vessels trading under EU flag states face compressed retrofit deadlines, pushing demand toward certified integrated packages over component-level procurement.
Buyer consolidation among container line alliances is concentrating specification power with fleet technical managers in Copenhagen and Singapore. These procurement functions are unbundling steering gear from main engine contracts, forcing standalone vendor qualification. Greek and German owner-operators are most aggressive in this transition, extracting service-level guarantees separate from equipment supply agreements.
Marine Base Steering Gear Market Segmentation
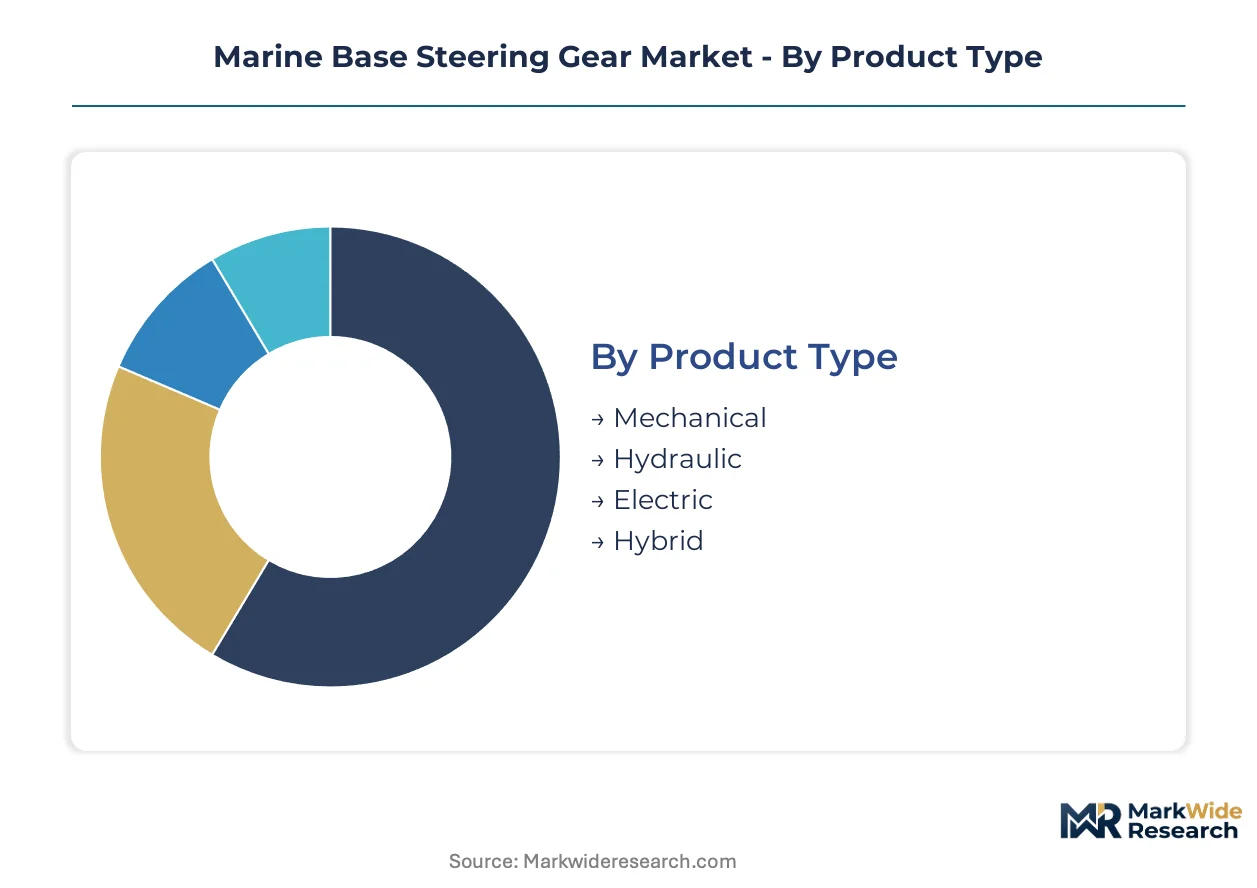
Marine base steering gear procurement specifications diverge sharply across vessel categories and operational profiles. Classification society rules, torque requirements, and redundancy mandates reshape how suppliers configure product architectures for distinct customer segments.
Product Type:
Cost tier differentiation separates mature hydraulic platforms from emerging electric alternatives with premium positioning.
- Hydraulic:Ram-type and rotary vane configurations dominate deep-sea commercial fleets with proven load-bearing capacity exceeding 2,000 kNm. South Korean shipyards specify these systems for LNG carriers and ultra-large container vessels where single-failure redundancy is mandatory under Lloyd's Register classification.
- Electric:Electromechanical servo-actuation eliminates hydraulic fluid maintenance and enables millisecond response precision for dynamic positioning integration. Norwegian coastal ferry operators are mandating these configurations for zero-emission routes, accepting higher capital outlay for reduced lifecycle operating costs.
- Hybrid:Combines hydraulic torque capacity with electric precision control for offshore support vessels requiring DP-2 redundancy.
- Mechanical:Manual screw or chain systems persist in small fishing boats and backup installations where electronic failure modes are unacceptable.
Hydraulic commands the established base. The steepest expansion runs through electric configurations.
End User:
Application-specific reliability requirements reshape torque ratings, certification tiers, and service interval specifications.
- Commercial Vessels:Container ships, bulk carriers, and tankers require SOLAS-compliant dual-power-source architectures with fatigue-tested ram cylinders. IMO carbon intensity regulations are accelerating fleet renewal programs that specify integrated steering and propulsion packages.
- Military Ships:Naval specifications demand shock-qualified manual override mechanisms and electromagnetic pulse hardening. These programs sustain demand for specialized alloy castings with extended qualification timelines.
- Recreational Yachts:Compact integrated installations serve high-net-worth owners prioritizing space efficiency over torque capacity.
- Fishing Boats:Smaller hydraulic or mechanical systems dominate where capital constraints limit automation adoption.
Commercial vessels anchor procurement volume. The fastest climb in margin contribution comes from military ships.
Installation Type:
Volume concentration in large newbuild programs favors integrated configurations over standalone procurement.
- Integrated:Steering gear bundled with main engine and propulsion contracts reduces interface risk for shipyards. Wärtsilä leverages this approach across European and Asian newbuild programs, compressing supplier qualification windows for standalone vendors.
- Standalone:Retrofit and aftermarket procurement allows owner-operators to unbundle steering systems from propulsion packages. Greek and German technical managers are extracting separate service-level guarantees through this channel.
- Inboard:Conventional below-deck mounting preserves deck space on cargo vessels with tight stern configurations.
- Outboard:Pod-mounted systems serve specialized vessels requiring minimized internal machinery footprint.
Integrated captures the dominant share of newbuild value. Standalone is gaining fastest in aftermarket unbundling.
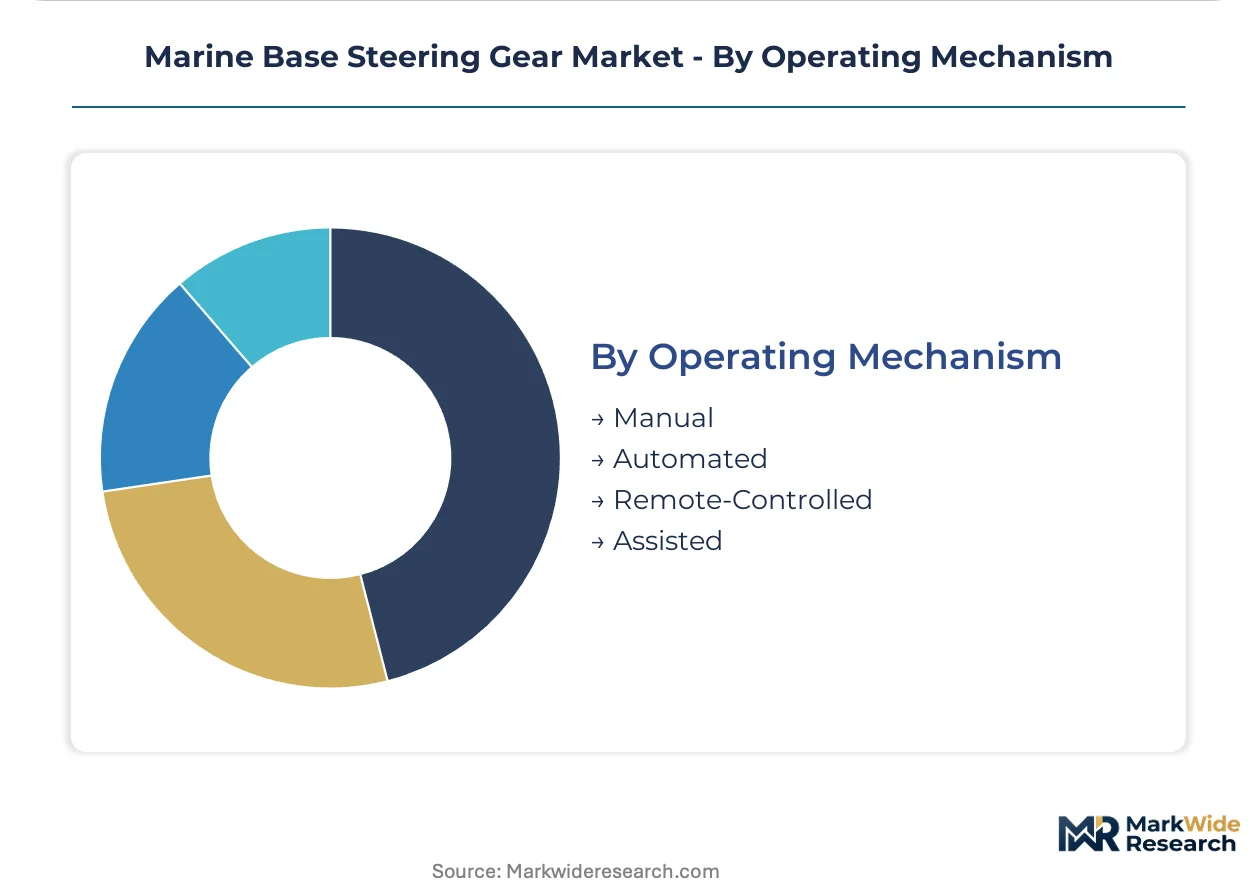
Operating Mechanism:
Customer type stratification separates autonomous-ready fleets from conventional manned operations.
- Automated:Bridge-to-propeller control architectures interface with autopilot and dynamic positioning systems. Kongsberg Gruppen competes through software-hardware co-design enabling AI-powered collision avoidance integration.
- Remote-Controlled:Shore-based and unmanned vessel operations require cyber-resilient CAN bus architectures with encrypted command protocols. Pending IMO guidelines are forcing re-engineering of diagnostics portals without finalized compliance benchmarks.
- Assisted:Partial automation with manual fallback serves offshore support vessels in DP-2 redundancy configurations.
- Manual:Direct mechanical linkage persists as SOLAS-mandated backup on all vessels above defined tonnage thresholds.
Automated systems hold the installed base. Remote-controlled is climbing fastest as autonomous navigation converges with regulatory frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyard order concentration in South Korea and contract clustering around specific maritime clusters are redrawing procurement geography for high-torque steering systems. Newbuild programs at Ulsan and Geoje facilities sustain multi-year demand cycles. Regulatory divergence across flag states is fragmenting certification requirements.
South Korea
Ulsan and Geoje shipyards anchor global demand for LNG carrier and ultra-large container vessel steering gear rated above 2,000 kNm. The Korea Register of Shipping enforces fatigue-testing protocols that extend supplier qualification timelines. Hyundai Heavy Industries leverages captive sourcing relationships to lock in multi-year procurement cycles for domestic newbuild programs.
China
State-owned shipyard consolidation at Shanghai and Dalian facilities is concentrating specification power for domestic fleet renewal. The China Classification Society implements SOLAS-aligned redundancy standards with additional GB standard compliance layers. Yangtze River Delta shipbuilders are expanding electric steering system adoption for coastal ferry electrification mandates.
Japan
Kawasaki Heavy Industries and Nakashima Propeller anchor domestic supply chains for precision-machined rudder components. The Nippon Kaiji Kyokai classification society maintains stringent shock-qualification protocols for naval and commercial overlap. Nagoya and Kobe industrial clusters sustain specialized alloy casting capabilities for high-torque ram cylinders.
Germany
ZF Marine and specialized hydraulic component fabricators serve North European retrofit demand from Hamburg and Bremen hub ports. The Federal Maritime and Hydrographic Agency enforces EU Cyber-Resilience Act timelines for networked steering interfaces. German owner-operators are unbundling steering gear procurement from main engine contracts to extract standalone service guarantees.
Norway
Kongsberg Gruppen anchors bridge-to-propeller control architecture development from Kongsberg and Horten facilities. The Norwegian Maritime Authority mandates zero-emission propulsion on short-sea routes by 2030, accelerating electric steering adoption. Oslofjord ferry operators are specifying regenerative-braking steering systems with energy recovery to vessel battery banks.
Marine Base Steering Gear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying machined castings and hydraulic subassemblies. The supplier base stratifies between full-bridge vendors bundling steering with propulsion contracts and standalone gear manufacturers competing on torque customization. Two archetypes dominate: integrated marine systems houses leveraging engine relationships, and precision-actuation specialists competing on millisecond response specifications. Competitive moves center on unbundling aftermarket service contracts from OEM networks and re-engineering CAN bus architectures for pending cyber-resilience mandates.
Among Nordic integrated systems houses, Wärtsilä and Kongsberg Gruppen occupy positions spanning propulsion-to-bridge control architectures. Wärtsilä exemplifies the bundled-contract archetype leveraging main engine relationships to compress standalone vendor qualification windows. Kongsberg Gruppen represents the automation-convergence specialist competing through software-hardware co-design capabilities. Japanese industrial conglomerates including Kawasaki Heavy Industries anchor precision-manufacturing positions in high-torque mechanical assemblies. Hyundai Heavy Industries sits within the captive-sourcing tier, internalizing demand from affiliated shipyard operations. These named entities illustrate how geographic clustering around Ulsan, Kongsberg, and Kobe shapes competitive positioning without exhaustive market share claims.
| Leading Market Players |
|---|
| Wärtsilä |
| Rolls-Royce Marine |
| Kongsberg Gruppen |
| Kawasaki Heavy Industries |
| Hyundai Heavy Industries |
| Jastram Engineering |
| Nakashima Propeller |
| ZF Marine |
| Thrustmaster of Texas |
| Others |
Supply & Pricing Matrix
Nickel-molybdenum steel plate concentration in Japanese and South Korean foundries anchors margin capture at the high-torque ram cylinder tier, where material costs consume 35-40% of finished assembly value and Lloyd's Register certification premiums compound pricing power for qualified suppliers.
Pricing Analysis
SOLAS Chapter II-1 dictates the pricing tier structure across dual-power-source architectures, with Lloyd's Register and DNV certification grades separating premium hydraulic systems from standard electric configurations. Price differentiation rests on fatigue-testing compliance depth and after-sales service bundling, with Norwegian ferry operators least sensitive due to zero-emission mandates while Southeast Asian fishing fleets resist premium positioning. Cost compression in standard hydraulic tiers is intensifying because South Korean shipyard captive sourcing locks out independent vendors.
Supply Chain Analysis
Export controls on precision-machined rudder components and high-grade alloy castings limit technology flows from Japanese industrial clusters to non-allied shipyards. Supply concentrates in South Korea, Japan, and Germany for torque-rated assemblies exceeding 2,000 kNm, with nickel-molybdenum steel plate and electromechanical servo motors as critical inputs. Single-source vulnerability runs through Lloyd's Register and DNV certification bottlenecks. Distribution runs through integrated propulsion bundling at newbuild stage and standalone aftermarket procurement at hub ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through SOLAS and classification society certification creates switching costs that protect incumbent positions across multi-year shipyard procurement cycles.
For Market Incumbents: Entrench certification leadership by deepening Lloyd's Register and DNV fatigue-testing protocol investment ahead of pending cyber-resilience amendments. Lock in backward integration into nickel-molybdenum steel plate supply through long-term offtake agreements with Japanese foundries. The threat of electric steering displacement in coastal routes demands preemptive hybrid system R&D to preserve hydraulic torque advantages. For New Entrants and Emerging Players: Establish a beachhead in coastal ferry electrification segments where Norwegian and Danish zero-emission mandates create specification windows unclaimed by entrenched hydraulic suppliers. Target autonomous navigation interface development as the most penetrable white-space, leveraging software-hardware co-design capabilities to bypass legacy certification barriers. A go-to-market angle through DP-2 redundancy subsystem partnerships with offshore support vessel operators bypasses integrated propulsion bundling. For Investors and Strategic Acquirers: Capital is best deployed toward precision-actuation specialists with millisecond response specifications and existing DNV cyber-resilience certification progress. Long-term viability favors vendors positioned at the automation convergence layer rather than commodity hydraulic component tiers. The signal to watch is IMO finalization of networked steering security guidelines, which will trigger accelerated vendor consolidation around compliant integrated architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early Lloyd's Register cyber-resilience approval locks out competitors during IMO guideline transition windows. |
| Backward Integration into Alloys | In-house nickel-molybdenum steel plate supply insulates margin from mining output disruption volatility. |
| Hybrid System Development | Combining hydraulic torque with electric precision captures coastal ferry electrification mandates without abandoning deep-sea position. |
| Aftermarket Service Unbundling | Independent seal replacement and hydraulic fluid analysis contracts at Singapore and Rotterdam hub ports capture recurring revenue streams. |
| Autonomous Navigation Partnership | Bridge-to-propeller control architecture integration with AI-powered collision avoidance systems opens specification windows beyond traditional bundling. |
Research Methodology
Cross-validation between shipyard procurement director interviews and classification society certification databases anchors the qualitative findings in this analysis. Primary fieldwork engaged fleet technical managers at Copenhagen and Singapore container line alliances, hydraulic system maintenance heads at Rotterdam and Singapore hub ports, and engineering directors at Ulsan and Geoje shipyard facilities. Secondary validation drew from Lloyd's Register and DNV published rule changes, SOLAS amendment tracking, Korea Register of Shipping bulletins, and EU Cyber-Resilience Act implementation timelines. Bottom-up vessel order book analysis and top-down fleet modernization spend estimates were triangulated to constrain range uncertainty.
Calibration against historical adoption curves for electric steering in Scandinavian ferry routes and hydraulic system replacement cycles in deep-sea commercial fleets shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, end-user vessel category, installation configuration, and operating mechanism autonomy level. CAGRs were derived from shipyard order book concentration at South Korean facilities and IMO regulatory compliance deadline clustering. Industry-specific forecast inputs encompass nickel-molybdenum steel price volatility bands and classification society approval timeline distributions.
Stress conditions across nickel-molybdenum mining output disruption severity, Lloyd's Register protocol revision timing, and South Korean shipyard order cancellation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about SOLAS amendment adoption trajectories and cyber-resilience guideline finalization schedules. Material shifts in IMO carbon intensity regulation stringency or classification society merger activity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Fishing Vessel Market
Marine
Azimuth Thrusters Market
Marine
Global Maritime Information Market
Marine
Marine Turbocharger Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Marine Fender Systems Market
Marine
Ship Heat Exchanger Market
Marine
Global Discount-Marine Trenchers Market
Marine
Marine AIS Monitoring System Market
Marine
Marine Communication Market
Marine
India Boat Davits Market
Marine
Marine and Marine Management Software Market
Marine
Marine Shackle Market
Marine
Marine Fasteners Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market