
 Self-Driving Electric Vehicle Market | 2026-2036
Self-Driving Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Electric Vehicle Market Analysis
Level 4 autonomy certification is bifurcating the competitive landscape into premium full-self-driving platforms and cost-constrained advanced driver-assistance systems. Tesla leverages its vertically integrated compute stack to sustain end-to-end neural network development. Waymo anchors commercial robotaxi operations across multiple US metropolitan zones. BYD dominates battery electric powertrain manufacturing at scale, extending cost advantages into autonomous vehicle partnerships.
Self-driving electric vehicles integrate electric propulsion systems with automated driving systems comprising lidar, radar, camera arrays, and centralized AI compute platforms, achieving functional safety ratings up to ASIL-D under ISO 26262 for fail-operational performance. The primary purpose is to eliminate human error from transportation while reducing lifecycle emissions through electrified drivetrains. Machine learning architectures within the technology segment are capturing disproportionate R&D investment as training data scale determines algorithmic performance. Ride-sharing under end user classification represents the fastest route to monetization, though fleet management accounts for the deepest margin pools through long-term service contracts. Urban mobility applications lead deployment volume, while last-mile delivery is concentrating specialized vehicle form factors.
NHTSA in the United States, MIIT in China, and the EU AI Act alongside UNECE WP.29 regulations are establishing divergent compliance pathways that fragment homologation strategies and delay cross-border platform launches. OEMs must navigate separate cybersecurity, data governance, and operational design domain requirements across jurisdictions. Stakeholders should monitor regulatory reciprocity negotiations, as mutual recognition agreements would reshape competitive positioning more than any single technical breakthrough.
Market Dynamics
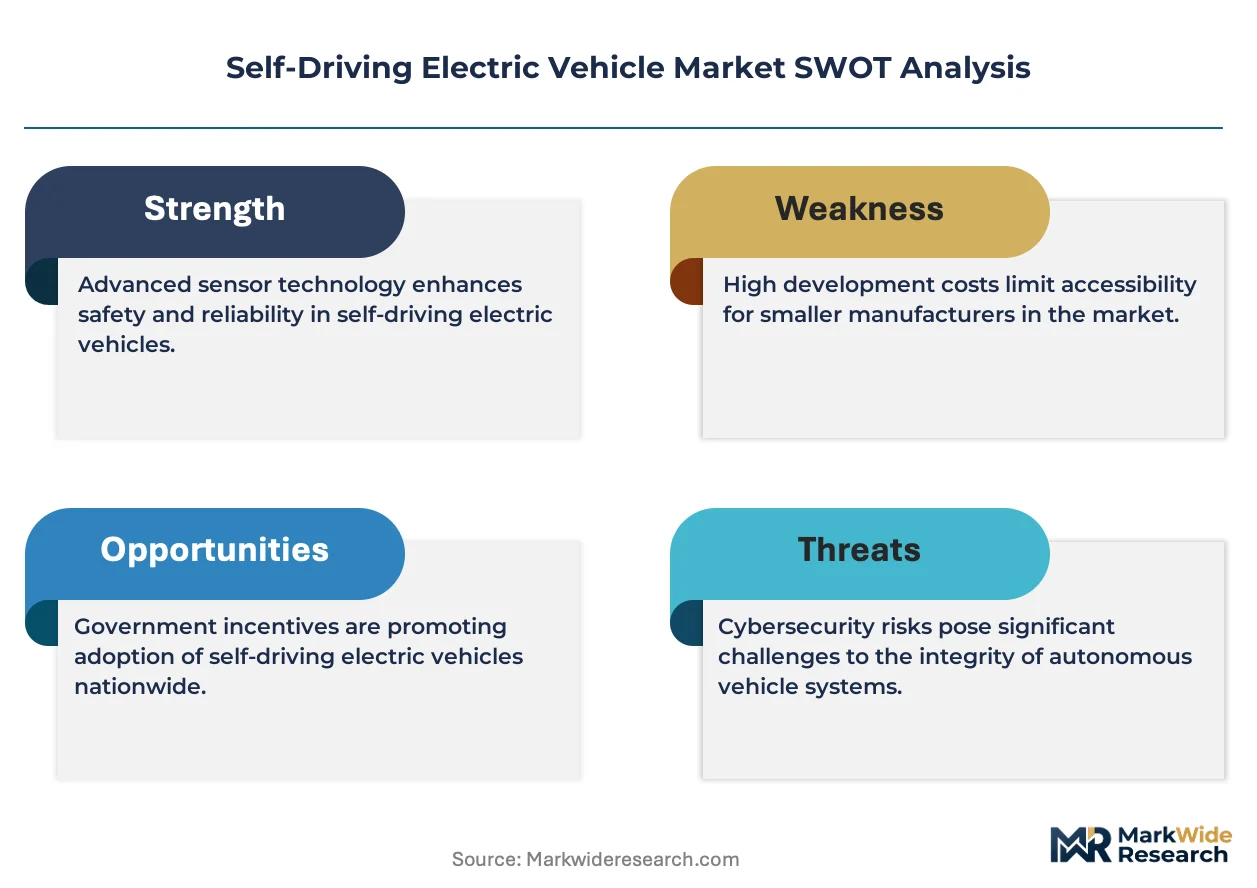
The Self-Driving Electric Vehicle Market is being reshaped by the divergence between centralized AI compute architectures and distributed edge-processing approaches, with NHTSA rulemaking on fail-operational performance standards forcing OEMs into expensive redundant sensor configurations.
Growth Catalysts
- NHTSA Safety Mandates:Federal requirements for redundant braking and steering systems are accelerating investment in ASIL-D certified components across US vehicle programs.
- Robotaxi Permits:Municipal licensing frameworks in Beijing and Shenzhen are converting testbed fleets into revenue-generating commercial operations.
- Lithium-Iron-Phosphate Chemistry:Battery cost curves for LFP cells are improving unit economics for high-utilization autonomous fleets.
Market Restraints
- Lidar Cost Structure:Solid-state and mechanical lidar units remain the single most expensive sensor category in Level 4 sensor suites.
- Rare Earth Concentration:Permanent magnet motor supply chains concentrate in Chinese processing facilities, creating geopolitical input risk.
- EU AI Act Friction:Conformity assessment requirements for automated decision-making systems are extending homologation timelines for European launches.
Strategic Opportunities
- Last-Mile Logistics:Urban delivery van form factors below 3.5 tonnes face lighter regulatory burdens than passenger robotaxi applications.
- India PLI Scheme:Production-linked incentives for advanced automotive technology are attracting battery and component manufacturing investments.
- V2X Infrastructure Convergence:Integration of cellular vehicle-to-everything protocols with edge computing nodes is opening fleet management service contracts.
Industry Challenges
- Systems Safety Engineering Talent:Functional safety expertise under ISO 26262 is scarce relative to demand from powertrain and autonomy programs.
- Sensor Fusion Validation:Proving deterministic performance across camera-radar-lidar combinations requires exponentially expanding test mileage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Electric Vehicle Market |
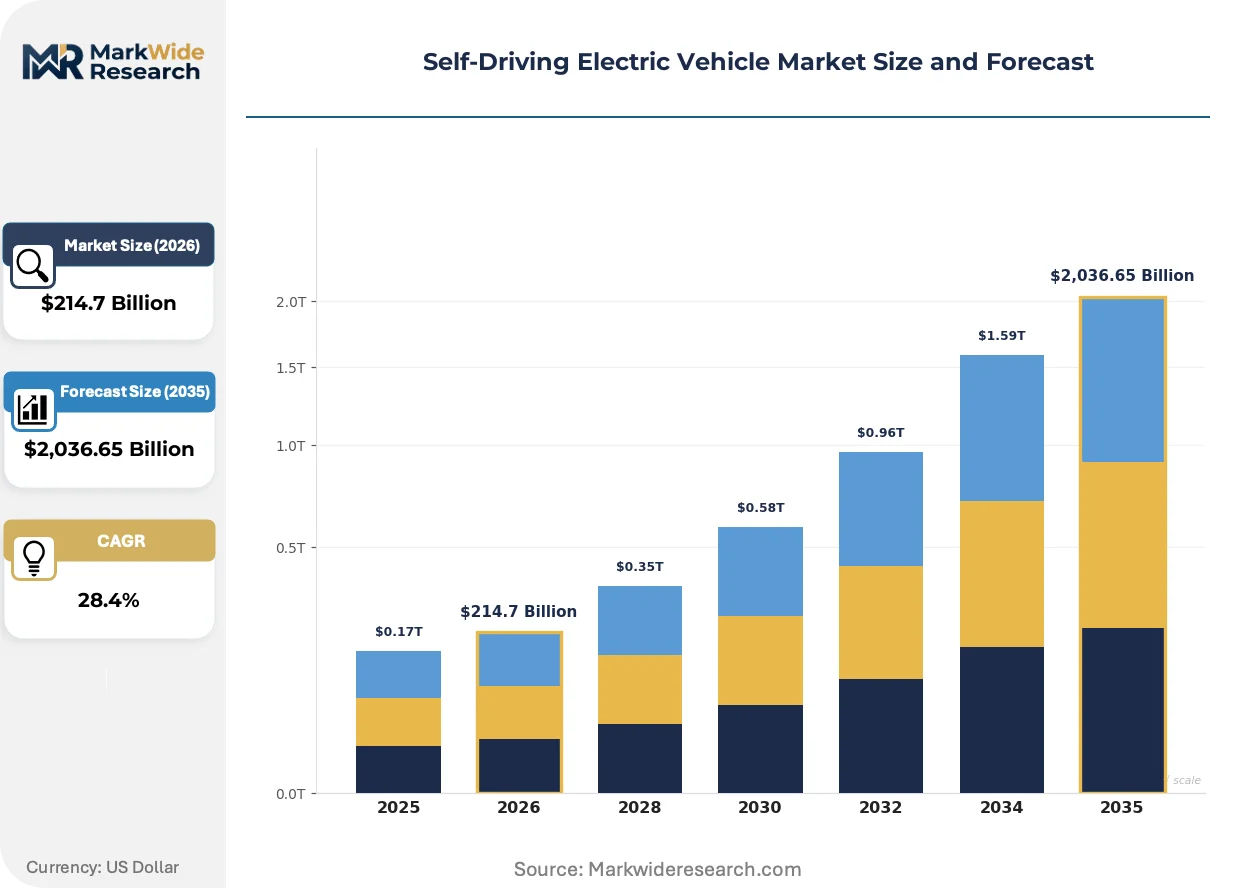
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $2,036.65 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Layered Architecture, Sensor Fusion, Machine Learning, Neural Networks End User: Ride-Sharing, Personal Ownership, Fleet Management, Public Transportation Application: Urban Mobility, Last-Mile Delivery, Highway Transportation, Automated Parking Powertrain: Battery Electric, Fuel Cell Electric, Hybrid Electric, Plug-in Hybrid |
| Companies Covered | XPeng, Li Auto, Tesla, NIO, Lucid Motors, Waymo, Zoox, Rivian, BYD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Electric Vehicle Market Emerging Trajectories
End-to-end neural network architectures are displacing modular perception-planning-control stacks, compressing development timelines while raising validation complexity. This shift is redrawing competitive boundaries between vertically integrated compute platforms and tiered supplier ecosystems.
Occupancy network representations are decomposing the traditional object-detection-and-tracking pipeline into unified 3D scene understanding. Autonomous vehicle developers at scale are adopting these architectures for urban robotaxi fleets. The technology is decomposing the historical separation between perception software suppliers and Tier 1 integration houses.
UNECE WP.29 regulations on cybersecurity and software updates are mandating over-the-air capability and intrusion detection systems for type approval. OEMs must restructure supplier contracts to maintain continuous compliance documentation. European passenger vehicle programs face the steepest implementation curves due to retroactive applicability clauses.
Fleet procurement is consolidating around guaranteed uptime contracts with penalty structures for availability shortfalls. Logistics operators are displacing traditional vehicle purchase models with full-service leases bundling maintenance, energy, and software subscriptions. This pattern is most visible in California and Germany where large last-mile operators run mixed electric-autonomous pilot programs.
Self-Driving Electric Vehicle Market Segmentation
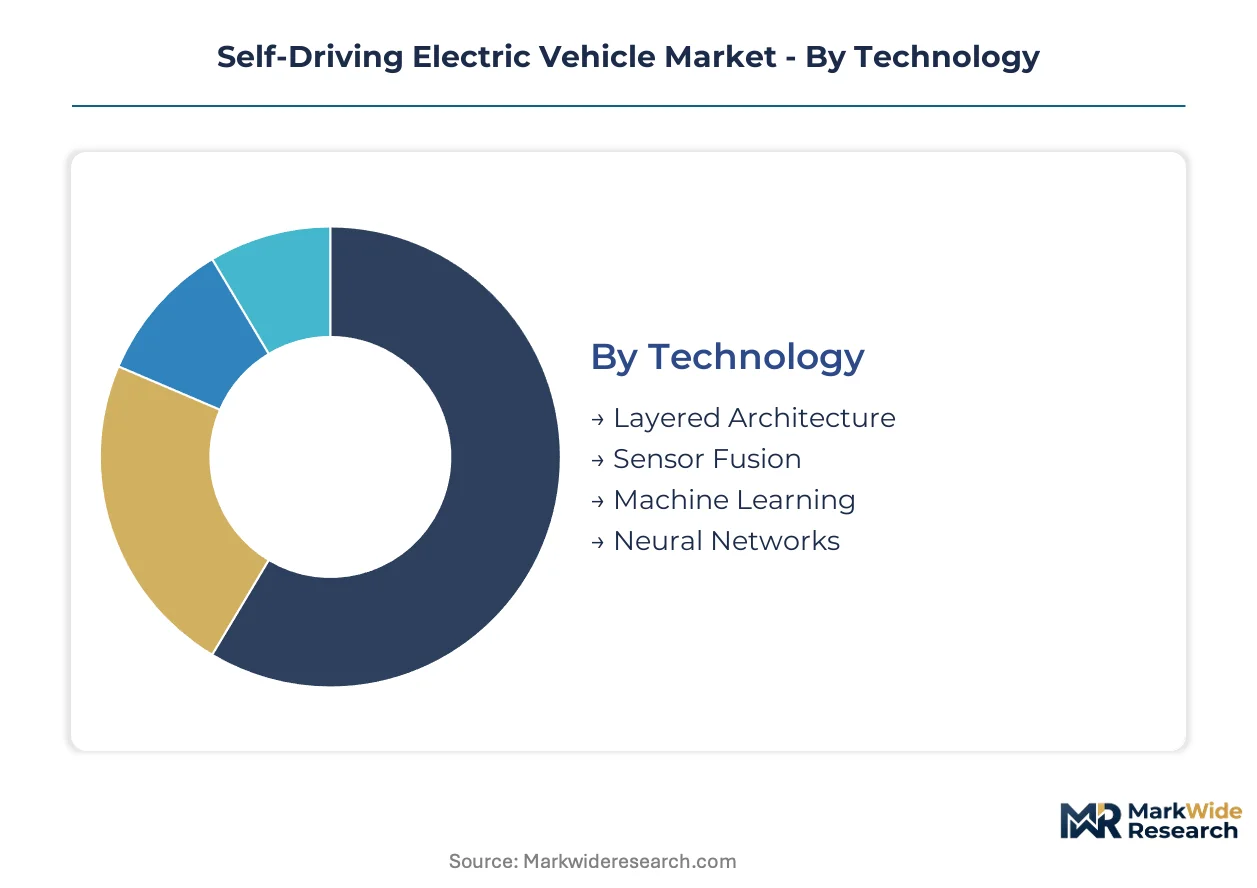
Segmentation in the Self-Driving Electric Vehicle Market reveals how autonomous technology, commercial deployment models, and electrification pathways intersect. Channel strategies diverge sharply between consumer-facing robotaxi services and B2B fleet contracts. Understanding these divisions clarifies where capital is concentrating and which regulatory pathways shape go-to-market timing.
Technology:
Technology segments flow through distinct commercialization channels. Layered architectures dominate established OEM supply chains. End-to-end neural approaches attract venture-backed autonomy specialists seeking direct fleet operator relationships.
- Layered Architecture:Modular perception-planning-control stacks separate sensor processing from decision algorithms. Tier 1 suppliers like Continental and Bosch dominate this channel through long-term OEM contracts. NHTSA's ASIL-D requirements reinforce supplier incumbency by demanding traceable validation documentation that modular systems provide.
- Machine Learning:Training-data scale determines performance differentiation. Cloud-based development pipelines concentrate in hyperscaler partnerships with Waymo and Cruise. MIIT certification pathways in Beijing and Shenzhen favor ML-heavy stacks that demonstrate statistical safety validation over deterministic rule-based alternatives.
- Sensor Fusion:Camera-radar-lidar integration demands specialized calibration expertise. Automotive electronics contract manufacturers in Taiwan and South Korea control this channel.
- Neural Networks:End-to-end architectures compress development timelines but require massive compute infrastructure. Tesla's vertically integrated stack bypasses traditional supplier channels entirely.
By volume, Layered Architecture leads. By growth pace, Neural Networks is climbing the fastest.
End User:
End user segments map to fundamentally different contract structures and margin profiles. Ride-sharing demands per-mile economics. Fleet management locks in long-term service agreements with guaranteed uptime clauses.
- Fleet Management:Logistics operators and delivery platforms negotiate full-service leases bundling vehicles, energy, maintenance, and software. California's last-mile pilots with FedEx and UPS anchor this segment. Contracts typically span 5-7 years with penalty structures for availability shortfalls below 95%.
- Ride-Sharing:Robotaxi services monetize through per-trip fees in dense urban corridors. Waymo's operations in Phoenix, San Francisco, and Los Angeles represent the commercial frontier. Municipal permitting in these cities creates concentrated deployment zones with regulatory moats.
- Personal Ownership:Consumer sales of Level 4-capable vehicles remain minimal due to liability frameworks and ODD restrictions. Premium OEM channels in Germany and California test subscription-based feature activation models.
- Public Transportation:Municipal procurement of autonomous shuttles follows rigid tender processes. Fixed-route campus and airport deployments in Singapore and Dubai lead this channel.
Fleet Management captures the deepest margins. Ride-Sharing offers the steepest expansion trajectory.
Application:
Application segments stratify by regulatory burden and infrastructure dependency. Urban mobility faces complex edge-case density. Highway transportation benefits from structured environment predictability.
- Urban Mobility:Dense pedestrian interaction, construction zones, and erratic traffic patterns demand the most sophisticated perception stacks. Beijing's robotaxi permits and Shenzhen's autonomous bus corridors concentrate deployment. NHTSA's pending urban ODD guidelines will determine US market entry timing.
- Last-Mile Delivery:Low-speed, geofenced operations below 40 km/h face lighter homologation requirements. Nuro and Amazon's Scout programs in Texas and Arizona exploit this regulatory arbitrage. Delivery van form factors under 3.5 tonnes bypass passenger-vehicle crash standards.
- Highway Transportation:Structured environments with predictable lane markings and traffic flows enable earlier Level 4 deployment. European truck platooning trials on German autobahns test this application.
- Automated Parking:Limited-speed, infrastructure-assisted operations represent the lowest autonomy barrier. BMW and Mercedes-Benz deploy in Germany under UNECE WP.29's ALKS regulation for designated parking structures.
Urban Mobility leads deployment volume. Last-Mile Delivery is gaining share fastest.
Powertrain:
Powertrain segments align with fleet utilization intensity and charging infrastructure maturity. High-utilization autonomous fleets favor battery configurations with proven supply chains.
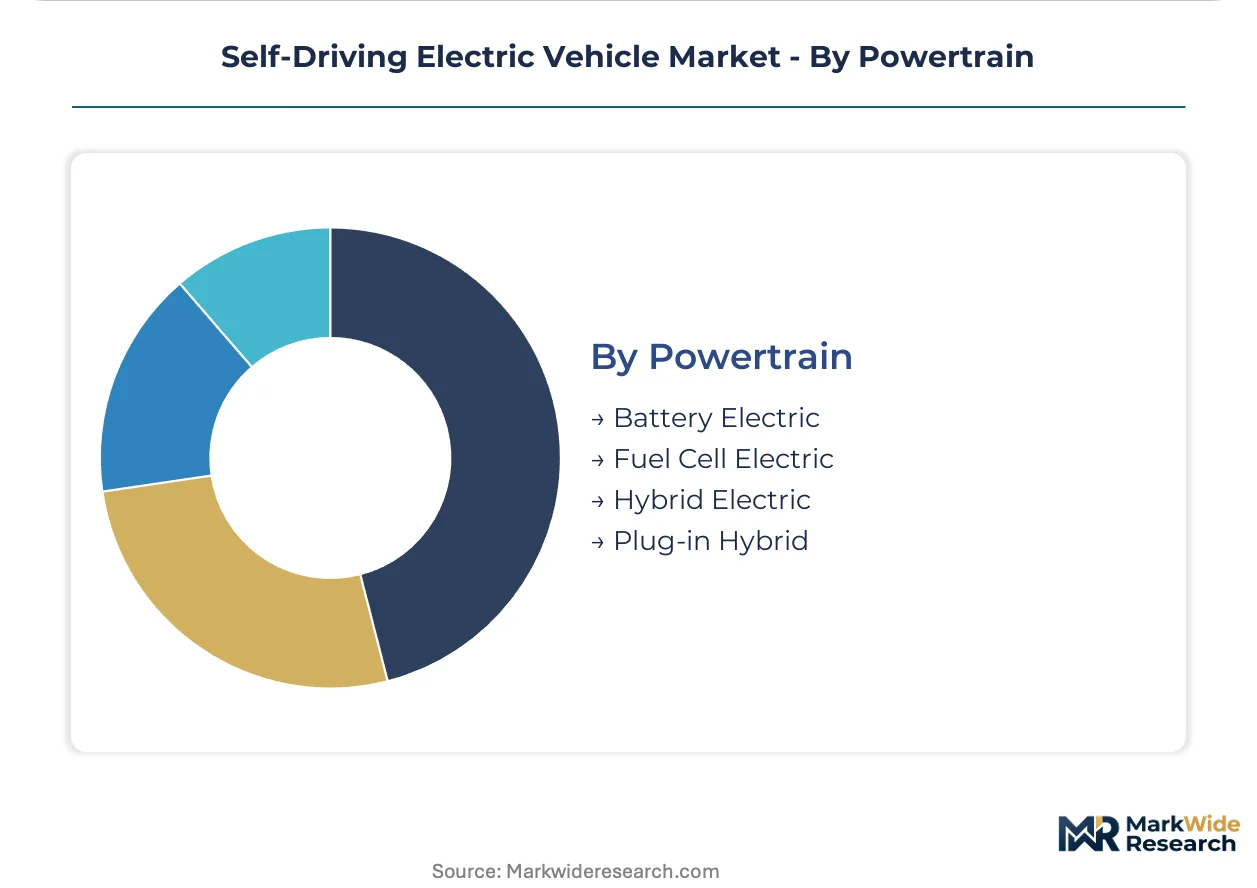
- Battery Electric:Lithium-iron-phosphate chemistry dominates high-mileage fleet applications due to cycle life and thermal stability. BYD's blade battery architecture anchors Chinese robotaxi deployments. Tesla's 4680 cell ramp targets autonomous fleet density in Texas and Nevada.
- Fuel Cell Electric:Hydrogen refueling speed advantages suit extended-range highway trucking. Hyundai's Xcient Fuel Cell pilots in Switzerland leverage existing H2 corridor infrastructure.
- Hybrid Electric:Range anxiety mitigation appeals to personal ownership segments in charging-sparse regions. Toyota's hybrid dominance in Japan creates regional channel concentration.
- Plug-in Hybrid:Transitional technology for fleets awaiting charging infrastructure buildout. European delivery operators in rural Germany and France test this configuration.
Battery Electric dominates unit economics. Fuel Cell Electric holds steepest expansion potential in long-haul corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in autonomous electric vehicle technology concentrate in China, Germany, and the United States, with each jurisdiction developing distinct regulatory reciprocity barriers that fragment cross-border platform deployment timelines.
United States
Robotaxi commercialization in Phoenix, San Francisco, and Los Angeles generates concentrated revenue streams for autonomous fleet operators. NHTSA rulemaking on fail-operational performance standards mandates redundant braking and steering systems that inflate hardware costs for domestic programs. Arizona's permissive regulatory environment anchors scaled testing-to-deployment corridors.
China
MIIT certification pathways and municipal robotaxi permits in Beijing and Shenzhen convert testbed fleets into commercial operations faster than Western counterparts. The dual carbon goals framework accelerates battery electric powertrain integration into autonomous platforms. BYD's blade battery architecture dominates supply chains serving robotaxi deployments.
Germany
UNECE WP.29 regulations on cybersecurity and software updates mandate over-the-air capability that extends homologation timelines for European launches. BMW and Mercedes-Benz deploy automated parking systems under ALKS regulations for designated structures. Bavaria's automotive engineering clusters concentrate functional safety expertise for ISO 26262 compliance.
Japan
METI funding for next-generation mobility infrastructure supports autonomous shuttle pilots in rural depopulation zones. Toyota's hybrid dominance creates regional channel concentration for transitional powertrain configurations. Nagoya's industrial corridor anchors sensor fusion calibration expertise serving domestic OEM supply chains.
South Korea
Seoul Capital Area robotaxi pilots leverage dense 5G infrastructure for cellular vehicle-to-everything protocol integration. MFDS alignment with international automotive safety standards streamlines component export certification for domestic suppliers. Busan-Ulsan manufacturing zones concentrate automotive electronics contract manufacturing for sensor integration.
Self-Driving Electric Vehicle Market Vendor Landscape
Concentration sits with vertically integrated technology stacks and tiered supplier ecosystems. Three to five players control neural network training infrastructure and ASIL-D certified component supply. Strategic moves center on hyperscaler cloud partnerships for development pipelines and long-term fleet service contracts with guaranteed uptime clauses.
Within the vertically integrated tier, Tesla, Waymo, and BYD occupy positions that exemplify divergent pathways to autonomous electric vehicle commercialization. Tesla represents the captive compute stack approach with end-to-end neural network development. Waymo anchors commercial robotaxi operations across multiple US metropolitan zones. BYD exemplifies battery electric powertrain manufacturing at scale extending into autonomous vehicle partnerships.
| Leading Market Players |
|---|
| XPeng |
| Li Auto |
| Tesla |
| NIO |
| Lucid Motors |
| Waymo |
| Zoox |
| Rivian |
| BYD |
| Others |
Supply Flow & Price Mechanics
Lithium-iron-phosphate cell chemistry displacing nickel-cobalt-manganese formulations redraws procurement geography toward Chinese cathode production while collapsing pack-level costs for high-mileage autonomous fleet operators. This substitution simultaneously concentrates supply chain leverage in BYD and CATL manufacturing corridors and compresses pricing floors for robotaxi unit economics.
Pricing Analysis
Industrial OEM buyers anchor contract structures around guaranteed uptime service agreements with penalty clauses for availability shortfalls below 95 percent. Three-tier pricing stratifies across ASIL-D certified full-self-driving platforms, advanced driver-assistance systems with modular validation, and geofenced low-speed delivery configurations. Cost compression in sensor suites intensifies as solid-state lidar volumes scale, though permanent magnet motor supply constraints limit downstream price erosion. Fleet management operators exhibit highest price sensitivity due to 5-7 year contract lock-ins, while premium robotaxi services absorb hardware premiums for regulatory moat maintenance.
Supply Chain Analysis
Rare earth processing concentration in Chinese separation facilities creates chokepoint exposure for permanent magnet motor supply serving autonomous vehicle powertrain programs. Taiwan and South Korea anchor automotive electronics contract manufacturing for sensor fusion calibration modules. Neodymium-dysprosium-terbium feedstocks and lithium carbonate spodumene concentrates flow through Qingdao and Tianjin port complexes. Single-source vulnerability in lidar emitter components threatens tiered supplier ecosystems. Distribution runs through OEM captive assembly in Texas and Nevada, tiered supplier integration houses in Bavaria, and vertically integrated BYD manufacturing in Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment erects prohibitive barriers to cross-border platform replication. Municipal permitting density in Beijing and Phoenix creates switching costs that compound with each commercial deployment mile accumulated.
For Market Incumbents: Secure ASIL-D certification pathways across multiple jurisdictions before regulatory reciprocity negotiations crystallize competitive positions. Deepen backward integration into neural network training infrastructure to offset hyperscaler cloud dependency. Lock 7-year fleet service contracts with logistics operators to entrench against emerging sensor fusion specialists threatening modular supplier channels.
For New Entrants and Emerging Players: Differentiate on last-mile delivery van form factors below 3.5 tonnes where lighter homologation requirements bypass passenger-vehicle crash standards. Target India's production-linked incentive corridors for battery component manufacturing cost advantages. Penetrate campus and airport shuttle procurement through fixed-route operational design domains with deterministic validation requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed autonomy specialists holding MIIT certification in Beijing and Shenzhen but lacking US robotaxi permits. Long-term viability hinges on regulatory reciprocity progress rather than algorithmic breakthrough velocity. Watch NHTSA rulemaking on urban operational design domain guidelines as the inflection signal determining cross-border platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtakes secure LFP chemistry access for high-utilization fleet economics. |
| Software-Defined Vehicle Investment | End-to-end neural architectures compress development timelines while raising validation complexity thresholds. |
| Geographic Manufacturing Footprint | Texas and Nevada assembly anchors US robotaxi deployment corridors under NHTSA jurisdiction. |
| Charging Infrastructure Partnership | Megawatt charging standard adoption enables heavy-duty autonomous truck corridor electrification. |
| Platform Standardization | Unified sensor fusion stacks reduce calibration overhead across robotaxi and delivery van variants. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet operator logistics directors, and NHTSA regulatory affairs specialists converged on the working assumptions. Primary interviews with autonomous vehicle development executives and municipal transportation authority officials combined with secondary validation against MIIT certification databases, UNECE WP.29 regulatory filings, vehicle production registration data, and hyperscaler capex disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing across technology, end user, application, and powertrain segmentation dimensions.
Segmentation dimensions modeled span layered versus end-to-end neural architectures, fleet management versus ride-sharing contract structures, urban mobility versus last-mile delivery operational domains, and battery electric versus fuel cell electric powertrain configurations. CAGRs derive from installed base accumulation curves and replacement cycle dynamics throughout the forecast period. Neural network training data scale requirements and ASIL-D component certification timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued MIIT permit expansion and NHTSA rulemaking progression; material deviation in regulatory reciprocity negotiations would warrant model refresh. Forecasts reflect base-case assumptions regarding lithium-iron-phosphate cost curves and lidar volume manufacturing scale. Practitioners should keep alternative scenarios live as EU AI Act conformity assessment timelines and rare earth supply chain restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market