
 Autonomous Vehicle Sensor Market | 2026-2036
Autonomous Vehicle Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Vehicle Sensor Market Analysis
Commercial logistics is recalibrating the end-use mix for autonomous vehicle sensors as freight operators deploy automated long-haul corridors faster than consumer passenger adoption. Robert Bosch GmbH leverages its manufacturing scale across European and Asian production hubs to supply integrated radar-camera modules. Continental AG anchors its position through captive supply of ultrasonic arrays for parking and low-speed maneuvering. Hesai Technology Co. Ltd. dominates lidar shipments to Chinese robotaxi programs with cost-optimized solid-state designs.
Autonomous vehicle sensors comprise electromechanical and photonic devices that detect, measure, and interpret environmental stimuli including electromagnetic waves, acoustic pulses, and optical reflections to enable real-time perception and path planning. These components operate across wavelength bands from ultrasonic frequencies through millimeter-wave radar to near-infrared lidar, with fusion algorithms correlating heterogeneous data streams into unified object maps for control systems. Lidar commands premium positioning in full automation architectures where centimeter-range accuracy proves non-negotiable for urban navigation. Camera-based perception sustains the largest volume footprint across partial automation deployments where cost constraints favor mature CMOS supply chains. Radar differentiates through all-weather reliability, anchoring safety-critical functions where optical occlusion from precipitation or dust degrades alternative modalities.
NHTSA in the United States and MIIT in China impose divergent testing protocols for sensor redundancy, compelling suppliers to engineer dual-homologation platforms rather than single-design global products. ECE R79 and ISO 26262 functional safety standards shape European product development timelines and qualification costs for embedded sensor modules. Stakeholders must monitor regulatory fragmentation between federal permissiveness and state-level operational restrictions as the primary determinant of deployment geography and revenue concentration.
Market Dynamics
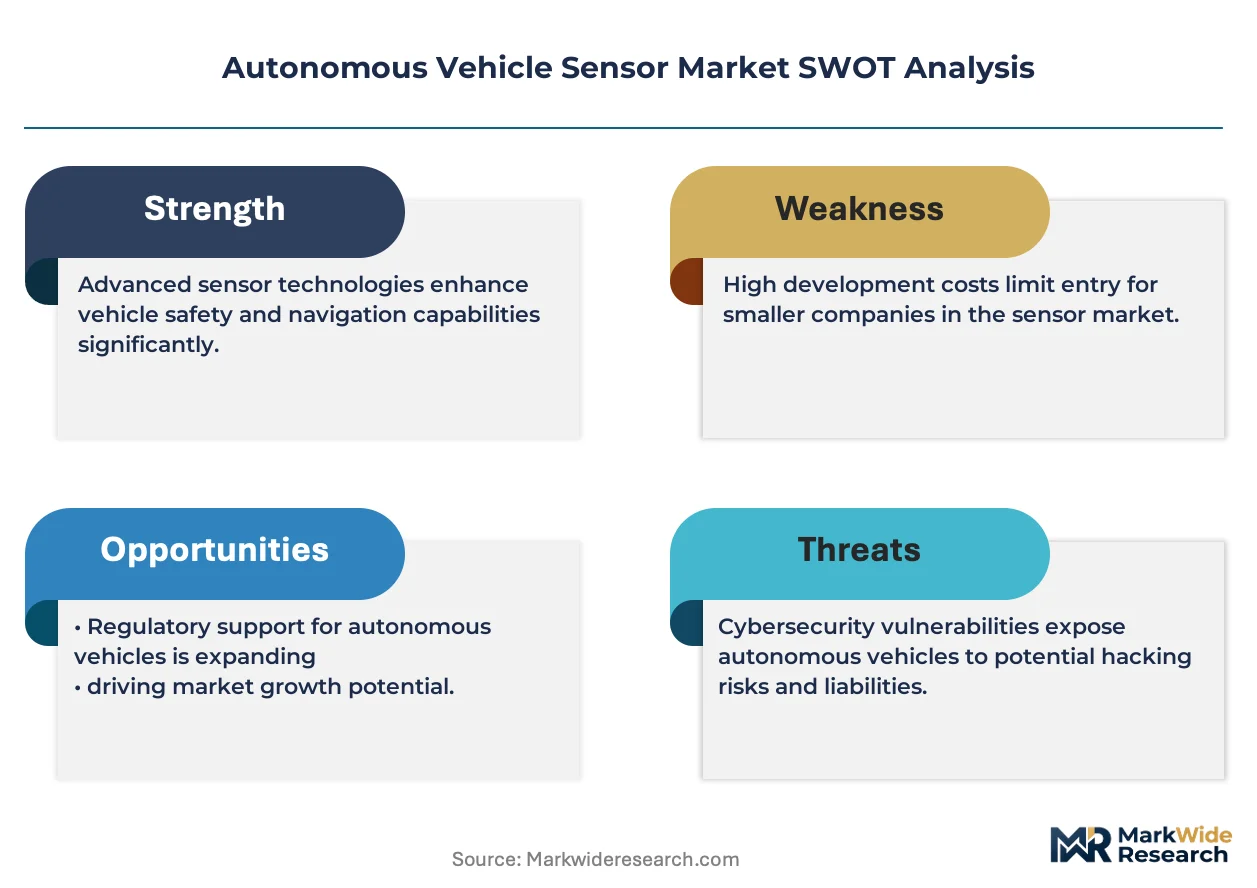
Multi-sensor fusion architectures are forcing suppliers to engineer integrated perception stacks rather than discrete component sales, compressing margins for standalone lidar and radar vendors while rewarding full-stack system integrators.
Growth Catalysts
- MIIT redundancy mandates:China's Ministry of Industry and Information Technology requires dual-homologated sensor suites on public-road autonomous vehicles, compelling fleet operators to procure backup perception layers.
- Freight corridor automation:Commercial logistics operators across the United States are deploying automated long-haul routes faster than consumer passenger adoption, concentrating sensor demand in heavy-duty vehicle specifications.
- Solid-state lidar maturation:Cost-optimized photonic designs are displacing mechanical scanning units in robotaxi programs, enabling volume procurement at price points viable for mass fleet deployment.
Market Restraints
- Silicon photonics input volatility:Indium phosphide and gallium arsenide substrate costs fluctuate with compound semiconductor foundry capacity constraints, squeezing lidar module gross margins.
- Dual-homologation engineering burden:NHTSA crashworthiness standards for steering-wheel-free vehicles diverge from MIIT testing protocols, forcing suppliers to maintain parallel qualification tracks rather than single global designs.
- Camera-based perception substitution:Advanced neural network inference on high-resolution CMOS arrays threatens to displace radar in partial automation tiers where weather resilience is deprioritized.
Strategic Opportunities
- Indian commercial vehicle retrofit:The country's national automotive regulator is drafting autonomous safety standards for existing truck fleets, creating aftermarket sensor installation demand absent in greenfield markets.
- ECE R79 adaptive steering integration:European functional safety standards for automated lane-keeping are mandating sensor fusion with steering actuators, opening embedded module supply contracts.
- Edge-to-cloud perception offloading:5G vehicle-to-infrastructure networks in South Korea and Germany enable split-computation architectures that reduce onboard sensor processing requirements.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates at Tier-1 suppliers, constraining startup lidar vendors from qualifying for OEM programs.
- Supply chain reconfiguration friction:Geofencing requirements under EU CSRD and US IRA domestic content rules are forcing sensor manufacturers to duplicate component sourcing across Atlantic and Pacific production footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Vehicle Sensor Market |
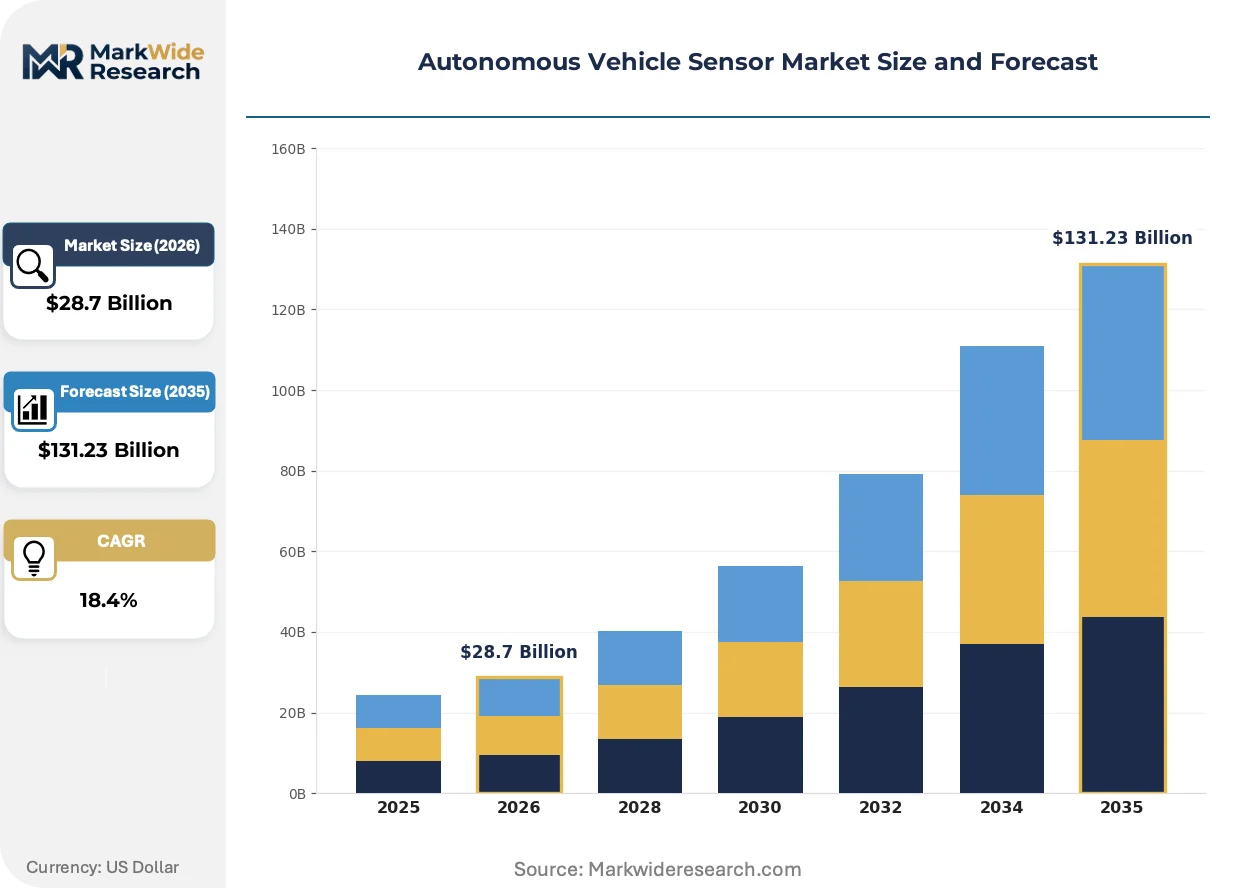
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $131.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Lidar, Radar, Camera, Ultrasonic Deployment Model: Embedded, Aftermarket, Mobile, Fixed Automation Level: Full Automation, Partial Automation, Highly Automated, Level 1 End User: OEMs, Fleet Operators, Ride-sharing, Logistics |
| Companies Covered | Continental AG, Robert Bosch GmbH, DENSO Corporation, Valeo SA, NXP Semiconductors, Aptiv PLC, Lumentum Holdings Inc., Hesai Technology Co. Ltd., Velodyne Lidar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Vehicle Sensor Market Emerging Trajectories
Perception hardware is converging with edge computing and connectivity infrastructure, dissolving traditional boundaries between sensing, processing, and transmission functions in vehicle architectures.
Silicon photonics is consolidating discrete optical components into monolithic chip-scale lidar engines. Robotaxi operators in the United States and China are adopting these designs for their thermal stability and vibration immunity. This consolidation is compressing the supplier base from mechanical assemblers to semiconductor foundry partners.
ECE R79 and ISO 26262 functional safety standards are tightening validation requirements for sensor fusion systems in Europe. Suppliers must now demonstrate correlated failure modes across radar, camera, and lidar inputs before receiving type approval. Heavy-duty freight applications face the longest certification timelines due to higher kinetic energy exposure.
Fleet procurement is consolidating around full-stack perception contracts rather than component sourcing. Logistics operators in Germany and the United States are demanding guaranteed mean-time-between-failures from integrated system vendors, displacing multi-source component bidding. This concentration favors suppliers with captive calibration and over-the-air update capabilities.
Autonomous Vehicle Sensor Market Segmentation
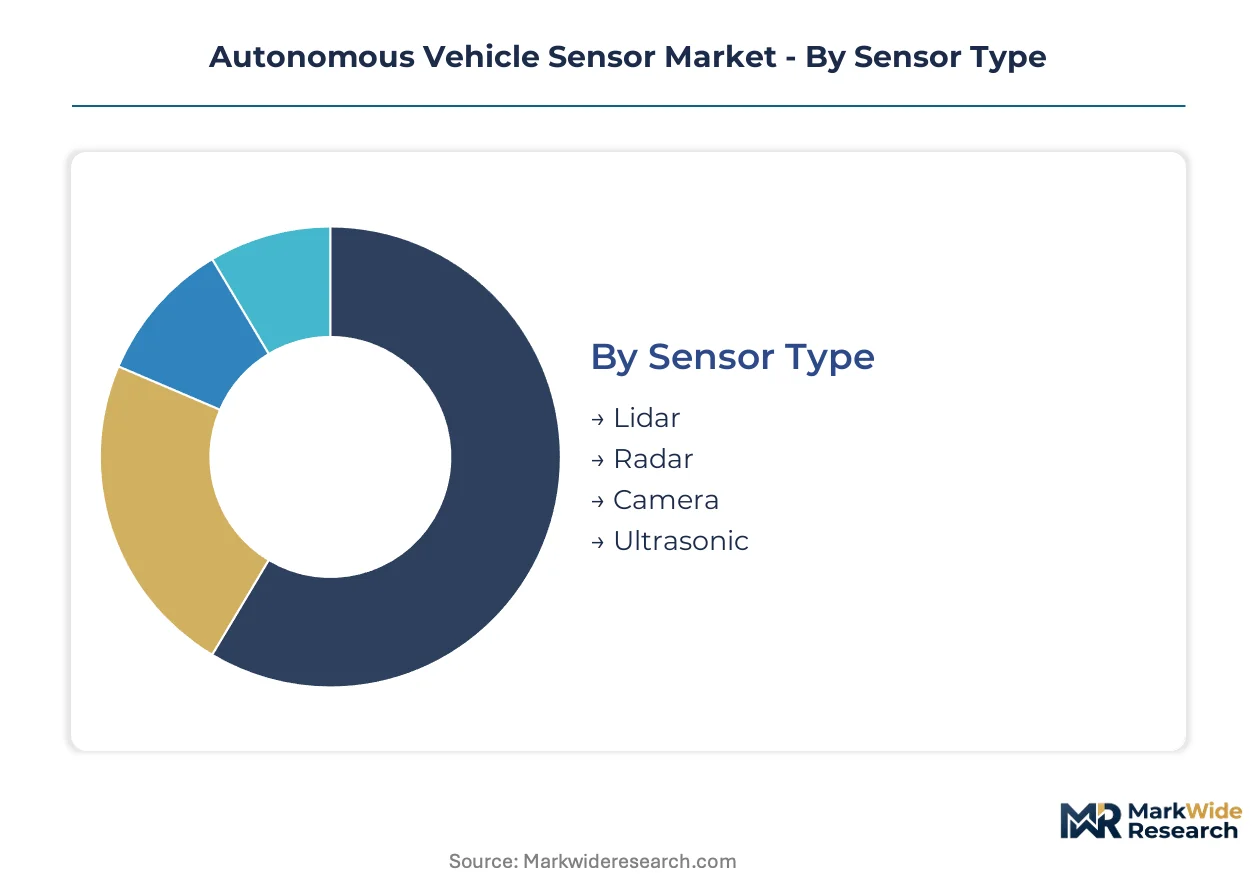
Sensor procurement patterns diverge sharply across automation tiers and deployment contexts, compelling suppliers to architect modular product families rather than universal platforms. Fleet operators prioritize mean-time-between-failures guarantees while OEMs negotiate embedded integration roadmaps spanning multiple vehicle generations.
Sensor Type:
Cost-performance tradeoffs dominate technology selection, with weather resilience and range precision determining specification tiers.
- Lidar:Solid-state photonic engines emit pulsed near-infrared light to construct centimeter-accurate 3D point clouds. Chinese robotaxi programs under MIIT mandates concentrate procurement here, though indium phosphide substrate volatility squeezes module margins.
- Radar:Millimeter-wave arrays penetrate precipitation and dust that blind optical alternatives. Long-haul freight corridors across the United States anchor demand for all-weather reliability in safety-critical braking and adaptive cruise functions.
- Camera:CMOS image sensors leverage mature consumer electronics supply chains for cost-constrained partial automation deployments.
- Ultrasonic:Short-range acoustic arrays dominate parking assistance and low-speed maneuvering where sub-meter precision suffices.
Volume sits with Camera; growth tilts toward Lidar.
Deployment Model:
Integration depth determines margin structure, with factory-installed systems commanding multi-year supply contracts against transactional aftermarket sales.
- Embedded:Sensors ship as original equipment with calibration and firmware update pipelines managed by OEMs. NHTSA crashworthiness standards for steering-wheel-free vehicles in the United States extend qualification timelines for these integrated architectures.
- Aftermarket:Retrofit installations target existing commercial fleets as India's national automotive regulator drafts autonomous safety standards for legacy trucks.
- Mobile:Portable units serve temporary mapping and validation applications in geofenced test zones.
- Fixed:Infrastructure-mounted sensors enable vehicle-to-infrastructure fusion in South Korean and German 5G corridor deployments.
Revenue concentrates in Embedded; aftermarket expansion accelerates most quickly in commercial vehicle retrofits.
Automation Level:
Functional safety certification burden scales with system autonomy, fragmenting supplier qualification tracks across ASIL tiers.
- Full Automation:Urban robotaxi architectures demand redundant lidar-radar-camera fusion with correlated failure mode analysis under ECE R79 and ISO 26262 ASIL-D standards.
- Highly Automated:Highway pilot systems split perception between onboard sensors and cloud offloading where 5G coverage permits.
- Partial Automation:Lane-keeping and adaptive cruise functions sustain the largest unit volumes through camera-radar combinations.
- Level 1:Standalone warning systems face substitution pressure from integrated advanced driver assistance suites.
Partial Automation carries current volume; Full Automation shows the steepest expansion trajectory.
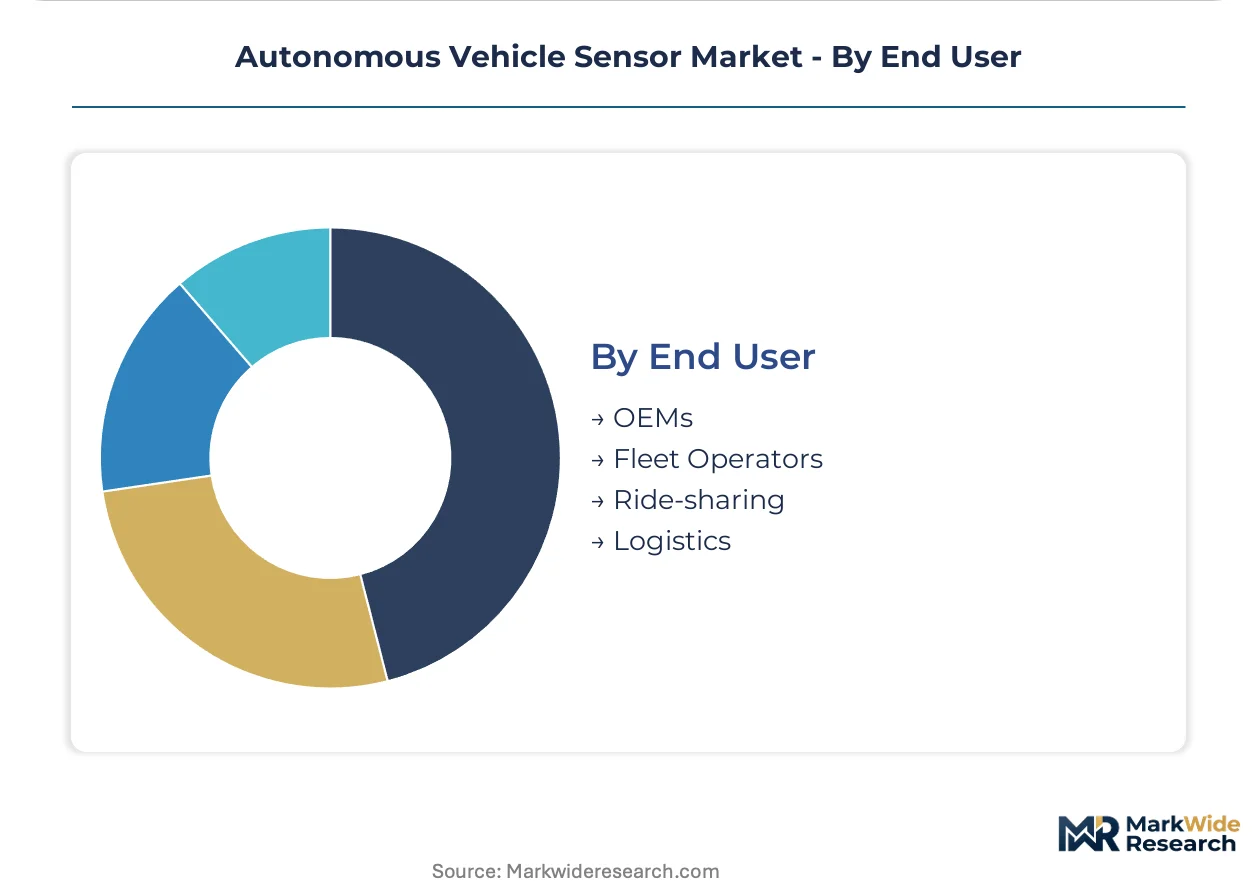
End User:
Procurement consolidation around full-stack perception contracts favors suppliers with captive calibration and over-the-air update infrastructure.
- Fleet Operators:Logistics providers across Germany and the United States demand guaranteed uptime from integrated system vendors, displacing multi-source component bidding. Heavy-duty specifications face extended certification timelines due to higher kinetic energy exposure.
- OEMs:Vehicle manufacturers negotiate embedded supply agreements spanning platform generations, with ECE R79 adaptive steering integration mandating sensor-actuator fusion modules.
- Ride-sharing:Robotaxi deployers in the United States and China consolidate procurement around solid-state lidar designs for thermal stability and vibration immunity.
- Logistics:Automated long-haul freight operators concentrate sensor demand in heavy-duty specifications with reinforced housings and extended temperature ranges.
Procurement volume clusters with OEMs; contract value expansion tilts toward Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Shanghai concentrate lidar module assembly, while Michigan's automated vehicle testing corridors attract sensor validation facilities. Tax incentives for semiconductor packaging in Penang and Dresden anchor radar component supply chains.
United States
Robotaxi fleet operators in Arizona and California accelerate procurement of solid-state lidar arrays for urban deployment. NHTSA crashworthiness standards for steering-wheel-free vehicles extend qualification timelines for integrated sensor architectures. The Detroit-Warren corridor hosts validation centers where Tier-1 suppliers test multi-sensor fusion systems for heavy-duty freight specifications.
China
Public-road autonomous vehicle programs under MIIT redundancy mandates drive dual-homologated sensor suite procurement. The Yangtze River Delta clusters solid-state lidar manufacturing around Shanghai and Suzhou foundries. Beijing-Tianjin-Hebei test zones concentrate robotaxi sensor calibration facilities serving domestic fleet operators.
Germany
ECE R79 adaptive steering integration mandates create embedded module supply contracts linking sensors to actuator systems. The Stuttgart region anchors ultrasonic array production for parking assistance systems. Bavaria's automated freight corridors along the A9 highway validate all-weather radar specifications for long-haul logistics.
Japan
METI-funded autonomous driving testbeds in Kanagawa and Aichi prefectures concentrate camera-radar fusion development. JIS standards for functional safety shape qualification protocols for embedded sensor modules. The Nagoya industrial corridor supplies CMOS image sensors leveraging consumer electronics manufacturing scale.
South Korea
5G vehicle-to-infrastructure networks in Sejong and Daegu enable edge-to-cloud perception offloading architectures. MFDS automotive safety guidelines influence sensor redundancy requirements for domestic OEM programs. The Pangyo cluster hosts startups developing millimeter-wave radar arrays for highway pilot systems.
Autonomous Vehicle Sensor Market Vendor Landscape
Top-tier vendors anchor integrated perception stacks, while component specialists compete on discrete module pricing. The supplier base stratifies between full-stack system integrators and standalone sensor manufacturers. German and Japanese conglomerates exemplify captive manufacturing archetypes, while Chinese photonics firms represent cost-optimized design houses. Capacity expansion and strategic partnerships dominate competitive moves as suppliers seek dual-homologation capabilities.
Among European-based conglomerates, Continental AG and Robert Bosch GmbH occupy positions reflecting integrated manufacturing scale, while Hesai Technology Co. Ltd. exemplifies the specialized photonics archetype serving fleet procurement programs. These three entities represent the dominant competitive formations: diversified industrial groups with captive component supply, and focused design houses optimizing for volume robotaxi deployment.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| DENSO Corporation |
| Valeo SA |
| NXP Semiconductors |
| Aptiv PLC |
| Lumentum Holdings Inc. |
| Hesai Technology Co. Ltd. |
| Velodyne Lidar Inc. |
| Others |
Supply Flow & Price Mechanics
MIIT-mandated dual-homologation requirements for Chinese robotaxi fleets are forcing lidar suppliers to engineer parallel qualification tracks rather than single global designs, compressing margins through duplicated engineering effort and fragmenting procurement scale across incompatible specification tiers.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent fleet deployment contracts from standard procurement cycles, with robotaxi operators in the United States and China paying premiums for accelerated delivery of solid-state lidar modules. Price differentiation hinges on ISO 26262 ASIL-D certification tier and volume commitment scale, with uncertified components trading at substantial discounts. Cost compression in mechanical scanning lidar is intensifying because silicon photonics displacement erodes residual demand. Fleet operators exhibit the highest price sensitivity due to per-unit procurement at thousand-vehicle scale, while OEM embedded programs tolerate premium pricing for multi-year supply security.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for embedded sensor modules, while specialized distributors serve aftermarket retrofit installers in emerging markets. Manufacturing concentrates in China, Germany, and Japan, with indium phosphide substrates, gallium arsenide wafers, and CMOS image sensors anchoring component dependencies. Single-source vulnerability in compound semiconductor foundry capacity poses structural risk, particularly for lidar photonic engines. Distribution runs through Tier-1 system integrators who bundle calibration and firmware update pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as dual-homologation engineering burdens and functional safety certification scarcity force subscale lidar vendors toward acquisition or exit.
For Market Incumbents: Hedge against silicon photonics substitution by securing captive semiconductor foundry partnerships in Taiwan and South Korea. Anchor margin defense through backward integration into indium phosphide substrate sourcing, reducing exposure to compound semiconductor spot market volatility. Accelerate ECE R79 qualification pipelines ahead of European adaptive steering mandates to lock out emerging competitors. For New Entrants and Emerging Players: Cloud-based perception software subscriptions offer a capital-light entry path around hardware certification barriers. Target India's commercial vehicle retrofit segment where autonomous safety standard drafting creates first-mover whitespace absent entrenched supplier relationships. Lead with over-the-air calibration services bundled with aftermarket sensor installation to bypass OEM embedded supply chain control. For Investors and Strategic Acquirers: The window for entry favors photonics design houses with MIIT-homologated products and established Chinese robotaxi supply relationships. Long-term viability rests on acquisition of ISO 26262 ASIL-D certification expertise concentrated at Tier-1 suppliers. Monitor NHTSA rulemaking on steering-wheel-free vehicle crashworthiness as the critical inflection signal for United States robotaxi sensor procurement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Homologation Platform Development | Parallel NHTSA and MIIT qualification tracks unlock access to the two largest robotaxi procurement markets. |
| Silicon Photonics Foundry Partnership | Monolithic chip-scale lidar engines reduce mechanical assembly cost and improve thermal stability for fleet deployment. |
| ISO 26262 ASIL-D Certification Investment | Functional safety qualification enables supply to OEM embedded programs with multi-year contract security. |
| Aftermarket Calibration Infrastructure Buildout | Over-the-air update capabilities differentiate full-stack vendors from component suppliers in fleet procurement. |
| Indian Commercial Vehicle Retrofit Entry | Draft autonomous safety standards for legacy truck fleets create regulatory-driven demand absent in greenfield markets. |
Methodological Framework
Multi-period observation of sensor procurement volumes, homologation timeline disclosures, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, robotaxi fleet operations managers, aftermarket distributors, and functional safety certification specialists. Secondary validation drew from NHTSA rulemaking dockets, MIIT public-road testing permits, ECE R79 implementation guidance, vehicle production databases, and SEC filings of listed sensor manufacturers. Bottom-up component shipment estimates triangulated against top-down fleet deployment projections.
Input-output matrices modeled sensor demand across automation level, vehicle class, deployment model, and regional regulatory cluster. CAGRs were derived from segment-level shipment trajectories and content-per-vehicle assumptions, cross-referenced against foundry capacity expansion announcements and fleet operator procurement disclosures. Industry-specific forecast inputs included robotaxi deployment schedules and freight corridor automation timelines.
The model holds under steady regulatory implementation schedules; deviation in NHTSA crashworthiness rulemaking timing or MIIT mandate enforcement intensity would shift revenue concentration between geographies. Forecasts reflect base-case assumptions regarding silicon photonics yield maturation and compound semiconductor substrate supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Canada Autonomous Navigation Market