
 Nordics Road Freight Transport Market | 2026-2036
Nordics Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Nordics Road Freight Transport Market Analytics
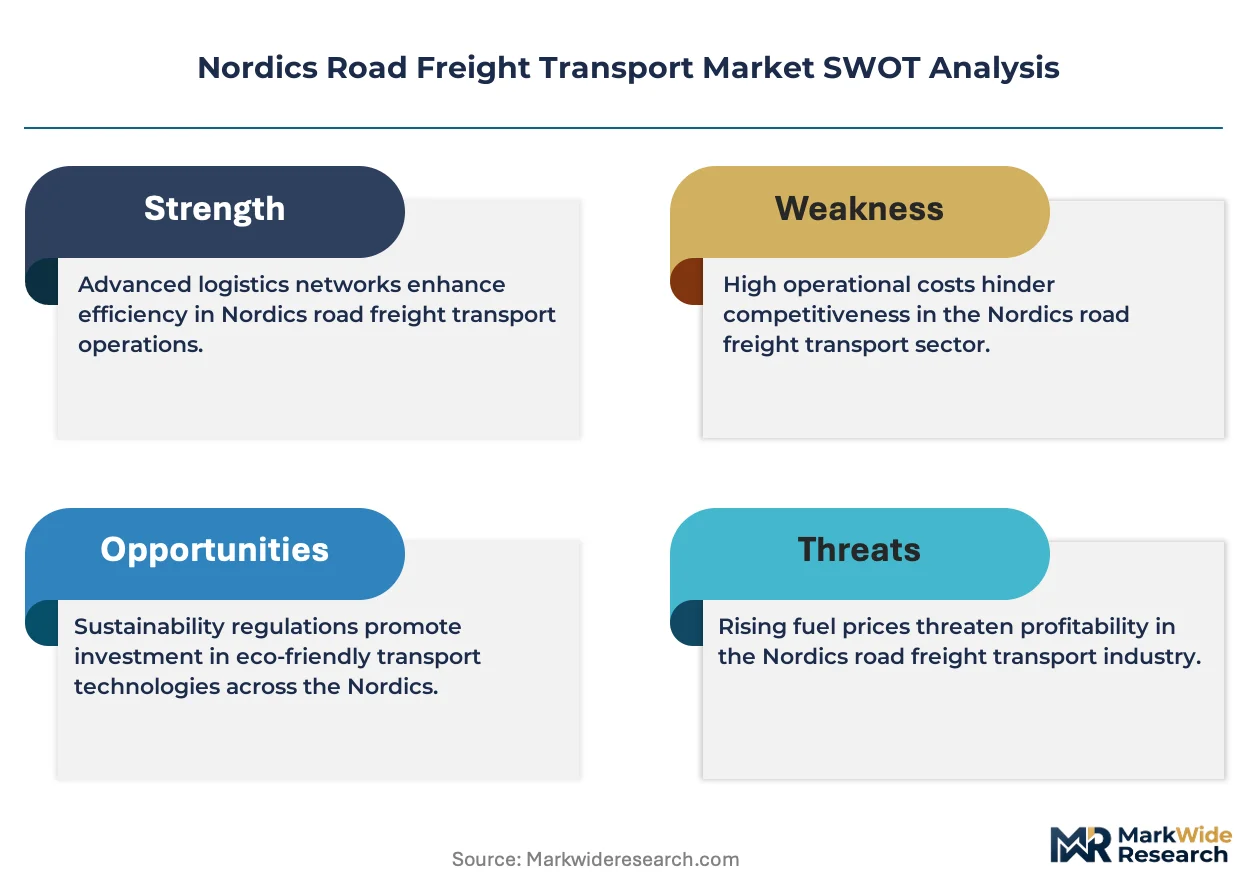
EU Green Deal compliance is consolidating the cost-of-entry calculus for Nordic road freight operators, raising capital requirements for zero-emission fleet certification and carbon reporting infrastructure. DSV A/S leverages its integrated logistics platform to sustain cross-border density across Denmark, Sweden, and Norway. DB Schenker anchors pharmaceutical cold chain corridors through temperature-controlled investments in the Øresund cluster. Kuehne + Nagel competes on intermodal rail-road coordination, reducing ferry dependency for Baltic-Scandinavian flows.
Nordics road freight transport encompasses the movement of goods by heavy commercial vehicles across Denmark, Finland, Iceland, Norway, and Sweden, utilizing diesel, biogas, battery-electric, and hydrogen fuel cell powertrains with gross vehicle weights typically ranging from 3.5 to 60 tonnes. Its primary purpose is to connect dispersed industrial production sites, Arctic port terminals, and urban consumption centers across vast territorial distances with limited rail penetration. Full truck load services dominate volume flows between pulp mills in northern Sweden and continental European export corridors, while temperature controlled segments capture disproportionate margin pools from Norwegian seafood and Danish pharmaceutical exports. Less than truck load networks concentrate around Copenhagen, Stockholm, and Oslo metropolitan zones, where outsourced logistics models are displacing captive fleet operations among mid-sized manufacturing end users.
Swedish Transport Agency regulations, Norwegian CO2 toll differentiation frameworks, and EU F-Gas Refrigeration standards collectively mandate telematics-enabled emissions verification and refrigerant leak monitoring across cross-border fleets. These requirements filter market access toward operators with certified workshop networks and real-time compliance dashboards. Stakeholders must monitor biogas refueling infrastructure buildout rates along TEN-T corridor extensions and assess battery-electric range adequacy for Arctic circle routes before committing to long-term fleet composition decisions.
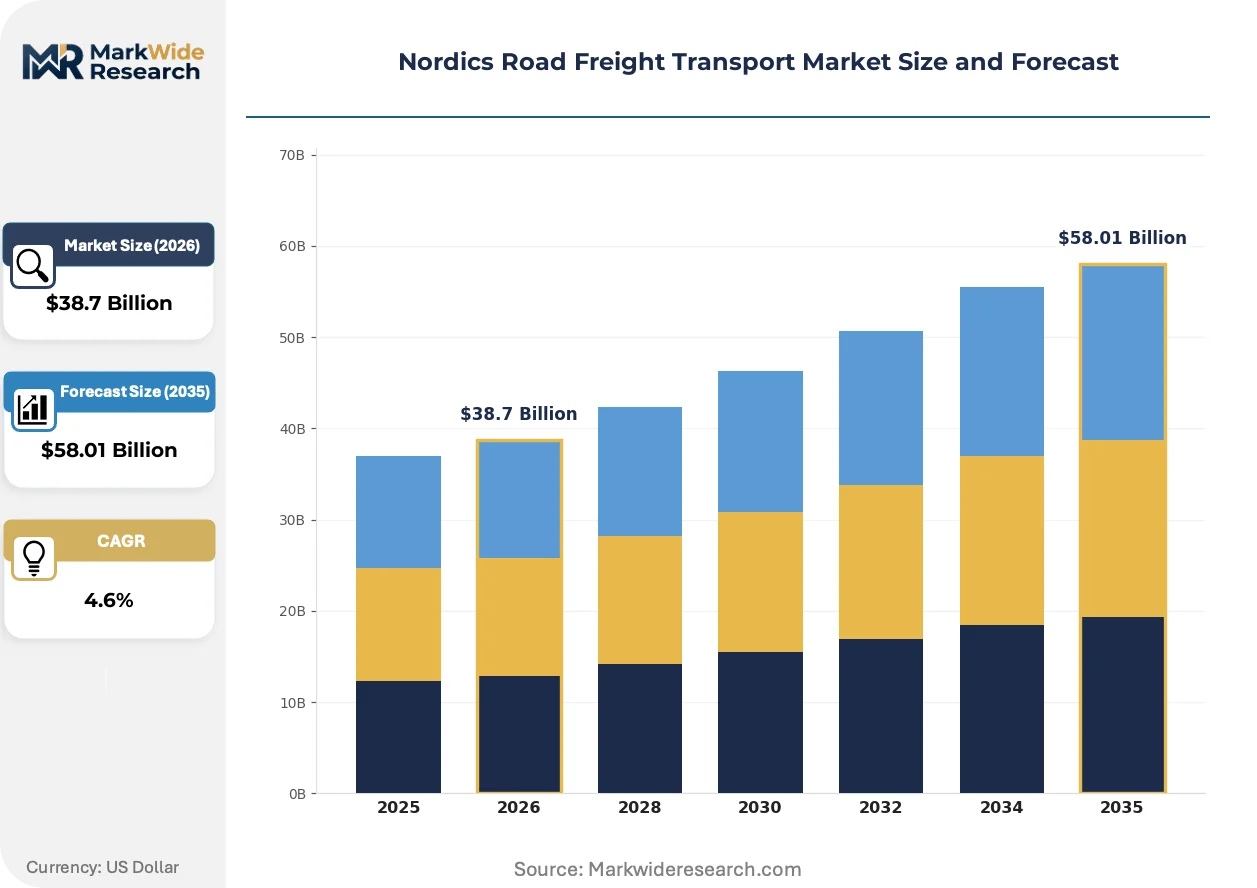
Market Dynamics
Norwegian CO2 toll differentiation frameworks and Swedish Transport Agency mandates are compressing fleet replacement cycles while biogas refueling infrastructure buildout along TEN-T corridors determines operator capital allocation priorities.
Growth Catalysts
- EU Green Deal compliance mandates:Zero-emission fleet certification requirements and carbon reporting infrastructure investments filter market access toward certified operators with real-time compliance dashboards.
- Danish pharmaceutical cold chain corridors:Temperature-controlled capacity across the Øresund region commands premium margins from biologics and vaccine distribution networks.
- Norwegian seafood export logistics:Fresh Atlantic salmon and Arctic cod shipments drive refrigerated truck deployment with strict temperature integrity protocols.
Market Restraints
- Biogas supply concentration:Limited refueling station density along Arctic Circle routes constrains fleet composition decisions for long-haul operators.
- Battery-electric range inadequacy:Sub-zero temperature performance degradation and charging infrastructure gaps impede full electrification of northern Sweden pulp mill corridors.
- F-Gas Refrigeration compliance costs:EU leak monitoring mandates and refrigerant phase-down schedules impose capital burdens on temperature-controlled fleet operators.
Strategic Opportunities
- Finnish Arctic port connectivity:Kemi and Oulu terminal expansions create intermodal rail-road coordination potential for Baltic-Scandinavian freight flows.
- Hydrogen fuel cell convergence:Heavy-duty long-haul segments combine electrolysis infrastructure with fuel cell powertrains for 60-tonne gross weight applications.
- Iceland circular economy logistics:Aluminum smelter byproduct transport and geothermal energy integration offer captive fleet electrification models.
Industry Challenges
- Telematics integration complexity:Cross-border emissions verification systems require real-time data harmonization across Swedish, Norwegian, and Danish regulatory platforms.
- Certified technician scarcity:Biogas and hydrogen fuel cell maintenance competencies lag fleet renewal timelines in remote northern territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordics Road Freight Transport Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Temperature Controlled, Intermodal Transport Vehicle Type: Flatbed Trucks, Refrigerated Trucks, Tankers, Box Trucks End User: Manufacturing, Retail, Construction, Food & Beverage Delivery Model: Same-Day Delivery, Scheduled Delivery, Bulk Delivery, Outsourced Logistics |
| Companies Covered | Kuehne + Nagel, A.P. Moller - Maersk, DSV A/S, Rhenus Group, DB Schenker, DHL Group, Girteka, DACHSER, DFDS Logistics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordics Road Freight Transport Market Evolving Landscape
Digital freight platforms and alternative drivetrain technologies are restructuring how Nordic operators match capacity with cargo flows across fragmented territorial distances and stringent environmental compliance frameworks.
Telematics-enabled emissions verification systems are unifying cross-border fleet management for operators serving Swedish pulp mills and Norwegian seafood processors. Danish logistics providers deploy these platforms fastest, integrating real-time carbon reporting with route optimization. The technology is unifying previously siloed national compliance systems into single operational dashboards.
Norwegian CO2-based road toll differentiation frameworks compress diesel truck economic viability while accelerating biogas and electric drivetrain adoption. Fleet operators face stepped toll charges based on verified emissions profiles at each border crossing. Temperature-controlled segments absorb compliance costs most readily through premium pricing power.
Consolidated procurement of outsourced logistics services displaces captive fleet operations among mid-sized manufacturing end users in Copenhagen, Stockholm, and Oslo metropolitan zones. Third-party operators capture volume through integrated platform offerings. Danish pharmaceutical manufacturers demonstrate this shift most visibly, abandoning in-house distribution for certified cold chain specialists.
Nordics Road Freight Transport Market Segmentation
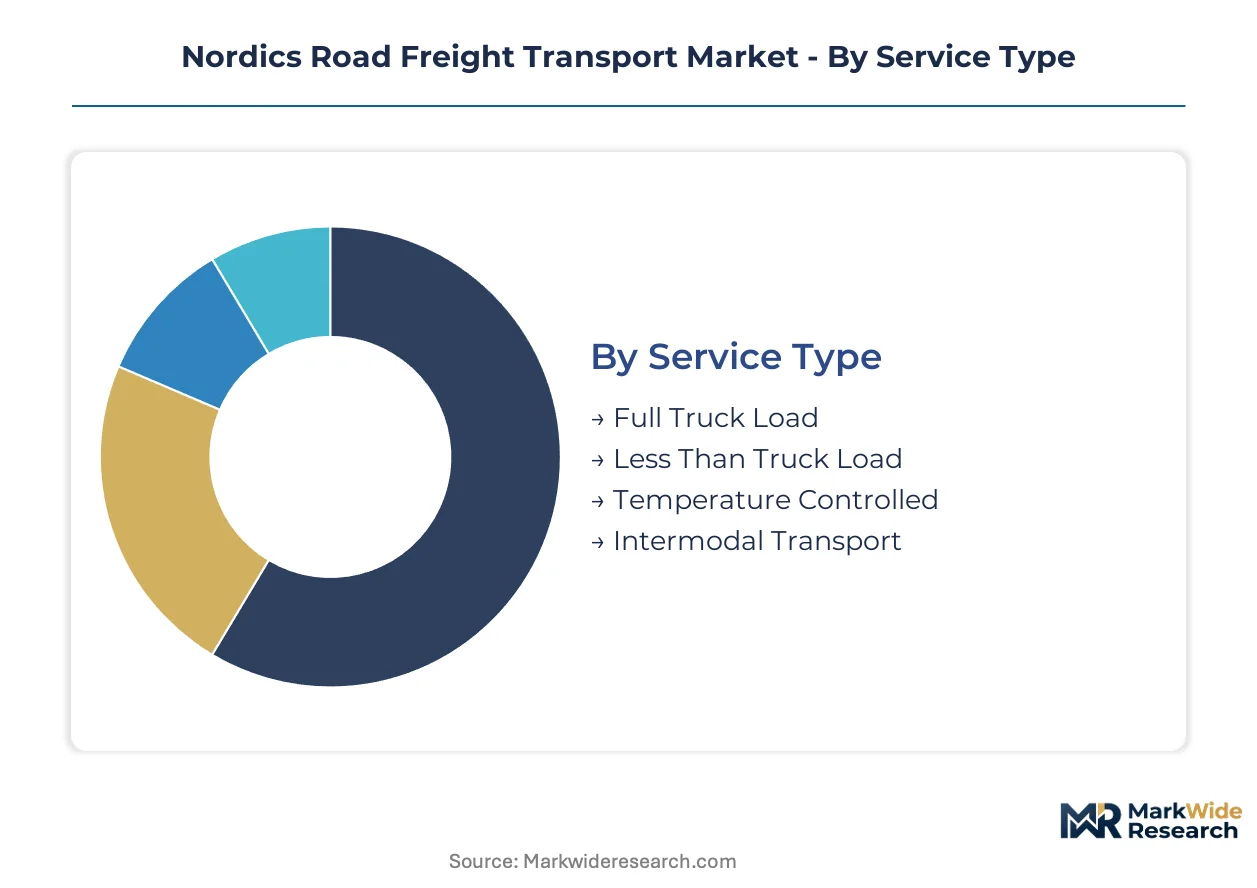
Fleet composition decisions across Denmark, Norway, and Sweden hinge on precise segment alignment with cargo characteristics and regulatory compliance tiers. Operators matching service type to vehicle specifications capture margin premiums while avoiding stranded asset risk from mismatched capacity.
Service Type:
Upgrade cycles for refrigerated and intermodal assets outpace standard fleet replacement timelines as EU Green Deal mandates force emissions-verified equipment turnover.
- Full Truck Load:Dedicated vehicle capacity moves pulp from northern Sweden to continental export corridors and seafood from Norwegian processing plants to Arctic ports. Demand concentrates along Oslo-Stockholm-Copenhagen axes where manufacturing shippers prioritize transit time reliability over cost minimization.
- Temperature Controlled:Refrigerated units with telematics-enabled leak monitoring serve Danish pharmaceutical cold chains and Norwegian fresh salmon distribution. Biologics manufacturers in the Øresund cluster absorb compliance cost premiums through strict temperature integrity protocols.
- Less Than Truck Load:Consolidated shipments from multiple shippers fill urban delivery routes around metropolitan Stockholm and Oslo zones. Retail networks leverage third-party platforms to displace captive fleet operations.
- Intermodal Transport:Rail-road coordination through Finnish Arctic ports reduces ferry dependency for Baltic-Scandinavian freight flows.
Volume placements concentrate in Full Truck Load; the faster expansion belongs to Temperature Controlled.
Vehicle Type:
Capital allocation tilts toward refrigerated and tanker configurations as food safety and chemical transport regulations tighten certification requirements.
- Refrigerated Trucks:Multi-temperature zone units with F-Gas compliant refrigeration systems handle Norwegian seafood and Danish vaccine shipments. Sub-zero Arctic performance requirements filter procurement toward certified workshop networks with real-time monitoring dashboards.
- Flatbed Trucks:Open-deck configurations transport construction materials and forestry products across vast Swedish territorial distances with limited rail penetration.
- Tankers:Specialized liquid cargo vehicles serve chemical processing clusters and fuel distribution networks.
- Box Trucks:Enclosed dry freight units dominate urban parcel consolidation and retail replenishment cycles.
Refrigerated Trucks command the steepest capital investment per unit; Flatbed Trucks maintain the broadest geographic deployment.
End User:
Customer procurement patterns separate captive fleet retention from outsourced logistics adoption based on shipment predictability and compliance complexity.
- Food & Beverage:Fresh grocery logistics and processed seafood exports drive refrigerated truck deployment with strict cold chain protocols. Swedish retail distribution networks expanding temperature-controlled capacity capture margin premiums from quality-sensitive categories.
- Manufacturing:Industrial production sites in Denmark and Sweden rely on scheduled delivery windows for just-in-line component flows.
- Retail:Omnichannel fulfillment requirements compress delivery timeframes for Copenhagen and Stockholm metropolitan zones.
- Construction:Project-based material flows demand flexible capacity scaling through outsourced logistics platforms.
Food & Beverage generates the densest refrigerated asset utilization; Manufacturing anchors the highest contract renewal rates.
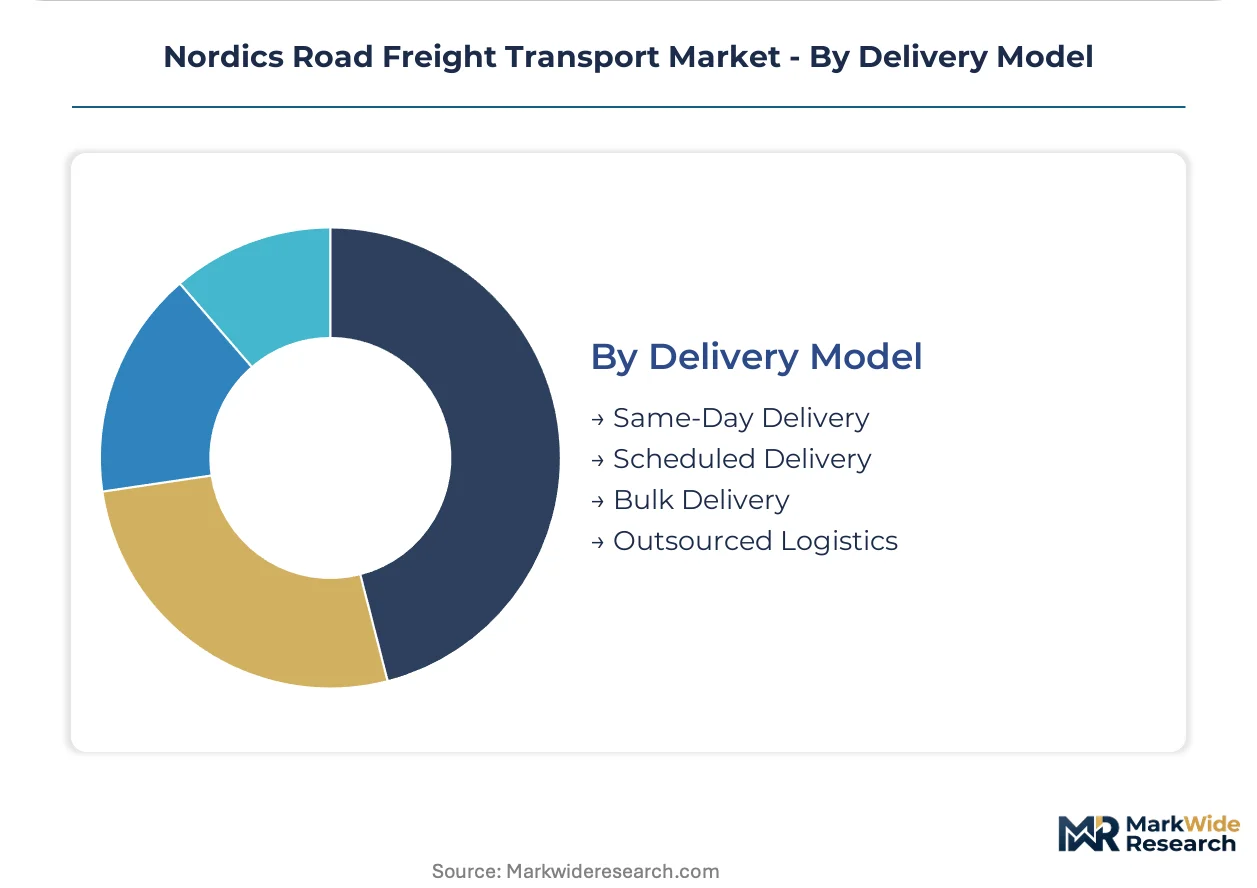
Delivery Model:
Service tier differentiation separates premium responsiveness from cost-optimized scheduling based on cargo value density and perishability windows.
- Scheduled Delivery:Fixed-route operations with telematics-verified emissions profiles serve manufacturing supply chains with predictable replenishment cycles. Norwegian CO2 toll differentiation frameworks reward pre-planned routing optimization.
- Outsourced Logistics:Third-party operators capture mid-sized manufacturing volume through integrated platform offerings displacing captive fleet operations.
- Same-Day Delivery:Expedited urban services concentrate around pharmaceutical and high-value retail corridors.
- Bulk Delivery:Large-volume shipments of raw materials and commodities move through dedicated contract arrangements.
Scheduled Delivery holds the largest contracted volume base; Outsourced Logistics is climbing the fastest as mid-market manufacturers abandon in-house distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Øresund region's integrated logistics zone concentrates pharmaceutical cold chain investment across Copenhagen and Malmö metropolitan clusters. This cross-border economic corridor channels premium freight volumes through coordinated customs and emissions verification systems.
Sweden
Northern pulp mill corridors drive dedicated full truck load capacity between Umeå and Gothenburg export terminals. The Swedish Transport Agency mandates telematics-enabled emissions verification for all cross-border fleet operations. Stockholm metropolitan consolidation centers are displacing captive manufacturing fleets with outsourced third-party logistics platforms.
Norway
Atlantic salmon and Arctic cod exports require strict temperature-controlled trucking from processing plants in Bergen and Tromsø to port terminals. CO2-based road toll differentiation frameworks compress diesel vehicle economic viability at each border crossing. Biogas refueling infrastructure buildout along E6 and E39 corridors determines fleet composition decisions for long-haul operators.
Denmark
Øresund pharmaceutical manufacturers absorb premium pricing for certified cold chain capacity serving biologics distribution networks. EU F-Gas Refrigeration standards mandate real-time leak monitoring across refrigerated fleet assets. Copenhagen metropolitan logistics zones concentrate less than truck load consolidation for retail omnichannel fulfillment.
Finland
Kemi and Oulu Arctic port expansions create intermodal rail-road coordination potential for Baltic-Scandinavian freight flows. National transport infrastructure programs prioritize TEN-T corridor extensions connecting northern terminals to continental European markets. Tampere industrial clusters generate manufacturing component flows requiring scheduled delivery reliability.
Iceland
Aluminum smelter byproduct transport and geothermal energy integration offer captive fleet electrification models for heavy industrial logistics. The island's circular economy waste streams require specialized tanker and bulk capacity between Reykjavik processing zones and port facilities. Limited domestic market scale concentrates operator specialization on export corridor efficiency.
Nordics Road Freight Transport Market Competitive Landscape
Danish and Swedish operators anchor one tier; German and Swiss logistics specialists hold cross-border coordination capabilities. The market structures around integrated platform providers with certified compliance infrastructure and niche cold chain specialists with temperature-controlled asset concentrations. Three archetypes dominate: integrated multimodal platforms, pharmaceutical cold chain specialists, and regional LTL consolidators. Competitive positioning hardens through M&A activity capturing outsourced manufacturing volumes and biogas fleet certification investments filtering market access.
Within the integrated platform tier, DSV A/S and DB Schenker represent archetypes of cross-border density maintenance through compliance-certified fleet networks. Kuehne + Nagel occupies a position emphasizing rail-road intermodal coordination to reduce ferry dependency. These operators exemplify how real-time emissions verification dashboards and certified workshop networks filter sustainable competitive position in a market where EU Green Deal mandates raise capital requirements for zero-emission fleet certification.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| A.P. Moller - Maersk |
| DSV A/S |
| Rhenus Group |
| DB Schenker |
| DHL Group |
| Girteka |
| DACHSER |
| DFDS Logistics |
| Others |
Value Network & Pricing Analysis
Diesel and biogas price indices cascade through Nordic road freight tiers, compressing margins on standard haulage while amplifying premiums for EU Green Deal-certified zero-emission capacity. Norwegian CO2 toll differentiation and Swedish Transport Agency mandates stratify pricing by emissions verification tier, rewarding pre-committed contract volumes with predictable cost structures.
Pricing Analysis
Short lead-time premiums for pharmaceutical cold chain capacity run 15-25% above scheduled contract rates, while spot market diesel trucking absorbs toll-induced cost compression. Three-tier pricing structure across premium certified-zero-emission, standard biogas-compliant, and economy diesel-exposed segments separates DSV A/S and DB Schenker offerings from regional competitors. Pricing pressure stems from F-Gas Refrigeration compliance capital burdens on refrigerated fleet operators. Food and beverage exporters show highest price sensitivity; Danish biologics manufacturers demonstrate lowest sensitivity due to temperature integrity requirements.
Supply Chain Analysis
Swedish Transport Agency domestic-content mandates for certified workshop networks reshape sourcing toward national telematics providers and emissions verification platforms. Vehicle and equipment supply concentrates in Germany, Sweden, and Denmark; biogas fuel supply draws from Norwegian and Finnish agricultural waste processing clusters. Raw material dependencies include steel for chassis manufacturing, lithium-ion battery cells for electric drivetrains, and refrigerant gases for temperature-controlled units. Single-source vulnerability runs through German axle and transmission suppliers for heavy-duty Arctic applications. Distribution runs through Copenhagen-Stockholm-Oslo metropolitan consolidation centers with cross-border rail-road coordination at Finnish Arctic ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified zero-emission fleet capacity constraints prop pricing premiums as EU Green Deal compliance filters market access toward operators with real-time emissions dashboards and biogas refueling network coverage.
For Market Incumbents: Deploy certified workshop network expansion as the primary lever against emerging digital freight platform entrants. Consolidate cross-border density through M&A capture of mid-sized manufacturing outsourced logistics volumes in Stockholm and Oslo metropolitan zones. Anchor defensive positioning with backward integration into biogas refueling infrastructure along TEN-T corridor extensions, neutralizing fuel supply concentration risk from Norwegian agricultural processor dominance. For New Entrants and Emerging Players: Digital freight matching platforms offer the lowest barrier entry route into less than truck load consolidation serving Copenhagen retail omnichannel networks. White-space targets concentrate on Finnish Arctic port intermodal coordination for Baltic-Scandinavian flows and Icelandic aluminum smelter captive fleet electrification models. Pursue partnership-based go-to-market with established biogas station operators to bypass stranded asset risk from infrastructure buildout timing uncertainty. For Investors and Strategic Acquirers: The window for entry favors pharmaceutical cold chain specialists with Øresund region temperature-controlled asset concentrations and certified EU F-Gas Refrigeration compliance infrastructure. Long-term viability hinges on fleet composition flexibility accommodating hydrogen fuel cell convergence for 60-tonne Arctic corridor applications. Monitor biogas refueling station density buildout rates along E6 and E39 corridors as inflection indicator for incumbent competitive position stability.| Strategic Initiative | Industry Significance |
|---|---|
| Biogas Fleet Certification Investment | EU Green Deal compliance filters market access toward operators with real-time emissions dashboards and certified workshop networks. |
| Arctic Port Intermodal Coordination | Finnish Kemi and Oulu terminal expansions reduce ferry dependency for Baltic-Scandinavian freight flows through rail-road integration. |
| Pharmaceutical Cold Chain Specialization | Danish Øresund biologics manufacturers absorb premium pricing for temperature-controlled capacity with F-Gas leak monitoring compliance. |
| Hydrogen Fuel Cell Pilot Deployment | Heavy-duty long-haul segments combine electrolysis infrastructure with 60-tonne fuel cell powertrains for Arctic circle route viability. |
| Telematics Platform Integration | Cross-border emissions verification unifies Swedish, Norwegian, and Danish regulatory compliance into single operational dashboards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Nordic road freight transport analysis. Primary interviews with fleet operations directors, logistics procurement managers at Danish pharmaceutical manufacturers, Swedish pulp mill supply chain leads, Norwegian seafood export coordinators, and biogas infrastructure developers combined with secondary validation from Swedish Transport Agency emissions databases, Norwegian Public Roads Administration toll frameworks, EU TEN-T corridor investment reports, and refrigerated vehicle registration statistics. Bottom-up service type segmentation and top-down regional GDP-trade flow correlation established triangulation integrity.
Data-stream reconciliation across vehicle registration databases, fuel consumption statistics, and cross-border freight volume indices shaped the analytical framework. Segmentation dimensions modeled include service type, vehicle configuration, end-use industry, and delivery model across the projection horizon. CAGRs derived from historical fleet replacement cycle analysis correlated with regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated biogas refueling station buildout schedules and battery-electric range performance degradation curves for sub-zero Arctic conditions.
The model holds under stable EU Green Deal implementation timelines and continued Norwegian CO2 toll differentiation enforcement; deviation in hydrogen infrastructure investment acceleration or biogas feedstock supply disruption would shift fleet composition trajectories and competitive positioning outcomes. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through rates and outsourced logistics adoption curves among mid-sized manufacturing end users. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Europe Customs Brokerage Market