
 Africa Autonomous Navigation Market | 2026-2036
Africa Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Autonomous Navigation Market Analytics
Modular sensor packages are restructuring buyer choice across Africa's autonomous navigation sector. Airobotics Ltd. leverages drone-based inspection modules for mining site surveys in Southern Africa. TomTom N.V. anchors high-definition mapping services for ground vehicle fleets operating on the continent's variable road infrastructure. DJI Technology Co., Ltd. competes through agricultural UAV platforms calibrated for precision spraying across East African farmlands.
Autonomous navigation denotes self-directed positioning and path-planning systems integrating Lidar point clouds, radar returns, GPS coordinates, and camera feeds to enable vehicle operation without human intervention across unstructured terrain. These systems fuse multi-spectral sensor inputs through Kalman filtering to maintain localization accuracy within centimeter-scale tolerances for commercial and industrial mobility. Camera Systems currently dominate hardware deployment due to lower unit costs and mature supply chains serving African fleet operators. Edge Computing architectures represent the fastest-expanding deployment mode as mining and logistics clients prioritize real-time decision latency over cloud bandwidth constraints in remote operational zones.
South Africa's National Regulator for Compulsory Specifications and the country's central transport authority enforce equipment homologation standards that filter which sensor configurations enter commercial service. ISO 26262 functional safety protocols and IEC 61508 reliability benchmarks further constrain system architecture choices for vendors targeting African mining and public transport contracts. Stakeholders must monitor how certification timelines and local content requirements evolve across jurisdictions with divergent technical enforcement capacities.
Market Dynamics
Sensor fusion architectures are compressing procurement cycles across Africa's autonomous navigation sector as mining operators demand centimeter-scale localization without cloud dependency. This technical imperative is restructuring vendor selection criteria and deployment timelines continent-wide.
Growth Catalysts
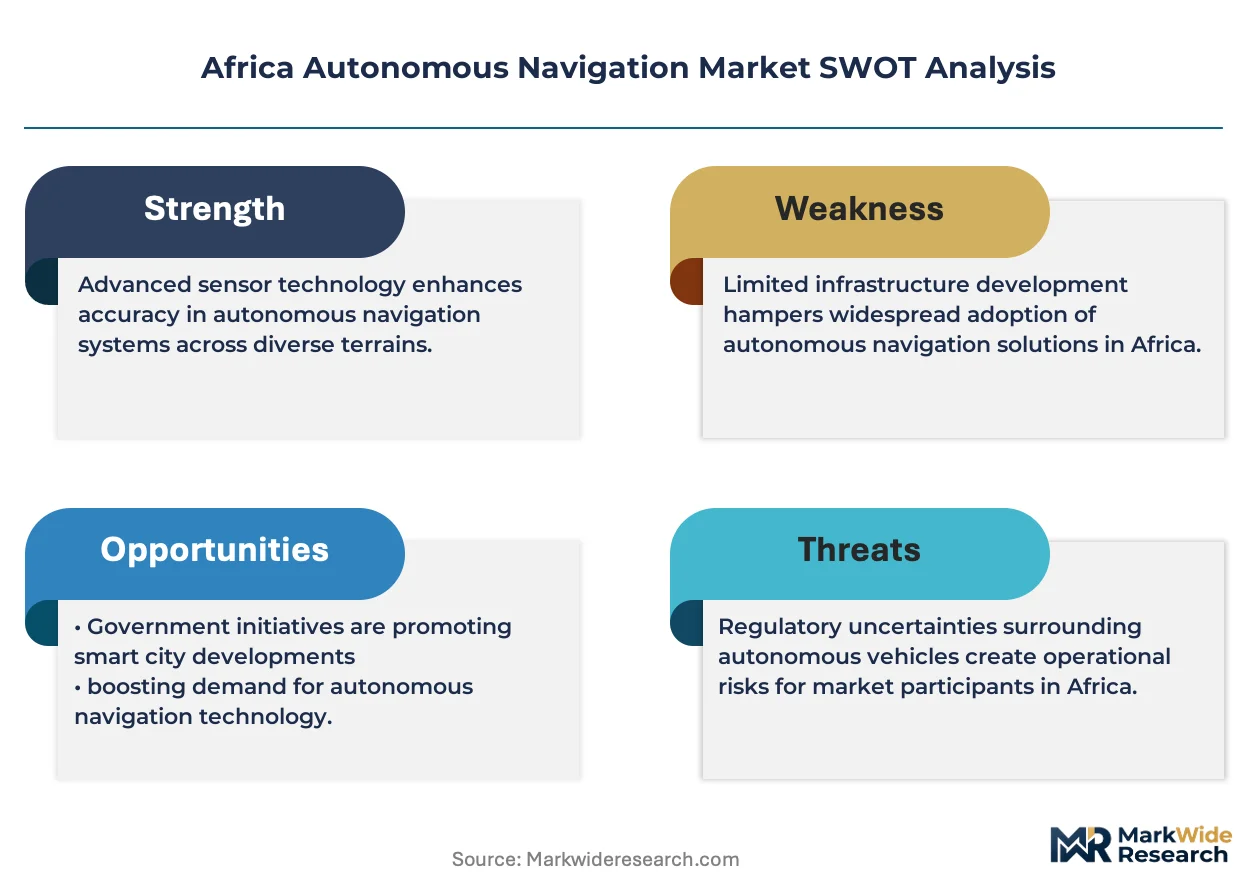
- Rising labor costs in extractive industries:South African platinum and gold mining corridors face wage pressure and safety compliance mandates. Autonomous haulage fleets reduce workforce exposure to hazardous terrain while maintaining throughput.
- ISO 26262 functional safety protocols:Equipment homologation standards enforced by South Africa's National Regulator for Compulsory Specifications filter sensor configurations entering commercial service. Vendors aligning with these benchmarks secure preferential procurement access.
- Edge Computing deployment:Mining and logistics clients prioritize real-time decision latency over cloud bandwidth constraints. Kalman-filtered multi-spectral fusion at the vehicle level enables operation in remote zones with intermittent connectivity.
Market Restraints
- Lidar sensor cost volatility:Solid-state and mechanical Lidar units remain capital-intensive relative to camera systems. African fleet operators with constrained capex budgets delay full sensor-stack upgrades.
- Supply concentration in Asian component manufacturing:Critical sensor modules and edge processing units source predominantly from East Asian foundries. Geopolitical friction or logistics disruption propagates procurement risk across Southern African mining networks.
- IEC 61508 reliability certification timelines:Extended validation periods for safety-critical navigation systems delay revenue recognition. Vendors face working capital pressure during protracted homologation cycles.
Strategic Opportunities
- Underpenetrated East African agricultural corridors:Precision spraying and crop monitoring applications in Kenya and Tanzania remain nascent. UAV platforms calibrated for smallholder farm geometries represent deployable white space.
- Dual-use defense-civilian navigation stacks:Military-grade sensor fusion technologies are migrating to commercial mining and logistics contracts. Vendors with defense heritage leverage hardened architectures for civilian certification pathways.
- Public-private infrastructure partnerships:Variable road conditions across Botswana and Namibia create demand for high-definition mapping subscriptions. TomTom N.V. and regional geospatial providers capture recurring revenue through fleet-scale data licensing.
Industry Challenges
- Kalman filtering and sensor fusion expertise scarcity:The specialized skill set integrating Lidar point clouds with radar returns and GPS coordinates concentrates in Johannesburg and Cape Town technology clusters. Mining operators compete for limited localization engineering talent.
- Legacy fleet integration complexity:Retrofitting autonomous navigation stacks onto existing haul trucks and logistics vehicles requires mechanical and electrical system reconciliation. Brownfield deployments demand extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Autonomous Navigation Market |
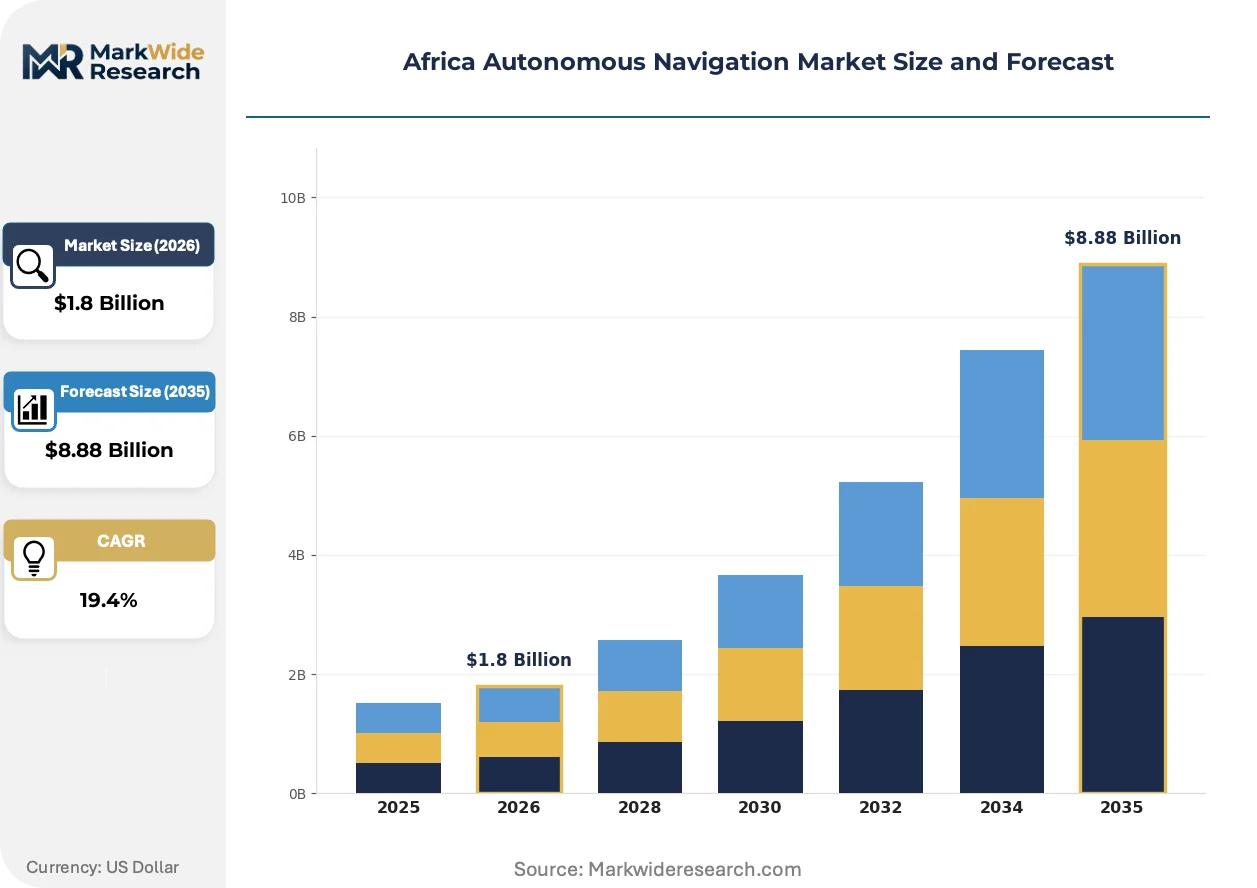
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lidar, Radar, GPS, Camera Systems End User: Logistics, Public Transport, Mining, Agriculture Application: Delivery Services, Personal Mobility, Fleet Management, Road Safety Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Uber Technologies, Inc., Airobotics Ltd., Waymo LLC, Safran, TomTom N.V., Tesla, Inc., DJI Technology Co., Ltd., L3Harris Technologies Inc., NVIDIA Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Autonomous Navigation Market Evolving Landscape
Multi-spectral sensor fusion is compressing the performance gap between premium and mid-tier navigation systems. Three convergent developments are restructuring competitive positioning across hardware, software, and service layers.
Sensor fusion middleware is unifying disparate Lidar, radar, camera, and GPS inputs through standardized APIs. Mining fleet operators in South Africa's Bushveld Complex are adopting these platforms at accelerating velocity. The technology is unifying previously siloed data streams, enabling single-vendor accountability for localization accuracy while reducing subsystem integration overhead.
South Africa's National Regulator for Compulsory Specifications has tightened equipment certification standards for autonomous ground vehicles operating in public-private transport corridors. Industrial consequence includes mandatory third-party validation of functional safety claims. Mining contractors in the platinum belt are responding by pre-certifying sensor configurations during procurement rather than post-deployment.
Site-based performance contracting is displacing equipment-centric sales models in Botswana's diamond mining regions. Autonomous navigation vendors now guarantee haul-cycle efficiency metrics rather than hardware specifications. This shift concentrates vendor risk in operational outcomes while transferring maintenance liability from mine operators to technology suppliers.
Africa Autonomous Navigation Market Segmentation
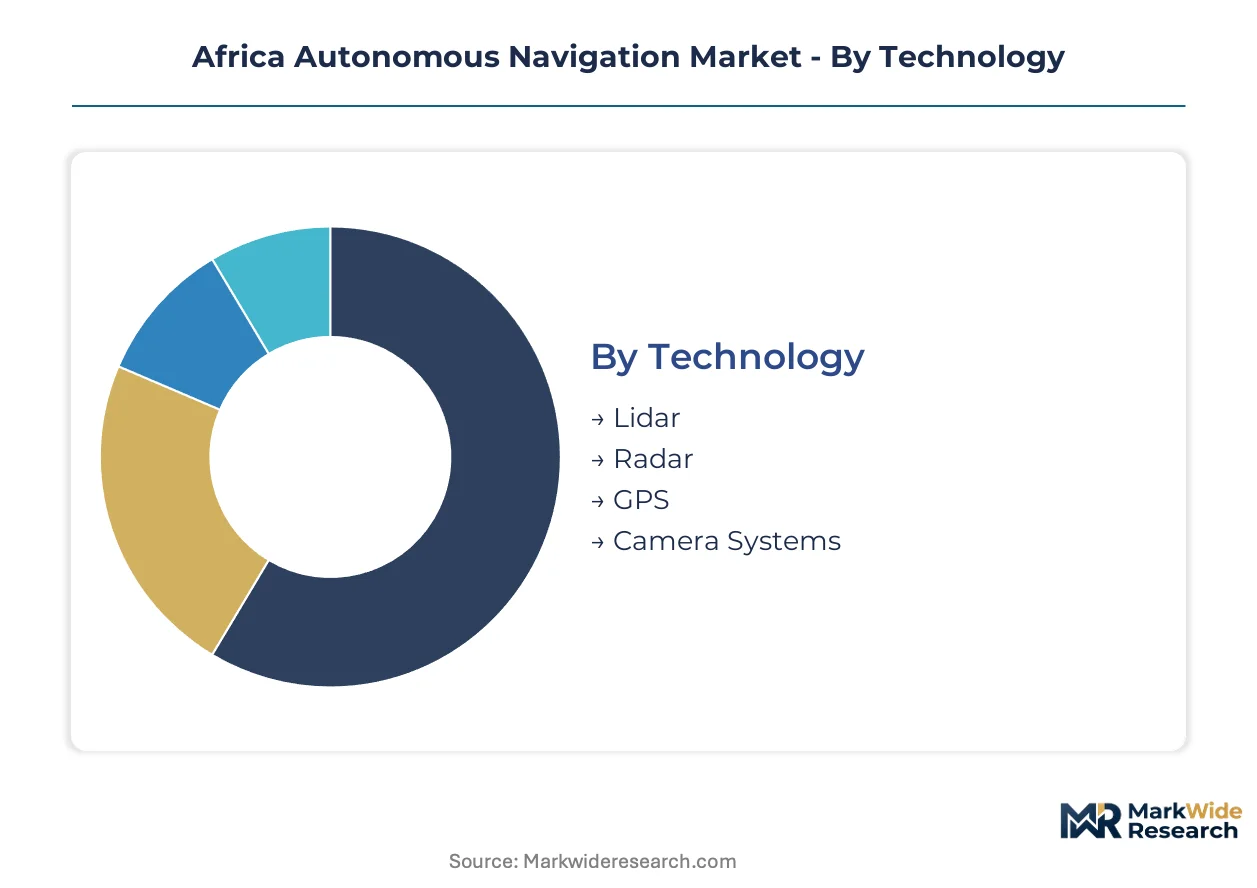
Segmentation reveals how procurement priorities diverge across Africa's autonomous navigation landscape. Mining operators in South Africa and Botswana prioritize ruggedized sensor stacks for haulage fleets, while East African agricultural buyers favor cost-optimized UAV platforms for precision spraying operations.
Technology:
Upgrade cycles in Southern African mining corridors are compressing replacement timelines as operators seek centimeter-scale localization without cloud dependency. Equipment refresh decisions now hinge on sensor fusion maturity rather than single-modality performance benchmarks.
- Lidar:Solid-state and mechanical units generate dense point clouds for terrain mapping in Botswana's diamond extraction zones. South African platinum belt operators deploy these systems where dust interference degrades camera reliability, though unit costs delay fleet-wide rollouts.
- Camera Systems:Lower unit costs and mature supply chains position this hardware as the dominant deployment across African fleet operators. Bushveld Complex mining contractors favor multi-camera arrays for visual odometry in GPS-denied pit environments where satellite signals attenuate.
- Radar:All-weather penetration capabilities suit Namibian logistics corridors with extreme temperature differentials and seasonal dust storms.
- GPS:Differential correction services anchor localization in open-pit environments with clear sky visibility across Zambian copper extraction sites.
Volume placements concentrate in Camera Systems; the faster expansion belongs to Lidar.
End User:
Customer-type segmentation exposes divergent procurement authority structures across the continent. State-linked mining houses in South Africa exercise centralized technology decisions, while East African agricultural cooperatives distribute purchasing across smallholder associations.
- Mining:Autonomous haulage fleets in South Africa's platinum and gold corridors reduce workforce exposure to hazardous terrain while maintaining throughput. National Regulator for Compulsory Specifications certification mandates filter which sensor configurations enter commercial service, extending vendor qualification timelines.
- Logistics:Last-mile delivery operators in Nigerian urban centers and Kenyan freight corridors deploy ground-based autonomous platforms for route optimization. Variable road infrastructure across Lagos and Nairobi drives demand for high-definition mapping subscriptions.
- Agriculture:UAV platforms calibrated for smallholder farm geometries in Kenya and Tanzania enable precision spraying and crop monitoring applications.
- Public Transport:Autonomous shuttle pilots in Cape Town and Johannesburg face extended homologation cycles under functional safety protocols.
Revenue concentration sits with Mining; Agricultural applications are climbing the fastest.
Application:
Margin structures vary sharply across application types, with fleet-scale deployments commanding volume discounts unavailable to pilot programs. Performance contracting models in Botswana's diamond regions now guarantee haul-cycle efficiency metrics rather than hardware specifications.
- Fleet Management:Mining operators in the Bushveld Complex adopt sensor fusion middleware unifying Lidar, radar, camera, and GPS inputs through standardized APIs. Single-vendor accountability for localization accuracy reduces subsystem integration overhead across multi-site operations.
- Road Safety:Public-private transport corridors in South Africa face tightened equipment certification standards from the National Regulator for Compulsory Specifications. Mandatory third-party validation of functional safety claims concentrates procurement risk with pre-certified sensor configurations.
- Delivery Services:Urban logistics operators in Nigerian and Kenyan cities navigate informal road networks with camera-dominant navigation stacks.
- Personal Mobility:Autonomous passenger services remain nascent across African markets due to regulatory uncertainty and infrastructure gaps.
Contract value concentrates in Fleet Management; Road Safety applications are gaining share fastest.
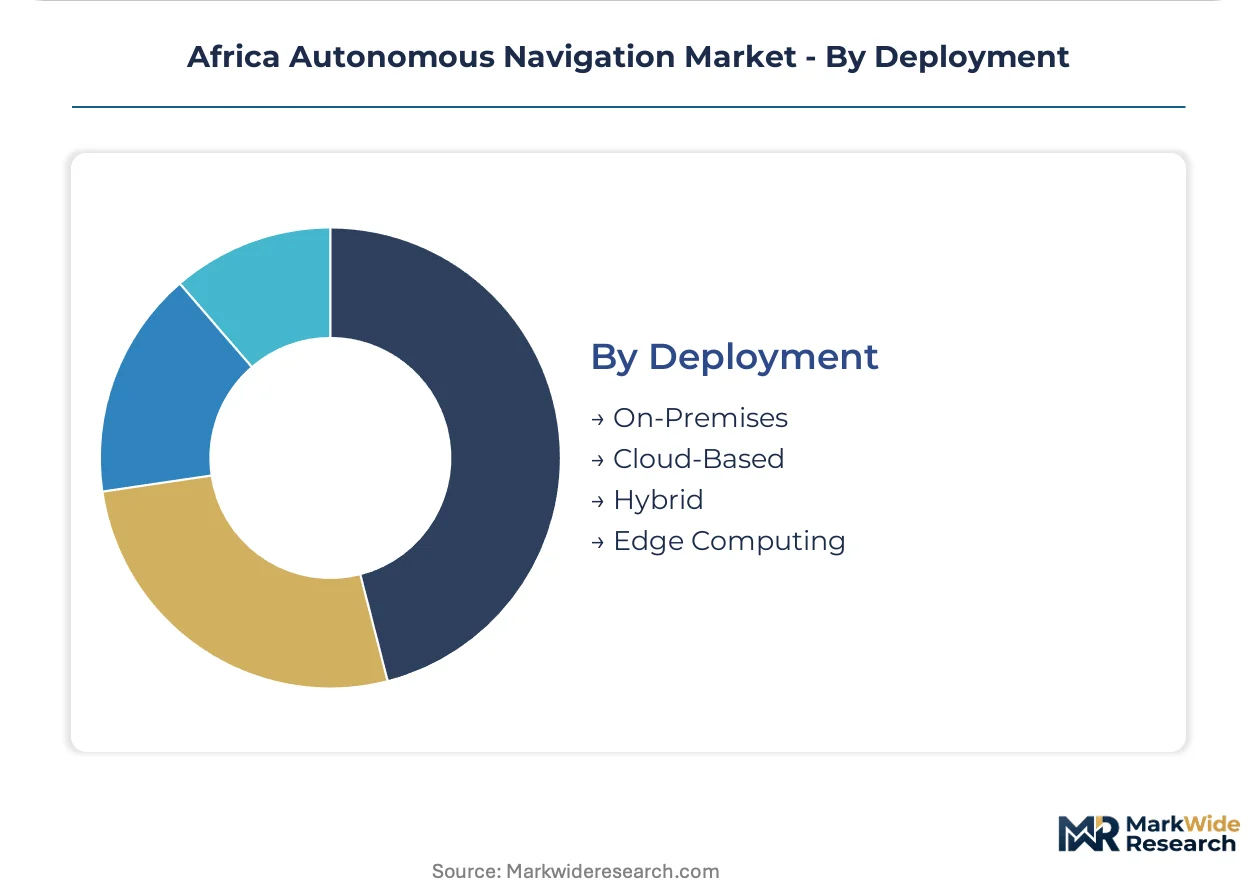
Deployment:
Supply concentration in Asian component manufacturing propagates procurement risk across Southern African mining networks. Edge processing architectures are displacing cloud-dependent systems where bandwidth constraints threaten operational continuity.
- Edge Computing:Kalman-filtered multi-spectral fusion at the vehicle level enables operation in remote zones with intermittent connectivity. Mining and logistics clients across Namibia and Botswana prioritize real-time decision latency over cloud bandwidth constraints.
- Cloud-Based:Centralized processing architectures serve pilot deployments in urban centers with reliable fiber infrastructure. Cape Town technology clusters host data aggregation for fleet performance analytics.
- Hybrid:Split architectures process time-critical localization at the edge while uploading telemetry for predictive maintenance.
- On-Premises:Fully localized systems serve defense-civilian dual-use applications with data sovereignty requirements.
Deployment share concentrates in Edge Computing; Hybrid architectures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of autonomous navigation hardware concentrates in East Asian manufacturing clusters, while consumption and deployment concentrate in Southern African mining corridors. This geographic divide shapes procurement patterns and technology transfer requirements across the continent.
South Africa
Platinum and gold mining corridors in the Bushveld Complex drive demand for centimeter-scale localization systems. The National Regulator for Compulsory Specifications enforces ISO 26262 functional safety protocols that filter sensor configurations entering commercial service. Johannesburg technology clusters host the continent's deepest concentration of Kalman filtering and sensor fusion engineering expertise.
Botswana
Diamond extraction zones in the Orapa and Jwaneng fields deploy solid-state Lidar units for terrain mapping where dust interference degrades optical sensors. Site-based performance contracting now guarantees haul-cycle efficiency metrics rather than hardware specifications. Gaborone serves as the procurement coordination hub for autonomous fleet deployments across the Kalahari mining belt.
Namibia
Logistics corridors connecting Walvis Bay to inland mining operations face extreme temperature differentials and seasonal dust storms that favor radar-dominant navigation stacks. Edge computing architectures enable real-time decision latency in remote zones with intermittent connectivity. The Walvis Bay corridor anchors demand for all-weather autonomous haulage between port and extraction sites.
Kenya
Precision agriculture applications in the Rift Valley and Mount Kenya highlands favor cost-optimized UAV platforms for smallholder farm geometries. Agricultural cooperatives distribute purchasing across producer associations rather than centralizing procurement authority. Nairobi technology clusters host emerging integration capabilities for camera-dominant navigation systems calibrated to East African crop patterns.
Nigeria
Last-mile delivery operators in Lagos and Abuja deploy ground-based autonomous platforms for route optimization across informal road networks. Variable infrastructure drives demand for high-definition mapping subscriptions from fleet-scale data providers. The Lagos-Ibadan corridor concentrates pilot deployments for urban logistics autonomy in West Africa's most densely populated metropolitan zones.
Africa Autonomous Navigation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Africa's autonomous navigation sector. Tier-one technology multinationals leverage integrated hardware-software stacks and established certification relationships with South African regulators. Mid-tier regional integrators occupy procurement niches requiring localized deployment support and brownfield retrofit expertise. Dominant competitive moves include strategic partnerships with mining houses for site-specific performance contracting and technology licensing arrangements that transfer sensor fusion capabilities to African engineering clusters.
Within the diversified technology tier, NVIDIA Corporation and Tesla, Inc. exemplify scale-driven platform strategies that span multiple application verticals. Airobotics Ltd. occupies a specialist position representing the drone-based inspection archetype for mining site surveys. TomTom N.V. anchors the geospatial services vector through high-definition mapping subscriptions calibrated to the continent's variable road infrastructure.
| Leading Market Players |
|---|
| Uber Technologies, Inc. |
| Airobotics Ltd. |
| Waymo LLC |
| Safran |
| TomTom N.V. |
| Tesla, Inc. |
| DJI Technology Co., Ltd. |
| L3Harris Technologies Inc. |
| NVIDIA Corporation |
| Others |
Value Network & Pricing Analysis
Lidar sensor module indices cascade through Africa's autonomous navigation supply chain into three distinct procurement tiers. Mining houses in South Africa's Bushveld Complex absorb premium positioning costs for ISO 26262-certified configurations, while East African agricultural cooperatives trade localization precision for camera-dominant economy stacks.
Pricing Analysis
Margin tightening in mid-tier sensor packages reflects solid-state Lidar cost volatility and extended IEC 61508 certification timelines. Three-tier pricing structure across premium, standard, and economy levels separates mining fleet operators from logistics pilots and smallholder UAV buyers. Price differentiation hinges on functional safety certification grade and after-sales service bundling. Agricultural segments in Kenya and Tanzania exhibit highest price sensitivity; platinum belt mining contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries producing edge processing units and solid-state Lidar emitters. Component manufacturing concentrates in China, South Korea, and Taiwan. Raw material dependencies span gallium arsenide substrates, rare-earth magnet alloys, and high-purity silicon wafers. Tariff exposure propagates procurement risk across Southern African mining networks. Distribution runs through Johannesburg technology clusters and Gaborone procurement hubs serving Kalahari extraction zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as certification timelines and capital requirements filter marginal vendors from African mining contracts. Protracted homologation cycles favor incumbents with established regulator relationships.
For Market Incumbents: Anchor market position through backward integration into edge computing hardware and captive sensor calibration facilities in Johannesburg. Pre-certify sensor configurations with South Africa's National Regulator for Compulsory Specifications before procurement cycles commence. Defensive moves should prioritize locking multi-year site-based performance contracts in Botswana's diamond regions against emerging pure-play specialists. For New Entrants and Emerging Players: Agricultural cooperatives in Kenya's Rift Valley represent the most penetrable channel partner type for cost-optimized UAV navigation stacks. Precision spraying applications for smallholder farm geometries remain underdeployed relative to Southern African mining saturation. Go-to-market execution should leverage Nairobi technology cluster partnerships for camera-dominant system integration and localized deployment support. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier regional integrators with brownfield retrofit expertise in South Africa's platinum belt. Long-term viability centers on acquisition targets possessing dual-use defense-civilian certification pathways and established mining house relationships. Watch for inflection signals in East African agricultural corridor penetration rates as UAV platform adoption crosses from pilot to fleet scale.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Middleware Platform Launch | Standardized APIs reduce subsystem integration overhead for Bushveld Complex mining operators. |
| ISO 26262 Certification Pre-Investment | Accelerated homologation timelines secure preferential procurement access with South African regulators. |
| Site-Based Performance Contracting | Outcome-based revenue models transfer operational risk from mining houses to technology vendors. |
| East African Agricultural Partnership | UAV platform distribution through Kenyan cooperatives unlocks precision spraying white space. |
| Edge Computing Hardware Integration | Kalman-filtered localization at vehicle level enables remote zone operation without cloud dependency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with mining technology procurement officers, sensor fusion engineering leads, UAV platform operators, and National Regulator for Compulsory Specifications officials combined with South African mining house annual reports, ISO certification databases, and East African agricultural cooperative disclosures. Bottom-up fleet deployment counts triangulated against top-down equipment import value estimates.
Granularity-level modeling operated at technology-by-deployment-by-end-user intersections across the projection horizon. Segmentation dimensions spanned sensor modality, computing architecture, application vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year equipment installation data. Forecast inputs incorporated mining sector wage pressure indices and agricultural mechanization policy trajectories.
Caveats apply where Lidar cost volatility, geopolitical friction in Asian component sourcing, or certification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions about equipment replacement cycles and regulator enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Autonomous Freight Trains Market