
 Autonomous Aircraft Sensors Market | 2026-2036
Autonomous Aircraft Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Aircraft Sensors Market Outlook
MIL-STD-810H qualification is unwinding as the baseline threshold for supplier entry into defense-grade autonomous platforms. Collins Aerospace leverages its integrated flight-control heritage to anchor positions in active-array radar subsystems for uncrewed military aircraft. Honeywell International Inc. sustains dominance in inertial measurement units through captive MEMS foundry capacity and FAA-certified repair station networks. Safran differentiates via European defense program participation, occupying sensor fusion roles on Franco-German FCAS demonstrators.
Autonomous aircraft sensors encompass transducers, processors, and signal-conditioning hardware that convert aerodynamic, electromagnetic, thermal, or inertial stimuli into flight-control actionable data, typically operating across temperature extremes from minus 55°C to 125°C and vibration profiles exceeding 20 g RMS. Their primary purpose is to enable closed-loop navigation and hazard response without onboard human intervention in denied or degraded visual environments. Lidar sensors command premium pricing in urban air mobility collision-avoidance stacks where centimeter-range resolution at 200-meter distances remains non-substitutable. Radar sensors retain volume leadership across military surveillance applications where all-weather penetration and electronic counter-countermeasure resilience outweigh cost considerations. Hybrid sensor architectures, fusing passive infrared signatures with active radio-frequency returns, are capturing the fastest expansion in cargo drone corridors requiring redundant hazard detection.
FAA Part 89 remote identification rules and forthcoming detect-and-avoid mandates are reshaping minimum sensor payload requirements for commercial autonomous operations below 400 feet AGL. EASA's Special Condition VTOL framework and EU AI Act risk-classification protocols for autonomous decision systems are creating dual certification burdens for suppliers serving transatlantic OEM customers. Stakeholders must monitor divergence between FAA performance-based standards and EASA prescriptive technical specifications when configuring sensor suites for multi-jurisdictional platform deployments.
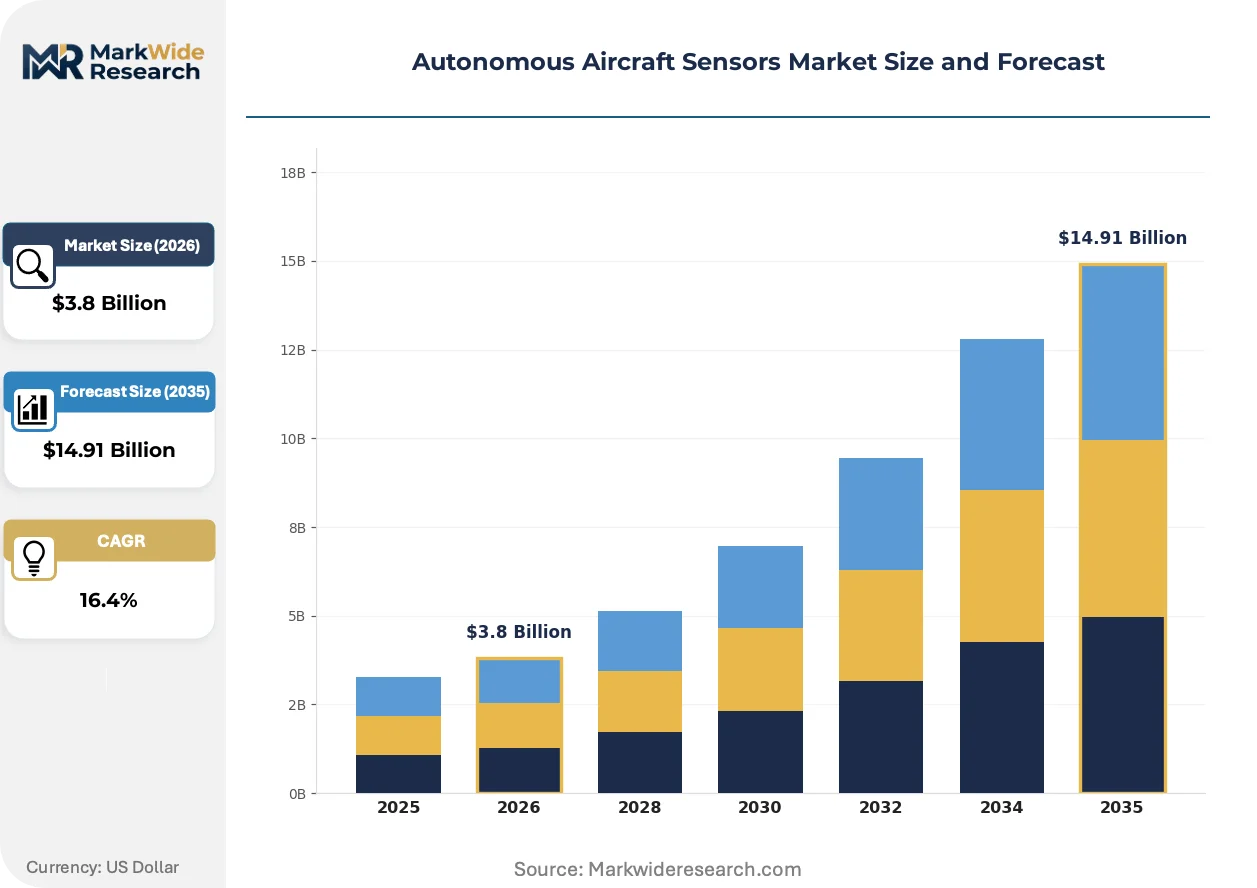
Market Dynamics
FAA Part 89 remote identification mandates and impending detect-and-avoid rulemakings are compressing certification timelines for sensor-integrated autonomous platforms, forcing suppliers to front-load qualification costs while military aviation programs across NATO members accelerate procurement of multi-spectral sensing suites for uncrewed combat air vehicles.
Growth Catalysts
- Remote ID Mandates:FAA Part 89 compliance deadlines are forcing commercial operators below 400 feet AGL to retrofit or procure sensor payloads with broadcast capabilities, creating baseline demand for integrated lidar-radar stacks.
- Multi-Spectral Military Procurement:NATO uncrewed combat air vehicle programs are accelerating fielding of fused electro-optical and synthetic aperture radar suites for contested electromagnetic environments.
- MEMS Foundry Scale:Captive inertial measurement unit production capacity in Arizona and Texas corridor clusters is collapsing lead times for defense primes and eVTOL developers co-locating flight-test operations.
Market Restraints
- Indium Phosphide Wafer Supply:Photonics-grade substrate concentration among three merchant foundries creates vulnerability for coherent lidar transceiver manufacturers facing 18-month order backlogs.
- MIL-STD-810H Qualification Costs:Vibration and thermal cycling test requirements spanning minus 55°C to 125°C impose six-figure entry barriers for sensor subsystem suppliers without defense heritage.
- Synthetic Aperture Radar Substitution:Passive electro-optical/infrared systems with onboard edge processing are displacing lower-frequency radar units in permissive airspace cargo corridors.
Strategic Opportunities
- EASA Special Condition VTOL:The European framework's prescriptive technical specifications for autonomous decision systems create first-mover advantage for suppliers with dual FAA-EASA certification experience.
- Hybrid Sensor Architectures:Fusing passive infrared signatures with active radio-frequency returns addresses redundancy requirements in beyond-visual-line-of-sight cargo drone corridors.
- India UTM Infrastructure:The country's national aviation regulator is establishing unmanned traffic management protocols requiring detect-and-avoid sensor mandates for commercial operations above 200 feet AGL.
Industry Challenges
- Sensor Fusion Algorithm Talent:Scarcity of embedded software engineers with simultaneous localization and mapping expertise is extending development cycles for urban air mobility collision-avoidance stacks.
- Dual Certification Burden:Divergence between FAA performance-based standards and EASA prescriptive specifications forces redundant engineering for transatlantic OEM customers.
- Legacy Avionics Integration:Retrofitting autonomous sensor suites onto existing manned platforms requires custom mechanical and electrical interface development without standardized form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Aircraft Sensors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Sensors, Lidar Sensors, Infrared Sensors, Position Sensors End User: Commercial Aviation, Military Aviation, Cargo Operators, Research Institutions Technology: Passive Sensors, Active Sensors, Hybrid Sensors, Microelectromechanical Systems Application: Navigation, Surveillance, Collision Avoidance, Weather Monitoring |
| Companies Covered | Meggitt PLC, Collins Aerospace, Honeywell International Inc., Crane Aerospace & Electronics, Curtiss-Wright Corporation, Safran, AMETEK Inc., Sensata Technologies, TE Connectivity Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Aircraft Sensors Market Strategic Shifts
Solid-state beam steering and integrated photonics are collapsing the size-weight-power-cost envelope for autonomous aircraft sensors, while regulatory frameworks on both sides of the Atlantic harden minimum performance thresholds for commercial operations.
Solid-state lidar with optical phased arrays is replacing mechanical spinning units in urban air mobility platforms. eVTOL developers in the United States are adopting these units at prototype-through-certification pace. The technology is miniaturizing collision-avoidance stacks from rack-mounted assemblies to palm-sized modules, compressing airframe integration timelines.
EASA's Special Condition VTOL framework and the EU AI Act's risk-classification protocols for autonomous decision systems are creating technical specification burdens distinct from FAA approaches. Suppliers must maintain parallel engineering tracks for transatlantic customers. Cargo drone OEMs serving both jurisdictions are consolidating sensor suite configurations to limit variant proliferation.
Defense primes are unbundling sensor procurement from platform integration contracts, forcing subsystem suppliers to assume airworthiness certification liability. Tier-2 vendors with captive test ranges in Arizona and Texas are capturing direct relationships previously mediated by primes. This channel disintermediation is most visible in NATO uncrewed combat air vehicle programs where national procurement offices now specify multi-spectral sensing suites at subsystem level.
Autonomous Aircraft Sensors Market Segmentation
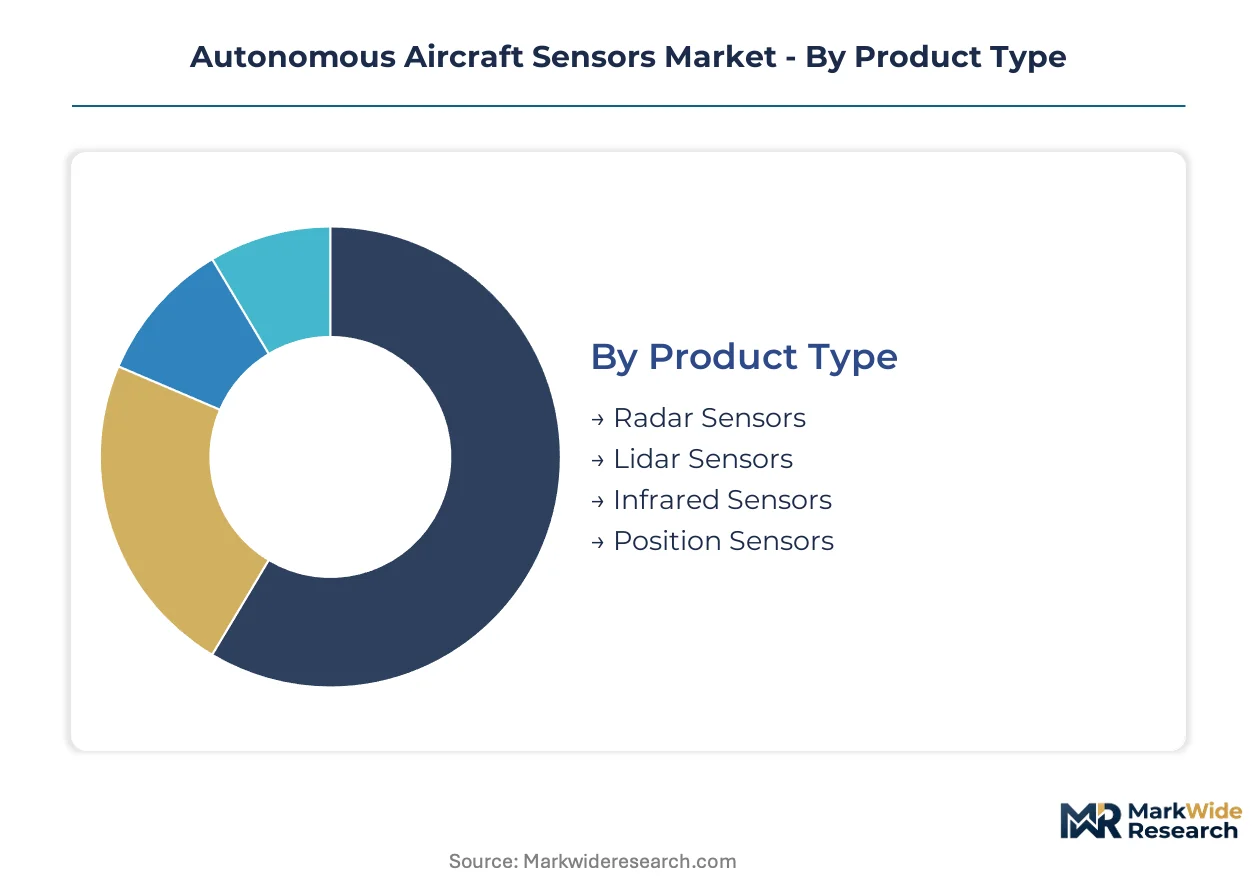
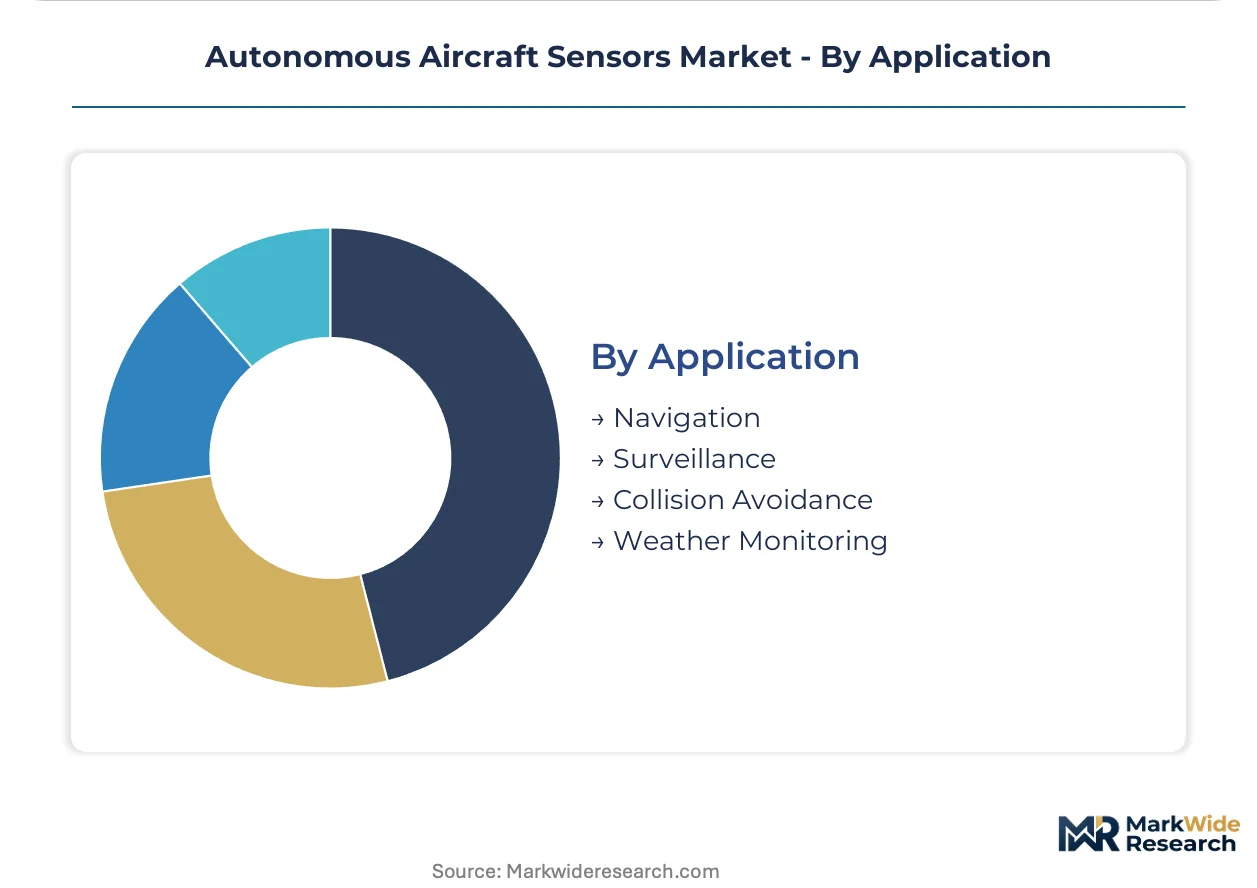
Sensor configurations diverge sharply across deployment contexts, with defense primes demanding MIL-STD qualification while commercial operators optimize for FAA Part 89 compliance. Channel strategies must align with these divergent procurement pathways.
Product Type:
Radar and lidar units flow through defense primes and eVTOL developers in Arizona and Texas corridor clusters, while infrared and position sensors reach research institutions via specialized distributors.
- Radar Sensors:Synthetic aperture and active-array architectures penetrate weather and electronic countermeasures across contested electromagnetic environments. NATO uncrewed combat air vehicle programs anchor procurement in the United States and European defense corridors. Military surveillance applications prioritize all-weather penetration over unit economics.
- Lidar Sensors:Solid-state optical phased arrays with coherent transceivers achieve centimeter-range resolution at 200-meter distances for urban air mobility stacks. FAA detect-and-avoid mandates for operations below 400 feet AGL compress integration timelines for these premium-priced units. Indium phosphide wafer supply constraints extend lead times for photonics-grade transceivers.
- Infrared Sensors:Passive thermal imaging arrays serve cargo drone corridors requiring signature detection without active emissions.
- Position Sensors:MEMS-based inertial measurement units from captive foundries collapse lead times for flight-control feedback loops.
Radar sensors dominate installed base across military platforms. Lidar sensors are where expansion concentrates for commercial certification.
End User:
Cost tiers separate defense-grade qualification paths from commercial retrofit economics, with cargo operators occupying a mid-tier hybrid position.
- Commercial Aviation:eVTOL developers in the United States co-locate flight-test operations with sensor suppliers to compress FAA certification cycles. EASA Special Condition VTOL frameworks impose parallel engineering tracks for transatlantic OEM customers. Dual certification burdens inflate upfront qualification costs.
- Military Aviation:NATO procurement offices now specify multi-spectral sensing suites at subsystem level, disintermediating traditional prime-contractor channels. MIL-STD-810H vibration and thermal cycling requirements from minus 55°C to 125°C filter supplier entry. National programs in France and Germany anchor European demand through FCAS demonstrators.
- Cargo Operators:Beyond-visual-line-of-sight corridors drive hybrid sensor adoption for redundant hazard detection.
- Research Institutions:Experimental platforms test fusion algorithms before commercial scale-up.
Military aviation commands premium pricing tiers. Commercial aviation represents the steepest expansion trajectory as urban air mobility platforms approach certification.
Technology:
Volume concentration favors MEMS inertial units, while margin capture concentrates in hybrid architectures requiring sensor fusion expertise.
- Passive Sensors:Electro-optical and infrared systems with onboard edge processing displace lower-frequency radar in permissive airspace cargo corridors. No active emissions reduce detectability and power draw. Processing latency constraints limit closed-loop navigation applications.
- Active Sensors:Radio-frequency and lidar emitters provide deterministic range measurements in degraded visual environments. Size-weight-power-cost envelopes collapse with solid-state beam steering and integrated photonics. All-weather penetration justifies premium positioning.
- Hybrid Sensors:Fused passive infrared with active radio-frequency returns addresses redundancy mandates for autonomous decision systems.
- Microelectromechanical Systems:Captive foundry capacity in Arizona and Texas underpins inertial measurement unit supply security.
Active sensors anchor revenue concentration. Hybrid sensors are where technology investment concentrates.
Application:
Customer workflows differentiate navigation stacks requiring continuous operation from surveillance payloads with intermittent duty cycles.
- Navigation:Inertial measurement units and GPS-denied positioning algorithms enable closed-loop flight control without ground infrastructure. Simultaneous localization and mapping expertise scarcity extends development cycles for urban air mobility stacks. MEMS foundry scale in United States corridor clusters supports demand concentration.
- Surveillance:Synthetic aperture radar and multi-spectral electro-optical suites penetrate denied areas for intelligence collection. NATO uncrewed combat air vehicle programs specify these capabilities at national procurement office level. Electronic counter-countermeasure resilience outweighs cost considerations.
- Collision Avoidance:Lidar-radar fusion stacks meet FAA detect-and-avoid mandates for commercial operations below 400 feet AGL.
- Weather Monitoring:Doppler radar and atmospheric sensors support route optimization for cargo corridors.
Navigation commands the largest installed base. Collision avoidance is where regulatory mandates are forcing fastest capability deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established aerospace clusters over emerging manufacturing bases. The United States runs a substantial surplus in defense-grade sensor subsystems, while European suppliers concentrate on dual-use certification pathways. Asian markets remain net importers of high-reliability inertial measurement units and coherent lidar transceivers.
United States
eVTOL developers and defense primes co-locate flight-test operations with sensor suppliers in Arizona and Texas corridor clusters. FAA Part 89 remote identification mandates and impending detect-and-avoid rulemakings compress certification timelines for integrated lidar-radar stacks. Phoenix and Dallas-Fort Worth metro areas anchor MEMS foundry capacity for inertial measurement unit production.
Germany
National procurement offices specify multi-spectral sensing suites at subsystem level for Franco-German FCAS demonstrators. EASA Special Condition VTOL frameworks impose prescriptive technical specifications distinct from FAA performance-based standards. Bavaria and Baden-Württemberg host sensor fusion development for autonomous decision systems.
France
Defense program participation anchors European demand through FCAS demonstrator workshare agreements. EU AI Act risk-classification protocols for autonomous decision systems create dual certification burdens for suppliers serving transatlantic OEM customers. Île-de-France and Provence-Alpes-Côte d'Azur concentrate electro-optical subsystem integration.
United Kingdom
NATO uncrewed combat air vehicle programs drive procurement of synthetic aperture radar and electronic counter-countermeasure suites. Ministry of Defence procurement offices increasingly specify subsystem-level requirements, disintermediating traditional prime-contractor channels. Greater London and South West England house radar signal processing expertise.
India
The Directorate General of Civil Aviation establishes unmanned traffic management protocols requiring detect-and-avoid sensor mandates for commercial operations above 200 feet AGL. Import dependence on photonics-grade indium phosphide substrates creates vulnerability for coherent lidar transceiver manufacturers. Karnataka and Telangana states emerge as flight-test corridors for cargo drone OEMs.
Autonomous Aircraft Sensors Market Competitive Environment
Concentration sits with defense-heritage primes and captive-component specialists. Tier-1 primes retain platform integration contracts while unbundling sensor procurement to subsystem vendors with captive test ranges. Three archetypes dominate: aerospace conglomerates with integrated flight-control heritage, MEMS foundry operators with FAA-certified repair networks, and European defense contractors with multi-national program participation. Competitive moves center on channel disintermediation and dual-certification engineering tracks.
Among aerospace conglomerates, Collins Aerospace and Honeywell International Inc. exemplify the integrated-systems archetype, while Safran occupies a position within the European defense-specialist tier. These entities represent contrasting geographic and regulatory positioning strategies, with United States-based firms anchoring FAA certification pathways and French suppliers navigating EASA prescriptive frameworks. The competitive terrain rewards captive manufacturing capacity and direct relationships with national procurement offices.
| Leading Market Players |
|---|
| Meggitt PLC |
| Collins Aerospace |
| Honeywell International Inc. |
| Crane Aerospace & Electronics |
| Curtiss-Wright Corporation |
| Safran |
| AMETEK Inc. |
| Sensata Technologies |
| TE Connectivity Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts between defense primes and MEMS foundry operators lock in supply access for inertial measurement units while capping unit cost escalation for multi-year NATO uncrewed combat air vehicle programs. These arrangements tether pricing visibility to Arizona and Texas corridor cluster output, where eVTOL developers compete for qualified substrate allocations against military procurement offices.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Autonomous Aircraft Sensors Market. Premium tiers capture MIL-STD-810H qualified units for defense applications where thermal cycling validation from minus 55°C to 125°C justifies cost premiums, while economy tiers serve research institutions with reduced qualification burdens. Pricing pressure stems from indium phosphide wafer supply constraints extending lead times for coherent lidar transceivers. Cargo operators exhibit highest price sensitivity as they balance redundancy requirements against per-unit payload economics.
Supply Chain Analysis
Eighteen-month order backlogs for photonics-grade substrates signal inventory strain across coherent lidar transceiver manufacturing. Supply concentrates in the United States, Germany, and France for qualified sensor subsystems, while merchant foundry capacity for indium phosphide wafers rests on three concentrated sources. Single-source vulnerability for photonics-grade substrates creates exposure for lidar manufacturers serving FAA Part 89 compliance deadlines. Distribution runs through defense primes unbundling procurement to subsystem vendors with captive test ranges, bypassing traditional prime-contractor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward defense procurement offices specifying multi-spectral sensing suites at subsystem level, fragmenting traditional prime-contractor channels and forcing tier-2 suppliers to assume direct airworthiness certification liability.
For Market Incumbents: Secure captive MEMS foundry capacity in Arizona and Texas corridor clusters to defend against emerging eVTOL developers vertically integrating into inertial measurement unit production. Anchor dual FAA-EASA certification engineering tracks to capture Franco-German FCAS demonstrator workshare against European defense specialists. Lock in long-term indium phosphide wafer offtake agreements before merchant foundry backlogs extend further. For New Entrants and Emerging Players: Anchor in India UTM infrastructure development, where the Directorate General of Civil Aviation's detect-and-avoid mandates above 200 feet AGL create first-mover white space without entrenched incumbent relationships. Target hybrid sensor architecture development for beyond-visual-line-of-sight cargo corridors, where redundancy requirements outstrip current supplier capacity. Pursue direct qualification pathways with national procurement offices rather than prime-contractor channels. For Investors and Strategic Acquirers: Sensor fusion algorithm specialists with simultaneous localization and mapping expertise represent the most defensible acquisition archetype, given embedded software engineering scarcity extending urban air mobility development cycles. Monitor EASA Special Condition VTOL framework divergence from FAA performance-based standards as inflection signal for dual-certification engineering premium capture. Long-term viability centers on suppliers bridging transatlantic regulatory fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Engineering Investment | Captures EASA-FAA divergence premium for transatlantic OEM customers. |
| Captive MEMS Foundry Expansion | Collapses lead times for defense primes co-locating flight-test operations. |
| Indium Phosphide Wafer Supply Agreement | Secures substrate access against eighteen-month merchant foundry backlogs. |
| Sensor Fusion Algorithm Acquisition | Addresses embedded software engineering scarcity for collision-avoidance stacks. |
| Direct National Procurement Office Relationship | Bypasses prime-contractor disintermediation in NATO uncrewed combat air vehicle programs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA rulemaking dockets, EASA Special Condition VTOL technical specifications, NATO procurement office specifications, and defense prime SEC filings. Primary interviews engaged sensor subsystem procurement leads at tier-1 aerospace conglomerates, MEMS foundry operations directors in Arizona and Texas corridor clusters, eVTOL certification engineers, and national procurement office technology advisors. Bottom-up unit economics triangulate against top-down defense budget allocation analysis across the analysis window.
Segmentation dimensions modeled span sensor product type, end-user procurement pathway, underlying technology architecture, and application workflow duty cycle. CAGRs derive from installed base evolution, replacement cycle compression, and regulatory mandate timing throughout the forecast period. Forecast inputs incorporate FAA detect-and-avoid rulemaking progression, EASA prescriptive specification adoption rates, and indium phosphide wafer foundry capacity expansion announcements.
Material uncertainties — regulatory divergence acceleration, photonics substrate supply disruption, sensor fusion algorithm talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions without contingency for unannounced military program cancellations or accelerated eVTOL certification pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Military Robotics Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market