
 North America AUV Market | 2026-2036
North America AUV Market Size, Share, and Industry Trends Forecast 2026-2036
North America AUV Market Analytics
Defense procurement channels is reshaping vendor access across the North America AUV Market, with prime contractors consolidating subsystem awards and tier-two suppliers facing higher qualification barriers. General Dynamics Corporation leverages its Columbia-class submarine industrial base to extend AUV payload integration capabilities. Lockheed Martin Corporation anchors deep-water autonomous programs through its undersea systems division in Massachusetts. Teledyne Technologies Incorporated competes across the sensor-to-platform stack, sustaining dual-use revenue from both naval and energy survey accounts.
An autonomous underwater vehicle is a self-propelled, untethered marine robot operating without real-time human control, typically rated for depths from 200 meters to over 6,000 meters depending on hull pressure vessel construction and battery configuration. Its primary purpose is to execute pre-programmed survey, inspection, or data collection missions across seabed mapping, pipeline monitoring, and military reconnaissance operations. The hybrid AUV segment captures premium positioning where operators require mode-switching between autonomous transit and remote intervention, concentrating margin pools in deep-water oil and gas contracting. Software-defined architectures within the technology dimension are displacing hardware-fixed navigation stacks, enabling faster mission reprogramming and reducing platform obsolescence cycles. Battery-powered propulsion dominates unit economics for survey-class vehicles, though energy density constraints limit endurance in long-range defense applications.
The US Navy's Unmanned Campaign Framework and FAA coordination protocols for surfaced recovery operations shape certification pathways and fleet integration timelines for domestic suppliers. Canada's Department of National Defence procurement guidelines and US ITAR export controls jointly determine which platforms cross the border for joint NORAD undersea surveillance exercises. Buyers must weigh sovereign capability requirements against subsystem sourcing flexibility as both Washington and Ottawa harden supply chain security reviews for maritime autonomy systems.
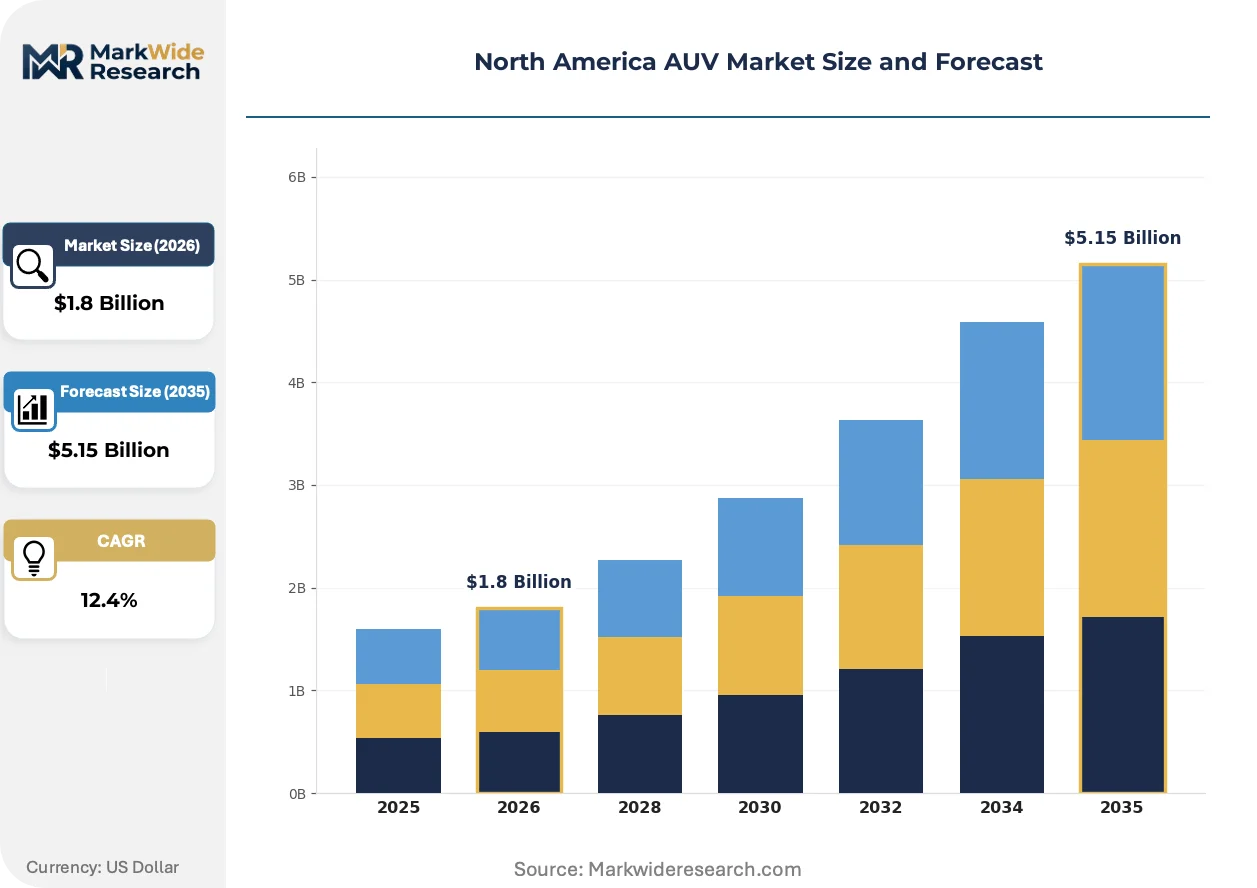
Market Dynamics
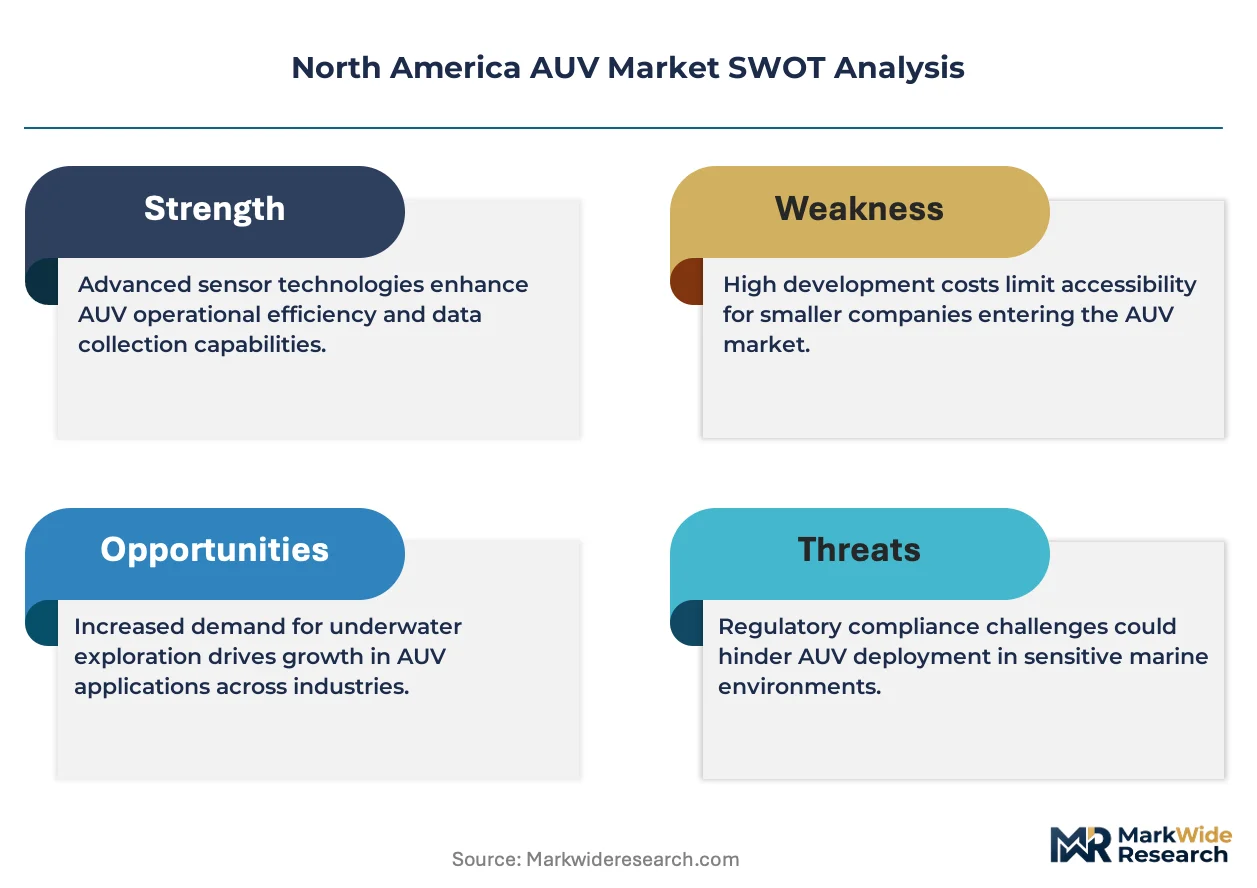
The US Department of Defense's Unmanned Campaign Framework is consolidating AUV procurement around software-defined architectures, compressing hardware refresh cycles and forcing subsystem vendors to requalify under stricter supply chain security protocols.
Growth Catalysts
- Undersea warfare autonomy mandates:The US Navy's force structure assessments prioritize AUV fleet expansion for seabed warfare and mine countermeasures, generating sustained platform demand through 2035.
- Offshore energy decommissioning wave:Gulf of Mexico operators require autonomous inspection vehicles for aging pipeline infrastructure, creating recurring survey contracts in the energy corridor.
- Lithium-sulfur battery maturation:Energy density improvements in next-generation power systems extend mission endurance for long-range defense applications previously limited by propulsion constraints.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors for AUV propulsion depend on Chinese-processed neodymium, exposing US and Canadian builders to export control volatility.
- Pressure vessel fabrication bottlenecks:Deep-rated titanium hemispheres require specialized forging capacity concentrated in a handful of domestic machine shops.
- ITAR classification friction:Dual-use navigation and communication subsystems trigger export licensing delays that complicate Canadian cross-border collaboration.
Strategic Opportunities
- Arctic seabed mapping:Canada's northern territorial claims and ice-capable AUV demand from the Department of National Defence create underpenetrated procurement channels.
- Hybrid AUV-ROV convergence:Mode-switching platforms capture premium contracting in deep-water oil and gas where operators seek to reduce vessel days.
- IRA clean energy manufacturing credits:Battery cell domestic production incentives lower landed cost for survey-class vehicle power systems.
Industry Challenges
- Autonomy software certification timelines:The FAA's surfaced-recovery coordination protocols and Navy safety cases require multi-year validation cycles that delay revenue recognition.
- Acoustic sensor integration complexity:Synthetic aperture sonar and inertial navigation fusion demands specialized systems engineering talent scarce in the domestic workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America AUV Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Underwater Vehicle, Remotely Operated Vehicle, Hybrid AUV, Mini AUV End User: Oil & Gas, Defense, Environmental Monitoring, Research Institutes Application: Surveying, Inspection, Exploration, Data Collection Technology: Battery-Powered, Software-Defined, Autonomous Navigation, Communication Systems |
| Companies Covered | General Dynamics Corporation, Lockheed Martin Corporation, L3Harris Technologies, Boeing, Teledyne Technologies Incorporated, International Submarine Engineering Ltd, Oceaneering International Inc., Fugro, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America AUV Market Evolving Landscape
Navigation and perception architectures are undergoing rapid modularization, enabling faster mission reprogramming and reducing platform-specific engineering overhead across defense and commercial programs.
Optical-acoustic sensor fusion is migrating from experimental seabed mapping applications into standard survey-class configurations. Offshore energy contractors in the Gulf of Mexico are adopting these packages for pipeline inspection at accelerating rates. The technology shift is compressing survey timelines from multi-day vessel operations to single-deployment autonomous missions.
The US Navy's Unmanned Campaign Framework and FAA surfaced-recovery protocols are tightening certification requirements for autonomous navigation systems. This regulatory pressure is elevating documentation burdens on subsystem suppliers while creating preferred vendor status for those with existing safety case libraries. Deep-water defense applications face the steepest compliance ramps.
Energy sector procurement is consolidating around integrated service contracts that bundle AUV deployment with data interpretation and regulatory filing support. Traditional equipment-only vendors in Southern California and Houston are restructuring offerings or partnering with offshore engineering firms. This bundling pattern is most pronounced in Gulf Coast deep-water operations where operators seek single-accountability risk transfer.
North America AUV Market Segmentation
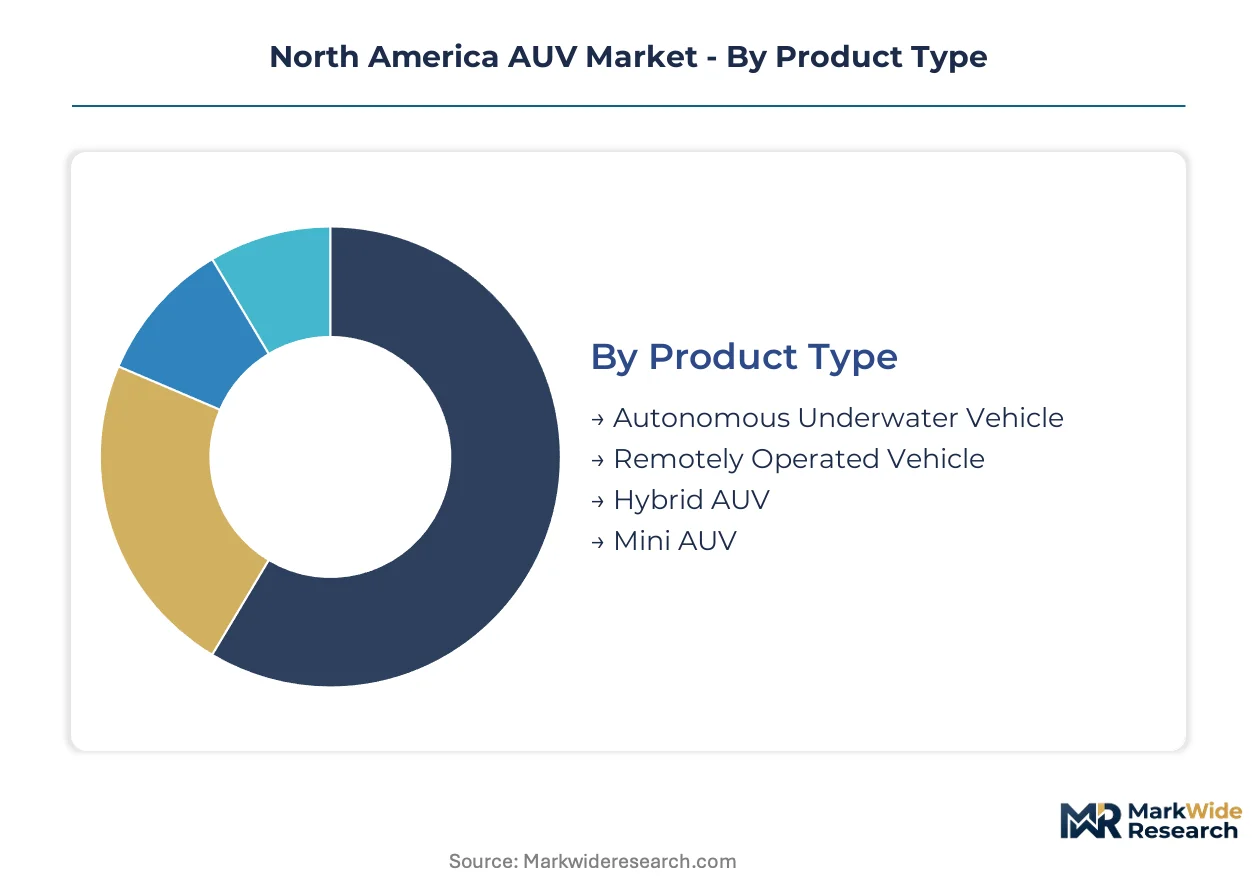
Segmentation in the North America AUV Market reveals how procurement priorities diverge between defense-grade endurance requirements and commercial survey economics. Platform specifications, power architectures, and mission software stacks determine vendor positioning across buyer categories.
Product Type:
Mature hull form factors dominate defense procurement, while emerging configurations capture energy sector experimentation.
- Autonomous Underwater Vehicle:Self-propelled untethered platforms rated for depths from 200 to 6,000 meters depending on pressure vessel construction. US Navy seabed warfare programs concentrate demand in Massachusetts and Rhode Island technology clusters, constrained by lithium-sulfur battery maturation timelines for extended endurance missions.
- Hybrid AUV:Mode-switching platforms alternate between autonomous transit and remote operator intervention through tethered docking interfaces. Gulf of Mexico deep-water contractors drive procurement, seeking to compress multi-day vessel operations into single-deployment missions while retaining intervention capability for anomaly response.
- Remotely Operated Vehicle:Tethered systems with real-time human control via surface umbilical, prevalent in legacy offshore infrastructure inspection.
- Mini AUV:Compact platforms under 100 kilograms displacement, deployed for rapid environmental assessment and harbor security screening.
Autonomous Underwater Vehicle retains volume leadership; Hybrid AUV holds the steepest expansion curve.
End User:
Cost tier stratification separates sovereign defense budgets from commercial operators seeking risk-transfer contracting models.
- Defense:The US Department of Defense's Unmanned Campaign Framework consolidates procurement around software-defined architectures, with platform requirements spanning mine countermeasures, seabed warfare, and undersea infrastructure protection. ITAR classification protocols constrain Canadian cross-border collaboration on navigation subsystem sourcing.
- Oil & Gas:Integrated service contracts now bundle AUV deployment with data interpretation and regulatory filing support, compressing margins for equipment-only vendors. Gulf Coast deep-water operators favor single-accountability risk transfer, restructuring procurement toward Houston-based offshore engineering firms with captive survey capabilities.
- Environmental Monitoring:Regulatory compliance mandates for seabed disturbance assessment and marine protected area baseline studies.
- Research Institutes:Academic and government laboratory programs with extended procurement cycles and open-architecture data requirements.
Defense commands the premium pricing tier; Oil & Gas is expanding most quickly through bundled service adoption.
Application:
Application intensity correlates with water depth and regulatory scrutiny, concentrating margin in frontier basins.
- Inspection:Pipeline and subsea facility assessment missions, now accelerated by optical-acoustic sensor fusion packages. Gulf of Mexico operators adopting these configurations are compressing survey timelines from multi-day vessel operations to autonomous single deployments.
- Surveying:Seabed mapping and bathymetric data acquisition for route planning and territorial claim support. Canada's Department of National Defence Arctic procurement channels concentrate here, with ice-capable platform requirements for northern territorial assertion.
- Exploration:Frontier basin reconnaissance and prospect evaluation in frontier deep-water lease blocks.
- Data Collection:Long-duration oceanographic monitoring and acoustic surveillance missions.
Inspection leads current deployment volume; Surveying is gaining share fastest from Arctic sovereignty programs.
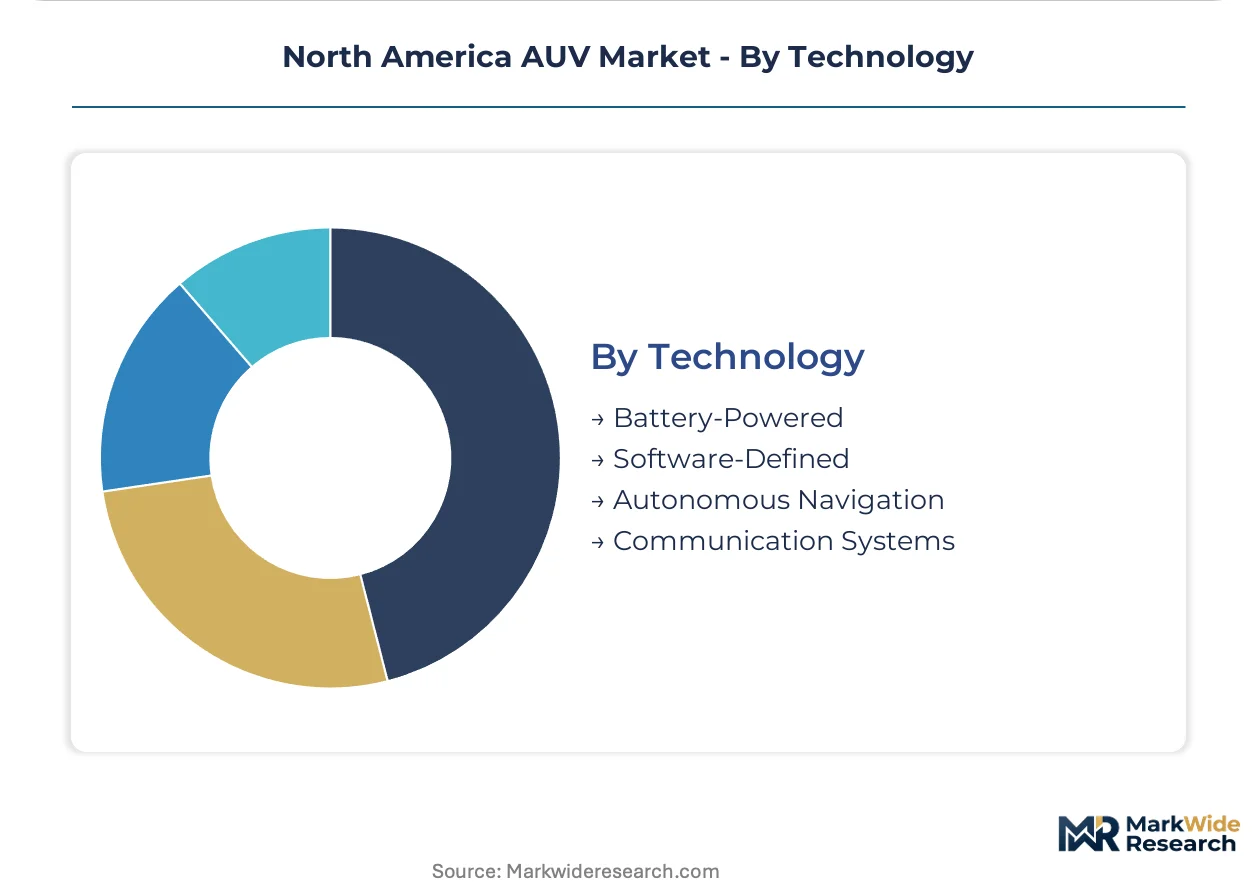
Technology:
Supply concentration in permanent magnet motors and pressure vessel forging shapes technology adoption constraints.
- Software-Defined:Modular navigation and perception architectures enabling faster mission reprogramming without hardware replacement. FAA surfaced-recovery coordination protocols and Navy safety cases are elevating documentation burdens on subsystem suppliers while creating preferred vendor status for those with existing certification libraries.
- Battery-Powered:Dominant propulsion architecture for survey-class vehicles, with IRA clean energy manufacturing credits lowering landed costs for domestic cell production. Energy density constraints persist for long-range defense applications.
- Autonomous Navigation:Inertial-sensor fusion and synthetic aperture sonar integration demanding scarce systems engineering talent in the domestic workforce.
- Communication Systems:Acoustic modem and satellite link subsystems for command updates and data exfiltration.
Battery-Powered retains installed base dominance; Software-Defined is climbing the fastest as procurement specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA and US Navy certification protocols anchor North American procurement, while Canadian Department of National Defence guidelines and ITAR cross-border constraints shape vendor access across the continent.
United States
US Navy seabed warfare programs and Gulf of Mexico decommissioning mandates concentrate demand in Massachusetts technology clusters and Houston energy corridors. The Department of Defense's Unmanned Campaign Framework consolidates procurement around software-defined architectures, compressing hardware refresh cycles. Southern California naval engineering hubs and Rhode Island undersea systems divisions host prime contractor payload integration facilities.
Canada
Arctic territorial assertion programs and ice-capable platform requirements from the Department of National Defence drive surveying application growth. ITAR export controls constrain navigation subsystem sourcing from US suppliers, complicating joint NORAD undersea surveillance exercises. British Columbia marine technology clusters and Atlantic Canada defense contractors develop sovereign capability alternatives.
Mexico
Offshore energy infrastructure inspection contracts in the Gulf of Mexico create downstream service opportunities for survey-class vehicle operators. National hydrocarbon regulator CNH mandates seabed disturbance assessments for deep-water lease blocks. Ciudad del Carmen and Tampico port clusters serve as logistics hubs for autonomous deployment vessels operating Mexican territorial waters.
North America AUV Market Competitive Landscape
Defense prime contractors and energy sector service integrators split the market along sovereign capability and commercial risk-transfer lines. The vendor structure concentrates around tier-one platform integrators with existing Navy safety case libraries, while tier-two subsystem suppliers face requalification barriers under tightened supply chain security protocols. Two strategic archetypes dominate: vertically integrated defense conglomerates leveraging submarine industrial base relationships, and sensor-to-platform specialists sustaining dual-use revenue streams. Competitive moves center on payload integration partnerships and bundled service contract restructuring.
Among defense-anchored conglomerates, General Dynamics Corporation and Lockheed Martin Corporation exemplify the prime contractor archetype, each leveraging established undersea systems divisions to extend platform integration capabilities. Teledyne Technologies Incorporated occupies a position bridging defense and commercial demand, representing the sensor-specialist archetype with cross-sector revenue exposure.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Boeing |
| Teledyne Technologies Incorporated |
| International Submarine Engineering Ltd |
| Oceaneering International Inc. |
| Fugro |
| Saab AB |
| Others |
Value Network & Pricing Analysis
Southern California naval engineering clusters concentrate titanium pressure vessel forging capacity, granting incumbent fabricators substantial pricing leverage over deep-rated AUV hull procurement. This geographic chokepoint compresses margins for tier-two platform integrators while elevating premium capture for defense-grade suppliers with established Navy safety case libraries.
Pricing Analysis
Price spreads between Gulf Coast energy contractors and Massachusetts defense procurement offices reflect divergent mission endurance specifications and certification burdens. Three-tier pricing structure across ITAR-restricted navigation stacks, dual-use sensor suites, and commercial survey packages differentiates vendor access. Pricing pressure stems from lithium-sulfur battery commercialization timelines as energy density improvements compress premium capture for endurance-limited platforms. Oil and gas operators exhibit highest price sensitivity through bundled service contracting, while seabed warfare programs absorb premium positioning for sovereign capability assurance.
Supply Chain Analysis
Upstream rare earth magnet processing draws from Chinese neodymium concentration, Japanese specialty alloy refinement, and domestic magnet fabrication in North Carolina. Titanium hemispheres, lithium-sulfur cathode materials, and synthetic aperture sonar arrays constitute critical input dependencies. Single-source vulnerability in deep-rated forging capacity exposes delivery timelines to machine shop scheduling constraints. Distribution runs through prime contractor payload integration facilities in Rhode Island and Massachusetts, with tier-two subsystem vendors facing requalification barriers under tightened ITAR protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FAA surfaced-recovery certification and Navy safety case libraries create switching costs that lock out unqualified competitors. Prime contractors with existing autonomy software validation histories command durable defensive moats.
For Market Incumbents: Entrench position through captive lithium-sulfur battery supply agreements and backward integration into pressure vessel forging capacity. Lockheed Martin Corporation and General Dynamics Corporation should expand Rhode Island undersea systems divisions to absorb tier-two subsystem vendors facing requalification barriers. ITAR classification friction threatens cross-border Canadian collaboration, necessitating sovereign capability partnerships with British Columbia marine technology clusters.
For New Entrants and Emerging Players: Arctic seabed mapping programs under Canada's Department of National Defence represent the most penetrable entry point for ice-capable platform specialization. Gulf of Mexico decommissioning inspection contracts offer secondary white-space through optical-acoustic sensor fusion packages. New entrants should pursue joint development agreements with Houston-based offshore engineering firms seeking captive survey capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates divesting non-core autonomy divisions under portfolio rationalization pressures. Long-term viability favors sensor-to-platform specialists with dual-use revenue exposure spanning naval and energy accounts. Watch for FAA certification timeline acceleration as the inflection signal indicating regulatory barriers to new entrant qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Migration | Modular navigation stacks reduce platform obsolescence cycles for Navy procurement. |
| Lithium-Sulfur Battery Supply Agreement | Energy density improvements extend mission endurance for seabed warfare applications. |
| Arctic Ice-Capable Platform Development | Canada's territorial assertion programs create underpenetrated surveying demand. |
| Hybrid AUV-ROV Convergence Investment | Mode-switching capability captures premium contracting in Gulf of Mexico deep-water. |
| ITAR-Compliant Navigation Subsystem Certification | FAA surfaced-recovery protocols elevate documentation burdens on subsystem suppliers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with undersea systems program managers, autonomy software architects, offshore engineering procurement leads, and Navy safety case engineers; and secondary validation through Department of Defense Unmanned Campaign Framework disclosures, FAA certification protocol documentation, SEC 10-K filings from prime contractors, and Canadian Department of National Defence procurement guidelines. Bottom-up platform deployment estimates triangulated against top-down defense budget allocation analysis.
Forecast inputs spanned hull form factor adoption curves, battery chemistry transition timelines, and regulatory certification velocity across the projection horizon. Segmentation modeling incorporated product type, end user budget tier, application water depth, and technology architecture dimensions. CAGRs derived from elasticity-adjusted demand curves calibrated to historical Navy fleet expansion patterns and Gulf of Mexico infrastructure decommissioning schedules.
Practitioners should monitor lithium-sulfur battery commercialization milestones, ITAR protocol amendments, and Arctic sovereignty program funding shifts for early signals requiring forecast revision. Cross-checking against Department of Defense future years defense program budget submissions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Remote Weapon Systems Market