
 North America ROV Market | 2026-2036
North America ROV Market Size, Share, and Industry Trends Forecast 2026-2036
North America ROV Market Analytics
Buyer concentration among supermajor oil companies is recalibrating procurement volumes across the North America ROV supply base. Oceaneering International Inc. anchors the Gulf of Mexico service layer through its integrated robotics and vessel fleet. Forum Energy Technologies Inc. differentiates via tooling and subsea work systems that bundle with ROV spreads. L3Harris Technologies Inc. leverages defense channel relationships to sustain military underwater vehicle programs alongside commercial opportunities.
A remotely operated vehicle is an uncrewed underwater system linked to a surface vessel or platform through a tethered umbilical carrying power, data, and control signals, typically operating at depths exceeding 3,000 meters for subsea intervention and observation tasks. Work-class ROVs dominate capital allocation due to heavy-lift tooling requirements in deepwater field development, while inspection ROVs capture recurring revenue streams through pipeline integrity management contracts. The tethered deployment mode retains the largest installed base despite autonomous underwater vehicle advances in survey applications.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer and wellhead inspections that directly sustain ROV utilization rates in federal waters. Transport Canada and the Canadian Coast Guard enforce submarine cable protection zones that shape inspection ROV deployment patterns off Nova Scotia and British Columbia. Stakeholders must weigh tethered system upgrade cycles against autonomous platform maturation timelines when committing capital to fleet renewal strategies.
Market Dynamics
The US Bureau of Safety and Environmental Enforcement's well integrity mandates are forcing offshore operators to expand subsea inspection frequencies, compressing ROV deployment cycles and recalibrating fleet utilization models across Gulf of Mexico contractors.
Growth Catalysts
- Deepwater field development:Heavy-lift tooling requirements in the US Gulf of Mexico and Mexican territorial waters sustain capital allocation toward work-class ROV systems.
- BSEE inspection mandates:Federal blowout preventer and wellhead inspection rules directly tether ROV utilization rates to regulatory compliance calendars.
- Pipeline integrity management:Recurring revenue streams from subsea pipeline contracts anchor inspection-class ROV deployment patterns off Nova Scotia and British Columbia.
Market Restraints
- Tethered system capex intensity:Surface vessel dependency and umbilical maintenance costs constrain fleet expansion for mid-tier service contractors.
- Autonomous underwater vehicle substitution:AUV advances in survey applications threaten inspection-class ROV market share in non-intervention missions.
- Gulf of Mexico supplier concentration:Equipment and tooling vendors cluster in Houston, creating geographic supply risk during hurricane disruptions.
Strategic Opportunities
- Canadian Atlantic offshore:Transport Canada submarine cable protection zones open inspection ROV deployment corridors off Newfoundland and Labrador.
- Military-commercial convergence:Defense underwater vehicle programs create technology transfer pathways for dual-use ROV platforms.
- Integrated robotics bundling:Service providers combining ROV spreads with subsea tooling capture larger contract scopes from supermajor operators.
Industry Challenges
- Pilot-technician scarcity:Deepwater ROV operation requires specialized training pipelines that lag fleet expansion timelines.
- Legacy vessel integration:Tether management system retrofits on aging offshore support vessels create operational downtime and certification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America ROV Market |
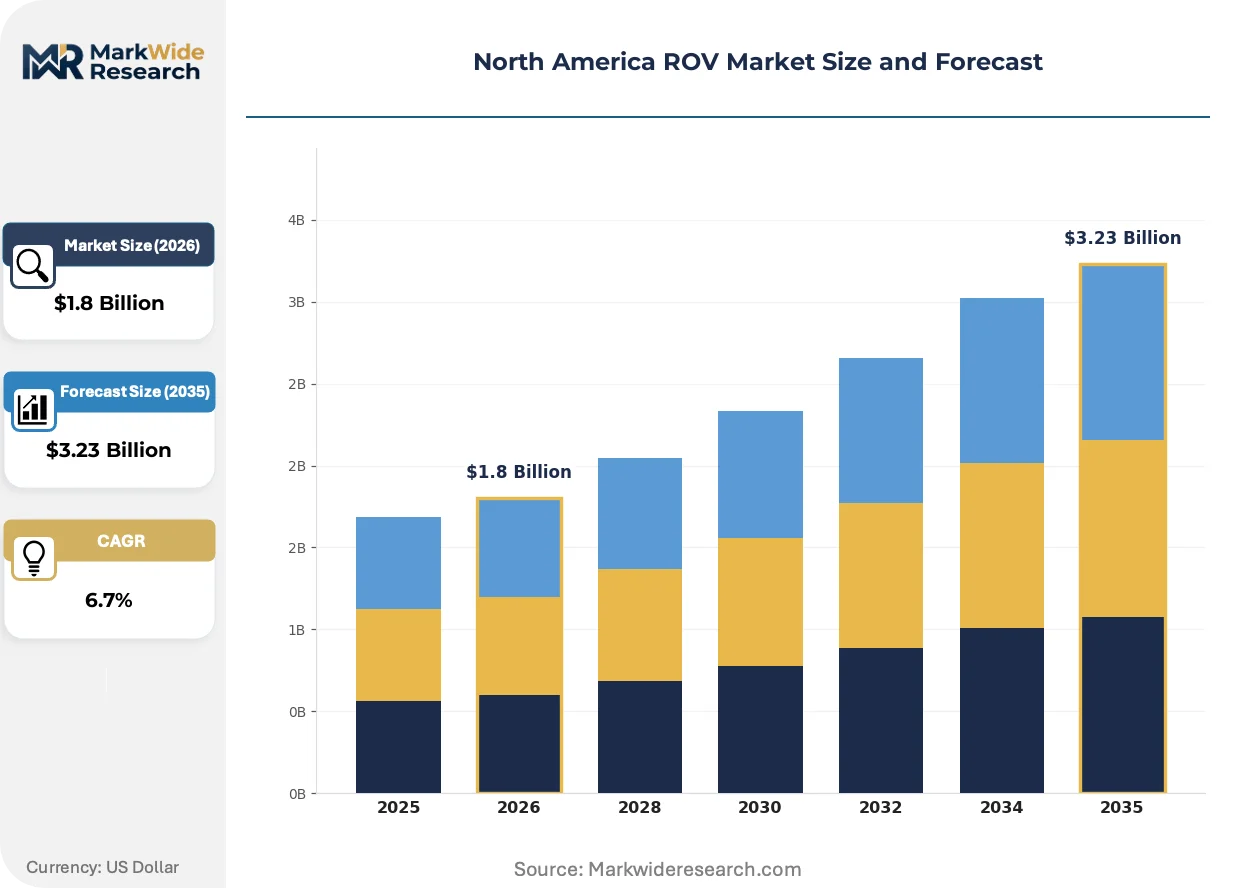
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inspection ROVs, Work-class ROVs, Mini ROVs, Hybrid ROVs End User: Oil & Gas, Marine Research, Military, Telecommunications Deployment Mode: Surface, Tethered, Autonomous, Hybrid Application: Pipeline Inspection, Underwater Construction, Environmental Monitoring, Search & Recovery |
| Companies Covered | Oceaneering International Inc., DOF Subsea AS, Helix Energy Solutions Group Inc, TechnipFMC PLC, DeepOcean AS, Forum Energy Technologies Inc., L3Harris Technologies Inc., Teledyne SeaBotix, VideoRay, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America ROV Market Evolving Landscape
Subsea robotics architecture is fragmenting into interchangeable component layers, enabling operators to reconfigure tooling packages without full system replacement and compressing upgrade cycles across the North American fleet.
Electric work-class propulsion is modularizing. Advanced thruster packages allow rapid powertrain swaps between inspection and intervention configurations. Supermajor operators in the US Gulf of Mexico are standardizing these interfaces across mixed-vendor fleets. The shift is compressing mobilization timelines and reducing vessel standby costs during tooling changeovers.
Canada's Coast Guard submarine cable protection enforcement is tightening spatial restrictions on subsea construction corridors. The regulatory friction is redirecting ROV deployment patterns toward pre-construction survey intensity and post-lay inspection frequency. British Columbia and Nova Scotia operators are absorbing higher compliance-driven ROV hours into project budgets.
Service contract unbundling is accelerating. Supermajor procurement teams are separating ROV spread provision from tooling and personnel, forcing traditional integrated providers to compete on discrete component pricing. The disaggregation is most visible in US federal waters, where spot-market vessel charters now routinely exclude full robotics packages.
North America ROV Market Segmentation
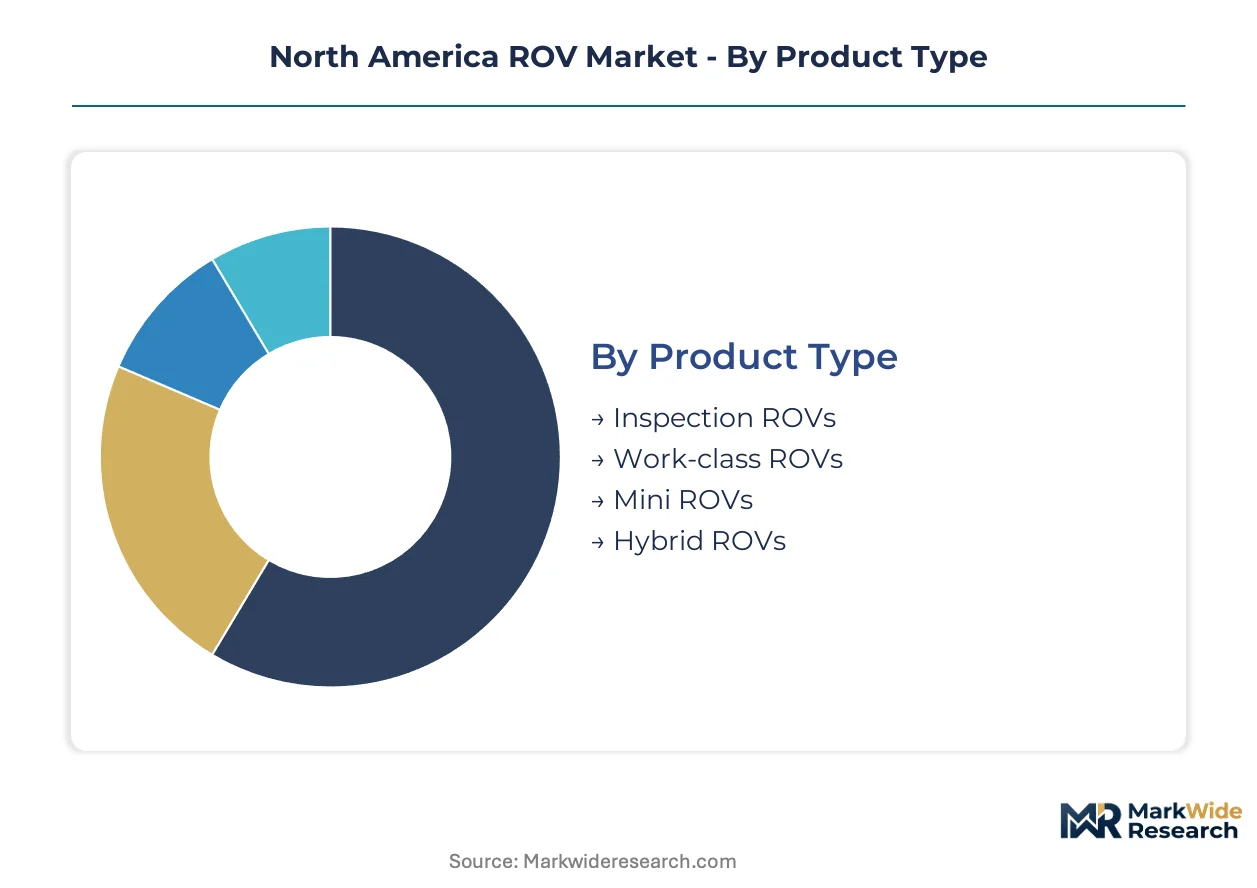
ROV procurement patterns diverge sharply across operational depth requirements and intervention complexity. Fleet composition decisions hinge on whether missions prioritize rapid visual assessment or heavy-lift subsea manipulation.
Product Type:
Customization intensity varies from standardized inspection units to bespoke work-class configurations engineered for specific wellhead geometries.
- Inspection ROVs:Compact electric propulsion systems with high-definition camera arrays and sonar payloads dominate this category. Pipeline integrity management contracts off Nova Scotia and British Columbia sustain recurring deployment schedules for these systems. The US Bureau of Safety and Environmental Enforcement mandates compress inspection cycles and expand fleet utilization.
- Work-class ROVs:Hydraulic power units rated for 250+ horsepower drive heavy-lift tooling manipulators and subsea intervention skids. Deepwater field development in the US Gulf of Mexico and Mexican territorial waters concentrates demand for these capital-intensive systems.
- Mini ROVs:Portable battery-powered units serve rapid-response hull inspection and confined-space penetration missions.
- Hybrid ROVs:Modular architecture allows reconfiguration between observation and light-intervention modes through swappable tooling packages.
Most installed capacity flows through Work-class ROVs. Expansion is steepest in Hybrid ROVs.
End User:
Contract structures range from supermajor oil company master service agreements to government procurement vehicles with multi-year technology development horizons.
- Oil & Gas:Offshore energy operators drive the largest procurement volumes through integrated drilling and production contracts. Blowout preventer inspection mandates from the US Bureau of Safety and Environmental Enforcement tether utilization directly to regulatory compliance calendars.
- Military:Defense underwater vehicle programs fund dual-use technology development with commercial spinoff pathways.
- Marine Research:Academic and government oceanographic institutions deploy ROVs for benthic sampling and deep-sea ecosystem mapping.
- Telecommunications:Submarine cable installation and repair contractors maintain specialized trenching and burial tool configurations.
Revenue concentration sits with Oil & Gas. Technology transfer momentum is strongest in Military.
Deployment Mode:
Operational trade-offs between real-time control fidelity and surface vessel independence shape architecture selection across mission profiles.
- Tethered:Copper-fiber umbilical cables deliver continuous power and high-bandwidth data for precision intervention tasks. This architecture retains the dominant installed base despite autonomous platform advances in survey applications.
- Autonomous:Pre-programmed mission profiles with acoustic positioning enable extended survey operations without surface vessel shadowing.
- Surface:Radio-controlled shallow-water systems operate without submerged tether management complexity.
- Hybrid:Switchable tethered-to-autonomous modes optimize for different mission phases within single deployments.
Fleet investment prioritizes Tethered systems. Capability development is accelerating fastest in Autonomous.
Application:
Revenue predictability varies from recurring integrity management contracts to project-based construction schedules with lump-sum pricing.
- Pipeline Inspection:Magnetic flux leakage and ultrasonic testing tool integration enables wall-thickness measurement without production shutdown. Recurring revenue streams from subsea pipeline contracts anchor inspection-class deployment patterns.
- Underwater Construction:Heavy-lift manipulators position subsea structures and conduct tie-in operations at depths exceeding 3,000 meters.
- Environmental Monitoring:Water column sampling and seabed habitat assessment support regulatory compliance and impact mitigation.
- Search & Recovery:Side-scan sonar and manipulator combinations serve accident investigation and asset retrieval missions.
Contract volume concentrates in Pipeline Inspection. Platform technology investment is expanding most quickly in Underwater Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ROV pilot-technicians cluster along the Gulf Coast from Houston to New Orleans, anchoring the continent's deepest talent pool for subsea robotics operations. Canadian offshore provinces and Mexican territorial waters draw on this expertise base while developing regional capabilities.
United States
Federal waters in the Gulf of Mexico host the densest concentration of work-class ROV deployment for deepwater field development. The US Bureau of Safety and Environmental Enforcement mandates blowout preventer and wellhead inspections that compress deployment cycles and sustain utilization rates. Houston anchors the supplier ecosystem, with equipment vendors and tooling fabricators clustering in the Energy Corridor and Port Fourchon serving as the primary offshore logistics hub.
Canada
Subsea pipeline integrity management off Nova Scotia and British Columbia drives recurring inspection ROV contracts with predictable revenue profiles. Transport Canada and the Canadian Coast Guard enforce submarine cable protection zones that redirect deployment patterns toward pre-construction survey intensity. St. John's, Newfoundland, hosts emerging offshore energy services capacity as Atlantic offshore development advances.
Mexico
Deepwater corridors in Mexican territorial waters sustain capital allocation toward heavy-lift tooling systems for field development campaigns. The National Hydrocarbons Commission oversees subsea safety regulations that align with US inspection protocols and facilitate cross-border contractor mobility. Ciudad del Carmen in Campeche Bay serves as the primary logistics concentration for southern Gulf operations.
Atlantic Canada
Offshore Newfoundland and Labrador present frontier expansion opportunities as inspection ROV deployment corridors open under evolving regulatory frameworks. The Canada-Nova Scotia Offshore Petroleum Board and Canada-Newfoundland and Labrador Offshore Petroleum Board coordinate safety mandates that shape contractor qualification requirements. Halifax maintains subsea engineering services capacity supporting regional project development.
North America ROV Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service layers in the North America ROV market. The structure concentrates around integrated service providers bundling robotics with vessels and tooling, while smaller specialists capture niche inspection and rapid-response segments. Three archetypes dominate: full-service integrated operators, component and tooling specialists, and defense-channel dual-use technology providers. Consolidation through strategic acquisitions and vertical integration into captive vessel and tooling assets represent the dominant competitive moves reshaping market positioning.
Within the integrated service tier, Oceaneering International Inc. and Helix Energy Solutions Group Inc. exemplify full-spread operators combining robotics, marine assets, and intervention capabilities. Forum Energy Technologies Inc. and L3Harris Technologies Inc. occupy positions on the component-specialist and dual-use technology vectors respectively, with L3Harris anchoring defense-commercial convergence pathways. DOF Subsea AS and DeepOcean AS represent European-headquartered operators with established North American presence, while Teledyne SeaBotix and VideoRay exemplify compact system specialists serving inspection and confined-access applications.
| Leading Market Players |
|---|
| Oceaneering International Inc. |
| DOF Subsea AS |
| Helix Energy Solutions Group Inc |
| TechnipFMC PLC |
| DeepOcean AS |
| Forum Energy Technologies Inc. |
| L3Harris Technologies Inc. |
| Teledyne SeaBotix |
| VideoRay |
| Others |
Value Network & Pricing Analysis
ROV pilot-technician concentrations along the Texas-Louisiana Gulf Coast anchor labor-cost differentials that widen pricing spreads between premium integrated service bundles and commoditized spot-market vessel charters. BSEE inspection mandates compress deployment cycles and elevate technician premiums, while Canadian and Mexican operators absorb Houston-sourced labor premiums through cross-border contractor mobility.
Pricing Analysis
Bundled service contracts combining ROV spreads with subsea tooling command premium positioning against unbundled component pricing now standard in US federal waters. Price differentiation centers on certification grade for deepwater intervention capabilities and volume scale of multi-year master service agreements. Cost compression in inspection-class tiers intensifies as AUV substitution threats force ROV providers to absorb vessel standby costs. Supermajor oil companies exhibit lowest price sensitivity due to regulatory compliance imperatives, while mid-tier independents drive spot-market bargaining.
Supply Chain Analysis
Workforce availability constraints in Houston's Energy Corridor and Port Fourchon propagate through umbilical manufacturing lead times and thruster module assembly. Component sourcing draws from US specialty cable fabricators, Norwegian hydraulic system suppliers, and Canadian subsea engineering houses. Single-source vulnerability concentrates in deepwater-rated manipulator arms and high-pressure valve packages. Distribution runs through integrated service providers maintaining captive vessel fleets and spot-market charter brokers serving project-specific demand spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ROV market functions as a regulatory compounder where BSEE well integrity mandates generate recurring demand independent of oil price cycles. Federal inspection calendars tether utilization rates to compliance-driven procurement.
For Market Incumbents: To counter AUV substitution in survey applications, anchor inspection ROV positioning through integrated sensor payloads that exceed autonomous platform capabilities. Deepen backward integration into thruster manufacturing to compress propulsion upgrade cycles and capture margin from electric work-class retrofits. For New Entrants and Emerging Players: Mid-tier Gulf of Mexico independents represent the most penetrable buyer archetype, underserved by full-spread integrated providers and squeezed by supermajor procurement consolidation. Target rapid-response mini-ROV deployment for unplanned well intervention with pay-per-day pricing that avoids capital-intensive vessel commitments. For Investors and Strategic Acquirers: Defense contractors with underwater vehicle programs are the most active acquirer in this space, seeking dual-use technology transfer pathways and commercial revenue diversification. Acquisition focus should center on tooling specialists with proprietary manipulator IP. Monitor BSEE enforcement intensity as the inflection signal; expanded inspection frequency mandates directly expand addressable ROV hours.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Retrofit Programs | Modular thruster swaps compress mobilization timelines for Gulf of Mexico operators. |
| Submarine Cable Protection Compliance | Transport Canada enforcement redirects ROV deployment toward pre-construction survey intensity. |
| Integrated Robotics Bundling | Tooling-plus-spread contracts capture larger scopes from supermajor procurement teams. |
| Defense-Commercial Technology Transfer | L3Harris and dual-use providers leverage military R&D for commercial ROV platform advancement. |
| Hybrid ROV Architecture Development | Swappable tooling packages enable reconfiguration between inspection and intervention modes. |
Research Methodology
Multiple input streams — primary interviews with ROV operations managers, subsea tooling procurement leads, and BSEE regulatory compliance officers; secondary validation through SEC filings of listed service contractors, US offshore lease databases, and Canadian Coast Guard cable protection enforcement records — were reconciled through bottom-up fleet utilization modeling and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning ROV class tier, deployment mode architecture, end-user contract structure, and regional regulatory cluster intensity. CAGRs were derived from installed base replacement cycles and regulatory-mandated inspection frequency expansion. Forecast inputs incorporated Gulf of Mexico rig count trajectories and Canadian Atlantic offshore development timelines.
Underlying measurement precision varies by segment; tethered work-class ROV utilization carries tighter precision than emerging hybrid platform adoption curves. Forecasts reflect assumptions regarding BSEE enforcement continuity and electric propulsion cost curves. Material deviation in federal inspection mandate expansion or AUV intervention capability breakthrough warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Autonomous Technology Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
United States Aerostat Systems Market