
 Aerospace Robotics Market | 2026-2036
Aerospace Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Robotics Market Intelligence
The role of automation in commercial aircraft assembly is hardening, while its application in satellite and launch vehicle production expands. KUKA AG specializes in high-payload robotic systems for structural assembly and drilling applications. FANUC Corporation leverages its extensive machine vision and control systems portfolio for precision inspection and finishing tasks. These suppliers are key to enabling higher production rates for next-generation aircraft programs.
Aerospace robotics involves the design and deployment of automated systems engineered for high-precision tasks in aviation and space manufacturing. These systems often require positional accuracy measured in micrometers and must handle delicate composite materials without causing damage. Articulated robots continue to dominate assembly and material handling applications due to their range of motion. However, collaborative robots represent the fastest-growing product type, enabling safer human-robot interaction in shared workspaces for inspection and light assembly.
Regulatory frameworks from bodies like the US FAA and certification requirements such as CE marking in Europe govern the validation of automated manufacturing processes. These standards ensure that robotic systems meet stringent safety and quality benchmarks for critical aerospace components. Navigating the capital investment required for automation against the need for skilled workforce development will define competitive advantage for manufacturers.
Market Dynamics
The imperative to clear historic aircraft order backlogs while industrializing composite-intensive airframes is the central force shaping aerospace robotics. This pressure demands automation that boosts throughput without compromising the structural integrity of delicate materials.
Growth Catalysts
- Automated Fiber Placement (AFP):Essential for producing composite fuselages and wings, this technology drives demand for high-precision, multi-axis robotic systems.
- Satellite Constellation Production:The shift to mass-producing small satellites requires high-volume robotic assembly, creating a new industrial-scale demand driver.
- National Industrial Policies:Initiatives in the United States and France to modernize aerospace supply chains are incentivizing capital investment in automation.
Market Restraints
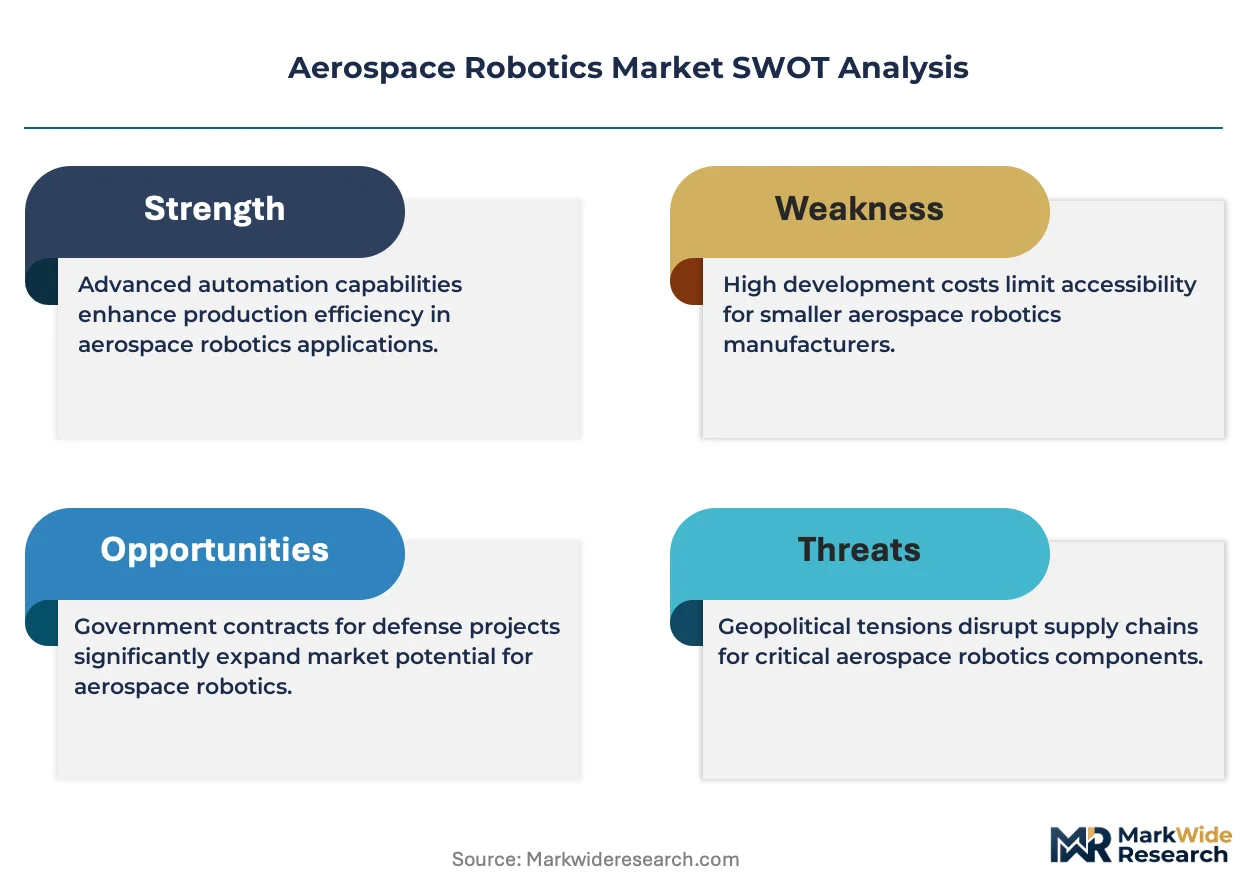
- High Capital Outlay:The significant initial investment for robotic cells and facility modifications is a major barrier for Tier 2 and Tier 3 suppliers.
- Non-Standardized Components:A lack of fastener and sub-assembly standardization complicates robot programming and adaptability, requiring extensive, costly customization.
- Stringent Process Validation:Automated processes require lengthy and expensive validation under FAA and EASA standards, delaying deployment.
Strategic Opportunities
- Maintenance, Repair, and Overhaul (MRO):Applying robotics to automated inspection and repair in the MRO sector represents a large, underpenetrated service market.
- Digital Twin Integration:Combining robots with digital twins enables offline programming and process optimization, creating new service revenue streams.
- Emerging Aerospace Hubs:Establishing integration capabilities in growing clusters within India and Mexico can capture demand from new manufacturers.
Industry Challenges
- Workforce Skills Gap:A shortage of technicians skilled in programming and maintaining complex aerospace-grade robotic systems constrains effective deployment and uptime.
- Legacy System Interoperability:Integrating modern robotic platforms with existing manufacturing execution systems (MES) is a significant technical and financial hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Robotics Market |
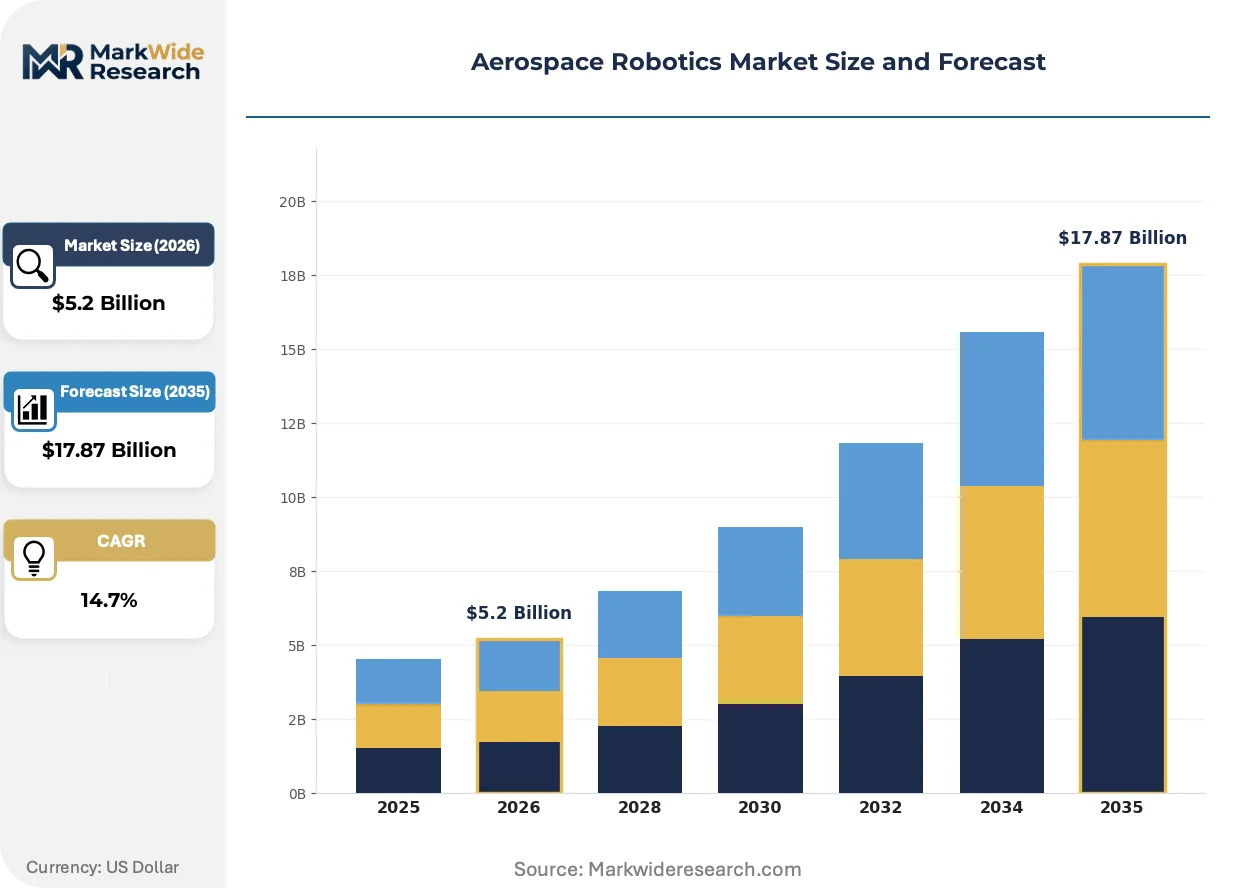
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $17.87 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Cartesian Robots, Collaborative Robots Technology: Machine Vision, Force Feedback, Artificial Intelligence, Sensor Fusion Application: Assembly, Inspection, Maintenance, Material Handling End User: Aircraft Manufacturers, Space Agencies, Defense Contractors, Component Fabricators |
| Companies Covered | ABB, KUKA AG, FANUC Corporation, Yaskawa Electric Corporation, Electroimpact Inc., OC Robotics, Universal Robots A/S, Kawasaki Heavy Industries Ltd, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Robotics Market Strategic Shifts & Innovations
The evolution from rigid, single-task automation to more flexible, sensor-driven systems is a defining theme. This shift enables robots to handle greater variability, expanding their applicability beyond high-volume, repetitive tasks.
Advanced sensor fusion combines vision, force-torque, and laser data to give robots perception-like capabilities. Aerospace component fabricators are adopting this for tasks like drilling on curved surfaces and gap-and-shim measurement. This real-time feedback loop is rewriting the economic case for automating complex assembly operations.
The EU AI Act introduces a risk-based framework for artificial intelligence, classifying systems in critical infrastructure like aviation as high-risk. This mandates stringent conformity assessments and risk management for AI-powered robotics in quality control. Robot manufacturers serving Europe must invest in auditable software to prove compliance.
A shift from purchasing standalone robots to procuring complete, turnkey automated manufacturing cells is gaining traction. This model transfers integration risk from the airframer to specialized system integrators or robot OEMs. The trend is most prominent in new factory setups in the United States and France.
Aerospace Robotics Market Segmentation
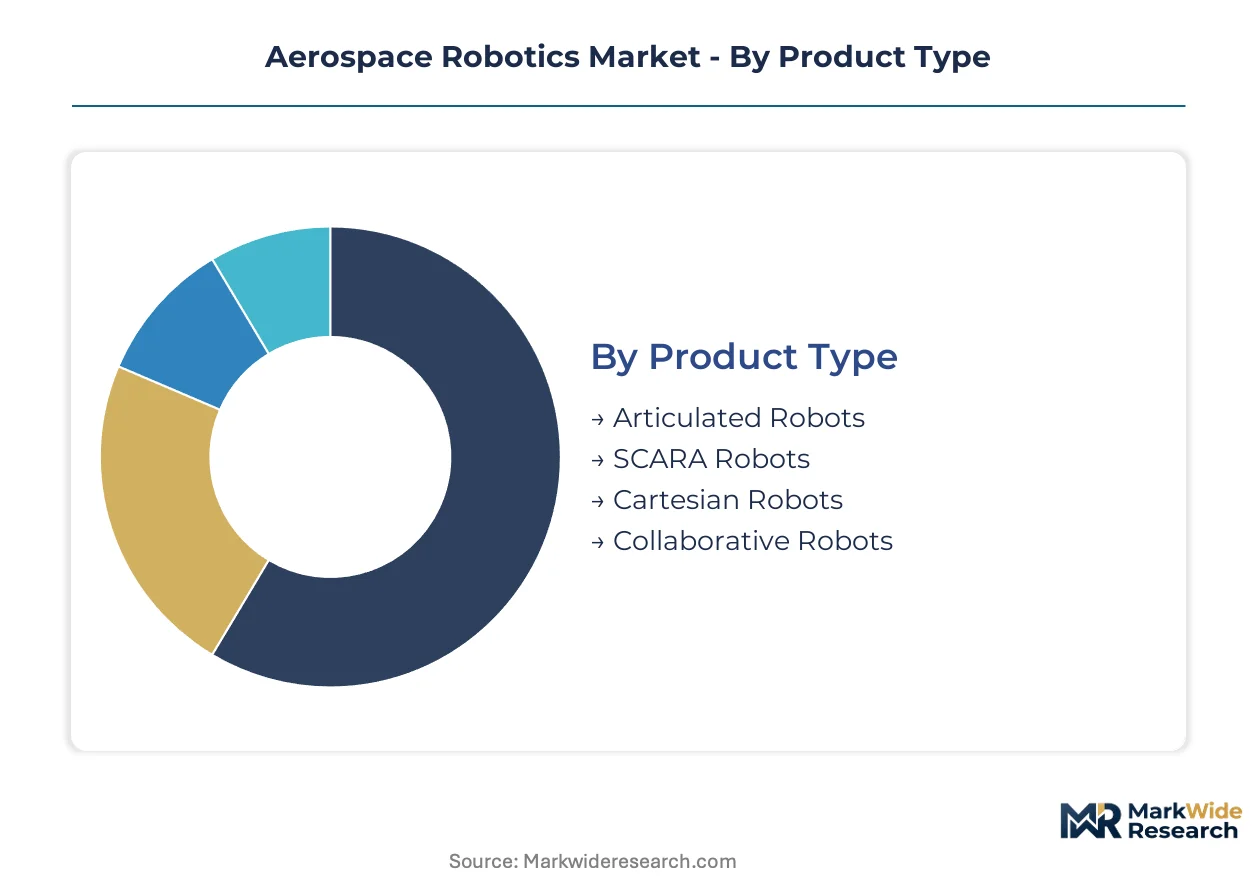
The aerospace robotics market delineates into several key segments, reflecting the diverse technological requirements and operational demands of the aviation and space industries. Understanding these distinctions is crucial for manufacturers targeting specific niches and for suppliers developing specialized robotic solutions.
Product Type:
The functional specifications of robotic arms dictate their suitability for precise aerospace manufacturing tasks.
- Articulated Robots:These multi-jointed robots offer extensive reach and flexibility, making them ideal for large-scale structural assembly and complex drilling operations on aircraft fuselages. Demand for these systems is high among major aircraft manufacturers in the United States.
- Collaborative Robots:Designed for safe human-robot interaction, cobots are smaller, more agile systems used for inspection, light assembly, and material handling in shared workspaces. Their demand is expanding most quickly in Europe, particularly for quality control processes.
- SCARA Robots:Selective Compliance Articulated Robot Arm (SCARA) robots excel in high-speed, high-precision pick-and-place tasks within a cylindrical workspace. These systems find utility in electronics assembly for avionics components.
- Cartesian Robots:Operating on three linear axes, Cartesian robots provide high rigidity and accuracy for tasks requiring precise linear motion, such as gantry systems for large-format additive manufacturing.
Mature deployment sits with Articulated Robots. Newer deployment is concentrated in Collaborative Robots.
Technology:
The integration of advanced sensing and processing capabilities defines the intelligence and adaptability of aerospace robotic systems.
- Sensor Fusion:This technology combines data from multiple sensors like vision, force-torque, and laser scanners to provide robots with enhanced environmental perception and real-time feedback for complex tasks. Component fabricators in France are increasingly adopting sensor fusion for adaptive drilling on curved surfaces.
- Machine Vision:Utilizing cameras and image processing algorithms, machine vision systems enable robots to perform precision inspection, part recognition, and guidance for assembly tasks. This technology is critical for quality assurance in next-generation aircraft programs.
- Artificial Intelligence:AI algorithms enhance robotic capabilities through predictive maintenance, optimized path planning, and autonomous decision-making in unstructured environments. Its application is emerging in complex MRO scenarios.
- Force Feedback:This technology allows robots to sense and respond to contact forces, crucial for delicate material handling and precise deburring operations without damaging sensitive composite structures.
The integration of Machine Vision remains foundational, while Sensor Fusion is rapidly expanding its footprint.
Application:
Robotics address a wide spectrum of operational needs across the aerospace manufacturing lifecycle, from initial fabrication to post-production maintenance.
- Assembly:This application involves robots performing tasks like drilling, fastening, and component placement for aircraft structures and sub-assemblies. The imperative to clear historic aircraft order backlogs drives significant investment in automated assembly.
- Inspection:Robots equipped with vision systems and sensors conduct precise quality checks, defect detection, and dimensional verification of aerospace components. This application is vital for ensuring compliance with stringent regulatory frameworks from bodies like the US FAA.
- Maintenance:Robotic systems are beginning to automate routine maintenance, repair, and overhaul (MRO) tasks, including automated inspection of airframe surfaces and component repair. This represents a strategic opportunity for service market growth.
- Material Handling:Robots manage the movement, loading, and unloading of heavy or delicate aerospace materials and components within manufacturing facilities. This reduces manual labor and improves safety.
High-volume manufacturing relies heavily on Assembly, with Maintenance seeing specialized growth.
End User:
The primary beneficiaries and demand generators for aerospace robotics span the entire aerospace value chain, each with distinct needs and operational scales.
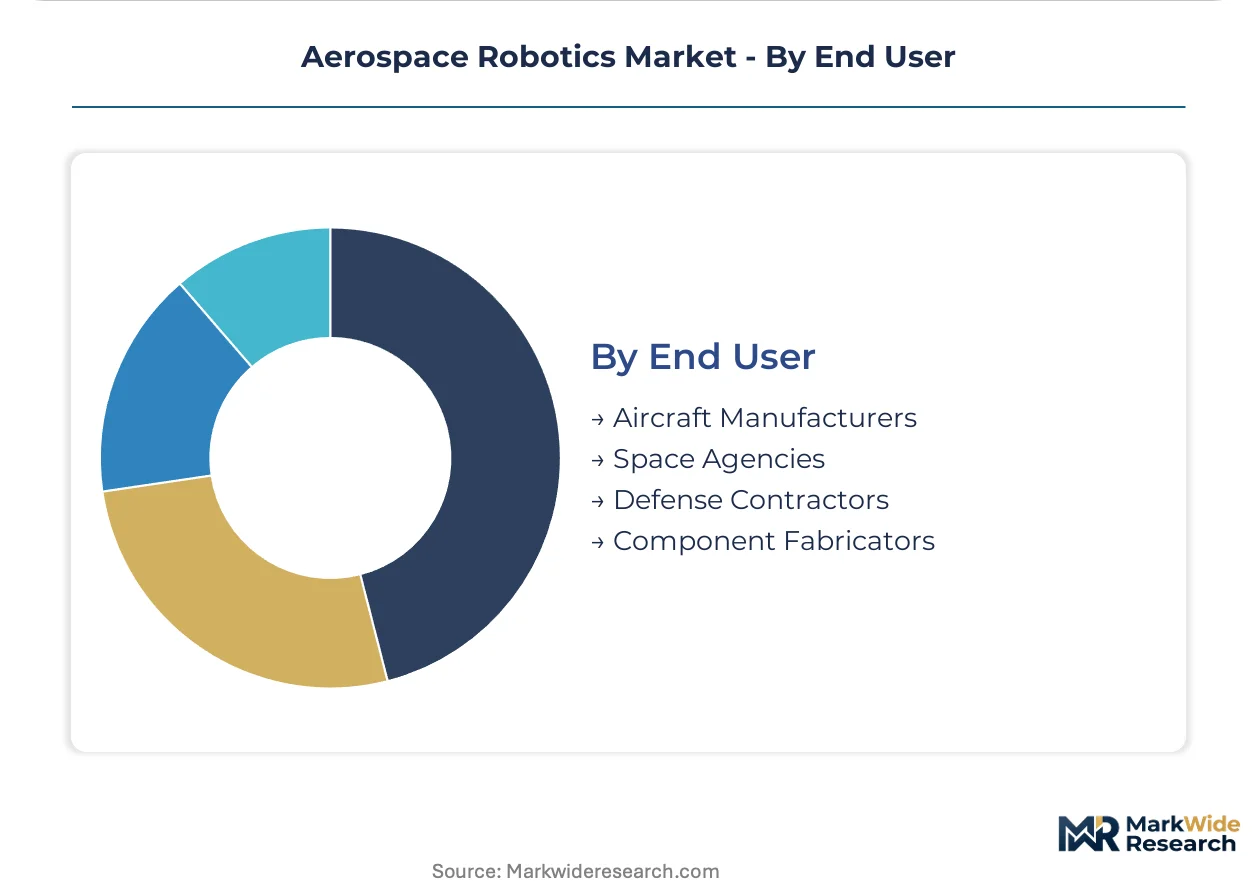
- Aircraft Manufacturers:These large-scale enterprises integrate advanced robotic systems for the production of commercial and military aircraft, focusing on high throughput and precision for composite-intensive airframes. Their demand concentrates in established aerospace clusters in the United States and France.
- Component Fabricators:Tier 1 and Tier 2 suppliers adopt robotics for high-precision tasks like automated fiber placement and drilling of intricate parts. These fabricators are critical enablers for next-generation aircraft programs.
- Space Agencies:Government and private space organizations utilize robotics for the assembly and testing of satellites and launch vehicles, particularly with the shift towards mass-producing small satellites. This creates a new industrial-scale demand driver.
- Defense Contractors:These entities deploy robotics for manufacturing advanced military aircraft, drones, and weaponry, often requiring specialized systems for classified or highly robust applications.
Demand from Aircraft Manufacturers drives significant investment, while Space Agencies represent a niche but critical market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad's aerospace special economic zone, alongside similar initiatives in France and the United States, drives significant capital investment into aerospace robotics. These zones concentrate demand for advanced automation solutions to meet ambitious production targets. National industrial policies often incentivize these manufacturing clusters.
United States
The United States leads demand for articulated robotic systems in commercial aircraft assembly and defense applications. US FAA regulations govern the validation of automated manufacturing processes, ensuring stringent safety and quality. The Seattle-Everett corridor, home to major aircraft manufacturers, consistently deploys new robotic systems for airframe production.
France
French aerospace clusters demonstrate high demand for sensor fusion technology in component fabrication. The EU AI Act mandates stringent conformity assessments for AI-powered robotics in critical infrastructure like aviation. Toulouse, a primary aerospace hub, integrates advanced robotic solutions for Airbus assembly lines and composite material handling.
Germany
Germany's industrial manufacturing base supports a strong market for high-payload robotic systems, particularly for structural assembly. CE marking requirements ensure robotic systems meet European safety and quality benchmarks. The Augsburg region, housing major robotics manufacturers, develops advanced automation for various aerospace applications.
India
India's emerging aerospace hubs are driving demand for high-volume robotic assembly, especially for satellite constellation production. The government's PLI scheme encourages domestic manufacturing and capital investment in advanced technologies. Bengaluru's aerospace and defense sector is rapidly expanding its robotic integration capabilities for new projects.
Mexico
Mexican aerospace manufacturing is attracting investment in robotics for assembly and MRO applications. Free trade zones and investment incentives support the establishment of new manufacturing facilities. The Querétaro aerospace cluster is a focal point for foreign direct investment in automated production systems.
Aerospace Robotics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a few large industrial automation firms dominating the core robotics hardware. The market structure exhibits a tiered consolidation, where established global players compete with niche integrators and software providers. Strategic archetypes include diversified industrial giants, specialized aerospace automation developers, and collaborative robotics innovators. Companies pursue strategic partnerships and portfolio diversification to expand their application reach.
Diversified industrial giants like KUKA AG, a German industrial robotics firm, represent high-payload systems critical for structural assembly and drilling applications. FANUC Corporation, a Japanese automation company, exemplifies advanced machine vision and control systems for precision inspection and finishing tasks. Universal Robots A/S, a Danish collaborative robotics specialist, occupies a position in the rapidly expanding market for human-robot interaction in shared workspaces. These companies collectively anchor the technology development across various aerospace applications, addressing both heavy-duty manufacturing and delicate assembly requirements.
| Leading Market Players |
|---|
| ABB |
| KUKA AG |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| Electroimpact Inc. |
| OC Robotics |
| Universal Robots A/S |
| Kawasaki Heavy Industries Ltd |
| Lockheed Martin |
| Others |
Cost & Logistics Intelligence
A composite material cost index, reflecting prices of advanced carbon fiber and resins, cascades through the aerospace robotics supply chain, influencing the final pricing tiers for high-precision robotic systems. This cost structure impacts capital investment decisions for component fabricators and end-users, particularly for composite-intensive airframes.
Pricing Analysis
Lead-time-driven pricing for complex aerospace robotic systems often commands a premium for rapid deployment and integration services. The pricing model primarily operates on a project-based and contract-based long-term agreement structure due to the high customization required. Price differentiation stems from the level of system integration, specific aerospace certifications like FAA or CE marking, and the scope of after-sales support. Pricing pressure stems from the significant capital outlay faced by Tier 2 and Tier 3 suppliers, while major aircraft manufacturers exhibit lower price sensitivity for critical assembly systems.
Supply Chain Analysis
The aerospace robotics supply chain primarily sources high-precision components like servo motors and advanced sensors from industrial automation hubs in Germany and Japan. Specialized robotic arms originate from manufacturers such as KUKA AG, FANUC Corporation, and Universal Robots A/S. A structural supply chain risk involves single-source vulnerability for highly specialized sensor fusion technology or advanced AI-powered control systems. Distribution generally occurs through direct sales channels from major robot OEMs to large airframers, complemented by specialized system integrators for smaller fabricators and MRO providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing a significant technology-transition phase, with flexible, sensor-driven systems like collaborative robots actively displacing legacy rigid automation in various applications.
For Market Incumbents:Lock in long-term strategic partnerships with major aircraft manufacturers to secure recurring revenue streams and influence next-generation program requirements. Invest heavily in research and development for AI-powered robotics to overcome the workforce skills gap and enhance autonomy. Expand capabilities in auditable software development to meet stringent regulatory frameworks like the EU AI Act. This strategy mitigates threats from emerging specialized integrators and non-standardized component challenges.
For New Entrants and Emerging Players:Online configurators and digital engineering platforms represent a key digital-channel route for new entrants to showcase specialized robotic solutions. Target the underpenetrated Maintenance, Repair, and Overhaul (MRO) sector with automated inspection and repair systems. Focus on developing cost-effective, modular collaborative robot solutions for light assembly and inspection tasks. A go-to-market strategy emphasizing turnkey automated manufacturing cells can lower integration barriers for Tier 2 and Tier 3 suppliers.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking to consolidate niche technology providers or specialized system integrators. The market demonstrates long-term viability, projected to expand significantly as aerospace manufacturing industrializes further. Prioritize companies with proven expertise in sensor fusion, AI-driven path planning, or specialized robotic end-effectors for delicate composite materials. Increased standardization of aerospace components across the industry will serve as a critical signal to watch for accelerated investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Sensor Fusion | Enhances robotic perception for complex tasks, crucial for composite material handling. |
| Develop Turnkey Integration Solutions | Reduces deployment risk for manufacturers, accelerating automation adoption rates. |
| Expand Collaborative Robotics Portfolio | Addresses demand for safer human-robot interaction in shared aerospace workspaces. |
| Target MRO Sector Automation | Unlocks a large, underpenetrated service market for inspection and repair. |
| Establish Regional Integration Hubs | Captures demand from emerging aerospace manufacturing clusters in India and Mexico. |
Research Approach
Document review covered FAA/EASA regulations, company annual reports, industry association publications, and academic journals on robotics, complemented by interviews with aerospace engineers, manufacturing plant managers, robotics R&D leads, and regulatory compliance officers. This primary research was triangulated with secondary data from trade databases and technical specifications, ensuring a comprehensive market view. Both bottom-up data from component fabricators and top-down validation from aircraft manufacturers informed the analysis.
The forecast framework cross-references historical market performance with expert panel input, providing projections across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional manufacturing cluster. Compound annual growth rates were derived from historical adoption trends and projected industrialization rates of composite airframes and satellite constellation production. Key forecast inputs included global aircraft order backlogs and planned satellite launch schedules.
The model holds under current technological and regulatory conditions; deviation in geopolitical stability, faster-than-expected regulatory evolution, or unforeseen technological breakthroughs would shift market projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Europe Aerospace Robotics Market