
 Europe Unmanned Systems Market | 2026-2036
Europe Unmanned Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Unmanned Systems Market Foresight
Software-defined mission payloads is consolidating as the dominant service layer across European unmanned platforms, shifting revenue from hardware sales to recurring capability upgrades. Airbus SE leverages its pan-European manufacturing footprint to anchor large-scale UAV production for military end users. Thales Group sustains competitive positioning through proprietary sensor integration and encrypted datalink architectures. Quantum-Systems GmbH specializes in vertical take-off and landing electric platforms for tactical reconnaissance missions.
Europe unmanned systems encompass aircraft, ground vehicles, marine systems, and hybrid platforms operating through autonomous navigation, remote control, AI-based systems, or communication links, with operational endurance typically spanning 30 minutes to 40 hours depending on propulsion architecture and payload weight. These systems serve surveillance, agriculture, delivery, and infrastructure inspection applications across military, commercial, government, and research institutional end users. Aircraft platforms dominate current procurement volumes given established defense spending patterns, while AI-based systems capture expanding margin pools as autonomy requirements intensify. Marine systems represent the fastest-growing product category driven by underwater infrastructure monitoring needs in the North Sea and Baltic corridors.
EASA's drone regulatory framework, CE marking requirements, and EU AI Act compliance standards collectively shape product certification timelines and operational authorization across member states. Military procurement further channels through national defense ministries and NATO standardization agreements that dictate interoperability specifications. Stakeholders must monitor how forthcoming EU defense industrial strategy revisions redistribute funding eligibility across cross-border consortium structures.
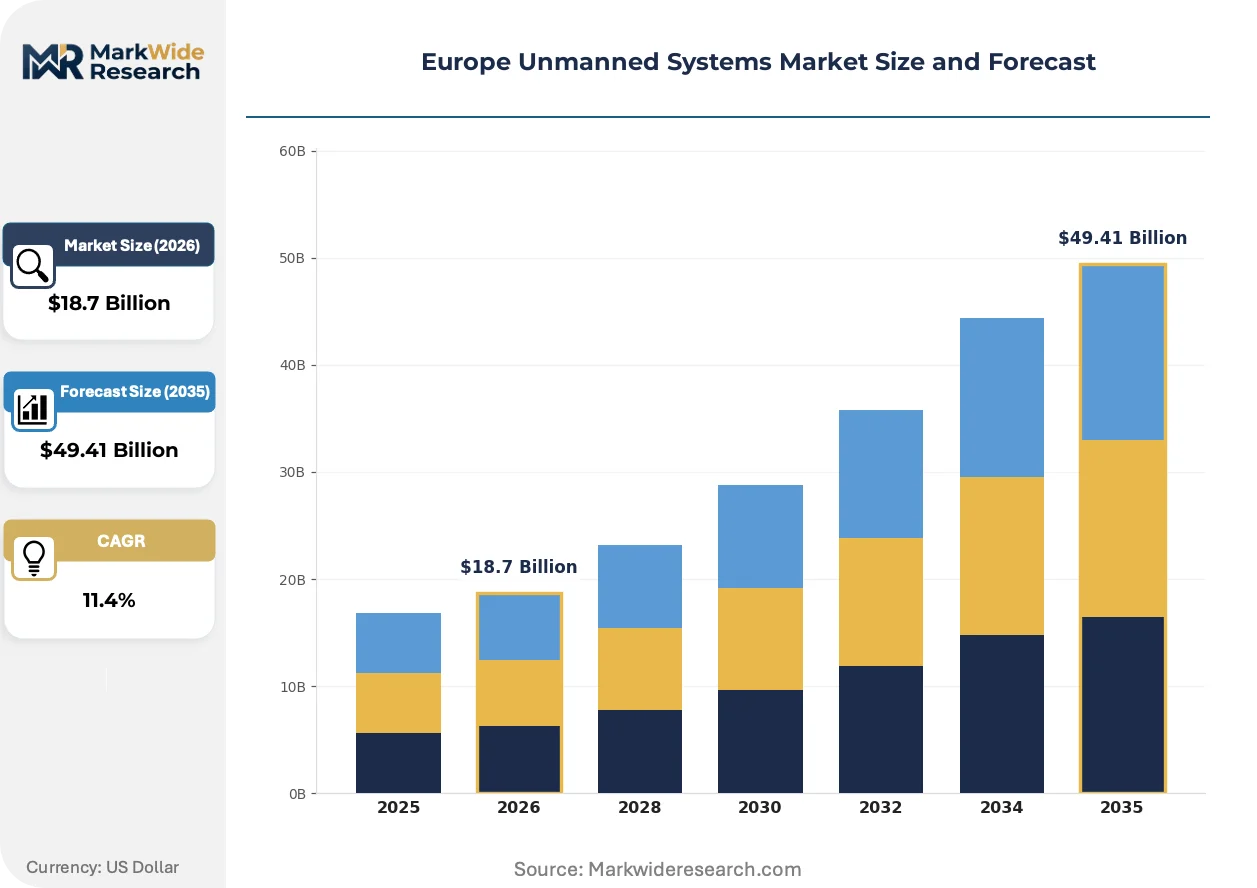
Market Dynamics
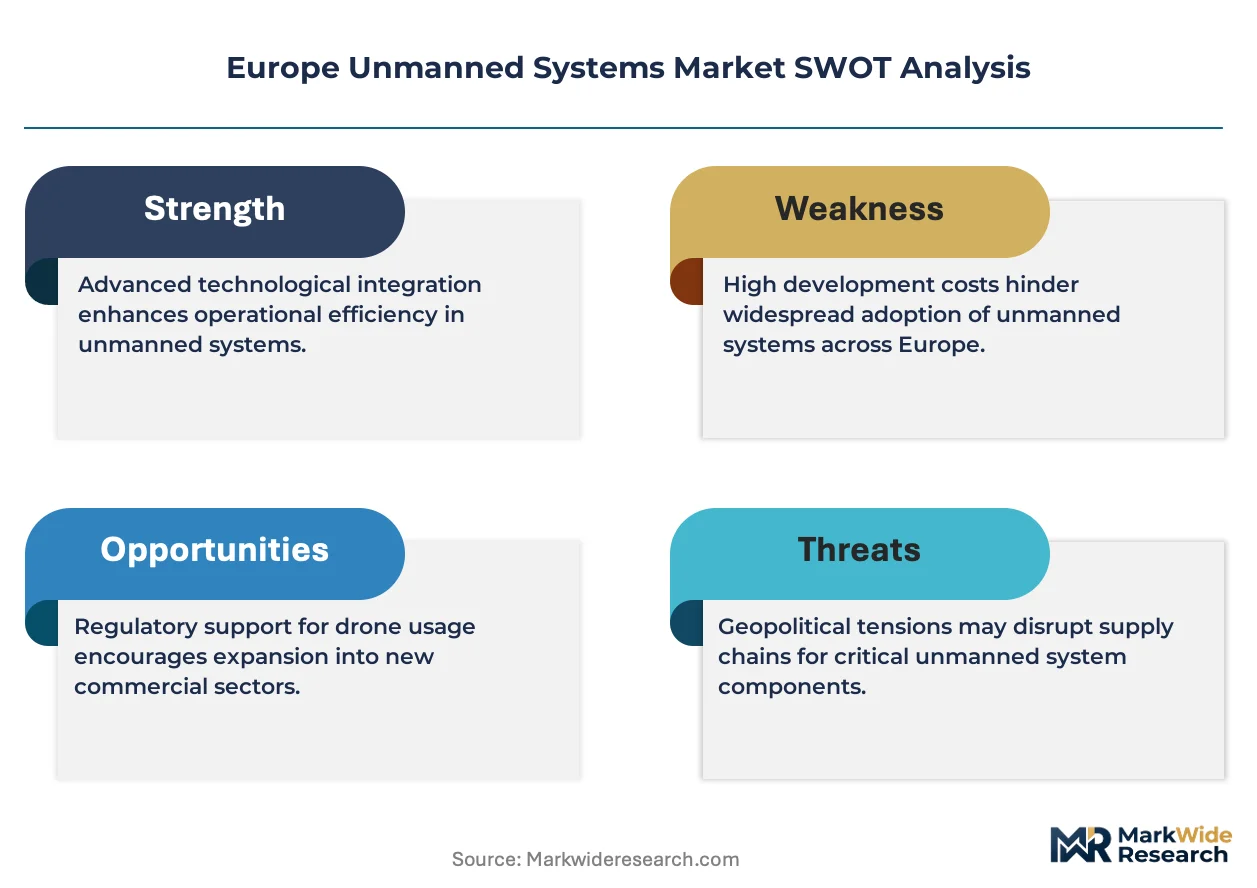
Software-defined mission payloads are consolidating as the dominant service layer across European unmanned platforms, shifting revenue from hardware sales to recurring capability upgrades and creating new competitive moats around data architecture ownership.
Growth Catalysts
- NATO Standardization Agreements:Interoperability mandates accelerate fleet modernization programs across allied defense ministries, creating synchronized procurement cycles for unmanned aerial platforms.
- EASA Regulatory Harmonization:Unified certification standards reduce cross-border operational authorization timelines, lowering market entry barriers for commercial drone operators in member states.
- North Sea Infrastructure Monitoring:Offshore energy operators deploy autonomous marine systems for subsea pipeline inspection, generating sustained demand for underwater platform endurance.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian manufacturing hubs, exposing European platform assemblers to input cost volatility and logistics bottlenecks.
- EU AI Act Compliance Burden:Risk classification requirements for autonomous decision-making systems extend product development timelines and certification costs for AI-enabled platforms.
- Satellite Communication Substitution:Low Earth orbit connectivity providers offer competing surveillance and data relay services, pressuring high-altitude long-endurance UAV value propositions.
Strategic Opportunities
- Baltic Corridor Marine Expansion:Underwater infrastructure monitoring demand in Estonian, Latvian, and Lithuanian territorial waters outpaces current autonomous underwater vehicle supply.
- CE Marking Fast-Track Pathways:EASA's specific category operational authorization streamlines beyond-visual-line-of-sight approvals for agricultural spraying and delivery applications.
- AI-Edge Computing Convergence:Onboard inference chips enable real-time target recognition without ground station dependency, opening tactical military segments previously reserved for manned assets.
Industry Challenges
- Embedded Systems Engineering Scarcity:Flight control software development requires specialized aerospace-IT hybrid talent pools that remain underdeveloped in Central European labor markets.
- Cross-Border Frequency Allocation:C-band and L-band spectrum coordination delays between national regulators fragment command-and-control link standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Unmanned Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Ground Vehicles, Marine Systems, Hybrid Systems Technology: Autonomous Navigation, Remote Control, AI-Based Systems, Communication Links Application: Surveillance, Agriculture, Delivery, Infrastructure Inspection End User: Military, Commercial, Government, Research Institutions |
| Companies Covered | Airbus SE, BAE Systems, Thales Group, Leonardo S.p.A., Saab AB, Parrot Drones SA, Microdrones GmbH, Rheinmetall AG, Quantum-Systems GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Unmanned Systems Market Shifts & Advancements
Autonomy architectures are absorbing investment flows previously directed toward airframe manufacturing, compressing hardware margins while expanding software and sensor payload value capture across European defense and commercial segments.
Swarm coordination algorithms are absorbing mission planning functions previously executed by individual operator stations. Military end users in Germany and France pilot multi-vehicle collaborative reconnaissance at platoon level, compressing sensor-to-shooter timelines and reducing single-point-of-failure exposure in contested electromagnetic environments.
EU AI Act risk-tier classification is absorbing compliance engineering resources across unmanned system developers. High-risk autonomous categorization triggers mandatory conformity assessment procedures that extend product launch timelines by 12-18 months, with German industrial corridors investing heavily in explicable AI documentation systems to preempt regulatory friction.
Defense procurement patterns are absorbing outcome-based contracting structures that shift payment milestones from delivery acceptance to operational availability metrics. French and British ministry buyers now structure UAV acquisitions around flight-hour guarantees, transferring maintenance risk to original equipment manufacturers and compressing traditional spare parts revenue streams.
Europe Unmanned Systems Market Segmentation
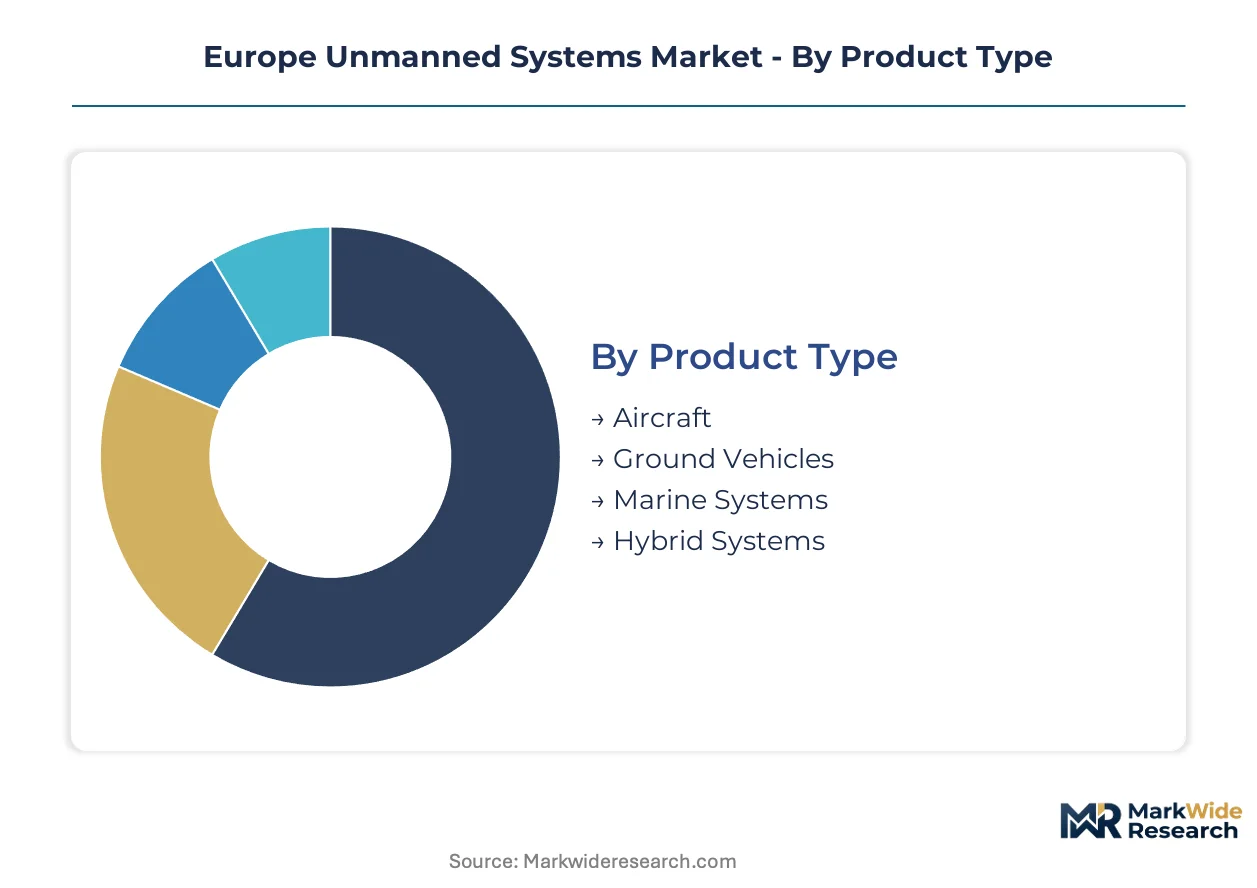
European unmanned systems procurement channels diverge sharply across defense, commercial, and institutional buyers, with certification pathways under EASA and national military standards fragmenting addressable markets. Segment-specific regulatory burdens determine vendor profitability and timeline-to-revenue more than unit economics alone.
Product Type:
Aircraft platforms carry the heaviest EASA type-certification burden for beyond-visual-line-of-sight operations, while marine systems navigate divergent national maritime safety regimes across Baltic and North Sea jurisdictions.
- Aircraft:Fixed-wing and rotary-wing platforms dominate defense procurement volumes, with NATO standardization agreements driving interoperability requirements across German, French, and Italian air forces. EASA's specific category framework governs commercial authorization timelines, compressing operational readiness for agricultural spraying operators in Poland and Spain.
- Marine Systems:Autonomous underwater vehicles and unmanned surface vessels address subsea infrastructure monitoring demand in Norwegian and UK offshore corridors. National maritime regulators in Estonia, Latvia, and Lithuania lack harmonized certification reciprocity, extending market entry timelines for Baltic-focused vendors.
- Ground Vehicles:Robotic platforms for explosive ordnance disposal and perimeter security operate under national defense procurement exemptions rather than EASA jurisdiction.
- Hybrid Systems:Vertical take-off and landing platforms with fixed-wing transition capabilities bridge tactical mobility and endurance requirements for German special operations commands.
Leading the category by volume: Aircraft. Growing fastest: Marine Systems.
Technology:
Cost tier separation runs deepest along autonomy sophistication, with fully autonomous systems commanding premium pricing against remote-controlled alternatives due to sensor fusion and embedded computing requirements.
- AI-Based Systems:Onboard inference architectures enable real-time target recognition without ground station dependency, opening tactical segments previously reserved for manned assets. EU AI Act high-risk classification triggers mandatory conformity assessment procedures that extend German and French product launch timelines substantially.
- Autonomous Navigation:GPS-denied positioning through visual-inertial odometry addresses electronic warfare resilience requirements for Eastern European defense ministries. EASA's artificial intelligence and machine learning guidance documents impose documentation burdens that favor established aerospace-IT hybrid vendors.
- Remote Control:Line-of-sight radio link architectures retain cost advantage for commercial agriculture and delivery applications in Southern European markets.
- Communication Links:Satellite relay and mesh networking protocols determine operational radius for cross-border NATO cooperative missions.
Commanding premium pricing: AI-Based Systems. Expanding most quickly: Autonomous Navigation.
Application:
Geographic demand concentration follows infrastructure investment patterns, with North Sea energy corridors and Eastern European border surveillance driving marine and aerial platform procurement respectively.
- Surveillance:Border monitoring and critical infrastructure protection absorb the majority of EU Internal Security Fund allocations for unmanned systems, with Romanian and Bulgarian ministries prioritizing aerial platforms for Black Sea corridor coverage.
- Infrastructure Inspection:Offshore wind farm and subsea pipeline operators in Danish, Dutch, and German territorial waters deploy autonomous marine systems for cathodic protection surveys and structural integrity assessments.
- Agriculture:Precision spraying and crop monitoring applications concentrate in French and Italian vineyard regions under EASA's specific category operational authorizations.
- Delivery:Last-mile logistics trials in Irish and Finnish urban environments face payload-weight restrictions that limit addressable parcel segments.
Absorbing largest budget share: Surveillance. Steepest expansion trajectory: Infrastructure Inspection.
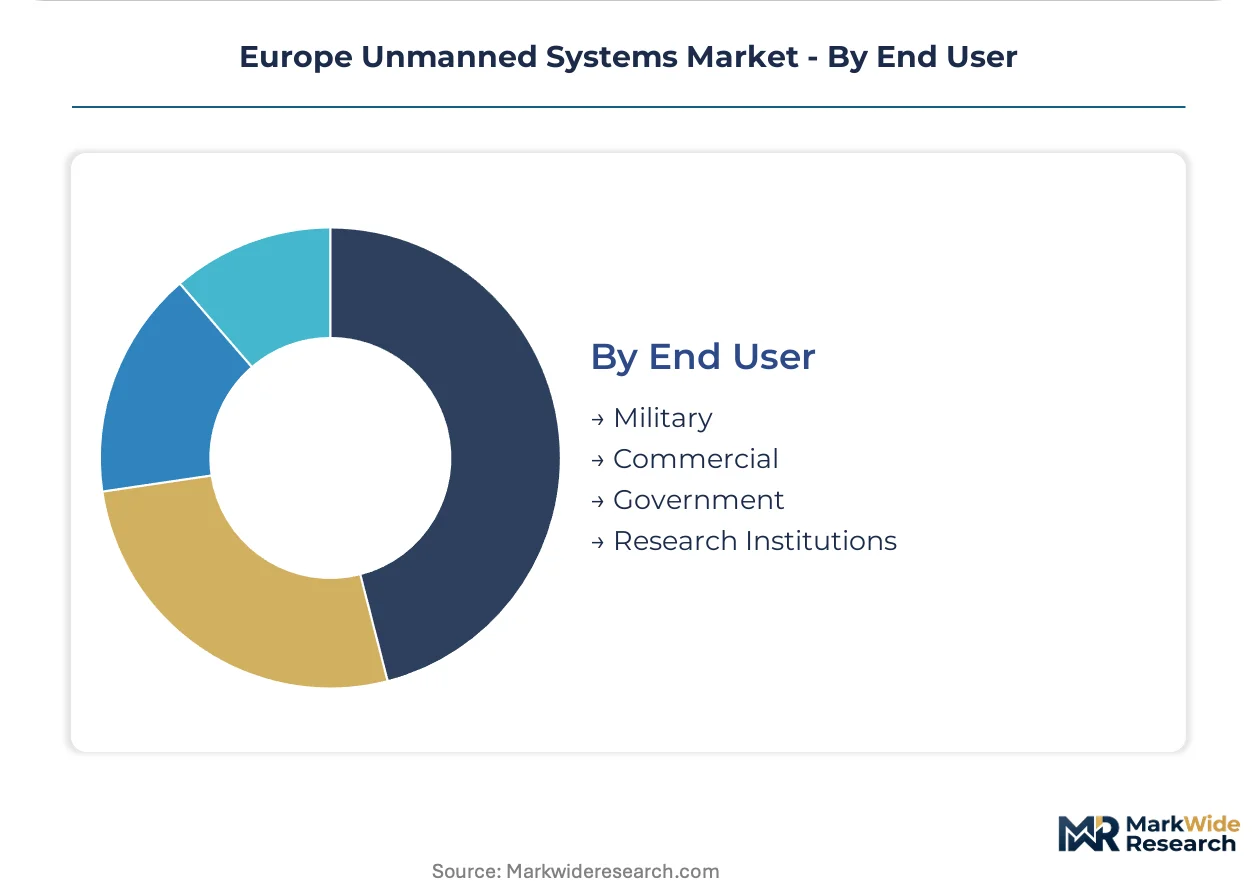
End User:
Customer type determines contract structure and margin profile, with military outcome-based agreements transferring operational risk to manufacturers while commercial buyers optimize for acquisition cost.
- Military:Defense ministries in Germany, France, and the UK structure UAV acquisitions around flight-hour guarantees and availability metrics, compressing traditional spare parts revenue streams. NATO standardization agreements mandate interoperability specifications that favor pan-European consortium bidders.
- Commercial:Agricultural cooperatives and logistics operators in Spain, Italy, and Poland prioritize CE marking compliance speed over performance specifications, driving vendor selection toward established EASA authorization holders.
- Government:Interior ministries and coast guard services in Greece, Portugal, and Croatia procure dual-use platforms suitable for both civilian emergency response and military contingency activation.
- Research Institutions:University consortia and national laboratories in Sweden, Switzerland, and the Netherlands pilot swarm coordination algorithms and quantum-encrypted datalinks under defense innovation funding programs.
Generating highest contract values: Military. Gaining share fastest: Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration clusters in Germany and France, while procurement demand distributes across NATO's eastern flank and North Sea energy corridors. This production-consumption divergence shapes logistics networks and regulatory compliance burdens across the continent.
Germany
Bundeswehr fleet modernization and special operations procurement drive aerial platform demand through 2035. KBA vehicle standards and national defense procurement exemptions govern ground vehicle authorization timelines. Bavaria's defense industrial corridor hosts Airbus SE and Quantum-Systems GmbH production facilities for tactical reconnaissance systems.
United Kingdom
Royal Navy submarine-hunting programs and offshore wind farm inspection generate marine system procurement. Maritime and Coastguard Agency certification requirements diverge from EASA frameworks for autonomous surface vessels. Scottish territorial waters host North Sea pipeline monitoring deployments by Aberdeen-based service operators.
France
Dassault Aviation supply chain integration and naval drone programs sustain dual-use platform development. Direction Générale de l'Aviation Civile coordinates with EASA on beyond-visual-line-of-sight operational authorizations. Toulouse aerospace cluster anchors Thales Group sensor integration facilities for encrypted datalink architectures.
Poland
Eastern border surveillance and Black Sea corridor monitoring absorb EU Internal Security Fund allocations for unmanned aerial systems. Polish Civil Aviation Authority implements EASA specific category frameworks with national adaptation periods. Warsaw defense procurement corridor concentrates tactical drone operator training facilities for Baltic contingency response.
Netherlands
Rotterdam port security and North Sea offshore energy infrastructure inspection drive autonomous marine system adoption. Human Environment and Transport Inspectorate enforces maritime safety regimes divergent from aircraft certification pathways. Eindhoven high-tech cluster hosts embedded systems engineering programs for flight control software development.
Europe Unmanned Systems Market Competitive Landscape
Top-tier vendors anchor pan-European consortium structures, while mid-tier specialists concentrate on single-domain platform categories. The vendor base stratifies across defense prime contractors, commercial drone manufacturers, and marine autonomy developers. Three archetypes dominate: aerospace conglomerates with manufacturing scale, sensor-software integrators with proprietary datalink architectures, and electric propulsion specialists with vertical take-off capabilities. Competitive moves center on NATO standardization compliance engineering and EASA certification pathway pre-emption.
Within the aerospace conglomerate tier, Airbus SE and BAE Systems occupy positions defined by pan-European manufacturing footprints and defense ministry relationships. Thales Group exemplifies the sensor-software integrator archetype through its positioning around encrypted datalink and mission payload systems. Quantum-Systems GmbH represents the electric propulsion specialist category with its vertical take-off and landing platform focus for tactical reconnaissance applications.
| Leading Market Players |
|---|
| Airbus SE |
| BAE Systems |
| Thales Group |
| Leonardo S.p.A. |
| Saab AB |
| Parrot Drones SA |
| Microdrones GmbH |
| Rheinmetall AG |
| Quantum-Systems GmbH |
| Others |
Supply & Pricing Matrix
Captive battery cell sourcing from East Asian manufacturing hubs anchors both supply security and pricing power for European platform assemblers, creating divergence between vendors with long-term offtake agreements and those exposed to spot market volatility. This integration choice shapes competitive positioning across NATO procurement cycles and commercial certification pathways.
Pricing Analysis
Margin tightening in AI-enabled platforms reflects EU AI Act conformity assessment burdens that extend development timelines and compress vendor pricing flexibility. Three-tier pricing structure across NATO-compliant, CE-marked, and uncertified tiers separates defense procurement from agricultural operators. Cost-down pressure on electric propulsion systems accelerates because lithium-ion cathode materials concentrate in South Korean and Chinese refining corridors. Commercial agricultural buyers in Poland and Spain exhibit highest price sensitivity, while German defense ministries prioritize availability guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Bundeswehr procurement offices require qualified suppliers for flight control processors and encrypted datalink modules, fragmenting vendor concentration. Component manufacturing concentrates in Germany, France, and the United Kingdom for airframe assembly, while semiconductor fabrication feeds from Taiwan and South Korea. Raw material dependencies span carbon fiber composites, rare-earth magnets for electric motors, and gallium arsenide for RF components. Single-source vulnerability in C-band radio frequency chips creates chokepoint exposure for beyond-visual-line-of-sight platforms. Distribution runs through national defense procurement corridors and EASA-authorized commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Unmanned Systems Market economics function as a cost-of-compliance story where EU AI Act high-risk classification and EASA specific category authorization create durable barrier-to-entry moats for vendors with established regulatory engineering capabilities.
For Market Incumbents: Hedge against satellite communication substitution by deepening software-defined payload architectures and securing NATO standardization agreement compliance engineering ahead of fleet modernization cycles. Acquire embedded systems engineering talent pools in Eindhoven and Toulouse clusters to preempt flight control software scarcity. Prioritize outcome-based contracting capabilities to align with French and British ministry flight-hour guarantee structures. For New Entrants and Emerging Players: Begin with Baltic Corridor marine autonomy where Estonian, Latvian, and Lithuanian territorial waters lack harmonized certification reciprocity and incumbent saturation. Target autonomous underwater vehicle supply gaps for subsea pipeline inspection in Norwegian and UK offshore corridors. Pursue EASA specific category operational authorization as the foundational go-to-market credential for agricultural spraying and delivery applications. For Investors and Strategic Acquirers: Exit pathways concentrate in sensor-software integrators with proprietary datalink architectures and encrypted mission payload systems. Long-term viability hinges on regulatory engineering capacity rather than airframe manufacturing scale. Monitor EU defense industrial strategy revision timing as the inflection signal for cross-border consortium funding eligibility redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Certification Pre-emption | Early specific category authorization locks out competitors from BVLOS agricultural and delivery segments. |
| NATO Standardization Compliance Engineering | Interoperability mandates synchronize procurement cycles across German, French, and Italian defense ministries. |
| AI-Edge Computing Integration | Onboard inference chips enable real-time targeting without ground station dependency for tactical missions. |
| Marine Autonomy Capacity Buildout | North Sea and Baltic infrastructure monitoring demand outpaces current autonomous underwater vehicle supply. |
| Dual-Use Platform Development | Greek and Croatian coast guard procurement favors systems suitable for civilian emergency and military activation. |
Research Methodology
Independent corroboration across defense procurement officers, EASA certification consultants, and embedded systems engineering directors underwrites the qualitative findings. Primary fieldwork with platform engineers at Airbus SE, Thales Group, and Quantum-Systems GmbH combined with secondary validation from NATO standardization agreement documentation, EASA artificial intelligence guidance publications, and EU defense industrial strategy white papers. Bottom-up triangulation across national ministry budget disclosures and top-down reconciliation with pan-European manufacturing capacity estimates anchors segment-level precision.
Rate-of-change decomposition across product type, technology sophistication, application vertical, and end-user procurement structure drives the analytical framework. Segmentation modeling spans aircraft, marine, ground, and hybrid platforms; remote control, autonomous navigation, AI-based, and communication link technologies; surveillance, infrastructure inspection, agriculture, and delivery applications; and military, commercial, government, and research institutional buyers. CAGRs derive from procurement cycle timing, regulatory authorization trajectory, and autonomy adoption curve assumptions. Forecast inputs incorporate lithium-ion supply contract tenors and EASA specific category approval velocity.
Underlying measurement precision varies by segment; military procurement with disclosed budget lines carries tighter precision than emerging commercial applications with fragmented operator counts. Forecasts reflect documented assumptions regarding NATO fleet modernization pacing and EU AI Act implementation timeline. Deviation in EASA artificial intelligence risk-tier classification interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Drone-In-A-Box Solutions Market