
 Autonomous Drone Station Market | 2026-2036
Autonomous Drone Station Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Drone Station Market Insights
Modular docking configurations is realigning procurement patterns as buyers mix charging stations, maintenance hubs, and landing platforms into site-specific arrays rather than purchasing monolithic systems. Skydio leverages its vertical integration in AI navigation to dominate enterprise security deployments. Airobotics anchors its position through persistent overseas operations in mining and energy corridors. Anduril Industries competes on defense-grade edge computing architectures that harden stations against electronic interference.
An autonomous drone station comprises a ground-based infrastructure node that shelters, powers, communicates with, and redeploys unmanned aerial vehicles without human intervention, typically incorporating weatherproof enclosures, automated battery swap or wireless charging coils, and mesh-networked telemetry relays operating across 2.4 GHz to 5.8 GHz bands. Its commercial purpose centers on enabling continuous beyond-visual-line-of-sight operations for remote sensing and asset monitoring. Charging stations currently occupy the largest product category as fleet operators prioritize uptime over incremental maintenance automation. AI navigation and edge computing represent the fastest-expanding technology layers, where latency constraints push processing from cloud servers directly into station-mounted hardware. Surveillance and infrastructure inspection applications generate the steepest demand curves among end users, driven by utility inspectors and security firms seeking round-the-clock perimeter coverage.
The FAA's Part 89 Remote ID rule and evolving U-space framework from EASA shape hardware design mandates, compelling manufacturers to embed broadcast transponders and geofencing logic directly into station firmware. China's CAAC BVLOS corridor approvals and GB standard compliance requirements create parallel certification tracks that fragment go-to-market strategies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid engineering lock-in as compliance architectures solidify.
Market Dynamics
Modular procurement architectures are fragmenting vendor lock-in as fleet operators assemble site-specific configurations from specialized charging, maintenance, and communications subsystems rather than accepting bundled turnkey platforms.
Growth Catalysts
- EASA U-space framework maturation:The phased rollout of U-space service provision mandates across European urban air mobility corridors is compelling infrastructure investments that preempt 2026 operational deadlines.
- Utility-scale solar inspection demand:Photovoltaic farm operators in Spain, Australia, and Chile are deploying autonomous stations to eliminate manual thermographic survey labor costs across multi-gigawatt installations.
- 5.8 GHz mesh telemetry:Industrial mesh networking protocols operating in unlicensed bands are reducing station-to-fleet communication latency below cloud-reliant architectures.
Market Restraints
- Lithium-ion cell supply concentration:Automated battery swap systems depend on cylindrical cell formats dominated by East Asian cathode material processors, exposing station OEMs to input volatility.
- FAA Part 89 compliance friction:Remote ID broadcast module integration requirements are extending hardware certification timelines and freezing pre-2024 installed base upgrade economics.
- Optical navigation substitution threat:Visual-inertial odometry advances in handheld UAVs are reducing the premium commanded by RTK-GNSS-dependent station architectures in certain inspection applications.
Strategic Opportunities
- Sub-Saharan mining corridors:Copper and cobalt extraction operations in Zambia and the Democratic Republic of Congo lack terrestrial communications infrastructure, creating first-mover advantages for satellite-backhauled autonomous stations.
- EU Green Deal carbon accounting:The CSRD's Scope 3 disclosure mandates are pressuring logistics operators to document last-mile delivery emissions reductions achievable through drone substitution.
- Digital twin convergence:Station-mounted edge processors are converging with BIM platform APIs to enable real-time infrastructure degradation modeling without cloud round-trips.
Industry Challenges
- Embedded systems firmware talent scarcity:Station manufacturers compete with automotive and robotics sectors for engineers proficient in real-time operating systems and safety-critical codebases.
- Multi-jurisdiction certification parallelism:Hardware architectures must simultaneously satisfy FAA, EASA, and CAAC diverging approaches to detect-and-avoid system validation, fragmenting engineering resources.
- Legacy SCADA integration complexity:Energy and utility customers require station telemetry to feed existing asset management platforms through proprietary protocols resistant to API standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Drone Station Market |
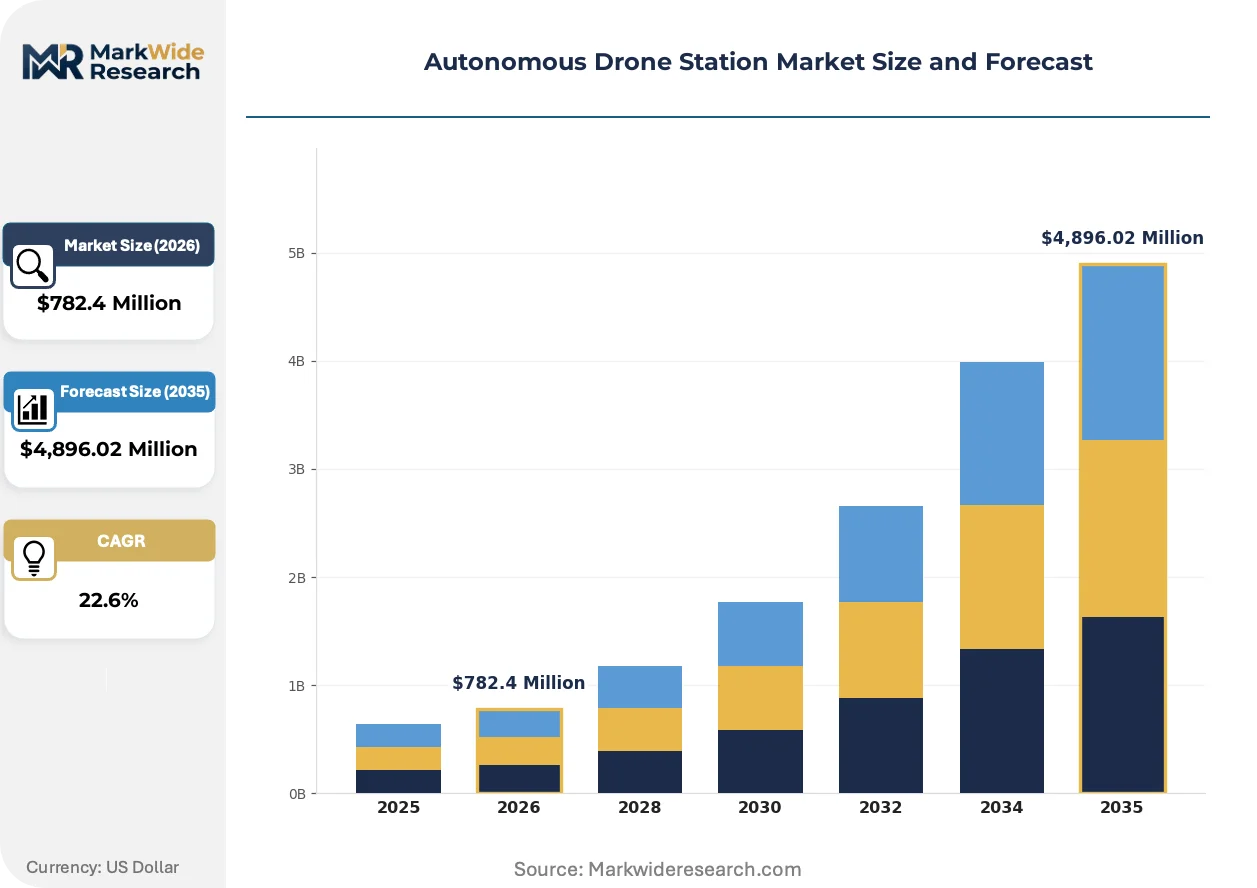
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $4,896.02 Million |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charging Stations, Maintenance Hubs, Launch Pads, Landing Platforms, Docking Modules Technology: Wireless Charging, Solar Power, IoT Integration, AI Navigation, Edge Computing Application: Surveillance, Agriculture Monitoring, Package Delivery, Infrastructure Inspection, Environmental Research End User: Logistics Providers, Security Firms, Farming Corporations, Utility Inspectors, Research Institutions |
| Companies Covered | Ascent AeroSystems, Delair, Skydio, Anduril Industries, EVA, Inc., Airobotics, Autel Robotics, FreeFly Systems, DJI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Drone Station Market Trends and Innovations
Edge-native processing architectures are displacing cloud-dependent station designs as latency requirements for real-time collision avoidance and mission replanning harden below 50-millisecond thresholds.
Wireless power transfer via resonant inductive coils is converging with photovoltaic-integrated station enclosures to eliminate conductive charging contact maintenance in desert and maritime deployments. Mining operators in Western Australia are piloting these architectures to sustain continuous pit survey operations without battery swap robotics. The technology is converging with automated thermal management systems that extend coil lifespan in abrasive dust environments.
EASA's phased U-space service provision regulation is mandating certified detect-and-avoid capabilities for operations above 120 meters in controlled airspace. Station manufacturers must embed radar or optical sense-and-avoid modules that interface with centralized traffic management systems. German industrial security deployments are most affected, with operators accelerating hardware refresh cycles to secure 2025 operational approvals.
Leasing structures for station infrastructure are displacing capital purchase models among mid-scale logistics providers seeking to match fleet capacity to seasonal delivery volumes. Equipment financiers in the Netherlands and Singapore are structuring pay-per-landing contracts that transfer utilization risk from operators to lessors. Agricultural spraying cooperatives in Brazil exhibit the fastest uptake of this arrangement as they navigate irregular crop protection demand cycles.
Autonomous Drone Station Market Segmentation
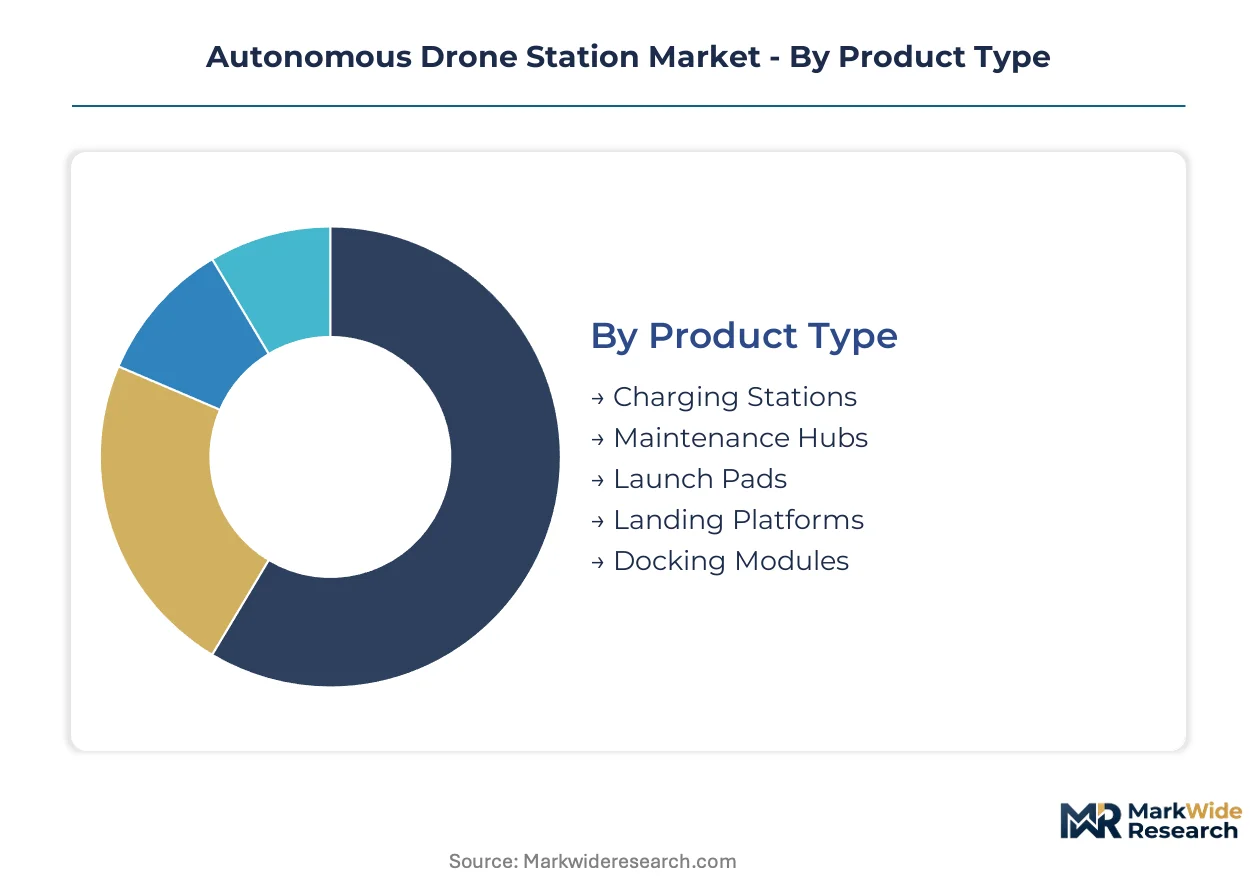
Autonomous drone stations fragment across hardware configurations, processing architectures, mission profiles, and buyer capabilities. Each segmentation axis reveals distinct procurement logics and margin structures that shape vendor positioning.
Product Type:
Physical station configurations vary by the operational function they automate, from power delivery to vehicle handling.
- Charging Stations:Enclosures house conductive or inductive power transfer systems with thermal management for continuous cycling. Fleet operators in Germany prioritize these for last-mile logistics density, where uptime economics dominate capital allocation decisions.
- Maintenance Hubs:Robotic arms execute propeller replacement, sensor cleaning, and firmware updates without human access. Mining operators in Western Australia deploy these across remote pit corridors where technician dispatch costs exceed automation premiums.
- Launch Pads:Elevated platforms with integrated positioning systems enable rapid deployment in uneven terrain. Forestry services in Canada favor these for wildfire monitoring missions.
- Landing Platforms:Precision touchdown surfaces with optical guidance accommodate variable weather conditions. Maritime logistics firms in Singapore specify these for offshore vessel-to-shore operations.
- Docking Modules:Compact units combining charging and secure storage for space-constrained urban deployments. Security integrators in Japan select these for building-integrated perimeter systems.
Charging Stations lead on scale; Maintenance Hubs lead on momentum.
Technology:
Processing and power architectures determine latency performance and operational autonomy in disconnected environments.
- Wireless Charging:Resonant inductive coils eliminate contact wear in abrasive or corrosive settings. Photovoltaic farm operators in Spain favor these for dust-prone thermographic survey stations.
- Solar Power:Integrated photovoltaic enclosures enable off-grid deployment without grid connection logistics. Conservation drones in Kenya operate on these for anti-poaching patrols.
- IoT Integration:Mesh telemetry protocols synchronize multiple stations across distributed footprints. Utility inspectors in Texas leverage these for substation network coordination.
- AI Navigation:Onboard path planning reduces cloud dependency for real-time obstacle avoidance. Urban air mobility pilots in France require these for EASA U-space corridor compliance.
- Edge Computing:Station-mounted processors execute mission replanning below 50-millisecond thresholds. Infrastructure engineers in South Korea deploy these for bridge deformation analysis without round-trip latency.
Edge Computing commands the steepest expansion trajectory; Wireless Charging holds the broadest installed base.
Application:
Mission profiles dictate sensor payloads, flight endurance requirements, and regulatory exposure.
- Surveillance:Perimeter monitoring with thermal and optical feeds demands 24/7 station availability. Critical infrastructure operators in Saudi Arabia prioritize these for oil facility protection.
- Agriculture Monitoring:Multispectral crop health assessment requires precise repeat-visit scheduling. Soybean cooperatives in Brazil specify these for variable-rate input optimization.
- Package Delivery:High-frequency landing cycles stress mechanical reliability and battery swap speed. Retail logistics networks in the United States test these for suburban last-mile substitution.
- Infrastructure Inspection:Structural defect detection with LiDAR or photogrammetry needs stable positioning references. Railway operators in Switzerland mandate these for alpine tunnel assessment.
- Environmental Research:Long-duration atmospheric sampling missions favor extended-range power architectures. Polar science stations in Norway deploy these for ice sheet monitoring.
Infrastructure Inspection generates the highest unit economics; Package Delivery shows the most volatile demand cyclicality.
End User:
Buyer sophistication and procurement authority shape contract structures and integration complexity.
- Logistics Providers:Volume-scaled operators seek modular capacity expansion matched to seasonal delivery peaks. Express carriers in the Netherlands favor leasing structures over capital purchase.
- Security Firms:Guarding services integrate stations into existing command centers through proprietary middleware. Corporate campus operators in the United Arab Emirates demand these for executive protection perimeters.
- Farming Corporations:Agribusinesses prioritize spray mission compatibility and chemical resistance in enclosure materials. Cotton plantations in Australia specify these for defoliant application windows.
- Utility Inspectors:Transmission and distribution operators require SCADA integration and failure-mode redundancy. Power generators in Chile mandate these for desert solar farm thermography.
- Research Institutions:Academic and governmental users accept longer deployment timelines for experimental payload accommodation. Atmospheric scientists in Finland select these for auroral zone data collection.
Logistics Providers concentrate procurement volume; Utility Inspectors drive specification standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The autonomous drone station industry traces its commercial origins to Israeli military and agricultural automation research from the early 2010s, with subsequent scaling concentrated in North American defense procurement and Chinese manufacturing export corridors.
United States
Defense contractors and logistics providers drive procurement volume through FAA-certified beyond-visual-line-of-sight waivers. The FAA's Remote ID mandate under Part 89 compels hardware retrofits across existing station networks. Arizona and Nevada host concentrated testbed operations where commercial drone delivery pilots scale autonomous landing infrastructure.
Germany
Industrial security firms and railway operators generate demand for EASA U-space compliant detect-and-avoid systems. Germany's national aviation authority enforces phased service provision deadlines that accelerate station hardware refresh cycles. Bavaria's Munich-Augsburg corridor anchors European urban air mobility infrastructure deployment.
China
Photovoltaic farm operators and last-mile logistics networks absorb high volumes of modular charging architectures. CAAC corridor approvals for commercial BVLOS operations in designated airspace zones standardize station firmware requirements. Shenzhen and Guangzhou manufacturing clusters supply integrated docking systems for domestic and export markets.
Australia
Mining corporations and agricultural cooperatives deploy off-grid solar-integrated stations across remote extraction and pastoral regions. The Civil Aviation Safety Authority's remotely piloted aircraft systems regulations govern certification pathways for autonomous operations. Western Australia's Pilbara region pilots resonant inductive charging systems for continuous pit survey missions.
Singapore
Maritime logistics operators and port authorities invest in vessel-to-shore autonomous landing platforms for supply chain optimization. The Civil Aviation Authority of Singapore's urban air mobility sandbox framework permits experimental station deployments in controlled airspace. The Tuas port district hosts integrated drone infrastructure for container terminal perimeter monitoring.
Autonomous Drone Station Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with defense-grade edge computing architectures commanding price multiples over standard logistics charging enclosures. The vendor base stratifies into three tiers: vertically integrated AI navigation specialists, modular subsystem assemblers, and commodity hardware fabricators. Strategic archetypes include full-stack platform providers, component-specialist suppliers, and defense-focused system integrators. Capacity expansion and technology licensing represent the dominant competitive moves as firms seek to preempt regulatory certification bottlenecks.
Within the defense-technology tier, Anduril Industries and Skydio exemplify premium-positioned players leveraging hardened computing architectures for electronic warfare resilience. Airobotics occupies a position among persistent overseas operations specialists, with corporate structure indicating Israeli market origins. DJI represents the scale-driven manufacturing archetype, with Shenzhen-based production capacity supplying global logistics and agricultural demand. These three anchors illustrate the competitive divergence between security-grade system integration and volume manufacturing efficiency.
| Leading Market Players |
|---|
| Ascent AeroSystems |
| Delair |
| Skydio |
| Anduril Industries |
| EVA, Inc. |
| Airobotics |
| Autel Robotics |
| FreeFly Systems |
| DJI |
| Others |
Pricing and Supply Chain Analysis
Defense procurement programs and utility-scale fleet operators concentrate buying power across the autonomous drone station market, anchoring contract-based long-term offtake agreements that lock in volume commitments against certification-grade pricing tiers. Their procurement scale forces component suppliers into multi-year supply arrangements that stabilize input costs while compressing margins for non-certified hardware fabricators.
Pricing Analysis
Three-tier pricing structure across defense-grade, enterprise-certified, and commercial-economy levels dominates transaction architectures, with FAA Part 89 and EASA U-space certification tiers driving price differentiation alongside edge computing performance benchmarks. Cost compression in the commercial tier is intensifying because optical navigation substitution in handheld UAVs reduces RTK-GNSS premium capture. Utility inspectors exhibit the least price sensitivity due to SCADA integration requirements and failure-mode redundancy mandates, while mid-scale logistics providers in seasonal demand cycles show acute price responsiveness.
Supply Chain Analysis
Certification parallelism across FAA, EASA, and CAAC diverging detect-and-avoid validation requirements gates supplier qualification, fragmenting engineering resources and extending hardware certification timelines. Manufacturing concentrates in China, Germany, and the United States, with cylindrical lithium-ion cell formats drawing from East Asian cathode material processors. Single-source vulnerability in automated battery swap robotics creates exposure to input volatility. Distribution runs through specialized industrial equipment channels and direct defense procurement programs rather than commodity electronics marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous drone station market reads as a late-cycle quality story where procurement is shifting toward defense-grade edge computing specifications and EASA U-space certified detect-and-avoid architectures that command sustained margin premiums over commodity charging enclosures.
For Market Incumbents: Acquire embedded systems firmware engineering capabilities to address talent scarcity competing with automotive and robotics sectors. Consolidate certification investment across FAA Part 89, EASA U-space, and CAAC BVLOS parallel tracks to preempt regulatory bottlenecks that fragment engineering resources. Threat substitution from optical navigation in handheld UAVs demands defensive positioning through RTK-GNSS performance differentiation and SCADA integration depth. For New Entrants and Emerging Players: Sub-Saharan mining corridor operators in Zambia and the Democratic Republic of Congo represent the most penetrable buyer archetype, lacking terrestrial communications infrastructure and creating first-mover advantages for satellite-backhauled autonomous stations. Agricultural spraying cooperatives in Brazil exhibit irregular demand cycles that favor pay-per-landing leasing structures over capital purchase. A go-to-market angle through equipment financiers in the Netherlands and Singapore transfers utilization risk from operators to lessors. For Investors and Strategic Acquirers: Defense contractors pursuing electronic warfare resilience are the most active acquirer in this space, seeking hardened edge computing architectures and AI navigation specialists. The acquisition target archetype centers on vertically integrated AI navigation specialists with captive firmware development and established certification pathways across multiple jurisdictions. Watch for EASA U-space service provision deadline acceleration as an inflection indicator for hardware refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Parallelism Investment | Simultaneous FAA, EASA, and CAAC track progression preempts regulatory fragmentation lock-in. |
| Edge Computing Architecture Development | Station-mounted processors below 50-millisecond latency thresholds displace cloud-dependent designs. |
| Wireless Power Transfer Integration | Resonant inductive coils with photovoltaic enclosures eliminate contact maintenance in abrasive environments. |
| Leasing Structure Innovation | Pay-per-landing contracts through Dutch and Singaporean equipment financiers match capacity to seasonal volumes. |
| Sub-Saharan Corridor Deployment | Satellite-backhauled stations in Zambian and DRC mining operations exploit infrastructure gaps. |
Research Methodology
Bottom-up utility and logistics fleet deployment modeling reconciled against top-down OEM production capacity tracking forms the analytical core. Primary interviews with station hardware engineering directors, fleet operations managers at logistics providers, utility SCADA integration specialists, and defense procurement officers combine with secondary validation through FAA certification databases, EASA regulatory filings, CAAC corridor approval records, and customs trade data for lithium-ion cell and inductive coil imports.
Input-output matrices map charging station, maintenance hub, and docking module unit economics against edge computing and AI navigation technology cost curves across the projection horizon. Segmentation dimensions span product configuration, processing architecture, mission profile application, and buyer sophistication tier. CAGRs derive from installed base replacement cycles, regulatory deadline acceleration effects, and fleet operator capital allocation surveys. Industry-specific forecast inputs include EASA U-space service provision phase rollout schedules and FAA Part 89 Remote ID compliance retrofit demand.
Underlying measurement precision varies by segment; defense-grade and utility-scale deployments carry tighter precision than mid-scale logistics leasing structures due to contract visibility. Forecasts reflect assumptions regarding regulatory deadline adherence, lithium-ion cell supply stability, and firmware engineering talent availability. A model refresh is warranted upon material change in EASA U-space implementation timelines or CAAC BVLOS corridor expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Drone Parachute System Market