
 Global Anti-Drone System Market | 2026-2036
Global Anti-Drone System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Drone System Market Analysis
Aftermarket service revenue for firmware updates and threat-library refreshes is narrowing the margin gap against original hardware sales. RTX Corporation leverages its Patriot radar heritage to anchor long-term service contracts with US military customers. Lockheed Martin Corporation sustains technology leadership through in-house production of gallium nitride transmit-receive modules for high-power jamming arrays. Israel Aerospace Industries dominates Middle Eastern deployments with integrated electro-optical and radar fusion systems optimized for desert clutter environments.
An anti-drone system comprises integrated sensor suites, effector platforms, and command-and-control software designed to detect, track, and neutralize unmanned aerial vehicles through kinetic impact, radio-frequency disruption, or directed-energy engagement. These systems operate across X-band and Ku-band radar frequencies with detection ranges extending from 500 meters for portable units to 15 kilometers for fixed-site installations, serving military air defense, civilian airport protection, and critical infrastructure security missions. Electronic jamming commands the largest installed base among product types due to its non-destructive engagement profile and reduced collateral risk in populated areas, though laser systems represent the fastest-growing category as solid-state fiber lasers achieve militarily relevant power densities at declining unit costs. Radar technology leads detection modality adoption, while acoustic and visual fusion architectures gain traction in urban environments where electromagnetic spectrum congestion limits standalone radio-frequency performance.
The US FAA and FCC jointly shape domestic market access through Part 15 equipment authorization rules and restricted frequency-allocation tables that limit jamming transmission power outside designated military bands. European operators navigate EASA drone regulation amendments alongside national spectrum regulators in Germany, France, and Italy that impose varying deployment permissions for counter-UAS equipment near civilian aviation corridors. Stakeholders must monitor divergence between permissive military procurement frameworks and restrictive civilian certification pathways, as this regulatory asymmetry will determine which technology suppliers can operate across both customer classes without product-line duplication.
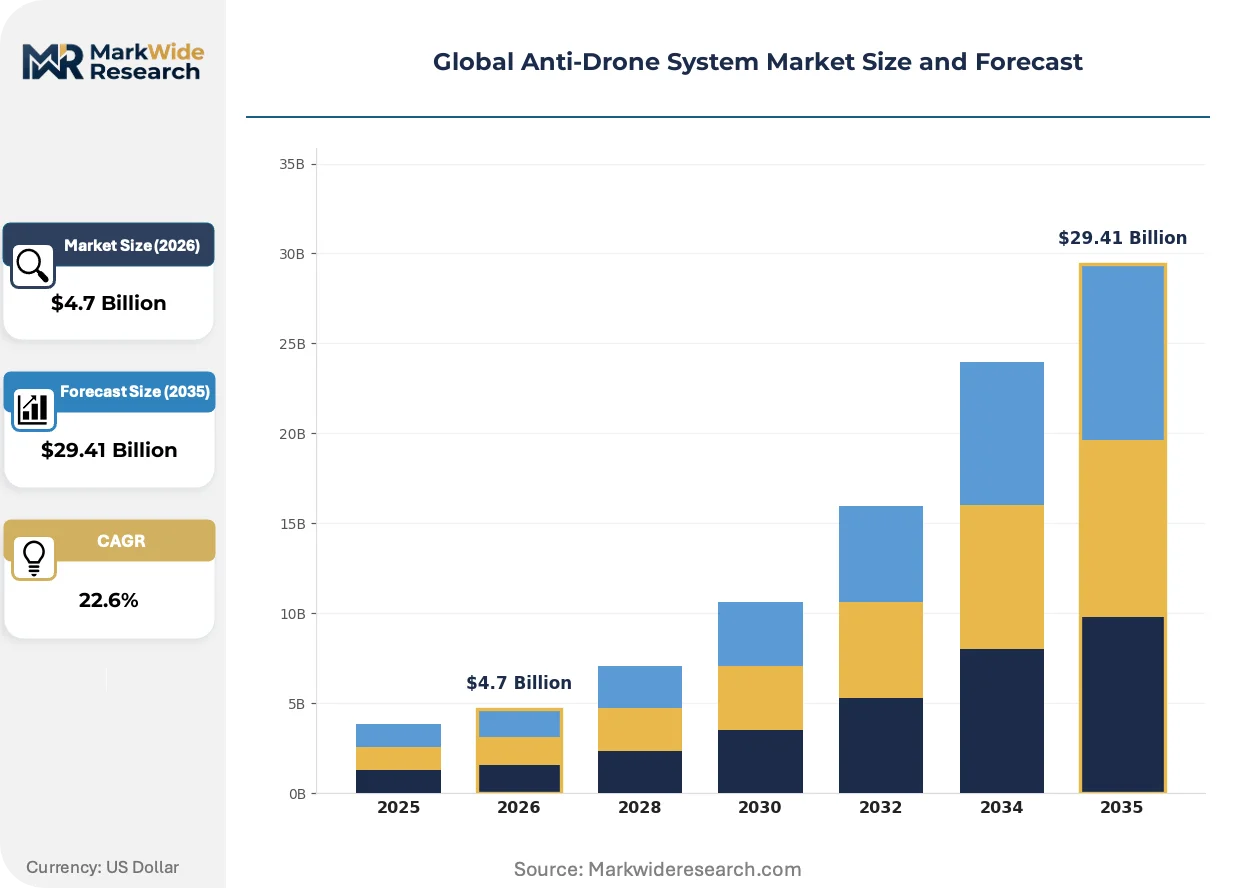
Market Dynamics
Layered counter-UAS architectures are compressing procurement cycles as defense ministries demand unified command interfaces across radar, electro-optical, and jamming subsystems. This integration imperative is forcing suppliers to abandon standalone hardware sales in favor of subscription-linked detection networks.
Growth Catalysts
- EU AI Act certification mandates:The European Union's risk-based classification for autonomous detection systems creates compliance-driven replacement demand across Dutch and German critical infrastructure operators.
- Civilian airport hardening:Federal Aviation Administration directives following multiple runway incursions are accelerating fixed-site radar deployments at United States commercial aviation hubs.
- Gallium nitride module maturation:Solid-state transmit-receive arrays are extending effective jamming range while reducing thermal management footprints for portable tactical units.
Market Restraints
- Restricted spectrum allocation:United States Federal Communications Commission Part 15 rules limit civilian jamming power outside designated military bands, constraining neutralization effectiveness in populated zones.
- Desert clutter performance gaps:Electro-optical sensors suffer elevated false-positive rates in Middle Eastern deployments where thermal mirage and sand particulate degrade target discrimination.
- Directed-energy capital intensity:Fiber laser systems require precision optical benches and closed-loop cooling infrastructure that triples unit cost against radio-frequency alternatives.
Strategic Opportunities
- Urban acoustic-radar fusion:Electromagnetic spectrum congestion in Tokyo and Singapore is creating first-mover advantage for microphone-array detection vendors.
- Aftermarket threat-library services:Firmware subscription models for drone signature updates generate recurring revenue streams independent of hardware replacement cycles.
- India's critical infrastructure perimeter:Nuclear facilities and metropolitan airports lack indigenous counter-UAS manufacturing capacity, opening import substitution pathways for foreign system integrators.
Industry Challenges
- Cross-domain software integration:Military command-and-control networks require STANAG-compliant interfaces that extend development timelines for commercial-off-the-shelf vendors.
- Directed-energy safety certification:Ocular hazard zone calculations for laser systems lack harmonized international standards, fragmenting approval pathways between national aviation regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Drone System Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Electronic Jamming, Net Guns, Kinetic Interceptors Technology: Radar, Infrared, Acoustic, Visual End User: Military, Homeland Security, Critical Infrastructure, Commercial Application: Surveillance, Counter-terrorism, Asset Protection, Airspace Management |
| Companies Covered | RTX Corporation, Lockheed Martin Corporation, Israel Aerospace Industries, Leonardo S.p.A., Thales Group, Rafael Advanced Defense Systems, Saab AB, DroneShield Ltd, Dedrone Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Drone System Market Emerging Trajectories
Software-defined detection architectures are displacing fixed-function hardware as the primary competitive differentiator. Virtualized signal processing enables rapid reconfiguration against evolving drone communication protocols without physical subsystem replacement.
Software-defined radio is virtualizing traditional hardware-based jamming architectures. United States military operators are fielding programmable waveform generators that adapt interference patterns in milliseconds against frequency-hopping control links. This virtualization is compressing procurement cycles for tactical units that previously required dedicated narrowband equipment for each threat spectrum.
The European Union AI Act's high-risk system classification is mandating human-in-the-loop verification for autonomous engagement decisions. German and French regulators are interpreting these provisions to require operator confirmation before kinetic or directed-energy neutralization. Civilian airport operators in these jurisdictions are responding by prioritizing detection-only contracts with deferred effector integration.
Buyers are unbundling after-sales service from initial hardware acquisition. United States federal agencies now structure separate indefinite-delivery contracts for threat-library updates and firmware maintenance. This purchasing pattern shift is most visible in domestic security deployments at nuclear facilities, where five-year service agreements now exceed original equipment value.
Global Anti-Drone System Market Segmentation
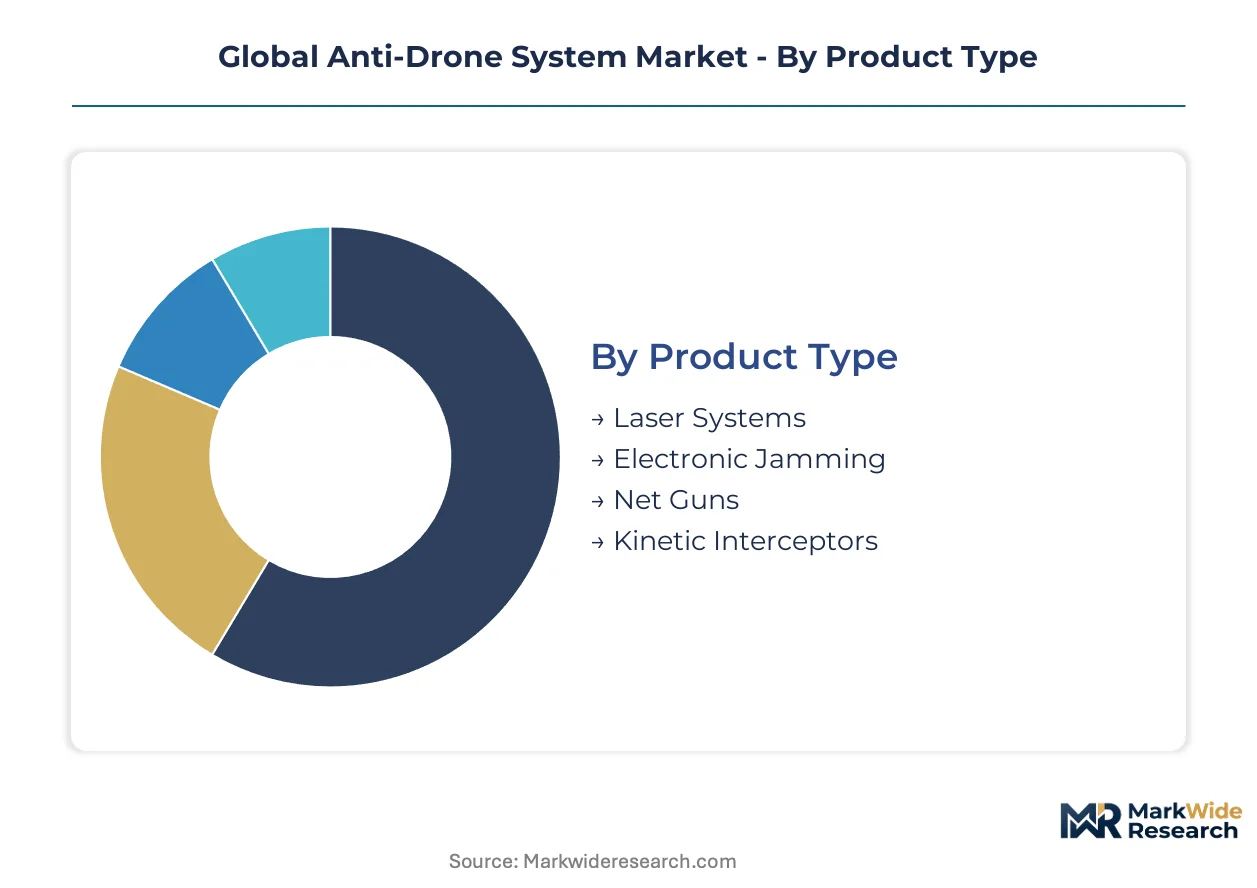
Segmentation in the anti-drone market determines procurement flexibility, as military operators prioritize rapid threat-library updates while civilian airports favor fixed-site installations with decade-long service horizons. Understanding where replacement cycles compress versus extend shapes supplier pricing power and aftermarket revenue capture.
Product Type:
Electronic jamming commands the shortest replacement cycle due to protocol obsolescence, while kinetic interceptors operate on multi-year stockpiling patterns with minimal refresh requirements.
- Electronic Jamming:Radio-frequency disruption systems generate interference across 2.4 GHz, 5.8 GHz, and GNSS bands to sever drone command links. United States federal agencies at nuclear facilities deploy these as primary neutralization layers, constrained by FCC Part 15 power limits that reduce effective range in civilian airspace.
- Laser Systems:Solid-state fiber lasers achieve militarily relevant power densities through gallium nitride pump diodes, enabling precision thermal destruction of drone airframes. German critical infrastructure operators under EU AI Act mandates are piloting human-in-the-loop verification protocols before autonomous engagement authorization.
- Net Guns:Pneumatic or compressed-gas launchers propel capture nets across 30-50 meter engagement envelopes for close-range interdiction.
- Kinetic Interceptors:Hard-kill projectiles and interceptor drones provide terminal defense against hardened targets.
Electronic jamming dominates installed base. Laser systems are where expansion concentrates.
Technology:
Cost tiers separate detection modalities, with radar platforms commanding premium positioning against acoustic arrays that compete on unit economics for perimeter security.
- Radar:X-band and Ku-band active electronically scanned arrays deliver detection ranges from 500 meters to 15 kilometers depending on transmit power and antenna aperture. United States commercial aviation hubs under FAA directive accelerate fixed-site deployments for runway protection.
- Infrared:Cooled indium antimonide and uncooled vanadium oxide focal plane arrays detect thermal signatures against sky backgrounds. Middle Eastern deployments suffer elevated false-positive rates from thermal mirage and sand particulate degradation.
- Acoustic:Microphone arrays triangulate rotor harmonic signatures through beamforming algorithms.
- Visual:Electro-optical cameras with machine-learning classification enable daytime target discrimination.
Radar anchors military procurement. Acoustic-radar fusion is gaining share fastest in Tokyo and Singapore electromagnetic congestion environments.
End User:
Customer type determines certification burden, with military frameworks permitting rapid fielding against civilian pathways that demand extensive safety documentation.
- Military:Layered counter-UAS architectures integrate radar, electro-optical, and jamming subsystems through STANAG-compliant command interfaces. NATO member state defense ministries compress procurement cycles through unified network requirements.
- Homeland Security:Domestic security operators at civilian airports and border crossings prioritize detection-only contracts with deferred effector integration under restrictive neutralization protocols.
- Critical Infrastructure:Nuclear facilities, power grids, and telecommunications nodes require 24/7 perimeter monitoring.
- Commercial:Private venues and logistics centers adopt portable units for event-specific deployment.
Military end users drive hardware volume. Critical infrastructure operators generate the steepest expansion trajectory through subscription-linked detection networks.
Application:
Application maturity varies by threat evolution speed, with counter-terrorism protocols refreshing quarterly against surveillance configurations that stabilize over years.
- Counter-terrorism:Rapid-response deployments require portable jamming and kinetic systems for swarm mitigation in urban environments. French and German regulators mandate operator confirmation before neutralization under EU AI Act high-risk system classifications.
- Airspace Management:Fixed-site radar networks enable continuous monitoring of approach corridors and restricted zones. India's metropolitan airports lack indigenous manufacturing capacity, opening import substitution pathways for foreign system integrators.
- Surveillance:Detection-only architectures support law enforcement and intelligence gathering missions.
- Asset Protection:Perimeter defense for high-value installations combines multiple detection layers.
Airspace management dominates installed base. Counter-terrorism applications are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentration in the United States and layered counter-UAS deployments across NATO member states are reshaping supply-side dynamics. Manufacturers anchor production near military customer clusters while navigating divergent civilian certification pathways.
United States
The FAA and FCC jointly regulate domestic market access through Part 15 equipment authorization and restricted frequency-allocation tables. Federal agencies at nuclear facilities deploy integrated radar-jamming platforms under constrained civilian jamming power limits. Domestic security operators in the Southwest concentrate fixed-site installations along border corridors.
Germany
Critical infrastructure operators respond to EU AI Act high-risk system classifications with human-in-the-loop verification protocols. EASA drone regulation amendments interact with national spectrum permissions that vary by federal state. Industrial clusters in Bavaria pilot acoustic-radar fusion architectures for urban electromagnetic congestion environments.
Israel
Desert warfare expertise drives electro-optical and radar fusion systems optimized for thermal mirage and sand particulate conditions. The national defense establishment maintains permissive military procurement frameworks distinct from export certification requirements. Tel Aviv-area technology corridors host integrated sensor-effector development for Middle Eastern deployments.
India
Metropolitan airports and nuclear facilities lack indigenous counter-UAS manufacturing capacity, creating import substitution pathways. The country's national aviation regulator collaborates with defense procurement agencies on perimeter security standards. System integrators concentrate demonstration activities around Delhi-Mumbai industrial corridors.
Japan
Electromagnetic spectrum congestion in Tokyo drives microphone-array detection vendor penetration against standalone radio-frequency limitations. METI coordinates civilian certification pathways that defer effector integration for detection-only contracts. Osaka-Kobe manufacturing zones adapt automotive sensor supply chains for acoustic array production.
Global Anti-Drone System Market Vendor Landscape
Defense prime contractors and specialized counter-UAS technology firms split the market along integration depth versus agility vectors. Tiered competition separates full-spectrum platform integrators from modular subsystem suppliers. Established aerospace conglomerates and agile technology specialists represent the dominant strategic archetypes. Consolidation pressure intensifies through long-term service contract capture and software-defined architecture licensing.
Among US-based defense conglomerates, RTX Corporation and Lockheed Martin Corporation occupy positions reflecting radar heritage and transmit-receive module production capabilities. Israel Aerospace Industries exemplifies regional specialist integration within Middle Eastern deployment environments. These three anchors sit within distinct competitive tiers: platform-scale integrators, component technology captives, and geography-bound system specialists.
| Leading Market Players |
|---|
| RTX Corporation |
| Lockheed Martin Corporation |
| Israel Aerospace Industries |
| Leonardo S.p.A. |
| Thales Group |
| Rafael Advanced Defense Systems |
| Saab AB |
| DroneShield Ltd |
| Dedrone Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Gallium nitride foundry capacity in the United States and Japan concentrates upstream margin capture for high-power transmit-receive modules, while downstream pricing power shifts toward aftermarket service tiers that decouple revenue from hardware replacement cycles.
Pricing Analysis
Aftermarket threat-library subscriptions now drive lifetime value across military and critical infrastructure deployments. Three-tier pricing structure across premium, standard, and economy levels separates STANAG-compliant military integrators from civilian airport operators with deferred effector integration. Cost compression in portable tactical units intensifies as solid-state module prices decline. Homeland security operators at nuclear facilities exhibit highest price sensitivity due to federal budget constraints, while NATO defense ministries show lowest sensitivity given mission-critical procurement mandates.
Supply Chain Analysis
Raw gallium nitride substrates and precision optical benches for fiber lasers draw from specialized suppliers in the United States, Japan, and Germany. Critical dependencies center on indium phosphide wafers, closed-loop cooling systems, and software-defined radio chipsets. Single-source vulnerability runs through gallium nitride foundry capacity concentrated with defense-captive suppliers. Distribution runs through prime contractor integration channels rather than direct component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-drone system market represents high-growth disruption as software-defined architectures compress procurement cycles and EU AI Act certification mandates force compliance-driven replacement demand.
For Market Incumbents: Entrench platform-scale positioning through backward integration into gallium nitride transmit-receive module production and long-term service contract capture at US nuclear facilities. Counter emerging acoustic-radar fusion specialists by accelerating STANAG-compliant command interface development. Certification investment in EU AI Act high-risk system pathways serves as the critical defensive lever against modular subsystem vendors. For New Entrants and Emerging Players: Establish a beachhead in India's metropolitan airports and nuclear facilities where indigenous manufacturing gaps create import substitution pathways. Target acoustic-radar fusion architectures for Tokyo and Singapore electromagnetic congestion environments. Go-to-market angle should emphasize detection-only contracts with deferred effector integration to bypass restrictive civilian neutralization protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed acoustic detection specialists and software-defined radio technology firms that lack military certification depth. Five-to-ten year viability hinges on cross-over capability between permissive military frameworks and restrictive civilian pathways. Watch for divergence between FAA Part 15 rule amendments and EU AI Act enforcement timelines as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Licensing | Virtualized signal processing enables rapid reconfiguration against evolving drone protocols without hardware replacement. |
| Gallium Nitride Module Captive Production | In-house transmit-receive arrays extend jamming range while reducing thermal management footprints for portable units. |
| EU AI Act Certification Investment | Human-in-the-loop verification protocols open civilian airport contracts under high-risk system classifications. |
| Aftermarket Threat-Library Subscription | Recurring firmware updates generate revenue streams independent of hardware procurement cycles. |
| Acoustic-Radar Fusion Development | Microphone-array detection penetrates Tokyo and Singapore electromagnetic spectrum congestion environments. |
Methodological Framework
A spread of perspectives from defense procurement officers, critical infrastructure security directors, radar systems engineers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA directive filings, EASA drone regulation amendments, EU AI Act implementation guidance, and defense ministry budget appropriations documents. Bottom-up unit deployment estimates triangulated against top-down market sizing from prime contractor revenue disclosures.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include product type, detection technology, end-user category, and application mission. CAGRs derived from deployment trajectory analysis against procurement cycle compression factors. Industry-specific forecast inputs incorporated gallium nitride module maturation curves and EU AI Act compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations, semiconductor supply constraints, or spectrum allocation rulings would shift the trajectory. Forecasts reflect documented assumptions about procurement cycle compression and regulatory harmonization. Cross-checking against NATO member state defense expenditure benchmarks and civilian airport capital improvement plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Aerospace Robotics Market