
 Central and Eastern Europe Cold Chain Logistics Market | 2026-2036
Central and Eastern Europe Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Central and Eastern Europe Cold Chain Logistics Market Outlook
The gap between premium temperature-controlled pharma logistics and commodity food cold storage is expanding across Central and Eastern Europe. Lineage Logistics leverages its automated high-bay warehouse network to dominate pharmaceutical-grade storage in Poland. NewCold sustains competitive advantage through proprietary automated storage and retrieval systems designed for frozen food consolidation. Dachser SE anchors its regional position with integrated road freight and warehousing coverage across the Czech Republic, Slovakia, and Hungary.
Central and Eastern Europe cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods, requiring continuous maintenance between minus eighty degrees Celsius and plus twenty-five degrees Celsius through insulated vehicles, refrigerated containers, and climate-monitored warehouses to preserve product integrity across pharmaceutical, food, and chemical supply chains. Warehousing commands the largest service type revenue pool due to land and energy cost inflation driving consolidation into automated multi-temperature facilities, while pharmaceutical end users generate the highest margin per pallet because of GDP validation requirements and audit-intensive compliance protocols. Frozen temperature range logistics maintains volume leadership through meat and dairy trade flows, though ultra-frozen segments for cell therapies and mRNA vaccines represent the fastest-expanding capacity investment category.
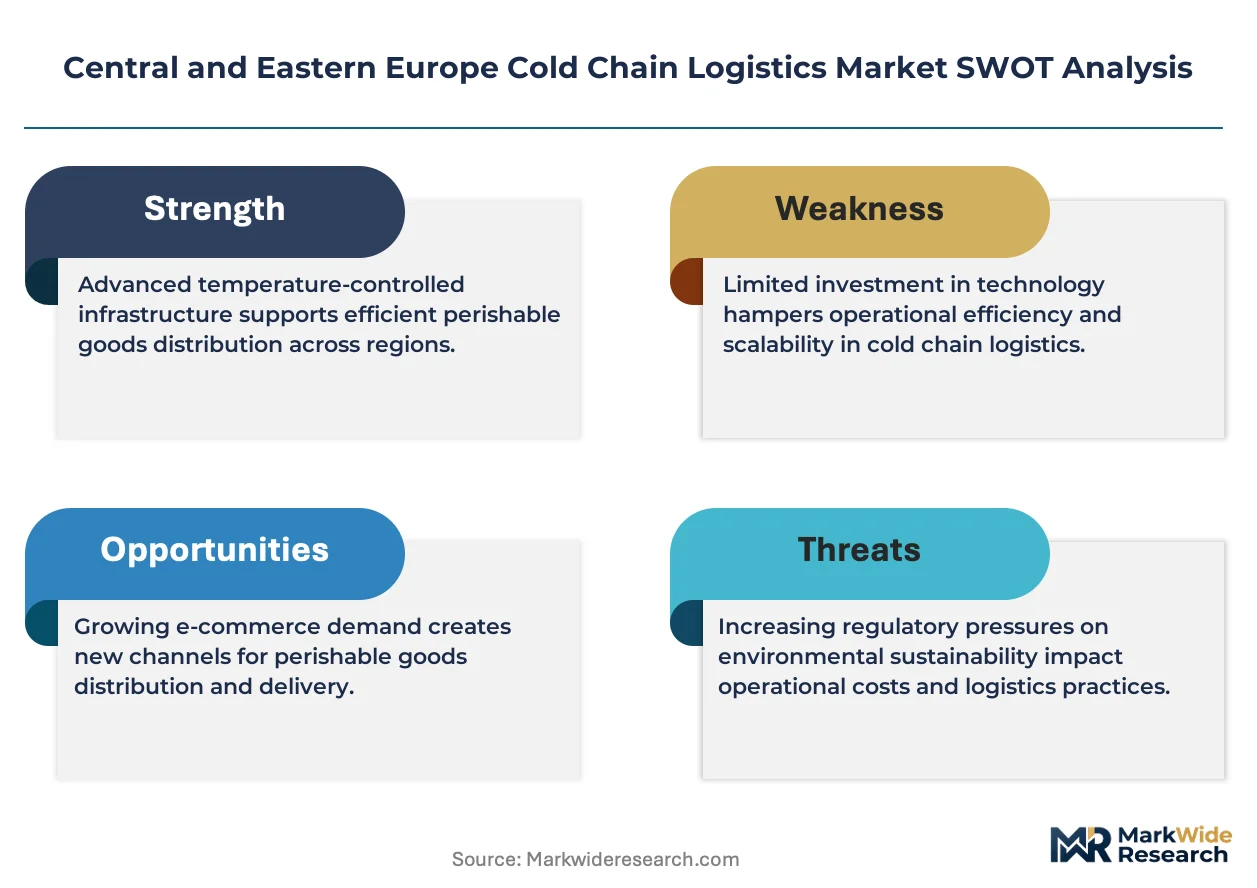
The EU GDP guidelines enforced by national regulators in each member state mandate qualified equipment, validated processes, and continuous temperature documentation for pharmaceutical distribution, creating compliance barriers that favor capital-intensive operators over fragmented local hauliers. Poland's Chief Sanitary Inspectorate and the Czech State Institute for Drug Control conduct unannounced inspections that suspend non-compliant operators, directing contract volumes toward certified multinational networks. Stakeholders must monitor the implementation timeline of the EU F-Gas Regulation's phase-down quotas, as refrigerant cost spikes and equipment retrofit requirements will reshape fleet replacement cycles and warehouse cooling system economics before the decade's midpoint.
Market Dynamics
The EU F-Gas Regulation's hydrofluorocarbon phase-down is compressing fleet replacement cycles and forcing warehouse operators across Poland, the Czech Republic, and Hungary to accelerate CO2 transcritical cooling retrofits before refrigerant cost spikes hit mid-decade.
Growth Catalysts
- Pharmaceutical GDP compliance:Poland's Chief Sanitary Inspectorate and the Czech State Institute for Drug Control enforce continuous temperature documentation mandates. Certified operators capture contract volumes from fragmented local hauliers suspended during unannounced inspections.
- Automated high-bay warehouse deployment:Food processing clusters along the Warsaw-Łódź corridor are consolidating into multi-temperature facilities with automated storage and retrieval systems. Land and energy cost inflation drives this consolidation.
- Cell therapy logistics emergence:Ultra-frozen segments for mRNA vaccines and regenerative medicines represent the fastest-expanding capacity investment category. Biologics manufacturers require minus eighty degrees Celsius qualified equipment and validated processes.
Market Restraints
- Refrigerant supply concentration:HFC quota reductions under the EU F-Gas Regulation create input cost volatility. Equipment retrofit requirements strain balance sheets before natural replacement cycles.
- Capital intensity barriers:GDP validation requirements and audit-intensive compliance protocols favor capital-intensive multinational networks. Fragmented local operators lack resources for continuous temperature monitoring infrastructure.
- Energy price exposure:Automated cold storage facilities face margin compression from electricity cost fluctuations. Poland and Hungary grid pricing volatility directly impacts warehouse cooling system economics.
Strategic Opportunities
- Slovak pharma corridor development:Bratislava's proximity to Vienna and Budapest positions it for underpenetrated biologics distribution hub status. EU GDP guidelines apply uniformly, lowering cross-border compliance friction.
- Ammonia-CO2 cascade system adoption:Converging natural refrigerant technologies enable industrial-scale freezing with lower global warming potential. Meat and dairy processors in the Czech Republic pilot these installations.
- Integrated road-rail intermodal:New multimodal terminals in Hungary connect refrigerated container flows to Adriatic and Black Sea ports. This channel innovation reduces road freight exposure to driver shortages.
Industry Challenges
- Qualified technician scarcity:CO2 transcritical and ammonia-based cooling systems require specialized refrigeration engineers. Poland's technical vocational pipeline produces insufficient certified installers for retrofit timelines.
- GDP certification timeline compression:Pharmaceutical manufacturers demand qualified equipment deployment within eighteen-month windows. Warehouse operators struggle to complete validation protocols while maintaining existing contract service levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central and Eastern Europe Cold Chain Logistics Market |
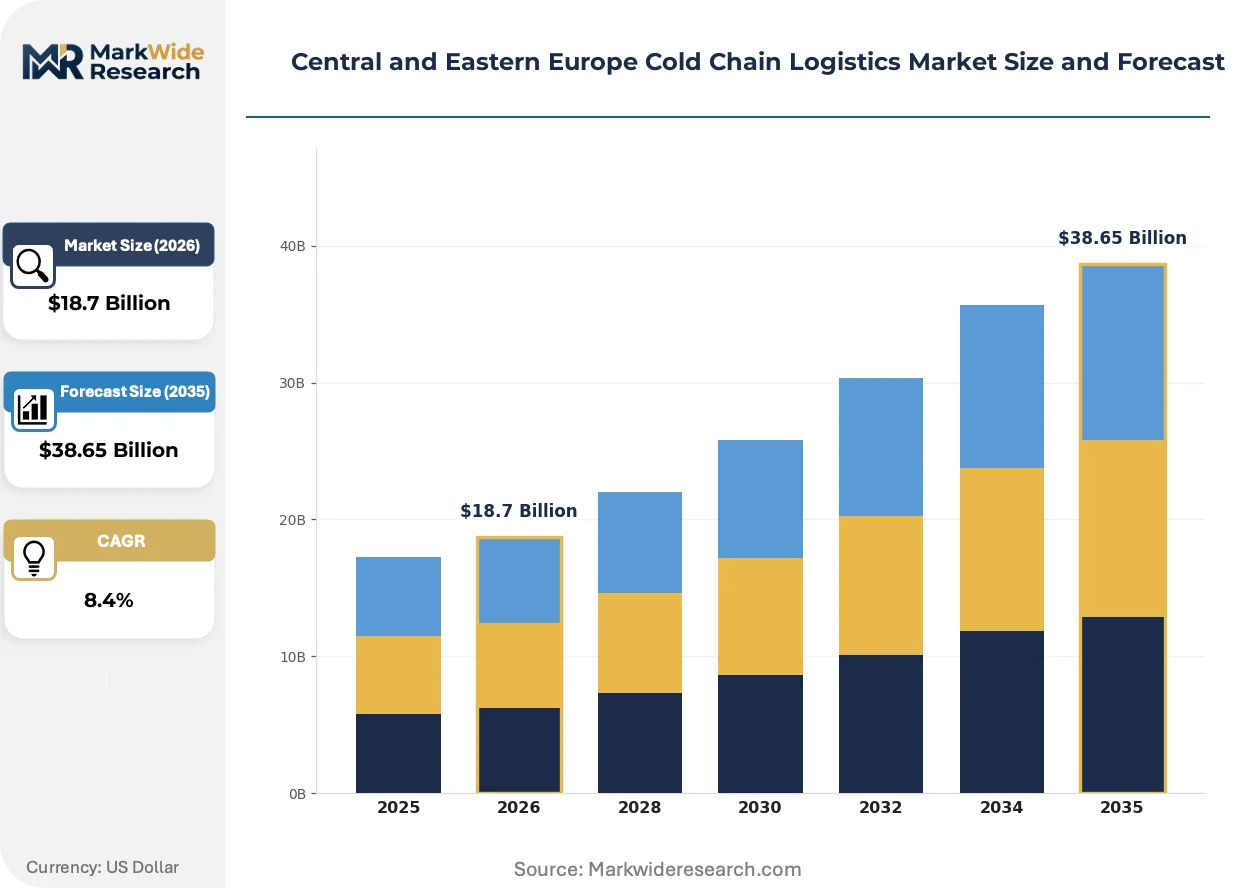
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Refrigeration End User: Pharmaceuticals, Food & Beverage, Cosmetics, Chemicals Temperature Range: Ambient, Chilled, Frozen, Ultra-Frozen Transportation Mode: Road, Rail, Air, Sea |
| Companies Covered | Lineage Logistics, NewCold, DHL Supply Chain, CEVA Logistics, Dachser SE, DSV, Kuehne + Nagel, Rhenus Logistics, Raben Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central and Eastern Europe Cold Chain Logistics Market Strategic Shifts
Digital temperature monitoring and predictive analytics are compressing excursion response times across pharmaceutical lanes. Automation investments now prioritize traceability integration over pure storage density.
IoT-enabled sensor networks with real-time cloud telemetry are expanding into pharmaceutical distribution lanes between Warsaw, Prague, and Budapest. Biologics shippers now mandate minute-by-minute temperature logging with automated alert escalation. This connectivity layer is expanding into contract terms as a non-negotiable service specification, displacing manual logger retrieval and batch record reconciliation.
The EU F-Gas Regulation's stepped quota reductions are forcing refrigerant transition strategies across the region's warehouse fleet. Operators must choose between early equipment retirement and costly HFC reclamation systems. Pharmaceutical-grade facilities in Poland face the tightest compliance deadlines due to their larger refrigeration charge sizes and stricter leak detection requirements.
Consolidation among food retailers is concentrating procurement power in fewer buying centers. Large Polish and Czech supermarket chains now demand vendor-managed inventory with continuous replenishment signals. This behavioral shift compresses order cycle times and pushes cold storage operators toward automated picking systems that can handle mixed-case frozen and chilled consolidation.
Central and Eastern Europe Cold Chain Logistics Market Segmentation
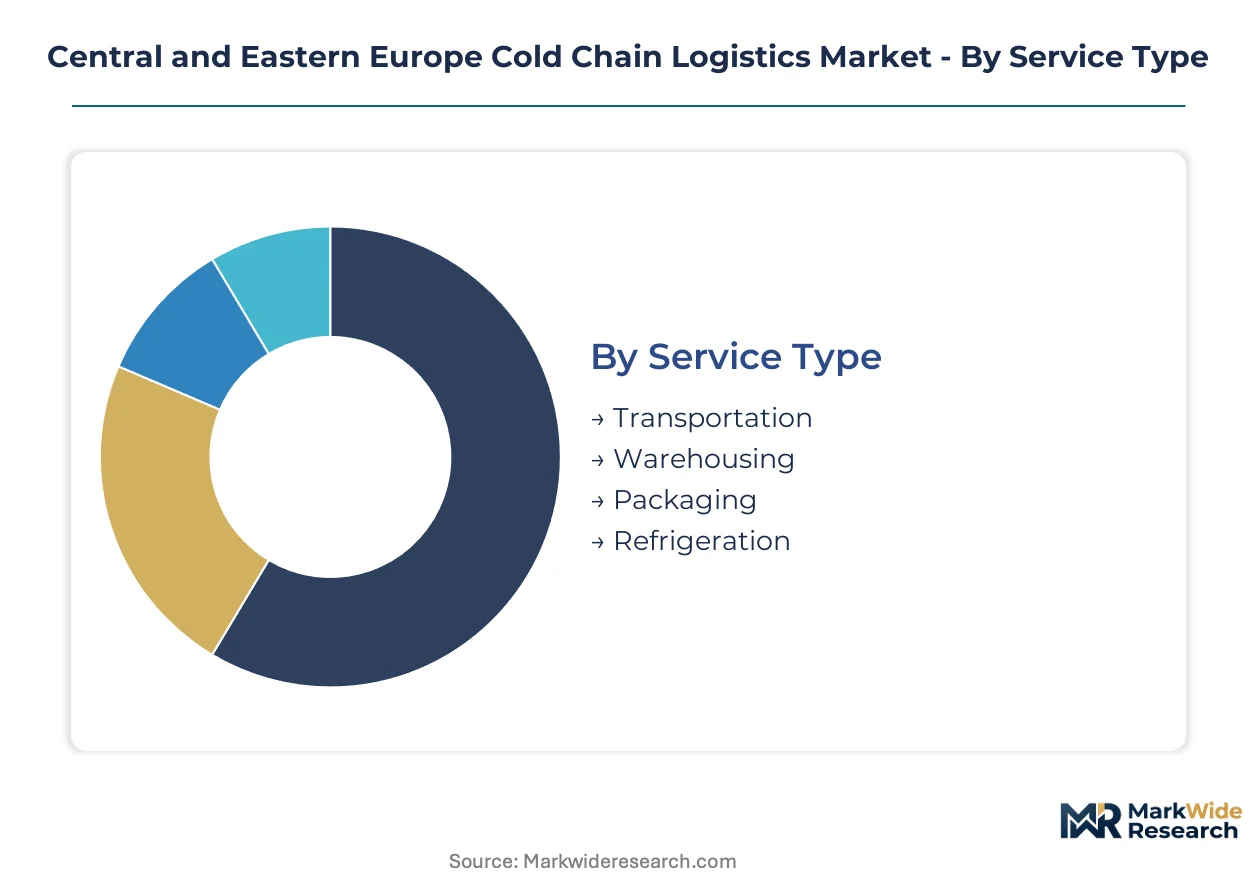
Segmentation in Central and Eastern Europe cold chain logistics reveals how capital deployment, regulatory pressure, and end-use requirements fragment service capabilities. Each dimension exposes distinct margin structures and investment priorities across Poland, the Czech Republic, and Hungary.
Service Type:
Supply concentration in automated multi-temperature facilities is compressing margins for standalone transport operators while elevating warehouse economics.
- Warehousing:Automated high-bay facilities with AS/RS technology dominate capital deployment along the Warsaw-Łódź corridor. Land scarcity and energy cost inflation push food processors and pharma manufacturers toward consolidated, multi-temperature campuses with integrated picking systems.
- Transportation:Refrigerated fleet operations face compressed replacement cycles as the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants. Road freight operators in Poland and Hungary absorb margin pressure from driver shortages while competing for pharmaceutical GDP-certified contract volumes.
- Packaging:Insulated shippers and phase-change materials protect temperature-sensitive biologics during last-mile distribution. GDP validation requirements mandate qualified packaging systems with documented thermal performance.
- Refrigeration:CO2 transcritical and ammonia-based cooling systems displace HFC equipment ahead of mid-decade quota reductions. Czech meat processors pilot ammonia-CO2 cascade installations for industrial-scale freezing.
Warehousing absorbs the bulk of installed capacity; refrigeration infrastructure is expanding most quickly as retrofit deadlines approach.
End User:
Margin stratification across end-use segments reflects divergent compliance burdens and contract security profiles.
- Pharmaceuticals:GDP-mandated continuous temperature documentation and audit-intensive protocols generate the highest margin per pallet. Poland's Chief Sanitary Inspectorate and the Czech State Institute for Drug Control suspend non-compliant operators, directing volumes toward certified multinational networks.
- Food & Beverage:Frozen meat and dairy trade flows sustain volume leadership across the region. Retailer consolidation in Poland and Czechia concentrates procurement power, demanding vendor-managed inventory with automated replenishment signals.
- Cosmetics:Temperature-sensitive skincare and active ingredient formulations require chilled distribution lanes. Brands leverage Central European warehousing hubs for EU-wide fulfillment.
- Chemicals:Industrial reagents and specialty chemicals need controlled ambient-to-chilled storage. Hazmat overlay requirements limit operator participation in this segment.
Food and beverage commands absolute volume; pharmaceuticals is climbing the fastest as biologics manufacturing expands across Poland and the Czech Republic.
Temperature Range:
Equipment qualification tiers separate commodity operators from premium service providers capable of handling advanced therapies.
- Frozen:Minus eighteen degrees Celsius standards dominate meat, dairy, and prepared food storage. Automated facilities in Hungary and Poland optimize energy efficiency for high-turnover frozen inventory.
- Ultra-Frozen:Minus eighty degrees Celsius capability serves mRNA vaccines and cell therapies. Biologics manufacturers in Warsaw and Prague require qualified equipment with validated processes and redundant backup systems.
- Chilled:Two to eight degrees Celsius bands handle fresh produce, dairy, and temperature-sensitive pharmaceuticals. Last-mile distribution in urban Czech and Polish corridors strains fleet availability.
- Ambient:Fifteen to twenty-five degrees Celsius coverage supports cosmetics and stable pharmaceuticals. This segment faces the weakest differentiation and lowest barriers to entry.
Frozen retains the largest installed base; ultra-frozen infrastructure is gaining share fastest as regenerative medicine manufacturing scales.
Transportation Mode:
Modal choice reflects distance economics, port access, and the urgency of temperature-sensitive cargo.
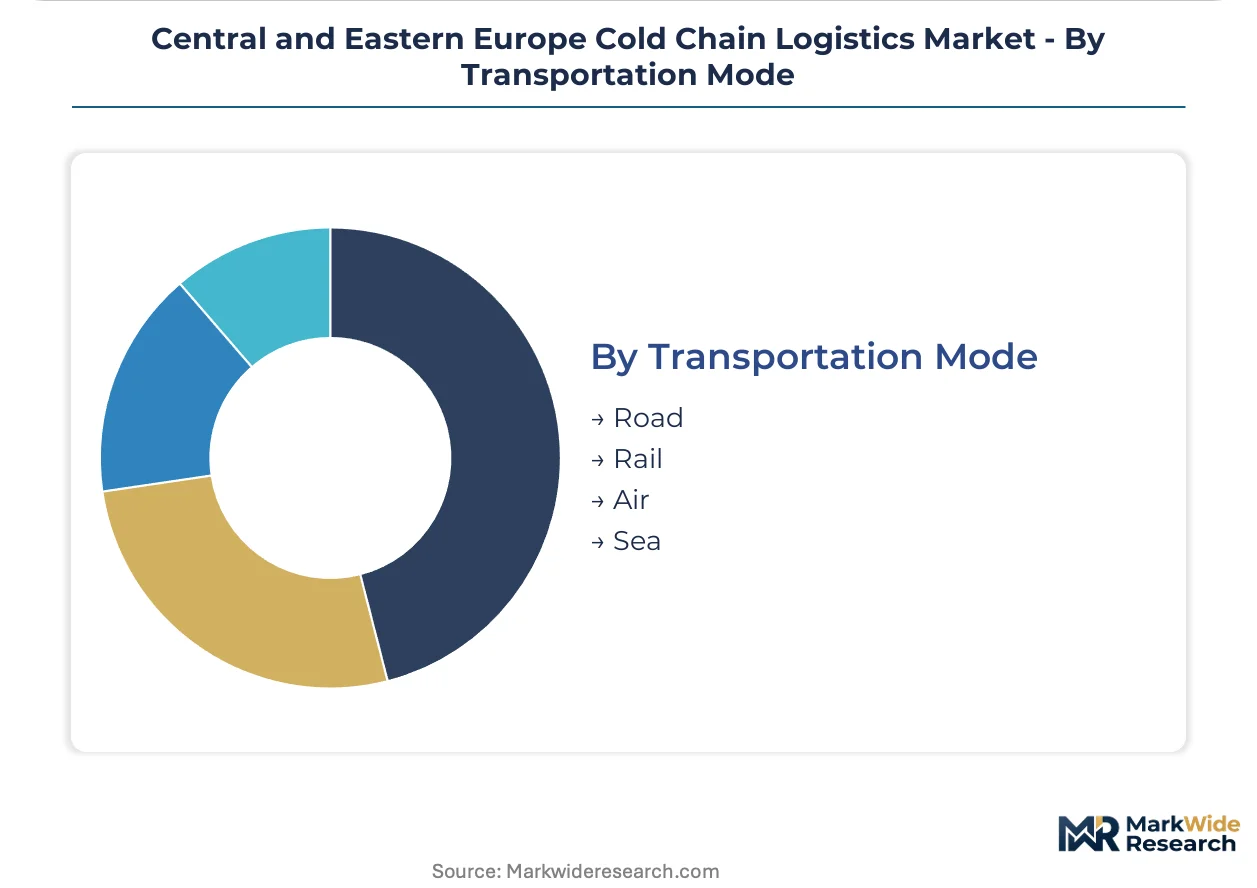
- Road:Refrigerated trucking dominates intra-regional distribution with flexibility for time-definite pharmaceutical deliveries. Driver shortages across Poland and Hungary constrain capacity expansion.
- Rail:Intermodal refrigerated containers connect Hungarian terminals to Adriatic and Black Sea ports. This mode reduces exposure to road freight volatility for bulk frozen movements.
- Air:Time-critical biologics and clinical trial materials move through Warsaw Chopin and Prague Václav Havel airports. GDP-compliant handling infrastructure limits viable operators.
- Sea:Reefer containers handle import volumes of frozen meat and seafood through Baltic and Adriatic ports. Modal share remains constrained by Central Europe's landlocked geography.
Road retains dominant modal share; rail intermodal is expanding most quickly as new terminal investments come online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Warsaw-Łódź corridor anchors cold chain capacity concentration across Central and Eastern Europe. This industrial axis hosts the region's densest clustering of automated multi-temperature warehouses serving pharmaceutical manufacturing and food processing.
Poland
Pharmaceutical manufacturing expansion in Warsaw and Łódź drives demand for GDP-certified warehousing. The Chief Sanitary Inspectorate enforces continuous temperature documentation through unannounced inspections. Food processing clusters along the Warsaw-Łódź corridor consolidate into automated high-bay facilities with integrated picking systems.
Czech Republic
Biologics production in Prague requires minus eighty degrees Celsius qualified equipment for cell therapy distribution. The State Institute for Drug Control suspends non-compliant operators during regulatory audits. Meat processors in the Moravian region pilot ammonia-CO2 cascade cooling installations ahead of F-Gas Regulation deadlines.
Hungary
Multimodal refrigerated terminals near Budapest connect container flows to Adriatic and Black Sea ports. Grid pricing volatility strains warehouse cooling system economics across automated facilities. Pharmaceutical distribution hubs in the capital region absorb EU GDP compliance costs to capture cross-border contract volumes.
Slovakia
Bratislava's proximity to Vienna and Budapest positions the city for biologics distribution hub development. EU GDP guidelines apply uniformly across member states, lowering cross-border compliance friction. Automotive and electronics manufacturing in the western regions generates ancillary demand for temperature-controlled component logistics.
Romania
Black Sea port access supports reefer container imports of frozen meat and seafood into Constanța. The national pharmaceutical regulator enforces qualified equipment standards for temperature-sensitive drug distribution. Bucharest logistics zones attract cold storage investment serving domestic retail consolidation.
Central and Eastern Europe Cold Chain Logistics Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade warehousing. The market structure bifurcates between capital-intensive multinational networks with GDP validation capabilities and fragmented local hauliers lacking continuous temperature monitoring infrastructure. Three archetypes dominate: automated high-bay warehouse operators, integrated road freight and warehousing providers, and specialized pharmaceutical-grade logistics networks. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through corridor-specific facility deployment.
Within the automated warehousing tier, Lineage Logistics and NewCold exemplify divergent specialization strategies. Lineage Logistics anchors pharmaceutical-grade storage positioning through high-bay automation density. NewCold occupies a position emphasizing proprietary systems for frozen food consolidation. Dachser SE represents the integrated service archetype, spanning road freight coverage with multi-country warehousing networks across the Czech Republic, Slovakia, and Hungary.
| Leading Market Players |
|---|
| Lineage Logistics |
| NewCold |
| DHL Supply Chain |
| CEVA Logistics |
| Dachser SE |
| DSV |
| Kuehne + Nagel |
| Rhenus Logistics |
| Raben Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up warehouse operators across Poland and the Czech Republic are consolidating fragmented cold storage assets into platform networks that extract pricing power through GDP certification scarcity. Their financing structure rewards throughput-based revenue models while the EU F-Gas Regulation's retrofit deadlines compress competitor margins.
Pricing Analysis
Outcome-based pricing anchored to temperature excursion rates and audit compliance scores dominates pharmaceutical-grade contracts. Three-tier pricing structure across GDP-validated premium, HFC-transitional standard, and commodity frozen economy levels separates certified operators from local hauliers. Pricing pressure stems from energy cost volatility straining automated facility economics. Food retailers exhibit highest price sensitivity through consolidated procurement centers, while biologics manufacturers accept premium rates for minus eighty degrees Celsius capability.
Supply Chain Analysis
Refrigerated freight costs from Poland, the Czech Republic, and Hungary into Western Europe absorb margin through driver shortages and diesel price exposure. Equipment sourcing draws from German compressor manufacturers, Italian refrigeration engineering, and Chinese sensor component suppliers. Single-source vulnerability concentrates in qualified CO2 transcritical system installers across the Warsaw-Łódź corridor. Distribution runs through hub-and-spoke warehouse networks with last-mile pharmaceutical delivery subcontracted to GDP-certified regional fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Central and Eastern Europe cold chain logistics market functions as a cost-of-compliance story where the EU F-Gas Regulation and GDP guidelines erect capital barriers that protect certified incumbents from price competition.
For Market Incumbents: Lock in pharmaceutical contract renewals ahead of mid-decade refrigerant quota reductions that will disqualify non-compliant competitors. Secure ammonia-CO2 cascade engineering partnerships in the Czech Republic before technician scarcity tightens retrofit timelines. Vertical integration into packaging qualification laboratories defends margin position against audit-intensive client demands. For New Entrants and Emerging Players: IoT-enabled temperature telemetry platforms offer a technology-first wedge into underserved Slovak biologics distribution lanes. Target Bratislava's underpenetrated pharma corridor where EU GDP guidelines lower cross-border compliance friction. Lead with minute-by-minute cloud logging capabilities that incumbent road hauliers lack capital to replicate. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated high-bay operators in Hungary facing energy price compression but holding irreplaceable multimodal terminal access. Long-term viability hinges on natural refrigerant transition completion and pharmaceutical certification density. Watch ammonia-CO2 cascade adoption rates across Moravian meat processors as inflection signal for equipment supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | Poland's Chief Sanitary Inspectorate suspensions redirect contract volumes toward validated operators. |
| Natural Refrigerant Retrofit | CO2 transcritical deployment ahead of EU F-Gas Regulation deadlines secures fleet replacement economics. |
| Automated High-Bay Expansion | Warsaw-Łódź corridor land scarcity rewards density-optimized AS/RS campus development. |
| Multimodal Terminal Integration | Hungarian rail connections to Adriatic ports reduce road freight exposure to driver shortages. |
| Pharma Corridor Geographic Expansion | Bratislava's Vienna-Budapest proximity captures underpenetrated biologics distribution hub status. |
Study Parameters
Independent corroboration across cold storage facility operators, pharmaceutical logistics procurement managers, and refrigeration engineering specialists underwrites the qualitative findings. Primary fieldwork engaged warehouse automation directors, GDP compliance officers at biologics manufacturers, fleet operations heads, and temperature monitoring technology vendors. Secondary validation drew from EU F-Gas Regulation implementation timelines, national pharmaceutical inspectorate enforcement records, customs trade data for refrigerated container flows, and energy grid pricing disclosures. Bottom-up capacity modeling triangulated against top-down regional demand aggregation.
Comparable-period anchoring calibrated the projection horizon against historical refrigerant phase-down cycles and pharmaceutical distribution network expansion patterns. Segmentation modeling spanned service type, end-use vertical, temperature qualification tier, and transportation mode across the analysis window. CAGRs derived from equipment replacement cycle compression, biologics manufacturing capacity announcements, and automated warehouse deployment pipelines. Forecast inputs incorporated EU quota reduction schedules and national inspectorate audit frequency trends.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement intensity variations, breakthroughs in solid-state cooling technology, and geopolitical disruptions to cross-border pharmaceutical trade flows. Forecasts reflect documented assumptions about refrigerant cost trajectories and certification timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market