
 Battery Charge Controller Market | 2026-2036
Battery Charge Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Charge Controller Market Insights
The gap between PWM and MPPT conversion efficiency is narrowing as algorithmic tracking and semiconductor packaging advance. Schneider Electric SE leverages its integrated energy management portfolio to anchor utility-scale deployments across multiple continents. Victron Energy competes through deep specialization in off-grid and marine applications where firmware configurability commands premium positioning. Morningstar Corporation sustains its standing in rural electrification projects through extended temperature-range hardware and remote monitoring compatibility.
A battery charge controller regulates voltage and current flow from generation sources to storage banks, preventing overcharge and deep discharge through pulse-width modulation, maximum power point tracking, or linear regulation typically spanning 12V to 48V nominal systems with amperage ratings from 10A to 100A. Its primary purpose centers on protecting lithium-ion and lead-acid battery chemistries while optimizing energy harvest from photovoltaic arrays. MPPT controllers capture the dominant margin pool in commercial and industrial installations where conversion efficiency differentiates system returns. PWM variants retain volume leadership in residential solar deployments across price-sensitive emerging markets. Hybrid controllers integrating wind and solar inputs represent the fastest-growing product architecture as multi-source microgrids proliferate.
FERC Order 2222 in the United States enables distributed energy aggregation that elevates controller interoperability requirements, while the EU Green Deal and CE marking directives enforce efficiency minimums and electromagnetic compatibility standards for equipment sold across European member states. India's CEA grid connectivity regulations and BIS certification mandates shape product qualification pathways for imports and domestic manufacturing alike. Stakeholders must monitor how evolving inverter-controller convergence and battery chemistry transitions toward solid-state architectures reshape hardware specification priorities and supplier qualification criteria.
Market Dynamics
The convergence of inverter-controller hardware and firmware-defined power electronics is collapsing procurement categories. Buyers now specify integrated energy management units rather than discrete charge controllers, forcing suppliers to reposition around system-level value capture.
Growth Catalysts
- India's CEA grid connectivity regulations:Rural microgrid mandates under the national solar rooftop program sustain procurement volumes for both PWM and MPPT controller architectures. Domestic manufacturing incentives accelerate local assembly qualification.
- Off-grid residential solar in Sub-Saharan Africa:National electrification mandates in Kenya, Nigeria, and Tanzania propel distributed generation deployment. Declining photovoltaic module costs expand addressable household segments.
- Algorithmic maximum power point tracking:Semiconductor packaging advances narrow efficiency gaps between controller topologies. Cost-sensitive buyers gain access to performance previously restricted to premium tiers.
Market Restraints
- Silicon carbide wafer supply concentration:High-performance switching substrate production clusters in limited East Asian foundry capacity. Input cost volatility constrains margin expansion for advanced MPPT designs.
- FERC Order 2222 interoperability requirements:Distributed energy aggregation standards impose firmware certification burdens on smaller controller suppliers. Compliance timeline friction advantages integrated energy management portfolios.
- Direct-coupled lithium-ion battery packs:Module-level power electronics in utility-scale storage displace external charge controller functions. Substitution threat concentrates in commercial and industrial installations above 100kW.
Strategic Opportunities
- Indonesia's archipelago microgrids:Maritime logistics constraints favor modular hybrid controllers integrating solar, wind, and diesel inputs. Remote island electrification programs create specification pull for multi-source architectures.
- Brazil's ANVISA medical device power standards:Healthcare facility backup power regulations mandate isolated battery management systems. Premium positioning opens for controllers with medical-grade electromagnetic compatibility certification.
- Wind-solar hybrid controller convergence:Multi-source input architectures capture fastest-growing product segment. Firmware configurability for variable renewable combinations differentiates supplier offerings.
Industry Challenges
- Firmware engineering talent scarcity:Power electronics algorithm development and embedded systems integration skills concentrate in automotive and consumer electronics sectors. Controller manufacturers compete for limited qualified personnel.
- CE marking electromagnetic compatibility testing:EU Green Deal efficiency minimums and revised CE directives extend certification timelines. Smaller suppliers face working capital pressure from delayed market entry.
- Legacy lead-acid system integration:Rural electrification projects in South Asia and Africa maintain substantial installed base of older battery chemistries. Dual-chemistry firmware support increases development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Charge Controller Market |
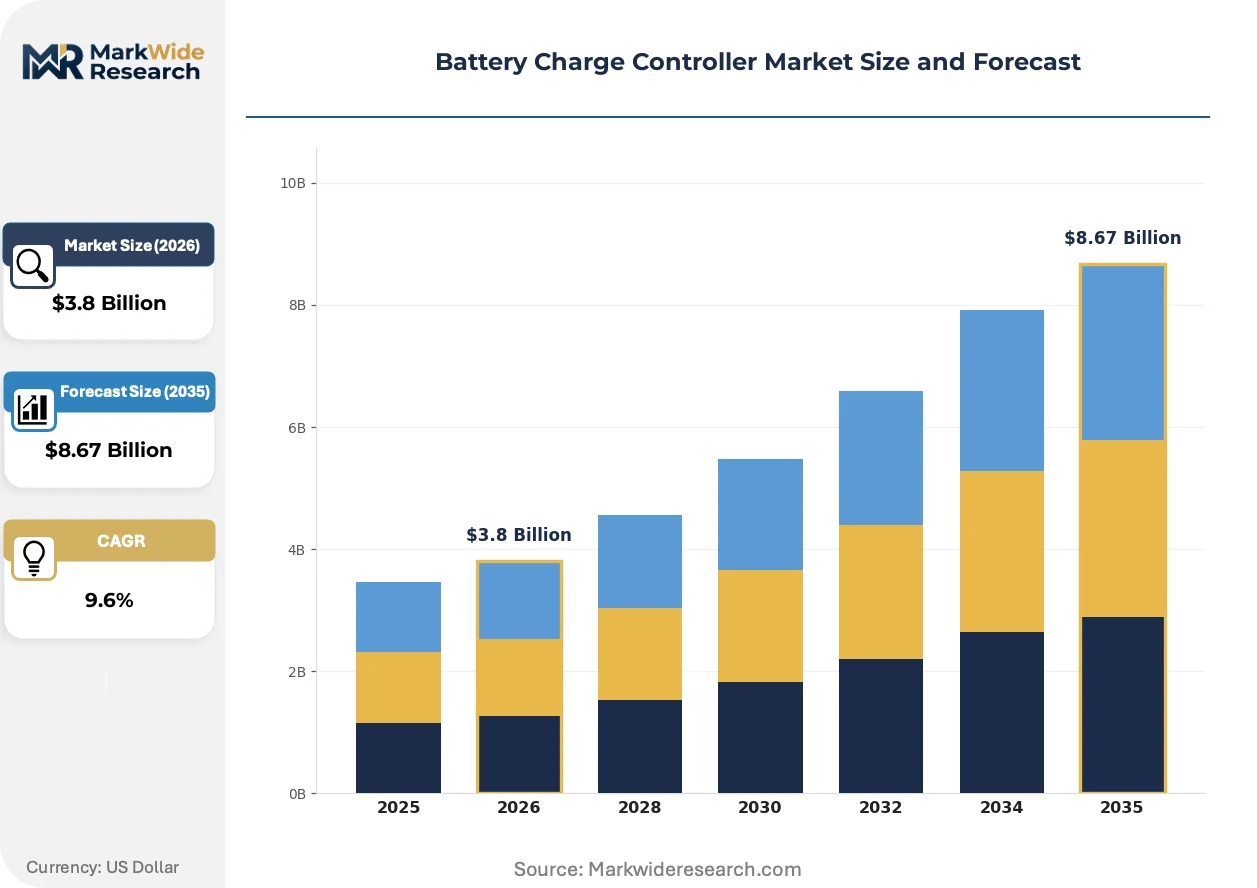
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PWM Controllers, MPPT Controllers, Linear Controllers, Hybrid Controllers Technology: Solar, Wind, Fuel Cell, Others End User: Residential, Commercial, Industrial, Automotive Application: Renewable Energy Systems, UPS, Electric Vehicles, Telecom |
| Companies Covered | Schneider Electric SE, Victron Energy, Morningstar Corporation, SUNGROW, Studer Innotec SA, OutBack Power Technologies, Beijing Epsolar Technology Co., Ltd., Luminous Power Technologies (P) Ltd., Xantrex Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Charge Controller Market Trends and Innovations
Controller hardware is dissolving into software-defined power management layers. Algorithmic control, semiconductor material transitions, and procurement model compression are reshaping supplier competitive requirements.
Gallium nitride switching substrates are replacing silicon MOSFETs in high-frequency MPPT designs. Marine and off-grid residential buyers in Northern Europe adopt these topologies for reduced thermal management footprint. The technology is hybridizing thermal and electrical design disciplines, compressing enclosure size specifications while expanding operating temperature ranges.
The EU F-Gas Regulation and revised CE marking directives enforce stricter electromagnetic compatibility thresholds for equipment sold across member states. Industrial and commercial solar installers face compliance verification burdens that favor pre-certified controller-inverter bundles. German and Italian project developers now specify integrated energy management units to minimize qualification risk.
After-sales service contracts are unbundling from hardware procurement across African and South Asian rural electrification programs. Microgrid operators in Kenya and Bangladesh now subscribe to remote monitoring and firmware update services separately from initial controller purchase. This consumption-pattern shift compresses upfront capital requirements while extending supplier revenue duration.
Battery Charge Controller Market Segmentation
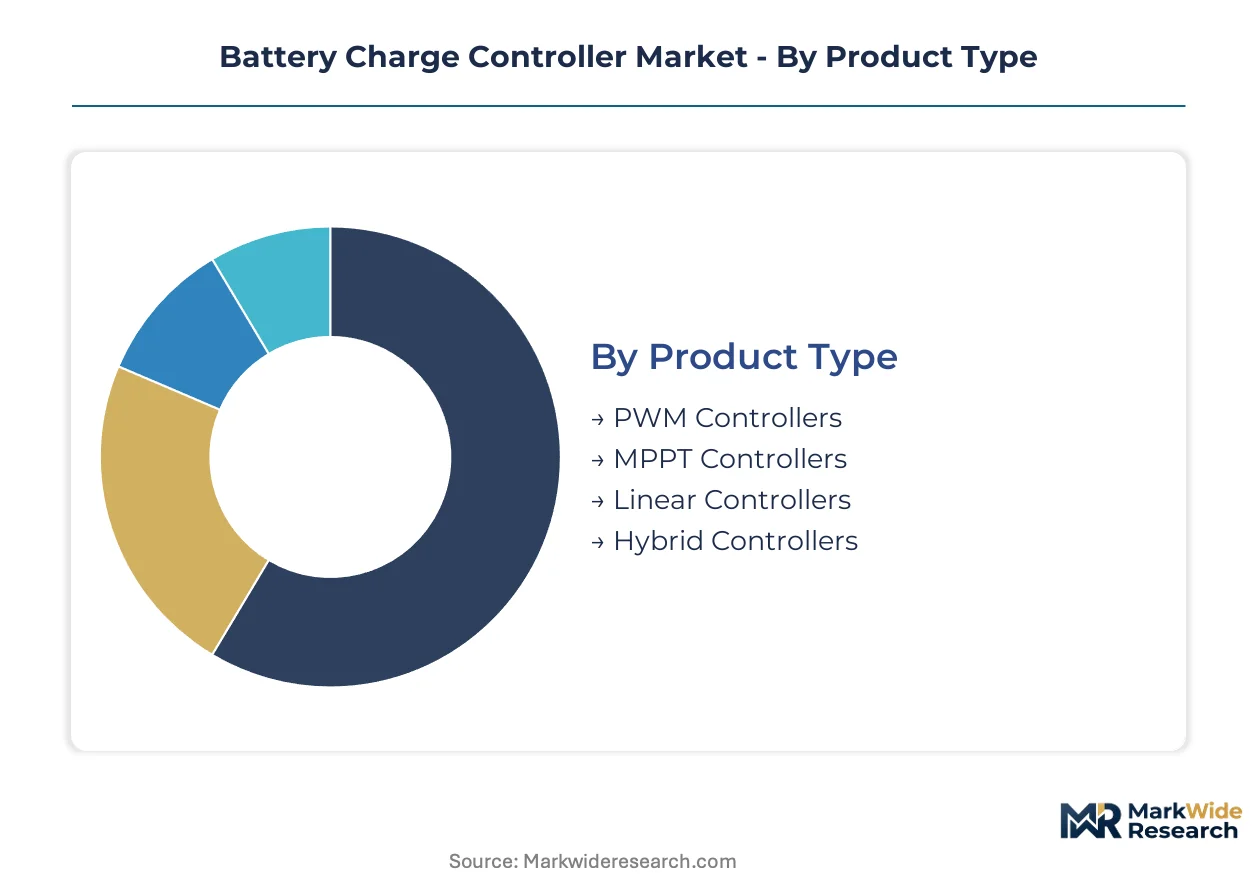
Controller segmentation determines procurement pathways and margin capture. Product topology dictates firmware complexity, while application context shapes certification requirements and service intensity.
Product Type:
After-sales service intensity varies sharply across controller architectures, with remote firmware management and thermal monitoring creating recurring revenue opportunities.
- MPPT Controllers:Maximum power point tracking algorithms dynamically adjust voltage-current curves to harvest peak photovoltaic output. Commercial and industrial installations in India concentrate demand as conversion efficiency directly impacts project returns. Algorithmic advances and gallium nitride switching substrates compress thermal footprints while expanding operating temperature ranges.
- Hybrid Controllers:Multi-source input architectures integrate solar, wind, and diesel generation through configurable firmware layers. Maritime microgrids across Indonesia's archipelago drive specification pull where logistics constraints favor modular, multi-input units. Wind-solar hybrid convergence captures the steepest expansion trajectory as renewable diversification accelerates.
- PWM Controllers:Pulse-width modulation topologies regulate battery charging through simple on-off switching cycles. Price-sensitive residential deployments in Sub-Saharan Africa sustain volume leadership.
- Linear Controllers:Continuous voltage reduction through resistive dissipation suits low-power, cost-constrained applications with minimal efficiency requirements.
MPPT controllers hold the largest share; momentum sits with hybrid architectures.
Technology:
Cost tier stratification separates premium semiconductor substrates from commodity silicon designs.
- Solar:Photovoltaic input optimization dominates controller deployment, with MPPT and PWM variants capturing utility-scale and residential segments respectively. India's CEA grid connectivity regulations and rooftop mandates sustain procurement volumes across both topologies.
- Wind:Variable input voltage conditioning requires robust firmware algorithms to manage turbine output fluctuations. Northern European marine and off-grid residential buyers adopt these controllers for hybrid system integration.
- Fuel Cell:Precise current regulation protects proton exchange membrane stacks from thermal runaway. Automotive and stationary backup power applications in Japan concentrate early adoption.
- Others:Emerging generation sources including tidal and thermoelectric inputs drive niche controller specifications for specialized research and defense installations.
Solar technology anchors volume; fuel cell controllers are climbing the fastest as hydrogen infrastructure scales.
End User:
Customer type determines specification rigor, with industrial buyers demanding extended temperature ratings and remote monitoring compatibility.
- Industrial:Heavy-duty cycling and 24/7 operational requirements drive demand for ruggedized enclosures and predictive maintenance firmware. Manufacturing facilities across Germany and Italy specify integrated energy management units to satisfy EU F-Gas Regulation compliance burdens.
- Residential:Off-grid electrification programs in Kenya, Nigeria, and Tanzania propel distributed generation deployment where declining photovoltaic module costs expand addressable household segments.
- Commercial:Retail and office building solar installations prioritize rapid payback periods, favoring MPPT efficiency premiums in grid-tied configurations.
- Automotive:Electric vehicle auxiliary battery management requires compact, high-reliability controllers with automotive-grade electromagnetic compatibility certification.
Industrial end users command the largest share; residential off-grid segments gain share fastest.
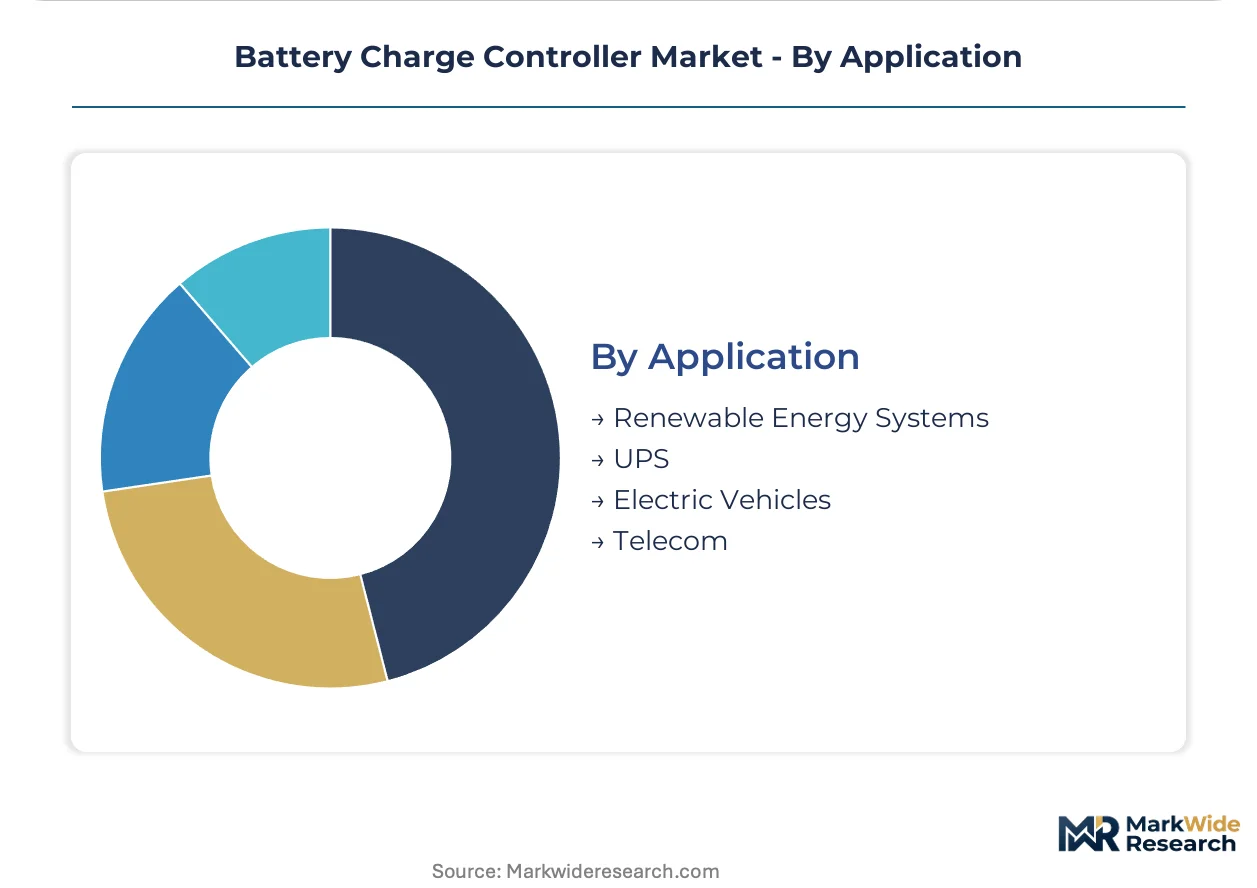
Application:
Volume concentration tracks electrification infrastructure buildout, with rural microgrids and telecom towers sustaining procurement pull.
- Renewable Energy Systems:Utility-scale and distributed solar installations require scalable controller architectures from residential 10A units to industrial 100A ratings. India's national solar rooftop program and rural microgrid mandates create sustained demand across PWM and MPPT variants.
- Telecom:Remote tower backup power systems demand high-reliability controllers with minimal maintenance intervals. Tower operators in Bangladesh and Kenya subscribe to remote monitoring services separately from hardware procurement.
- UPS:Uninterruptible power supply systems prioritize rapid switching and seamless grid-to-battery transitions for data center and healthcare facility protection.
- Electric Vehicles:Onboard battery management integration increasingly displaces external controller functions as module-level power electronics proliferate.
Renewable energy systems hold the largest share; telecom backup power applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany and utility-scale developers in India concentrate procurement volumes for high-efficiency MPPT controllers, while residential electrification programs across Sub-Saharan Africa sustain PWM demand.
United States
Utility-scale solar developers and distributed energy aggregators drive demand for grid-interactive controllers. FERC Order 2222 mandates firmware interoperability standards that favor integrated energy management portfolios. Texas and California project clusters specify MPPT architectures for commercial installations above 100kW.
Germany
Industrial manufacturing facilities and commercial solar installers prioritize pre-certified controller-inverter bundles. EU F-Gas Regulation and revised CE marking directives enforce electromagnetic compatibility thresholds. Bavarian and North Rhine-Westphalia industrial zones specify integrated units to minimize qualification risk.
India
Rural microgrid operators and national solar rooftop program implementers sustain procurement pull across PWM and MPPT variants. CEA grid connectivity regulations and BIS certification mandates shape import and domestic assembly pathways. Gujarat and Maharashtra manufacturing corridors accelerate local controller qualification under PLI scheme incentives.
Kenya
Off-grid residential electrification and telecom tower backup power operators subscribe to remote monitoring services. National electrification mandates expand distributed generation deployment. Nairobi and Mombasa microgrid clusters adopt modular hybrid controllers for solar-diesel integration.
Indonesia
Maritime microgrid developers across the archipelago specify multi-source hybrid controllers integrating solar, wind, and diesel inputs. Remote island electrification programs create logistics-constrained demand for modular units. Java and Sulawesi project clusters drive specification pull for configurable firmware architectures.
Battery Charge Controller Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement categories collapsing into integrated energy management units. The vendor base stratifies around three archetypes: diversified electrical conglomerates with system-level portfolios, deep specialists in off-grid and marine applications, and regional fabricators serving price-sensitive emerging markets. Competitive moves center on firmware-defined power electronics convergence and strategic partnerships with microgrid developers.
Among European-headquartered electrical conglomerates, Schneider Electric SE represents the integrated portfolio archetype spanning utility-scale deployments. Victron Energy B.V. and Morningstar Corporation exemplify the specialist tier, with Dutch and US origins respectively, occupying positions in off-grid and remote monitoring segments where firmware configurability commands premium positioning. These three anchors illustrate how supplier positioning compresses around either system-level value capture or application-specific depth.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Victron Energy |
| Morningstar Corporation |
| SUNGROW |
| Studer Innotec SA |
| OutBack Power Technologies |
| Beijing Epsolar Technology Co., Ltd. |
| Luminous Power Technologies (P) Ltd. |
| Xantrex Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Dongguan semiconductor packaging clusters anchor global controller component supply, with gallium nitride substrate capacity expansion feeding directly into MPPT controller pricing power for tier-one suppliers. Cost compression in PWM variants accelerates as silicon MOSFET oversupply from legacy foundries erodes margin buffers for mid-tier assemblers.
Pricing Analysis
Cost-plus contracts indexed to silicon carbide wafer spot prices dominate procurement for utility-scale MPPT controllers above 50kW. Three-tier pricing structure across premium, standard, and economy levels separates gallium nitride-enabled firmware-configurable units from commodity silicon designs. Pricing pressure stems from gallium nitride substrate yield improvements compressing premium tier premiums. Rural electrification programs in Kenya and Bangladesh exhibit highest price sensitivity, while German industrial buyers prioritize electromagnetic compatibility certification over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for controller manufacturers serving North American utility-scale developers. Semiconductor substrate fabrication concentrates in Taiwan, South Korea, and Japan, while final assembly clusters in China, India, and Vietnam. Controller production draws from silicon carbide wafers, aluminum thermal enclosures, and firmware development services. Distribution runs through EPC contractors and specialized renewable energy distributors rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery charge controller market sits in early-cycle recovery as photovoltaic module cost declines reaccelerate distributed generation deployment across price-sensitive emerging markets. Capital expenditure commitments from Indian and Indonesian microgrid developers signal sustained procurement pull through the projection horizon.
For Market Incumbents: Build switching-cost moats through firmware-defined power electronics convergence that locks microgrid operators into remote monitoring ecosystems. Deepen backward integration into gallium nitride semiconductor sourcing to offset Taiwan foundry concentration risk. Prioritize BIS certification investment for Indian PLI scheme qualification to defend against domestic assembly entrants.
For New Entrants and Emerging Players: Build out white-space presence in Indonesia's archipelago microgrid segment where maritime logistics constraints favor modular hybrid controller architectures. Target telecom tower backup power operators in Bangladesh and Kenya with subscription-based remote monitoring offerings. Pursue ANVISA medical-grade electromagnetic compatibility certification to access Brazil's healthcare facility backup power mandates.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-edge infrastructure play because distributed energy aggregation regulations elevate controller interoperability requirements that favor integrated software-hardware portfolios. Acquisition targets should demonstrate firmware engineering depth in multi-source input algorithms. Watch FERC Order 2222 compliance certification timelines as inflection signal for supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Substrate Integration | Enables thermal footprint reduction for Northern European marine and off-grid residential deployments. |
| Firmware-Defined Power Electronics Convergence | Collapses procurement categories toward integrated energy management units preferred by German industrial buyers. |
| Remote Monitoring Service Unbundling | Compresses upfront capital requirements for Kenyan microgrid operators while extending supplier revenue duration. |
| Hybrid Controller Multi-Source Architecture | Captures specification pull from Indonesia's remote island electrification programs facing logistics constraints. |
| Medical-Grade Electromagnetic Compatibility Certification | Opens premium positioning for Brazil's ANVISA-regulated healthcare facility backup power market. |
Research Methodology
Operator-level perspectives from microgrid developers, EPC contractors, firmware engineering directors, and rural electrification program procurement officers anchored the qualitative base for this analysis. Primary interview findings triangulated against customs trade data for controller imports, CEA and BIS regulatory filings, SEC 10-K disclosures from listed electrical conglomerates, and IEA distributed energy deployment databases. Bottom-up unit economics from individual project specifications combined with top-down market sizing across technology and end-use segments.
Scenario-bracketing framed the analytical approach, with demand trajectories tested against photovoltaic cost decline acceleration and silicon carbide supply expansion assumptions across the projection horizon. Segmentation modeling captured product topology, generation source technology, end-user category, and application context dimensions. CAGRs derived from installed base growth rates and replacement cycle analysis, with controller-inverter convergence timelines and battery chemistry transition curves as industry-specific forecast inputs.
Stress conditions across gallium nitride substrate supply disruptions, FERC interoperability compliance delays, and lithium-ion module-level power electronics substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory implementation timing or semiconductor material transition acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Power Integrated Modules Market
Power Systems
Global Plasma Generators Market
Power Systems
Series Reactor Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Automotive Power Electronics Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Battery Balancer Market