
 Flyback Transformer Market | 2026-2036
Flyback Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Flyback Transformer Market Analysis
Automotive-grade AEC-Q200 qualification is unwinding across supplier bases as EV onboard chargers and DC-DC modules require higher isolation ratings. TDK Corporation leverages its ferrite material verticality to anchor premium magnetics supply. Coilcraft specializes in compact surface-mount architectures for space-constrained medical and telecom designs. STMicroelectronics extends its power-management IC pairing strategy to tighten system-level integration around flyback controllers.
A flyback transformer stores energy in its gapped ferrite core during the switch-on interval and transfers it to the secondary winding during switch-off, with typical operating frequencies spanning 50 kHz to 500 kHz depending on topology and power rating. Switching mode technology dominates volume production due to efficiency advantages in adapter and LED driver applications, while isolated product types command margin premiums in medical devices and industrial equipment where safety agency clearance is mandatory. Digital control architectures represent the fastest-growing technology segment as programmable switching sequences enable adaptive loop compensation across variable load profiles.
REACH compliance in Europe restricts hazardous substance content in ferrite cores and coil formers, while the EU Ecodesign Directive mandates minimum efficiency thresholds for external power supplies that cascade into transformer specifications. The US FAA and FDA impose isolation and reliability standards on flyback units deployed in avionics and patient-contact medical equipment respectively. Stakeholders must monitor how pending updates to IEC 61558 safety standards for power transformers reshape testing protocols and market access timelines.
Market Dynamics
The EU Ecodesign Directive is cascading efficiency mandates through external power supply specifications, forcing ferrite core redesigns and tighter winding tolerances across supplier bases. China, Germany, and the United States concentrate procurement for high-reliability medical and automotive units, compressing delivery timelines for qualified sources.
Growth Catalysts
- AEC-Q200 qualification:Automotive-grade isolation requirements for EV onboard chargers and DC-DC modules are pulling certified transformer volumes upward.
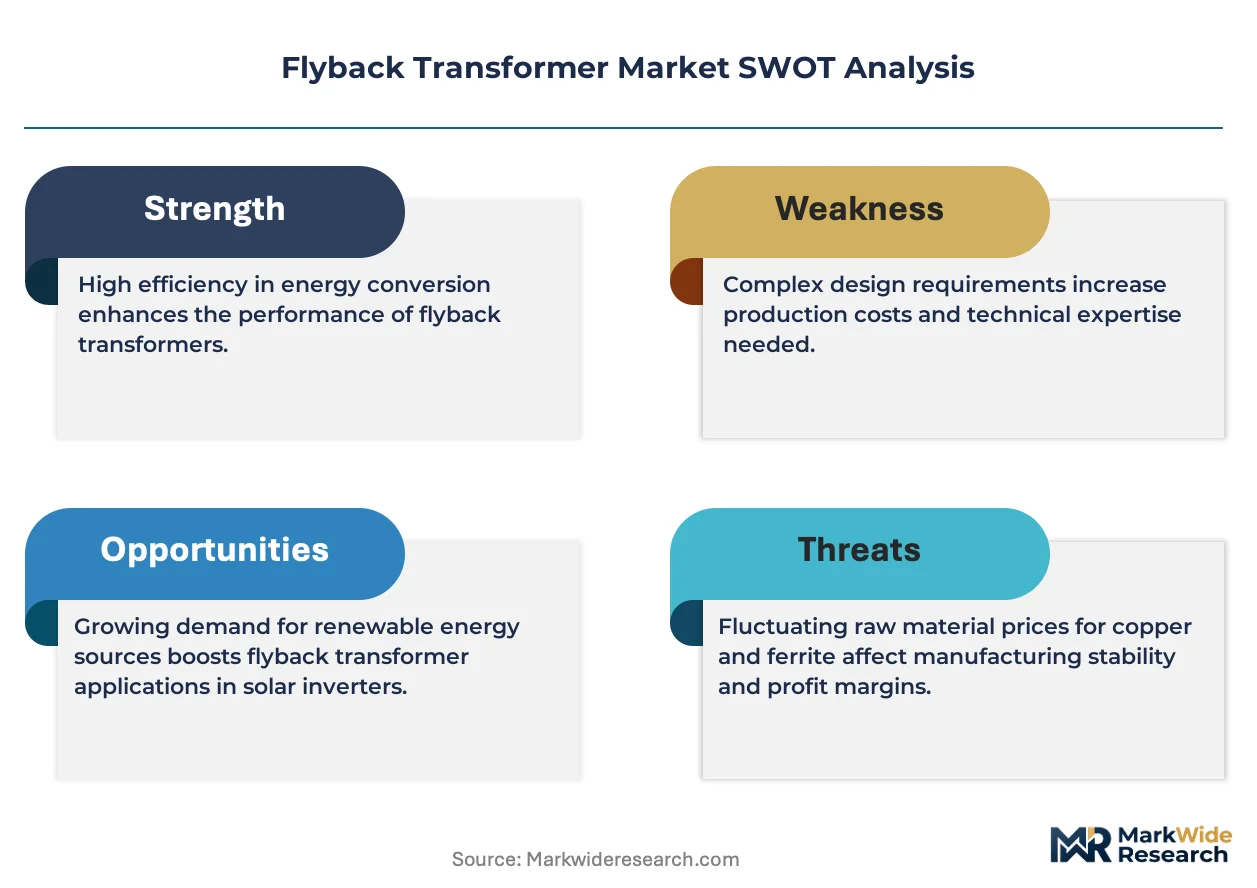
- EU Ecodesign Directive:Minimum efficiency thresholds for external power supplies are mandating core material upgrades and gapping precision improvements.
- Medical device isolation:Patient-contact equipment requiring safety agency clearance is expanding demand for reinforced insulation architectures.
Market Restraints
- Ferrite core supply concentration:Premium MnZn and NiZn ferrite production clusters in East Asian material processors, exposing buyers to logistics bottlenecks.
- REACH compliance costs:ECHA restrictions on hazardous substances in coil formers and core binders are elevating qualification expenses for European market access.
- Planar transformer substitution:Low-profile magnetics in sub-100W adapters are displacing conventional bobbin-wound flyback units in consumer electronics.
Strategic Opportunities
- Digital control convergence:Programmable switching sequences enabling adaptive loop compensation are opening premium pricing for software-defined magnetics.
- Avionics isolation demand:FAA reliability standards for airborne power systems are creating certified supplier scarcity in North American aerospace procurement.
- India medical device manufacturing:CDSCO localization incentives and PLI scheme benefits are attracting flyback transformer assembly for diagnostic equipment.
Industry Challenges
- Magnetics design talent scarcity:Experienced ferrite core gapping and leakage inductance optimization engineers are retiring faster than training pipelines refill.
- IEC 61558 certification timelines:Pending safety standard updates are delaying market access approvals and freezing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flyback Transformer Market |
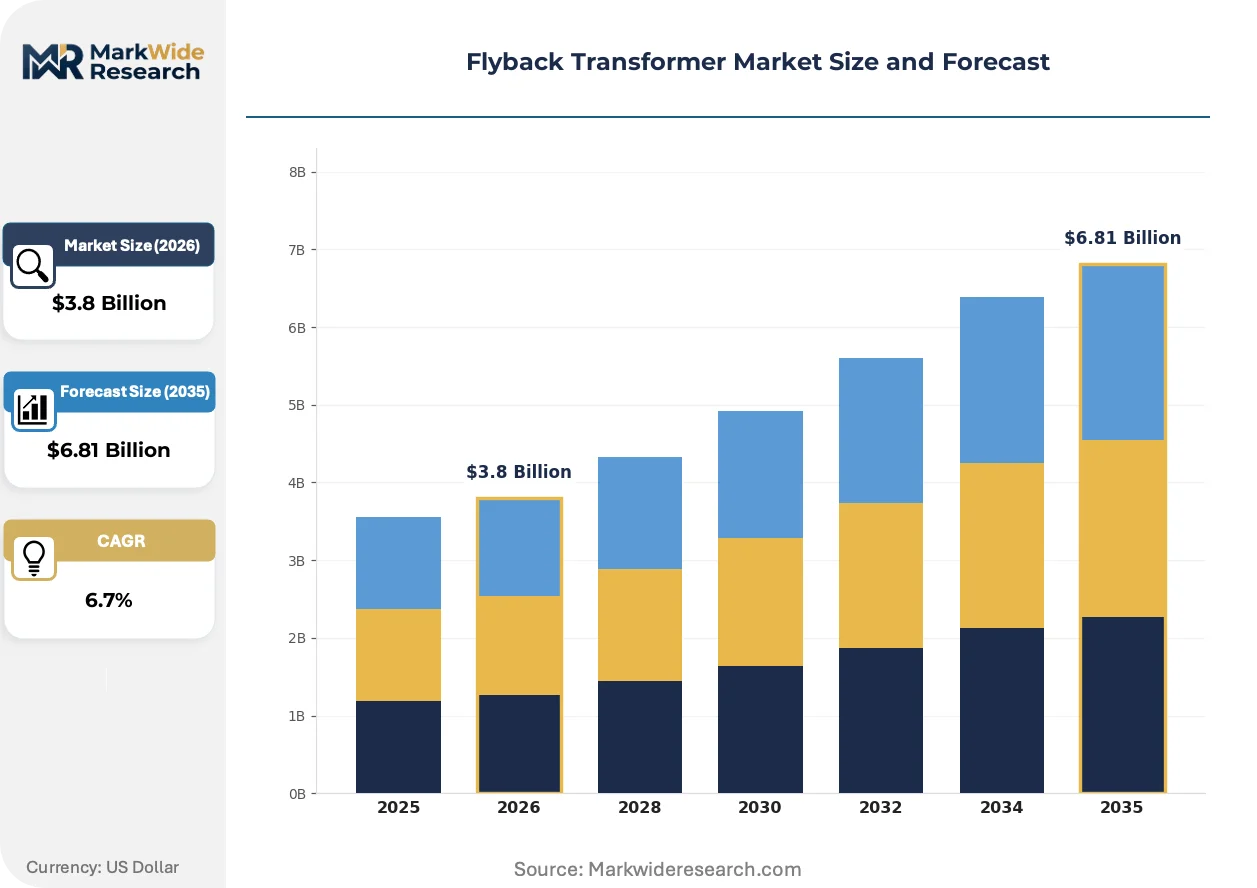
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Low Voltage, Isolated, Non-Isolated Technology: Switching Mode, Linear Mode, Digital Control, Analog Control End User: Consumer Electronics, Industrial Equipment, Medical Devices, Telecommunications Application: Power Supply Units, LED Drivers, Battery Chargers, Data Communication |
| Companies Covered | STMicroelectronics, Texas Instruments, ON Semiconductor, TDK Corporation, Wurth Elektronik, Coilcraft, Custom Coils, Allied Components International, Kormag UK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flyback Transformer Market Emerging Trajectories
Magnetics design is splitting between commodity surface-mount units and application-specific high-isolation architectures. Digital control integration and material science advances are reshaping competitive differentiation across power ratings.
Gapped ferrite core technology is bifurcating the supplier landscape. Precision-gapped cores with tight AL value tolerance serve medical and automotive isolation requirements, while standard-gap variants dominate adapter and LED driver volumes. Tier-one magnetics houses are consolidating premium ferrite verticality, compressing margin availability for second-source buyers.
REACH compliance in Europe is restricting hazardous substance content in ferrite cores and coil formers. ECHA substance-of-very-high-concern listings are forcing reformulation of core binders and winding insulation tapes. Medical device manufacturers are accelerating supplier audits to preempt authorization delays.
Buyer consolidation among tier-one power supply OEMs is compressing supplier negotiation leverage. Long-term magnetics contracts with volume commitments are displacing spot procurement for 50W-150W adapter applications. This concentration is most visible in East Asian contract manufacturing clusters serving North American consumer electronics brands.
Flyback Transformer Market Segmentation
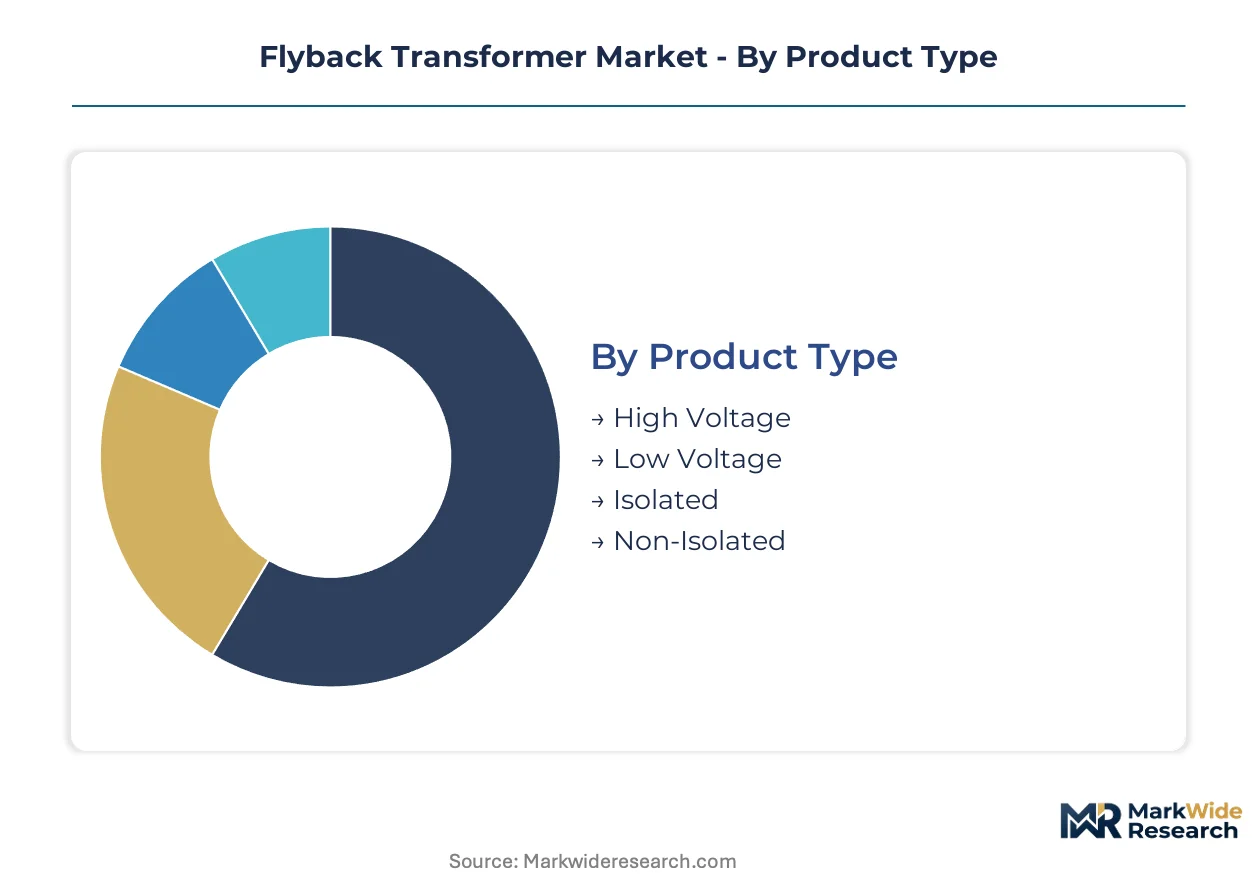
Flyback transformer procurement splits across regulatory regimes, with safety agency clearances determining accessible market tiers. Technical specifications cascade from end-use requirements, creating distinct qualification pathways for medical isolation versus consumer efficiency.
Product Type:
Regulatory differentiation separates reinforced insulation architectures from basic isolation, with IEC 61558 and FDA patient-contact standards mandating specific creepage and clearance geometries.
- High Voltage:Gapped ferrite cores with enhanced insulation systems withstand kilovolt-level transients in industrial motor drives and EV onboard chargers. Demand concentrates in Germany and the United States where factory automation and electrified vehicle assembly require certified isolation. IEC 61558-2-16 compliance adds 12-16 week qualification cycles.
- Isolated:Reinforced insulation with triple-insulated wire constructions serves patient-contact medical equipment and avionics power systems. FDA 21 CFR Part 820 and FAA DO-160G standards drive procurement in North American aerospace and diagnostic imaging clusters. Safety agency listings command 15-25% margin premiums over basic variants.
- Low Voltage:Standard bobbin-wound units for sub-100W adapter applications prioritize ferrite material efficiency over isolation ratings.
- Non-Isolated:Buck-derived architectures in cost-sensitive LED drivers and basic charging modules.
Established volume favors Low Voltage; emerging adoption favors Isolated.
Technology:
Cost tier stratification separates commodity analog controllers from programmable digital architectures, with development expense and unit economics determining competitive positioning.
- Digital Control:Adaptive loop compensation algorithms adjust switching sequences across variable load profiles in server power supplies and programmable medical devices. STMicroelectronics and Texas Instruments supply paired controller ICs that lock in transformer specifications. Expanding most quickly in 100W-500W industrial and telecom rectifier applications.
- Switching Mode:Hard-switched and quasi-resonant topologies at 50-500 kHz dominate adapter and LED driver volumes. MnZn ferrite cores from TDK-EPCOS and Ferroxcube anchor material supply. Efficiency mandates under EU Ecodesign Directive Version 6 force core loss reductions in 5-25W external power supplies.
- Analog Control:Fixed-frequency PWM controllers in mature consumer electronics designs with minimal feature differentiation.
- Linear Mode:Residual demand in noise-sensitive audio equipment and legacy instrumentation requiring minimal electromagnetic interference.
Switching Mode captures present volume leadership; Digital Control gains share fastest in premium tiers.
End User:
Application maturity determines margin structure, with long-qualified segments facing pricing pressure and emerging verticals offering certification-based differentiation.
- Medical Devices:Diagnostic imaging, patient monitors, and infusion pumps require 2xMOPP (means of patient protection) isolation per IEC 60601-1. CDSCO manufacturing incentives in India and FDA 510(k) pathways in the United States are localizing assembly for export markets. Reinforced insulation architectures with 8mm creepage minimums dominate procurement specifications.
- Consumer Electronics:Smartphone adapters, laptop chargers, and peripheral power supplies represent the highest unit volumes. EU Ecodesign Directive efficiency tiers and DOE Level VI standards in the United States define minimum performance thresholds. Planar transformer substitution threatens conventional bobbin-wound designs in sub-65W applications.
- Industrial Equipment:Motor drives, PLCs, and factory automation systems prioritize reliability over cost minimization.
- Telecommunications:Base station power supplies and network infrastructure require wide input range operation and holdup time specifications.
Consumer Electronics sustains absolute volume; Medical Devices offers the steepest expansion trajectory in value terms.
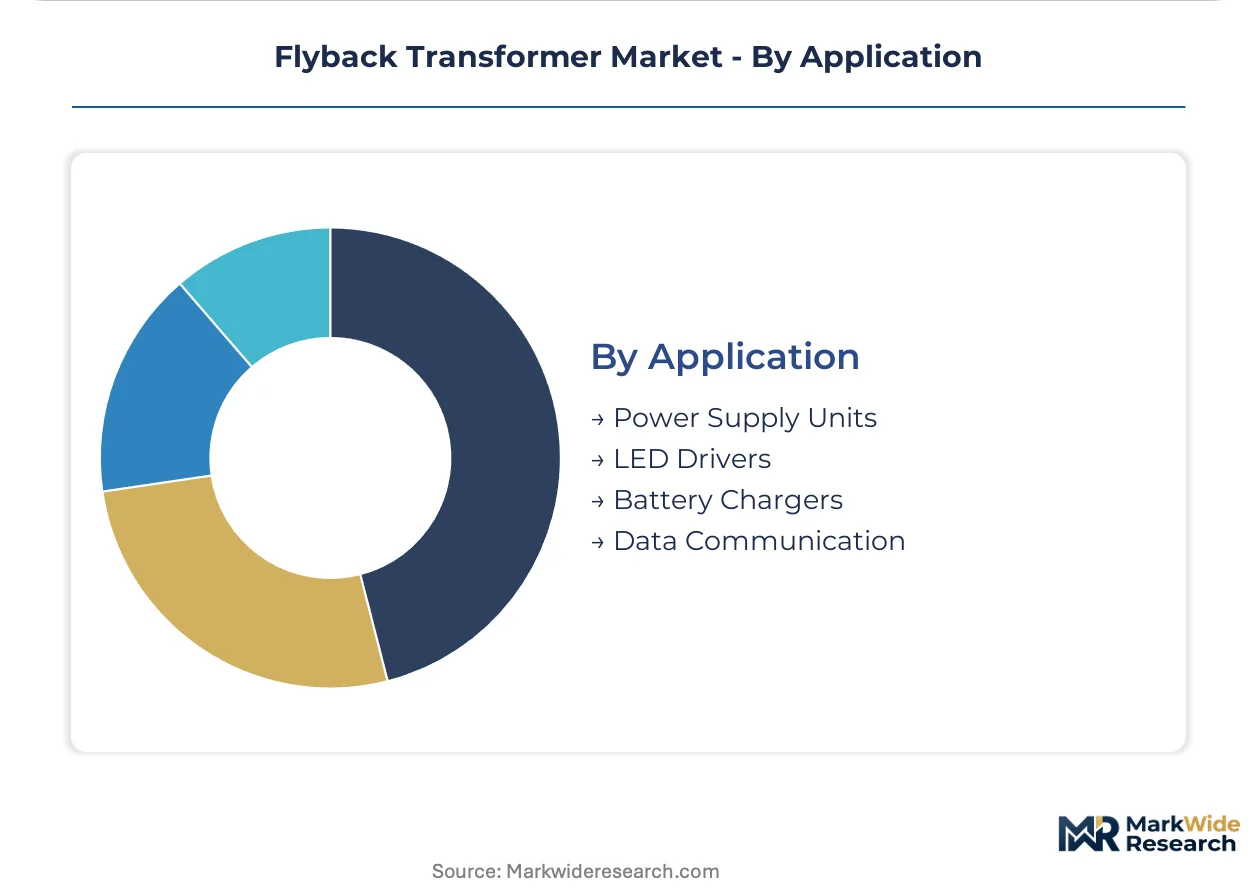
Application:
Customer type concentration shapes supply relationships, with OEM direct procurement favoring qualified sources and contract manufacturing enabling second-source competition.
- Power Supply Units:External adapters, open-frame converters, and enclosed industrial supplies span 5W to 500W ratings. Tier-one OEMs in China and Taiwan consolidate procurement through annual magnetics contracts with volume commitments. Efficiency regulations in Europe and North America cascade into ferrite core material specifications.
- LED Drivers:Constant-current architectures for commercial and residential lighting prioritize power factor correction and THD compliance. EU Ecodesign Directive Lot 19 mandates minimum efficiency and flicker requirements. Isolated and non-isolated variants split by safety class and installation environment.
- Battery Chargers:EV onboard chargers and industrial forklift systems require AEC-Q200 automotive qualification or equivalent reliability screening.
- Data Communication:PoE injectors, server power supplies, and network equipment demand high-density magnetics with minimal footprint.
Power Supply Units anchor present procurement scale; Battery Chargers show the strongest forward momentum from electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian ferrite processors export wound cores to Germany, the United States, and India, where medical device and automotive OEMs complete final assembly and qualification testing.
China
Domestic EV production and medical device exports drive procurement of high-isolation flyback units. MIIT efficiency mandates under GB standards force core material upgrades in external power supplies. Yangtze River Delta clusters around Shanghai and Suzhou concentrate precision winding operations for export markets.
Germany
Factory automation and EV powertrain assembly anchor demand for AEC-Q200 qualified transformers. REACH compliance through ECHA restricts hazardous substances in ferrite binders and coil formers. Bavaria's industrial corridor hosts tier-one magnetics qualification labs serving automotive OEMs.
United States
FDA patient-contact equipment and FAA avionics power systems require reinforced insulation architectures. DOE Level VI efficiency standards cascade into adapter transformer specifications. Texas and California medical device clusters drive procurement of 2xMOPP isolation units.
India
CDSCO localization incentives and PLI scheme benefits attract flyback transformer assembly for diagnostic imaging exports. BIS certification requirements align with IEC 61558 safety standards. Maharashtra and Karnataka host contract manufacturing operations serving European and North American medical OEMs.
Japan
Industrial robotics and precision medical equipment sustain demand for tight-tolerance magnetics. METI energy efficiency guidelines influence ferrite core specifications in consumer adapters. Kanto region manufacturers supply high-reliability units to domestic semiconductor equipment makers.
Flyback Transformer Market Vendor Landscape
Listed leaders compete with private specialists across material verticality and qualification depth. The supplier base stratifies into three tiers: integrated ferrite producers, dedicated magnetics houses, and contract winding operations. Strategic archetypes include backward-integrated material suppliers, application-specific isolation specialists, and scale-driven adapter component vendors. Dominant competitive moves involve captive ferrite sourcing and AEC-Q200 certification capacity expansion.
Among semiconductor-integrated suppliers, STMicroelectronics and Texas Instruments exemplify controller-transformer pairing strategies that lock in system-level specifications. TDK Corporation represents the backward-integrated archetype with in-house ferrite material production. Coilcraft occupies a position within the compact magnetics specialist tier, serving space-constrained medical and telecom designs. These three anchors illustrate how competitive differentiation splits between material control, IC integration, and architectural miniaturization.
| Leading Market Players |
|---|
| STMicroelectronics |
| Texas Instruments |
| ON Semiconductor |
| TDK Corporation |
| Wurth Elektronik |
| Coilcraft |
| Custom Coils |
| Allied Components International |
| Kormag UK |
| Others |
Supply Flow & Price Mechanics
Planar transformer substitution in sub-100W consumer adapters is simultaneously redrawing supplier geography toward East Asian contract manufacturers and compressing margin pools for conventional bobbin-wound producers. This displacement dynamic concentrates pricing power with buyers who can qualify alternative magnetics architectures while forcing legacy suppliers into certification-intensive medical and automotive segments.
Pricing Analysis
The technology-generation pricing gap between analog-controlled legacy units, switching-mode mainstream designs, and digitally controlled premium architectures defines current market stratification. Pricing stratifies across AEC-Q200 automotive, FDA-cleared medical, and basic consumer tiers, with certification premiums reaching 15-25% for reinforced insulation. Cost compression in consumer electronics adapters stems from planar transformer competition and buyer consolidation among tier-one OEMs. Contract manufacturers serving smartphone and laptop brands exhibit extreme price sensitivity, while medical device OEMs prioritize isolation reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs for MnZn and NiZn ferrite cores shipped from East Asian processors to European and North American winding facilities have tightened delivery windows and elevated working capital requirements. Premium ferrite production clusters in China, Japan, and South Korea, with precision gapping operations concentrated in the Yangtze River Delta and Kanto region. Raw material dependencies include rare-earth-doped ferrite powders, triple-insulated copper wire, and high-temperature coil formers. Single-source vulnerability around automotive-qualified core suppliers exposes buyers to allocation risk during demand surges. Distribution runs through annual magnetics contracts with volume commitments rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flyback transformer procurement is recovering from a cyclical trough as EV production ramps and medical device reshoring accelerates capital deployment into magnetics capacity. The recovery trajectory hinges on AEC-Q200 certification backlogs clearing and IEC 61558 standard updates finalizing.
For Market Incumbents: Fortify captive ferrite sourcing through backward integration into core material production or long-term offtake agreements with East Asian processors. Expand AEC-Q200 testing capacity in Germany and the United States to capture automotive qualification premiums before second-source competitors mature. Digital control pairing strategies with STMicroelectronics and Texas Instruments lock in specification control at the system level.
For New Entrants and Emerging Players: CDSCO fast-track certification for medical device exports offers the most penetrable entry point, with Maharashtra and Karnataka contract manufacturers seeking qualified second sources for European and North American diagnostic OEMs. Target India's PLI scheme benefits to offset initial qualification costs. A go-to-market angle focused on adaptive loop compensation algorithms for programmable medical power supplies differentiates against commodity analog competitors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed magnetics specialists that consolidated during the last downturn and now face refinancing pressure against a recovering demand backdrop. Five-to-ten-year viability favors suppliers with demonstrated FDA and FAA certification track records over pure-play adapter component vendors. The inflection signal to watch is IEC 61558-2-16 compliance timeline clarity, which would unlock frozen product development cycles and normalize market access approvals.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Certification Expansion | Automotive-grade isolation capacity captures EV onboard charger procurement from Germany and US-based OEMs. |
| Backward Ferrite Integration | In-house MnZn core production insulates margins from East Asian logistics bottlenecks and allocation risk. |
| Digital Control IC Pairing | Software-defined magnetics specifications lock in transformer designs with STMicroelectronics and Texas Instruments platforms. |
| India Manufacturing Localization | CDSCO and PLI incentives attract assembly operations for diagnostic imaging exports to European markets. |
| REACH Compliance Reformulation | ECHA-aligned core binder and insulation tape substitutions preserve European market access against authorization delays. |
Methodological Framework
A standing panel of magnetics design engineers, automotive Tier 1 procurement managers, medical device quality directors, and contract manufacturing operations heads provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with ferrite material suppliers and power supply OEMs, validated against secondary sources including SEC filings from TDK Corporation and STMicroelectronics, ECHA REACH authorization databases, FDA 510(k) clearance records, and MIIT GB standard efficiency disclosures. Bottom-up unit demand modeling and top-down macroeconomic triangulation anchored value estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled demand by product type, technology generation, end-user vertical, and application, with additional segmentation by regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating AEC-Q200 adoption rates, EU Ecodesign Directive efficiency tier transitions, and medical device isolation requirement escalations. Industry-specific inputs included ferrite core loss coefficients, winding labor productivity indices, and safety agency clearance timelines.
Decision-makers should treat outputs as directional under assumptions of stable automotive electrification policy support and no major disruption to East Asian ferrite processing capacity; material deviation would warrant model refresh. Specific risks that could revise forecasts include IEC 61558 standard update delays, REACH substance authorization disruptions, and planar transformer technology breakthroughs in higher power ratings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Inverter Market
Power Systems
Micro-Inverter Market
Power Systems
Europe Shunt Reactors Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Smart Power Strips Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Global Frequency Converter Market
Power Systems
Telecom Power Systems Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
AC DC Power Adapter Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Global Excitation Systems Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Power Supply and Charger Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Asia Pacific Battery Management System Market