
 Automotive Pedestrian Protection System Market | 2026-2036
Automotive Pedestrian Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pedestrian Protection System Market Analysis
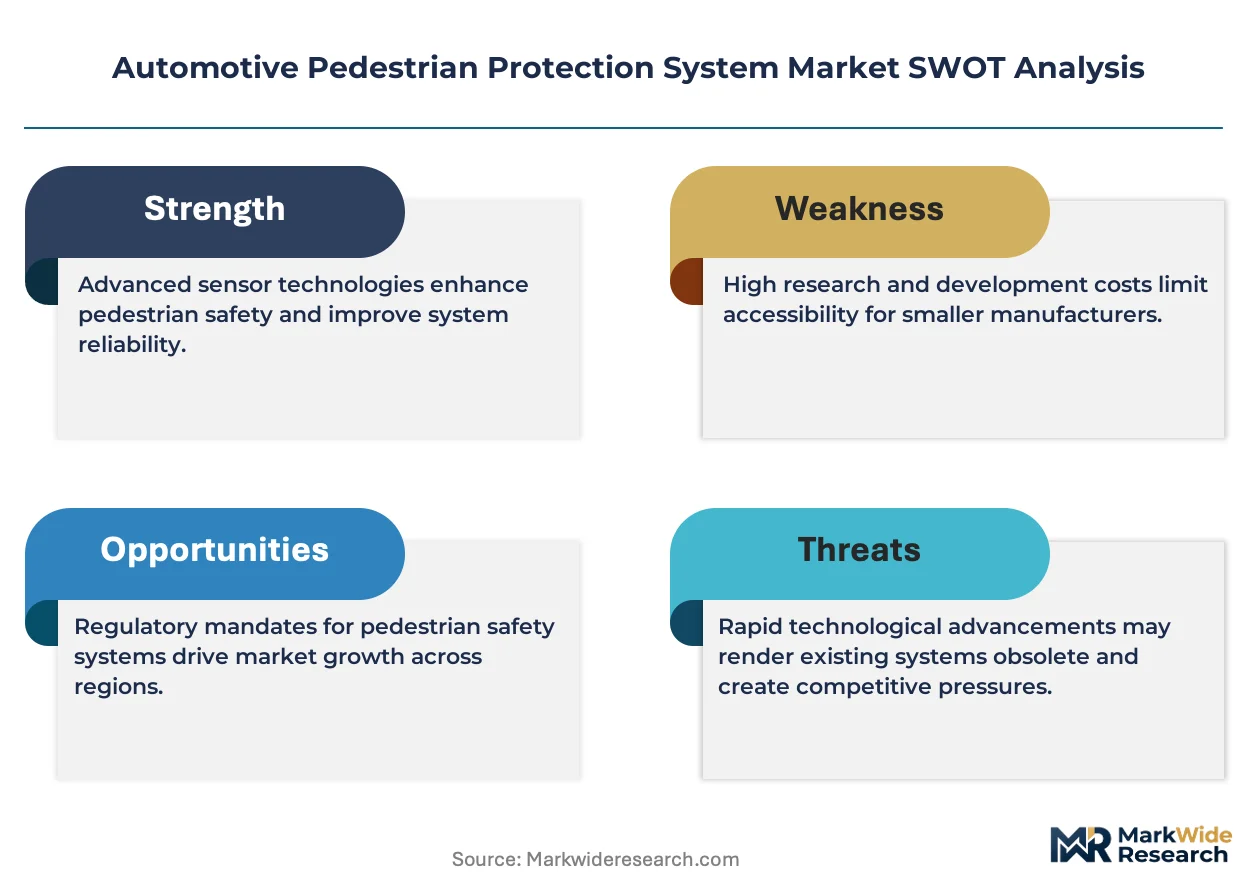
The gap between premium sensor-fusion platforms and cost-constrained ultrasonic-only configurations is recalibrating procurement criteria across OEM tiers. Robert Bosch GmbH leverages its integrated radar-camera stack to anchor high-volume contracts with European and Asian manufacturers. Continental AG competes through specialized Lidar processing modules that differentiate its offerings in the luxury vehicle segment.
Automotive pedestrian protection systems encompass active collision avoidance technologies, passive energy-absorbing structures, and hybrid architectures that combine predictive sensing with deployable countermeasures, typically operating through radar frequencies near 77 GHz or camera-based neural networks trained on pedestrian kinematic models. Their primary purpose is to reduce injury severity or prevent impact entirely by detecting vulnerable road users and triggering automated braking or hood-lifting mechanisms. Active safety systems dominate current revenue pools due to escalating OEM integration mandates, while hybrid systems represent the fastest-growing category as manufacturers combine predictive braking with passive hood actuation to satisfy evolving test protocols. Sensor technologies concentrate margin capture among semiconductor and optics specialists who control the upstream component layer.
NHTSA in the United States and Euro NCAP in Europe enforce divergent test protocols that shape sensor placement, algorithm training datasets, and activation thresholds for vehicles sold in each jurisdiction. China's MIIT issues GB standards that mandate pedestrian detection capabilities on new energy vehicles, creating a distinct regulatory corridor that domestic and foreign suppliers must navigate separately. Stakeholders must monitor how regional testing divergence affects platform standardization strategies and whether sensor fusion complexity will consolidate procurement toward full-stack integrators or fragment across specialized tier-one suppliers.
Market Dynamics
The collision between Euro NCAP's 2026 testing protocols and China's MIIT mandates for new energy vehicles is forcing OEMs to redesign sensor architectures around unified active-passive platforms rather than discrete safety modules.
Growth Catalysts
- Euro NCAP protocol escalation:The testing body's expanded vulnerable road user scenarios now require predictive braking plus deployable hood actuation, compelling European OEMs to source integrated hybrid systems.
- 77 GHz radar proliferation:Semiconductor foundries in Taiwan and Germany have scaled millimeter-wave production, collapsing unit costs for mid-volume vehicle platforms previously limited to ultrasonic alternatives.
- China NEV mandate pipeline:MIIT's GB standards for pedestrian detection on electric vehicles create guaranteed procurement volumes through 2030 for compliant sensor-fusion suppliers.
Market Restraints
- Lidar module cost volatility:Specialized gallium arsenide substrates and MEMS mirror assemblies from single-source Japanese suppliers create input price instability for luxury-tier hybrid systems.
- Algorithm training dataset bias:Neural networks trained predominantly on European pedestrian kinematics generate false-negative rates above acceptable thresholds in South Asian and African urban environments.
- Regulatory fragmentation:NHTSA's pending rulemaking on automatic emergency braking uses divergent activation thresholds from Euro NCAP, forcing dual-certification engineering for export platforms.
Strategic Opportunities
- India two-wheeler integration:The country's unpenetrated scooter and motorcycle segment offers first-mover positioning for compact camera-radar stacks as BIS considers mandating vulnerable road user detection.
- Retrofit aftermarket channel:Fleet operators in Brazil and Mexico are sourcing aftermarket pedestrian detection kits ahead of ANVISA's anticipated commercial vehicle safety regulations.
- Edge-AI sensor convergence:On-chip neural processing units from semiconductor vendors are enabling camera modules with embedded inference, collapsing the need for discrete ECUs in cost-sensitive platforms.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among German and Japanese tier-one suppliers, constraining second-tier vendors from qualifying for OEM direct contracts.
- Sensor fusion validation timelines:The 18-24 month homologation cycle for multi-modal systems delays platform launches and locks engineering resources on single vehicle programs.
- Legacy CAN bus integration friction:New pedestrian protection architectures require gateway redesigns to communicate with 10-year-old vehicle networks still prevalent in commercial truck segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pedestrian Protection System Market |
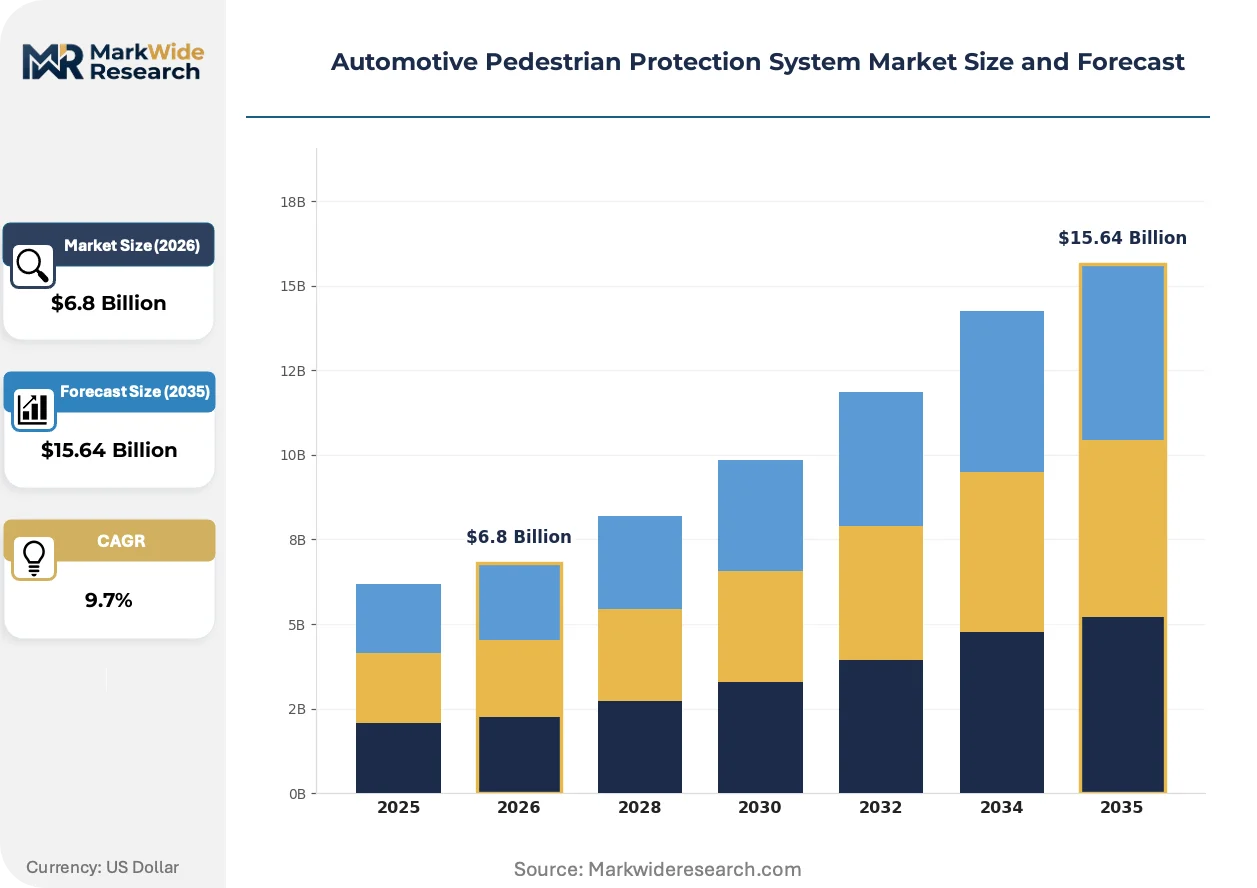
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Safety Systems, Passive Safety Systems, Hybrid Systems, Sensor Technologies Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Technology: Radar Technology, Camera-Based Systems, Lidar Technology, Ultrasonic Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Autoliv Inc, Denso Corporation, ZF Friedrichshafen AG, Aptiv PLC, Valeo, Magneti Marelli SpA, Mobileye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pedestrian Protection System Market Emerging Trajectories
Engineering resources are migrating from discrete component optimization toward system-level integration, compressing development cycles and collapsing traditional tier boundaries between sensor suppliers and braking system manufacturers.
Camera-radar sensor fusion is modularizing around standardized physical interfaces and common software stacks, enabling Chinese EV manufacturers to mix-and-match subsystems from competing semiconductor vendors without full-stack revalidation. This architecture fragmentation accelerates platform refresh rates from 48 months to 24 months. Tier-one suppliers with captive radar production are modularizing their offerings into plug-compatible units that preserve OEM algorithm investments across hardware generations.
REACH restrictions on perfluorinated compounds are eliminating certain hydrophobic lens coatings previously standard in automotive cameras, forcing German and Korean optics suppliers to qualify fluorine-free alternatives with equivalent degradation resistance. The regulatory compression affects primarily luxury vehicle programs with extended warranty obligations. Tier-two coating specialists are responding by accelerating plasma-enhanced deposition processes that achieve comparable performance without restricted chemistries.
Fleet procurement contracts now specify pedestrian protection performance metrics tied to insurance premium reductions, displacing traditional component-specification purchasing in European commercial vehicle segments. Leasing companies and logistics operators in Germany and the Netherlands are consolidating buying power to demand system-level warranties rather than individual sensor coverage. This behavioral shift concentrates contract awards toward full-stack integrators capable of underwriting integrated performance guarantees.
Automotive Pedestrian Protection System Market Segmentation
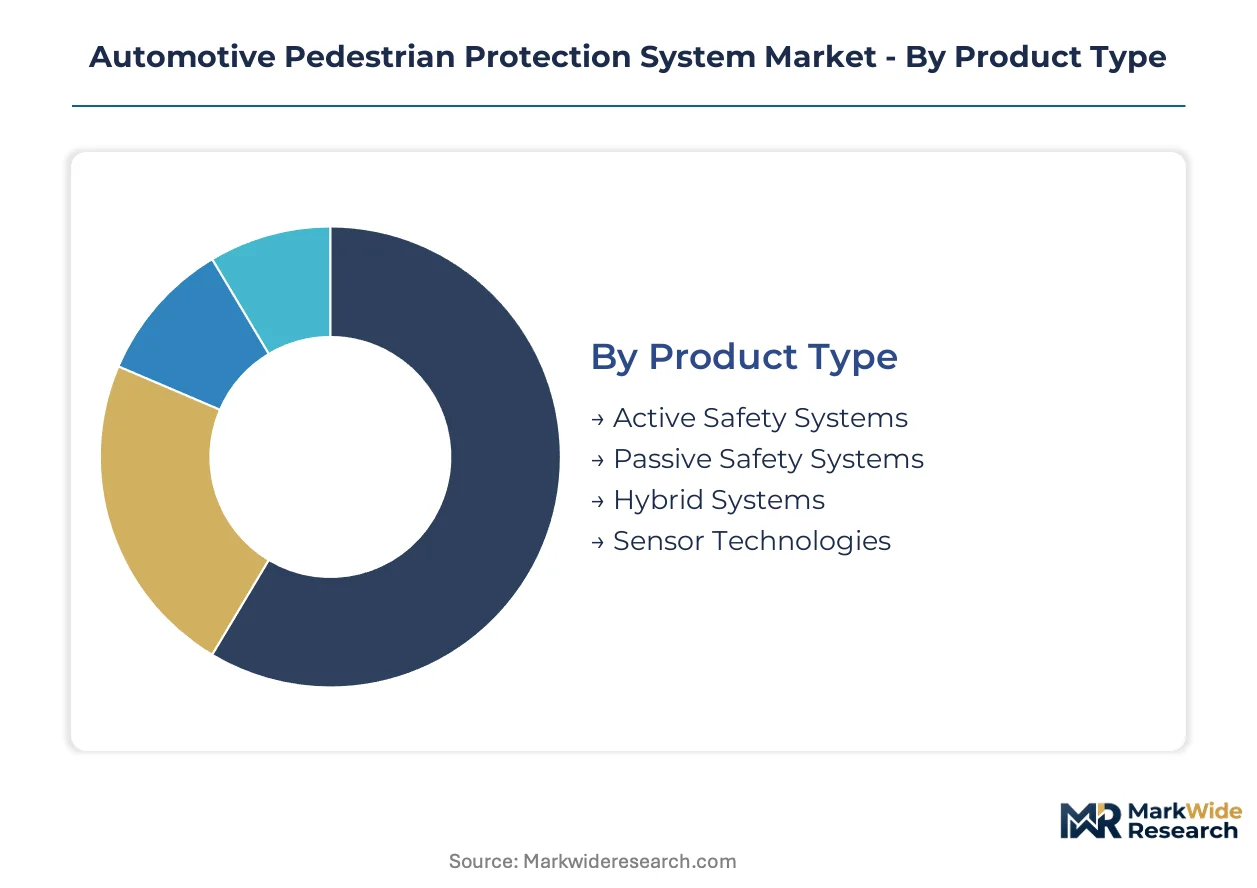
Segmentation in pedestrian protection systems reveals how certification burdens and integration complexity fragment procurement patterns across OEM tiers. Each dimension—product architecture, vehicle application, sensing modality, and supply chain position—carries distinct regulatory checkpoints that reshape competitive positioning.
Product Type:
ISO 26262 ASIL-D certification applies unevenly across product categories, with active and hybrid systems facing the most stringent functional safety validation while sensor technologies navigate component-level EMC directives.
- Active Safety Systems:Radar-camera fusion stacks with automated emergency braking algorithms dominate procurement volumes from German and Japanese OEMs. Euro NCAP's expanded vulnerable road user scenarios now mandate predictive braking plus hood actuation, forcing redesigns of legacy braking architectures.
- Hybrid Systems:Combined predictive sensing with deployable countermeasures—hood lifters, exterior airbags—requires dual-certification across active safety and passive crashworthiness protocols. China's MIIT mandates for new energy vehicles accelerate adoption as domestic EV platforms integrate these architectures from launch.
- Passive Safety Systems:Energy-absorbing hood structures and bumper systems rely on ECE R127 pedestrian safety certification with simpler homologation cycles than active alternatives.
- Sensor Technologies:Discrete radar, camera, and lidar modules face REACH compliance for lens coatings and RoHS restrictions on semiconductor substrates.
Active Safety Systems sits at the top of the volume ranking, with Hybrid Systems climbing the fastest.
Application:
Vehicle category determines sensor packaging constraints and activation thresholds, with electric vehicles commanding distinct thermal management and power budgets that reshape component selection.
- Passenger Vehicles:Premium sedans and SUVs integrate 77 GHz radar with stereo camera arrays for 360-degree vulnerable road user coverage. Procurement concentrates among European and Chinese OEMs redesigning platforms around unified active-passive architectures.
- Electric Vehicles:Battery-electric platforms from Chinese manufacturers mandate pedestrian detection as standard equipment under MIIT GB standards, creating guaranteed volumes through 2030. Sensor fusion modules must accommodate high-voltage isolation requirements and thermal loads from battery thermal management systems.
- Commercial Vehicles:Fleet operators in Germany and the Netherlands specify system-level performance warranties tied to insurance premium reductions, shifting purchasing from component-specification to outcome-based contracts.
- Two-Wheelers:Unpenetrated scooter and motorcycle segments in India present first-mover positioning for compact camera-radar stacks as BIS considers vulnerable road user detection mandates.
Passenger Vehicles captures the largest revenue pool, while Electric Vehicles gains share fastest on regulatory compulsion.
Technology:
Millimeter-wave and optical sensing modalities diverge in semiconductor supply chains and algorithm training requirements, with cost trajectories and performance trade-offs fragmenting platform strategies.
- Camera-Based Systems:Neural networks trained on pedestrian kinematic models process stereo or monocular inputs for object classification and trajectory prediction. Dataset bias toward European pedestrian profiles generates elevated false-negative rates in South Asian and African urban environments, constraining deployment.
- Radar Technology:77 GHz front-facing and corner radar modules from Taiwanese and German foundries collapsed unit costs for mid-volume platforms previously limited to ultrasonic alternatives. ASIL-B certification suffices for most radar-only configurations, shortening validation timelines.
- Lidar Technology:Specialized gallium arsenide substrates and MEMS mirror assemblies from Japanese suppliers create input price volatility for luxury-tier hybrid systems requiring high-resolution point clouds.
- Ultrasonic Sensors:Parking-assist heritage limits range and angular resolution, relegating this technology to low-speed maneuvering aids in cost-constrained vehicle programs.
Camera-Based Systems leads technology deployment, with Radar Technology expanding most quickly on cost reduction.
End User:
Supply chain position determines algorithm ownership, warranty exposure, and direct regulatory liability, with full-stack integrators capturing margin from tier-one suppliers facing disintermediation pressures.
- OEMs:Volkswagen, Toyota, and BYD increasingly specify system-level performance rather than component specifications, concentrating procurement toward suppliers capable of underwriting integrated guarantees. Direct sourcing of sensor-fusion stacks bypasses traditional tier-one braking system manufacturers.
- Tier-1 Suppliers:Bosch and Continental compete through modular radar-camera stacks and specialized lidar processing modules, respectively. Functional safety engineer scarcity concentrates ASIL-D certification expertise among German and Japanese vendors, constraining second-tier qualification.
- Aftermarket Providers:Fleet operators in Brazil and Mexico source retrofit pedestrian detection kits ahead of ANVISA's anticipated commercial vehicle safety regulations.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations receive pre-validated safety system modules from platform licensors, minimizing local engineering investment.
OEMs dominates procurement authority, with Aftermarket Providers ascending fastest on regulatory anticipation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineers cluster in Stuttgart, Munich, and Nagoya, anchoring the design centers where ASIL-D certification expertise concentrates. These talent pools shape where tier-one suppliers validate pedestrian protection architectures.
Germany
Volkswagen and BMW procurement teams mandate integrated active-passive systems under KBA homologation requirements. Euro NCAP protocol escalation forces redesigns of legacy braking architectures. Stuttgart-based engineering centers validate radar-camera fusion stacks for export platforms.
China
BYD and NIO production lines integrate pedestrian detection as standard equipment. MIIT GB standards for new energy vehicles create guaranteed procurement volumes through 2030. Yangtze River Delta manufacturing clusters host sensor-fusion module assembly for domestic EV platforms.
Japan
Toyota and Honda accelerate procurement of hybrid safety suites ahead of revised METI vehicle safety guidelines. JIS standards govern electromagnetic compatibility for 77 GHz radar modules. Nagoya-area tier-one suppliers concentrate ASIL-D certification expertise for OEM direct contracts.
United States
Fleet operators in Michigan and California specify system-level performance warranties. NHTSA pending rulemaking on automatic emergency braking uses divergent activation thresholds from Euro NCAP. Detroit-based engineering centers manage dual-certification programs for export platforms.
India
Scooter and motorcycle manufacturers in Pune and Chennai pilot compact camera-radar stacks. BIS considers vulnerable road user detection mandates for two-wheelers. Tamil Nadu automotive corridors attract first-mover suppliers positioning ahead of regulatory finalization.
Automotive Pedestrian Protection System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the sensor-fusion value chain. The market structure concentrates among German and Japanese tier-one suppliers who control ASIL-D certification pipelines, while Chinese and Korean vendors fragment the mid-tier camera module segment. Three archetypes dominate: full-stack integrators underwriting system-level warranties, specialized radar or lidar component suppliers, and semiconductor foundries capturing margin from millimeter-wave chip production. Competitive moves center on modular platform standardization and backward integration into captive radar production.
Among German-based full-stack integrators, Robert Bosch GmbH and Continental AG exemplify the tier-one archetype that anchors high-volume contracts with European and Asian OEMs. Denso Corporation represents the Japanese specialist position within this competitive set.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Autoliv Inc |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Valeo |
| Magneti Marelli SpA |
| Mobileye |
| Others |
Supply Flow & Price Mechanics
OEM procurement teams in Germany and China are mandating unified active-passive architectures under Euro NCAP and MIIT protocols, forcing sensor suppliers to absorb ASIL-D certification costs and collapsing margin structures for tier-two vendors unable to qualify for direct contracts.
Pricing Analysis
The bundled-versus-unbundled service split separates full-stack integrators from component-only suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks ASIL certification grade and algorithm ownership. Cost compression in mid-tier camera-radar stacks is intensifying because Taiwanese foundries collapsed 77 GHz unit costs. Fleet operators in commercial vehicle segments show lowest price sensitivity due to insurance-linked performance warranties, while Indian two-wheeler OEMs remain most cost-constrained.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates concentrate procurement authority among German and Japanese tier-one suppliers with captive functional safety engineering teams. Taiwan, Germany, and Japan anchor millimeter-wave semiconductor production. Gallium arsenide substrates and MEMS mirror assemblies draw from single-source Japanese suppliers. Single-source vulnerability in specialized lidar components creates input price instability. Distribution runs through OEM direct contracts and pre-validated module supply to vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement shifts from component specifications toward system-level performance warranties underwritten by full-stack integrators.
For Market Incumbents: Anchor ASIL-D certification pipelines in Stuttgart and Nagoya engineering centers to defend against modular platform disintermediation. Deepen backward integration into captive 77 GHz radar production to preserve margin capture as semiconductor foundries expand capacity. Lock long-term contracts with Chinese EV manufacturers before MIIT mandate volumes peak. For New Entrants and Emerging Players: Capture first-mover positioning in India's unpenetrated two-wheeler segment ahead of anticipated BIS vulnerable road user detection mandates. Target aftermarket retrofit channels in Brazil and Mexico where fleet operators pre-position ahead of ANVISA commercial vehicle regulations. Lead with edge-AI camera modules embedding neural processing units to collapse discrete ECU requirements for cost-sensitive platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two coating specialists accelerating fluorine-free plasma-enhanced deposition processes under REACH hydrophobic lens restrictions. The five-to-ten year viability window favors acquisition targets with ISO 26262 ASIL-D certification infrastructure and Chinese EV platform validation. Monitor divergence between NHTSA and Euro NCAP activation thresholds as the signal for dual-certification engineering demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Camera-radar fusion modularization enables Chinese EV manufacturers to mix-and-match subsystems without full-stack revalidation. |
| Backward Integration into Radar | Tier-one suppliers with captive 77 GHz production preserve OEM algorithm investments across hardware generations. |
| Edge-AI Sensor Convergence | On-chip neural processing units from semiconductor vendors collapse discrete ECU requirements in cost-sensitive vehicle programs. |
| Geographic Manufacturing Footprint | Yangtze River Delta clusters host sensor-fusion module assembly for domestic Chinese EV platforms under MIIT mandates. |
| Software-Defined Vehicle Investment | Gateway redesigns for legacy CAN bus integration unlock commercial truck segments with decade-old vehicle networks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered OEM platform engineers at Volkswagen, Toyota, and BYD; tier-one supplier procurement leads at Robert Bosch GmbH and Continental AG; aftermarket distributors in Brazil and Mexico; and functional safety certification specialists in Stuttgart and Nagoya. Secondary validation drew from vehicle production databases, IHS Markit registration data, Euro NCAP test protocol disclosures, MIIT GB standard filings, and SEC 10-K filings from listed automotive suppliers. Bottom-up segment sizing triangulated against top-down OEM procurement budget analysis.
Segment-weighting across product architecture, vehicle application, sensing modality, and supply chain position anchored the analytical framework across the analysis window. Vehicle class, propulsion architecture, and content per vehicle shaped volume and value allocation. CAGRs derived from regression against historical adoption curves for comparable active safety technologies. Industry-specific inputs included Euro NCAP protocol escalation timelines, MIIT mandate implementation schedules, and semiconductor foundry capacity expansion announcements.
Regulatory divergence between NHTSA and Euro NCAP, foundry capacity constraints in Taiwan and Germany, and algorithm training dataset bias are the dominant revision risks. Forecasts reflect documented assumptions on mandate implementation timing and sensor fusion adoption curves. A model refresh is warranted upon material change in NHTSA automatic emergency braking rulemaking finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market