
 Parking Space Management Market | 2026-2036
Parking Space Management Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Space Management Market Insights
Hardware-software distribution is fragmenting as legacy equipment vendors cede ground to cloud-native platforms and mobile-first integrators. Siemens AG anchors European infrastructure deployments through its traffic management heritage and embedded municipal relationships. Kapsch TrafficCom AG competes aggressively in tolling-adjacent parking systems, leveraging transponder interoperability across transport modes. SKIDATA specializes in access-control hardware that sustains premium positioning in stadium and airport verticals where throughput reliability commands pricing power.
Parking space management encompasses sensor networks, dynamic pricing engines, and occupancy analytics that optimize finite curb and garage inventory. Systems typically integrate magnetic or camera-based detection with cloud-hosted reservation APIs to achieve sub-minute vacancy updates across distributed assets. IoT Solutions and Cloud Platforms currently lead technology segmentation because municipalities demand real-time data feeds for congestion pricing and enforcement dispatch. Mobile Applications represent the fastest-expanding application layer as consumer expectations shift toward frictionless entry-exit via smartphone credentials rather than physical tickets.
Regulatory pressure from the EU Green Deal and F-Gas Regulation is accelerating retrofit mandates for energy-efficient parking infrastructure across European member states. The US DOT and FAA indirectly shape demand through airport capital improvement grants that now require smart parking components in terminal expansion plans. Stakeholders must monitor how municipal procurement codes evolve to favor outcome-based service contracts over capital-heavy equipment purchases.
Market Dynamics
Cloud-native platforms are displacing legacy on-premise parking management systems as municipalities demand API-first architectures that integrate congestion pricing, enforcement dispatch, and mobile payment rails through unified data layers.
Growth Catalysts
- EU Green Deal retrofit mandates:European member states now require energy-efficient sensor networks in municipal garages, forcing wholesale replacement of magnetic loop detectors with low-power IoT alternatives.
- Airport capital improvement grants:US DOT and FAA funding conditions now embed smart parking components in terminal expansion plans, accelerating procurement across 45 major hub airports.
- Magnetic-to-camera detection transition:Computer vision systems with edge processing are capturing share from inductive loops due to sub-meter accuracy and reduced roadway excavation costs.
Market Restraints
- Semiconductor supply concentration:LiDAR and mmWave sensor modules depend on Taiwanese foundry capacity, exposing deployment timelines to 18-24 month lead time volatility.
- F-Gas Regulation compliance friction:EU restrictions on synthetic refrigerants in enclosed parking structures add €40,000-€80,000 per facility to HVAC upgrade costs.
- Legacy protocol fragmentation:Proprietary data formats from 1990s-era parking equipment block seamless cloud integration, forcing expensive middleware development.
Strategic Opportunities
- Curbside monetization in Dubai and Singapore:Land scarcity in these city-states is forcing dynamic pricing pilots that adjust rates every 15 minutes based on real-time occupancy.
- EV charging-parking convergence:Integration of reservation APIs with charge point operators creates bundled service models at multi-tenant commercial properties.
- Japan METI smart city subsidies:Municipalities in Osaka and Fukuoka receive 50% cost offsets for sensor deployments that feed centralized urban mobility dashboards.
Industry Challenges
- Embedded systems firmware talent scarcity:Parking technology vendors compete with automotive and robotics sectors for engineers skilled in real-time operating systems.
- Multi-vendor integration complexity:Municipal procurement often fragments sensor hardware, cloud platform, and mobile application across separate vendors, creating API compatibility failures.
- UL 294 and EN 50133 certification timelines:Access control components require 8-14 month approval cycles that delay stadium and airport deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Space Management Market |
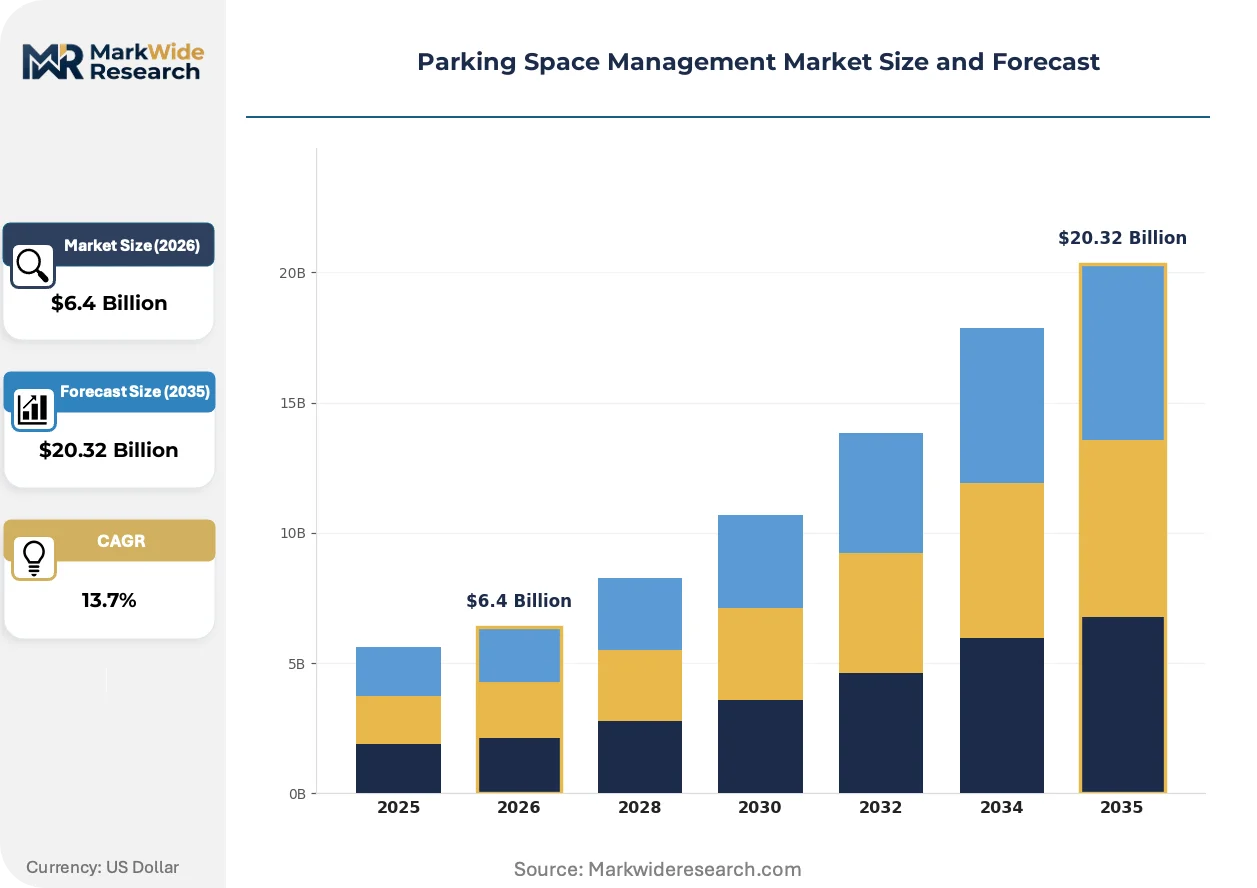
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $20.32 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Mobile Applications, Cloud Platforms, Reservation Systems Application: Commercial Areas, Residential Buildings, Event Venues, Airports End User: Malls, Corporations, Residential Complexes, Municipalities Service Type: Monitoring Services, Enforcement Solutions, Payment Processing, Analytics Tools |
| Companies Covered | Amano Corporation, INDIGO Group, ABM Industries Incorporated, Siemens AG, LAZ Parking, SP Plus Corporation, Kapsch TrafficCom AG, SKIDATA, Cubic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Space Management Market Trends and Innovations
Edge computing architectures are compressing data latency in parking networks, while regulatory pressure on embodied carbon is reshaping hardware specifications. Buyers now prioritize interoperability over single-vendor stacks.
Camera-based occupancy detection is migrating from centralized server processing to on-device inference using NVIDIA Jetson and Qualcomm Vision Intelligence platforms. Large commercial garage operators in London and New York are piloting these systems to eliminate bandwidth costs and achieve 200-millisecond vacancy updates. This distributed architecture is compressing infrastructure spend by 30-40% compared to fiber-backhauled alternatives.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in enclosed parking structures by 2030, forcing HVAC system redesigns across German and French municipal assets. Equipment vendors must now certify heat pump and ventilation units using CO2 or propane alternatives. Underground garage projects in Stuttgart and Lyon are already specifying compliant systems to avoid mid-life retrofit penalties.
Frictionless entry via smartphone credentials is displacing physical ticket dispensers at commercial properties. Property managers in Singapore and Dubai now demand license plate recognition integrated with mobile wallet payments, eliminating gate hardware entirely. This behavioral shift is most visible in premium retail and medical office verticals where queue reduction directly correlates with tenant renewal rates.
Parking Space Management Market Segmentation
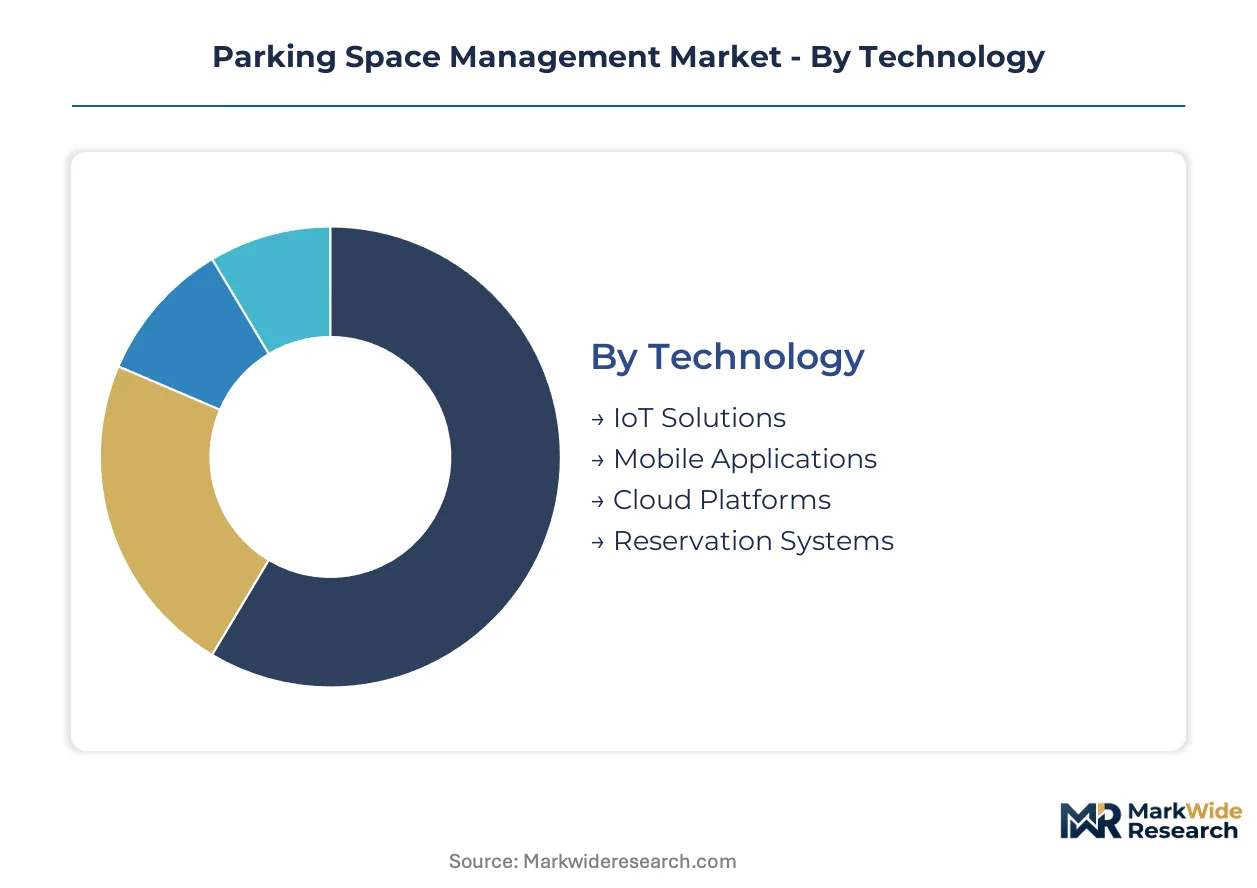
Parking space management systems fragment across four distinct dimensions that determine procurement patterns and technology deployment cycles. Understanding these segment boundaries clarifies why sensor hardware vendors, software platforms, and service operators rarely compete directly despite serving overlapping customer bases.
Technology:
Replacement cycles vary dramatically across technology layers, with infrastructure hardware turning over every 7-10 years while application software refreshes every 18-24 months.
- IoT Solutions:Sensor networks combining magnetic, ultrasonic, and camera-based detection feed real-time occupancy data to municipal traffic centers. German cities under EU Green Deal mandates are accelerating magnetic loop replacements with low-power wide-area alternatives. Stuttgart and Munich procurement codes now specify sub-watt standby consumption thresholds.
- Cloud Platforms:Centralized data aggregation layers normalize inputs from heterogeneous sensor fleets and expose APIs for pricing engines and enforcement dispatch. Dubai's Roads and Transport Authority runs the largest single-tenant deployment, processing 340,000 space updates hourly across commercial corridors.
- Mobile Applications:Consumer-facing reservation and payment interfaces with license plate recognition integration. Singapore mall operators report 60% transaction volume migrating from physical tickets to smartphone credentials within 18 months of deployment.
- Reservation Systems:Advance booking platforms with dynamic pricing algorithms that adjust rates based on predicted demand. London Heathrow and Frankfurt Airport terminals use these for premium proximity spaces.
IoT Solutions anchors the volume base while Mobile Applications gains share at the steepest rate.
Application:
Site-specific constraints create divergent technical specifications, with enclosed structures demanding ventilation integration and open-air deployments prioritizing weatherproofing.
- Commercial Areas:Mixed-use districts with high turnover requiring frictionless payment integration and curbside enforcement coordination. Dubai's Downtown and Business Bay districts operate 15-minute dynamic pricing pilots that adjust rates based on real-time sensor feeds.
- Airports:Terminal-adjacent facilities with 24/7 operations, security screening requirements, and multimodal transit connections. US DOT capital improvement grants now mandate smart parking components in hub airport expansions, covering 45 major facilities.
- Residential Buildings:Multi-tenant garages with access control and visitor management priorities. Singapore condominium associations favor license plate recognition over RFID cards to reduce hardware replacement costs.
- Event Venues:Stadiums and arenas with extreme demand spikes requiring pre-booking systems and traffic flow optimization. SKIDATA maintains dominant positioning here through throughput reliability guarantees.
Commercial Areas generate the highest transaction density while Airports command the steepest expansion trajectory due to federal funding conditionality.
End User:
Budget authority and procurement sophistication separate end-user categories, with municipalities running multi-year capital cycles and private operators favoring subscription models.
- Municipalities:City governments managing on-street parking and public garages under smart city directives. Japan's METI subsidizes 50% of sensor deployment costs in Osaka and Fukuoka for systems feeding centralized mobility dashboards.
- Malls:Retail property managers prioritizing tenant retention through queue reduction and loyalty program integration. Singapore premium retail verticals correlate frictionless parking directly with lease renewal rates.
- Corporations:Campus operators with employee commute reduction mandates and visitor experience requirements. German automotive manufacturers specify EV charging-parking convergence in new facility designs.
- Residential Complexes:Homeowner associations and property management firms with cost-sensitive maintenance budgets. These deployments lag commercial adoption by 3-4 years due to fragmented decision-making.
Municipalities anchor the volume base while Malls expand most quickly as retail competition intensifies.
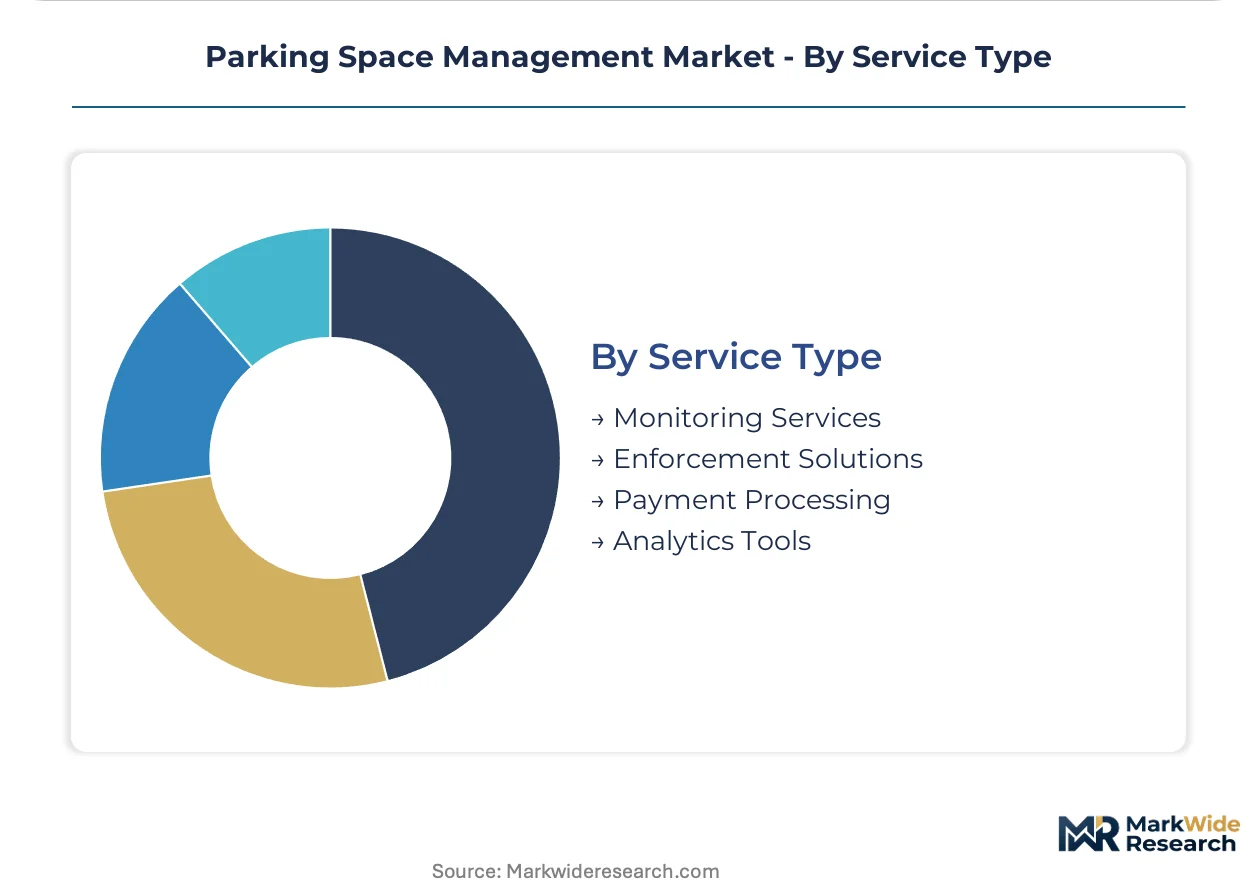
Service Type:
Revenue model differentiation separates monitoring-centric offerings from outcome-based enforcement and payment contracts.
- Monitoring Services:Continuous occupancy tracking with SLA-guaranteed data freshness for dynamic pricing algorithms. London commercial garage operators now specify 200-millisecond vacancy update requirements.
- Payment Processing:Transaction rails integrating mobile wallets, license plate recognition, and municipal citation systems. Singapore and Dubai property managers increasingly demand gateless entry-exit architectures.
- Enforcement Solutions:Automated citation issuance and scofflaw identification using camera-based license plate capture. EU member states embed these capabilities in congestion pricing zone management.
- Analytics Tools:Demand forecasting and revenue optimization platforms that ingest historical occupancy patterns. These tools command premium pricing in land-scarce markets where precision economics matter most.
Monitoring Services anchors the volume base while Payment Processing climbs the fastest as cashless transaction norms solidify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US DOT anchors the dominant geography through airport capital improvement grants that now mandate smart parking components in 45 major hub expansions. Germany's EU Green Deal retrofit mandates and Japan's METI subsidies are accelerating sensor deployments across three continents.
United States
Airport infrastructure modernization drives procurement velocity, with US DOT and FAA funding conditions embedding smart parking requirements in terminal expansion plans. Federal grants cover sensor networks and dynamic pricing integration at hub facilities in Atlanta, Denver, and Los Angeles. Commercial corridors in Manhattan and downtown Chicago operate pilot programs adjusting curb rates every 15 minutes based on real-time occupancy feeds.
Germany
EU F-Gas Regulation compliance is forcing HVAC redesigns in enclosed municipal garages across Stuttgart, Munich, and Frankfurt. The country's national automotive regulator KBA influences equipment standards for license plate recognition systems deployed at manufacturing campuses. Bavarian cities under Green Deal mandates specify sub-watt standby consumption thresholds for new sensor networks replacing magnetic loop detectors.
Japan
METI subsidizes 50% of sensor deployment costs in Osaka and Fukuoka for systems feeding centralized urban mobility dashboards. The country's industrial standards body JIS shapes interoperability requirements for parking reservation APIs integrated with multimodal transit apps. Tokyo's commercial garage operators pilot edge-computing camera systems achieving 200-millisecond vacancy updates.
Singapore
Land scarcity forces precision parking economics in the city-state's premium retail and medical office verticals. The Land Transport Authority coordinates dynamic pricing pilots in Downtown and Business Bay districts with 15-minute rate adjustments. Mall operators report 60% transaction volume migrating from physical tickets to smartphone credentials within 18 months of deployment.
United Arab Emirates
Dubai's Roads and Transport Authority operates the largest single-tenant cloud platform deployment, processing 340,000 space updates hourly across commercial corridors. MOHAP influences ventilation and safety standards for underground facilities in the emirate's dense urban core. Abu Dhabi property managers increasingly demand gateless entry-exit architectures integrating license plate recognition with mobile wallet payments.
Parking Space Management Market Competitive Landscape
Infrastructure heritage players and cloud-native integrators split the market across divergent procurement channels. Municipal relationships and embedded traffic management expertise favor established European equipment vendors in German and French public sector tenders. Mobile-first platforms capture share in Asian commercial corridors where frictionless consumer experience commands premium pricing. Dominant competitive moves include API-first architecture development and outcome-based service contract restructuring away from capital-heavy equipment sales.
Within the infrastructure heritage tier, Siemens AG and Kapsch TrafficCom AG occupy positions shaped by decades of municipal traffic system deployments. Siemens anchors European public sector procurement through embedded relationships with German and Austrian transport authorities. Kapsch exemplifies tolling-adjacent expansion, leveraging transponder interoperability expertise across multimodal parking and road pricing systems. SKIDATA represents the access-control specialist archetype, sustaining positioning in stadium and airport verticals where throughput reliability guarantees justify pricing premiums.
| Leading Market Players |
|---|
| Amano Corporation |
| INDIGO Group |
| ABM Industries Incorporated |
| Siemens AG |
| LAZ Parking |
| SP Plus Corporation |
| Kapsch TrafficCom AG |
| SKIDATA |
| Cubic Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwanese foundry concentration for LiDAR and mmWave sensor modules determines both the customization-premium spread in municipal procurement and the geographic shape of hardware supply chains. This single-source dependency forces tiered pricing structures where configured-to-order sensor networks command substantial premiums over standard cloud-platform subscriptions.
Pricing Analysis
Configured-to-order pricing for sensor hardware diverges sharply from standardized SaaS-tiered cloud platform subscriptions. Pricing stratifies across premium, standard, and economy tiers based on certification grade—UL 294 and EN 50133 compliance adds substantial cost—and customization level for legacy protocol integration. Cost compression in the hardware tier is intensifying because Taiwanese semiconductor lead times extend deployment windows. Municipalities exhibit the highest price sensitivity due to multi-year capital cycles, while airport operators under federal grant conditionality show the least.
Supply Chain Analysis
Upstream feedstock for parking sensor networks draws from Taiwan for semiconductor foundry capacity, China for rare earth magnet components in inductive loops, and Germany for precision mechanical assemblies in access control gates. Raw material dependencies center on silicon wafers, neodymium magnets, and aluminum extrusions for enclosure fabrication. Single-source vulnerability in Taiwanese LiDAR module production exposes deployment timelines to geopolitical disruption. Distribution runs through municipal procurement channels, systems integrators, and direct OEM relationships with airport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion positioning as cloud-native platforms displace legacy on-premise systems and EU Green Deal retrofit mandates accelerate sensor replacement timelines across European municipal fleets.
For Market Incumbents: Harden embedded municipal relationships through API-first architecture investments that preempt cloud-native substitution. Deepen certification holdings in UL 294 and EN 50133 to maintain pricing power in stadium and airport verticals where throughput reliability commands premiums. Consolidate middleware capabilities to resolve legacy protocol fragmentation that blocks competitor integration. For New Entrants and Emerging Players: Pursue curbside monetization pilots in Dubai and Singapore where land scarcity forces 15-minute dynamic pricing adjustments and procurement sophistication lags technical capability. Target residential complexes in Japan where METI subsidies reduce customer acquisition costs and decision-making fragmentation creates entry windows. Lead with mobile-first credentialing that eliminates gate hardware entirely. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors cloud-native integrators with embedded traffic management expertise over pure hardware vendors. Long-term viability hinges on outcome-based service contract restructuring away from capital-heavy equipment sales. Watch Japan METI subsidy renewal decisions as the inflection indicator for Asian deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables real-time congestion pricing integration with municipal traffic management systems. |
| Edge Computing Camera Deployment | Achieves 200-millisecond vacancy updates while eliminating fiber backhaul infrastructure costs. |
| Outcome-Based Service Contracting | Shifts revenue from capital equipment to recurring performance-guaranteed monitoring services. |
| EV Charging Convergence | Creates bundled reservation APIs with charge point operators at multi-tenant commercial properties. |
| F-Gas Compliant HVAC Retrofit | Avoids mid-life penalties in enclosed German and French municipal garage structures. |
Research Methodology
The analysis maps IoT sensor networks, cloud platforms, mobile applications, and reservation systems, each validated through municipal procurement officers, airport capital planning directors, parking facility operators, and systems integration specialists. Primary interviews combined with secondary validation from EU Green Deal implementation reports, US DOT airport grant filings, Japan METI subsidy disclosures, and Singapore Land Transport Authority pilot documentation. Bottom-up deployment counts triangulate against top-down municipal budget allocations.
Assumptions held fixed include regulatory compliance timelines for EU F-Gas Regulation and US DOT grant conditionality, while sensor technology transition rates and cloud-platform adoption curves were varied across the projection horizon. Segmentation dimensions modeled encompass technology layer, application site type, end-user budget authority, and service revenue model. CAGRs derive from deployment trajectory analysis correlated with municipal capital improvement cycles and federal funding authorization patterns.
Macroeconomic conditions sit as an overlay; deviation in municipal tax revenue, semiconductor foundry utilization, or federal infrastructure appropriations would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology replacement cycles. Cross-checking against airport capital improvement program announcements and smart city procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Smart Parking Systems Market