
 Airbag Sensor Market | 2026-2036
Airbag Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Airbag Sensor Market Analytics
OEM procurement concentration is recalibrating as electric vehicle platforms multiply sensor node requirements across new vehicle architectures. Robert Bosch GmbH leverages its MEMS fabrication depth to dominate crash-sensor supply for European premium platforms. Autoliv Inc. anchors North American OEM relationships through integrated safety-module contracts. Continental AG competes on capacitive-sensor miniaturization for steering-wheel and seat-track deployments.
An airbag sensor detects collision dynamics through accelerometric, pressure, or inertial measurement and triggers restraint-system deployment within milliseconds; MEMS-based units now integrate multi-axis detection at sub-millimeter semiconductor scale. Acceleration sensors lead unit volume due to universal fitment across frontal and side-impact modules, while pressure sensors capture the fastest growth trajectory as pedestrian-protection airbags proliferate in hood and bumper systems. Piezoelectric technology occupies the mature cost-optimized tier, whereas capacitive architectures differentiate through immunity to electromagnetic interference in electric-vehicle high-voltage environments.
NHTSA Federal Motor Vehicle Safety Standards, Euro NCAP assessment protocols, and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements collectively mandate detection latency thresholds and false-positive suppression that elevate sensor precision specifications. The EU AI Act and UNECE cybersecurity regulations are extending compliance burdens into sensor firmware validation and over-the-air update governance. Stakeholders must monitor how software-defined vehicle architectures redistribute sensing intelligence between edge nodes and central domain controllers.
Market Dynamics
Electric vehicle architectures are redistributing sensor intelligence from discrete crash-detection modules toward integrated central domain controllers, compressing unit economics while expanding functional requirements per node.
Growth Catalysts
- Euro NCAP 2026 Protocols:The revised assessment framework mandates enhanced pedestrian-protection airbag coverage, forcing hood and bumper sensor densification across European vehicle programs.
- Silicon Carbide Inverter Penetration:High-voltage power electronics in EV drivetrains generate electromagnetic interference that capacitive sensor architectures uniquely withstand, accelerating their displacement of piezoelectric alternatives.
- Software-Defined Vehicle Stacks:Over-the-air update capabilities enable continuous refinement of crash-detection algorithms, extending sensor functional lifecycles and reducing replacement frequency.
Market Restraints
- MEMS Foundry Concentration:Front-end fabrication for automotive-grade accelerometers concentrates in Taiwan and South Korea, exposing supply continuity to geopolitical friction and capacity allocation decisions.
- Raw Material Cost Volatility:Palladium and platinum group metals essential for piezoelectric ceramic electrodes face price instability tied to South African mining output and Russian export flows.
- Functional Safety Certification Burden:ISO 26262 ASIL-D validation for crash-critical sensors extends development timelines and locks out mid-tier semiconductor entrants lacking automotive qualification experience.
Strategic Opportunities
- India Production-Linked Incentive Scheme:The PLI scheme for automotive components offers cost-offsets for domestic sensor assembly, attracting tier-1 suppliers to establish captive manufacturing near Chennai and Pune vehicle hubs.
- Occupant Classification Integration:Seat-mounted pressure sensors are converging with capacitive occupant-detection systems, creating unified modules that reduce wiring harness complexity and assembly labor.
- UNECE Cybersecurity Regulation:The mandate for intrusion detection and secure firmware update channels creates aftermarket service revenue streams for sensor calibration and certificate management.
Industry Challenges
- Functional Safety Engineering Talent:The scarcity of engineers with ISO 26262 implementation experience constrains validation throughput at sensor suppliers expanding EV program portfolios.
- Legacy Platform Integration:Retrofitting central-domain controller architectures into existing vehicle electrical systems requires backward-compatible sensor interfaces that add cost and latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airbag Sensor Market |
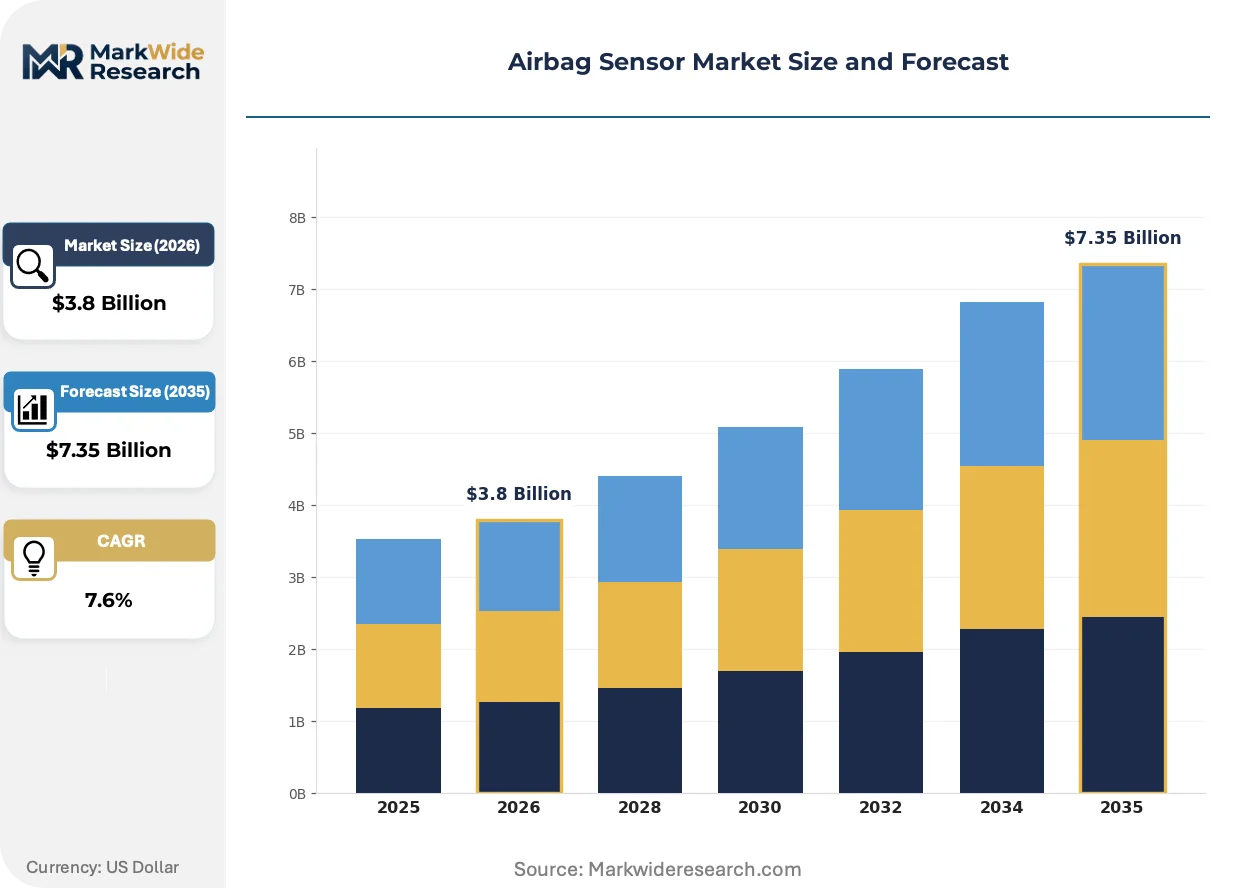
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crash Sensors, Pressure Sensors, Acceleration Sensors, Impact Sensors Technology: Piezoelectric, Capacitive, MEMS, Optical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles |
| Companies Covered | Robert Bosch GmbH, Autoliv Inc., Continental AG, ZF Friedrichshafen AG, DENSO Corporation, Joyson Safety Systems, Hyundai Mobis Co., Ltd., Toyoda Gosei Co., Ltd., NXP Semiconductors NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airbag Sensor Market Evolving Landscape
Sensor fusion architectures are collapsing discrete accelerometer, gyroscope, and pressure nodes into single inertial measurement units, compressing bill-of-materials while demanding higher semiconductor integration density.
Capacitive sensing technology is converging with MEMS fabrication processes to produce dual-axis crash detectors immune to electromagnetic interference from 800-volt EV powertrains. European premium OEMs are adopting these units for steering-wheel and seat-track deployments ahead of North American programs. The structural consequence is a compression in piezoelectric sensor pricing as capacitive alternatives capture high-voltage platform design wins.
The EU AI Act's risk-classification framework now governs machine-learning inference models embedded in crash-detection firmware, requiring documented training-data provenance and bias-auditing protocols. Sensor suppliers must maintain algorithm version histories and explainability documentation for type-approval submissions. German KBA and French ANSM regulatory staff are conducting joint inspections of validation records, elevating compliance costs for non-European component vendors.
Fleet operators and mobility-as-a-service providers are unbundling sensor replacement cycles from traditional vehicle service intervals, instead triggering component swaps based on predictive degradation models. This consumption-pattern shift compresses aftermarket parts revenue for conventional distributors while creating subscription-based calibration-service contracts. The transformation is most visible in German and Japanese commercial-vehicle leasing programs where uptime guarantees dominate procurement criteria.
Airbag Sensor Market Segmentation
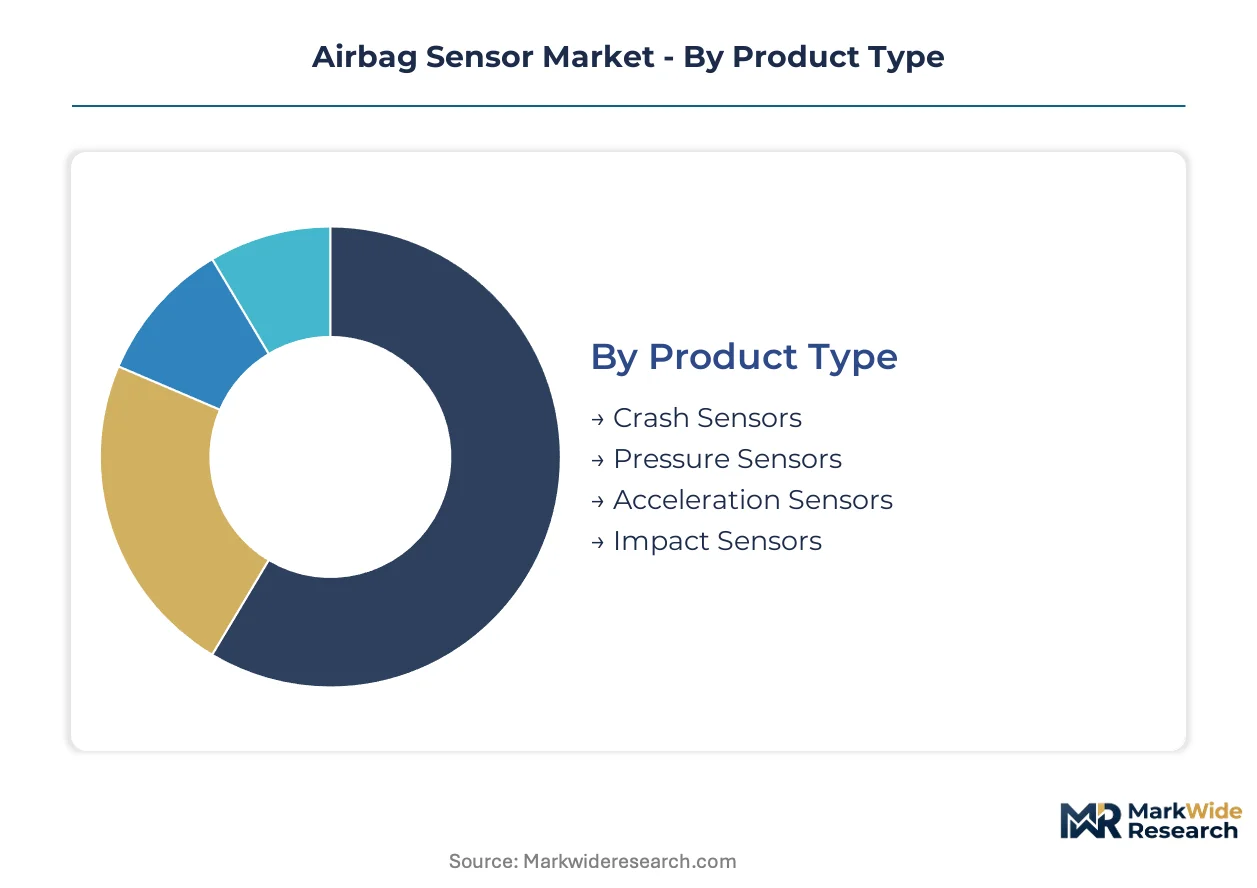
Airbag sensor procurement patterns diverge sharply across product architectures and voltage environments, with capital deployment decisions increasingly tied to electric vehicle platform requirements and electromagnetic compatibility specifications.
Product Type:
Crash sensors demand the heaviest upfront capital commitment due to multi-axis MEMS fabrication complexity and ASIL-D validation requirements.
- Crash Sensors:Multi-axis MEMS units integrate accelerometric and gyroscopic detection within single semiconductor packages. European premium OEMs specify these for central domain controller architectures in high-voltage platforms, compressing unit economics while expanding functional scope per node.
- Pressure Sensors:Hood and bumper deployments for pedestrian protection require rapid-response piezoelectric or capacitive elements. Euro NCAP 2026 protocols are forcing sensor densification across German and French vehicle programs, steepest expansion trajectory in this category.
- Acceleration Sensors:Universal frontal and side-impact fitment produces highest unit volumes.
- Impact Sensors:Discrete single-axis units serve legacy platform retrofits and cost-optimized segments.
Most installed capacity flows through Acceleration Sensors. Expansion is steepest in Pressure Sensors.
Technology:
Technology selection hinges on electromagnetic immunity requirements and foundry access, with capacitive architectures commanding premium pricing in 800-volt EV applications.
- MEMS:Silicon-based microelectromechanical systems enable sub-millimeter multi-axis integration at automotive-grade reliability. Taiwan and South Korea foundries concentrate front-end fabrication, exposing supply continuity to geopolitical friction and capacity allocation decisions.
- Capacitive:Electrostatic sensing architectures withstand high-voltage powertrain interference without shielding overhead. German KBA type-approval records show accelerating adoption for steering-wheel and seat-track deployments ahead of North American programs.
- Piezoelectric:Ceramic-based mature tier faces pricing compression as capacitive alternatives capture design wins.
- Optical:Emerging fiber-optic approaches for extreme electromagnetic environments.
MEMS dominates current production volumes. Capacitive technology is gaining share fastest in new platform awards.
End User:
Procurement authority concentrates with entities controlling system integration and type-approval pathways.
- OEMs:Volkswagen Group, Toyota Motor, and Ford Motor specify sensor performance parameters and validate supplier algorithms through proprietary crash-test protocols. Direct procurement of strategic sensor categories is expanding as software-defined vehicle architectures demand tighter firmware governance.
- Tier-1 Suppliers:Autoliv, Bosch, and Continental aggregate discrete sensors into integrated safety modules, capturing value through assembly labor and validation documentation.
- Vehicle Assemblers:Contract manufacturers execute build-to-print sensor installation with limited design authority.
- Aftermarket Providers:Distributors and service networks handle replacement cycles and calibration services.
OEMs command specification authority. Tier-1 Suppliers capture the steepest margin expansion through module integration.
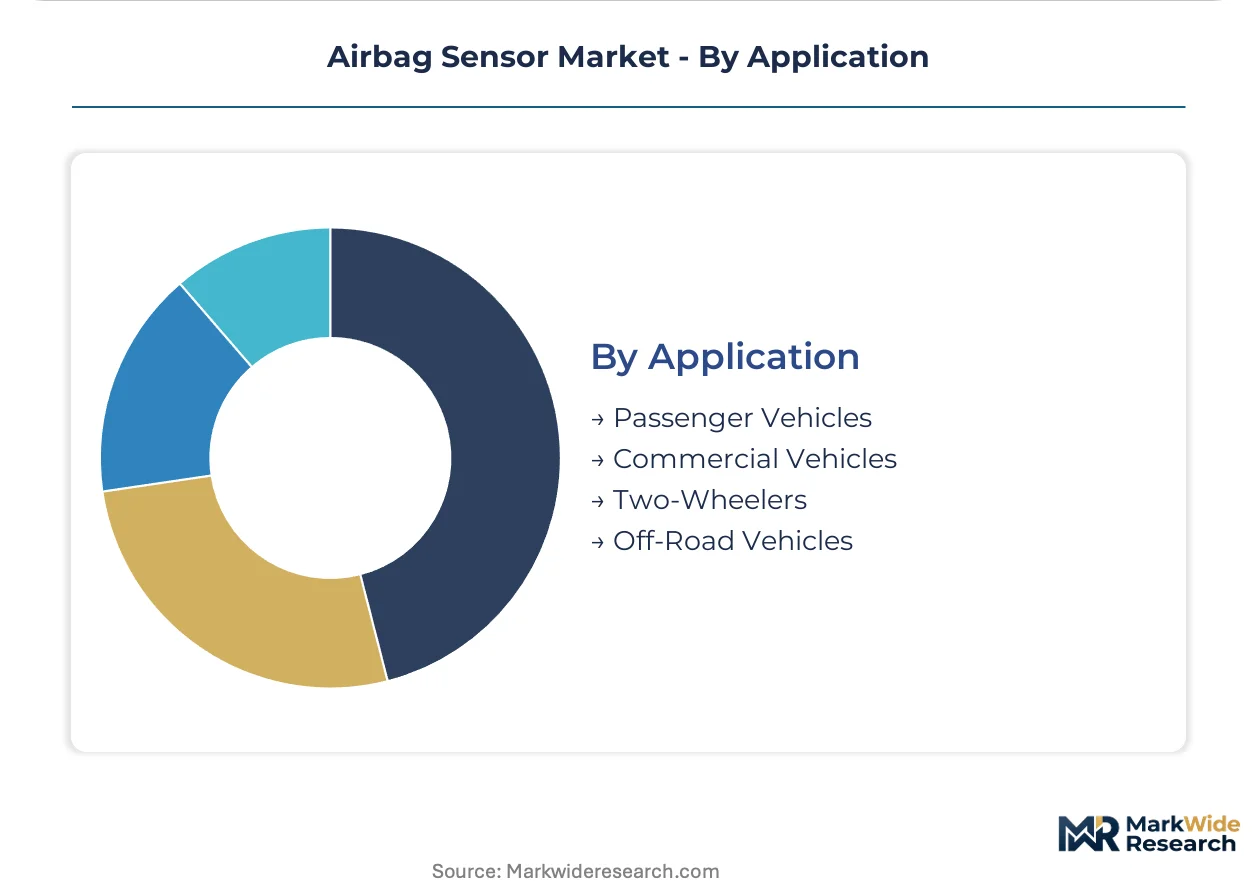
Application:
Vehicle electrification intensity and regulatory crash-test regimes determine sensor count and sophistication per platform.
- Passenger Vehicles:Light-duty electrified platforms deploy the densest sensor arrays, with European and Japanese OEMs leading hood airbag integration for pedestrian protection. NHTSA and Euro NCAP divergence in test protocols creates regional specification fragmentation.
- Commercial Vehicles:Fleet operators in German and Japanese leasing programs are unbundling replacement cycles from traditional service intervals, triggering component swaps based on predictive degradation models rather than mileage thresholds.
- Two-Wheelers:Emerging regulatory mandates in India and Southeast Asia are creating volume opportunities at reduced per-unit specification levels.
- Off-Road Vehicles:Construction and agricultural equipment subject to ISO 26262 derivative standards with modified environmental sealing requirements.
Passenger Vehicles absorb most sensor production. Commercial Vehicles are expanding most quickly through fleet electrification and uptime-guarantee procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vehicle assembly hubs command denser sensor arrays per platform than Japanese counterparts, reflecting divergent pedestrian-protection regulatory timelines and EV electrification intensity across these manufacturing centers.
United States
NHTSA Federal Motor Vehicle Safety Standard 208 mandates detection latency thresholds that elevate precision specifications for frontal-impact modules. Detroit-area assembly plants source integrated safety modules through tier-1 suppliers co-located in Michigan and Ohio. The Southeast corridor from Tennessee to South Carolina attracts sensor assembly investments as transplant OEMs expand electrified SUV production.
Germany
Volkswagen Group and BMW procurement specifications drive capacitive sensor adoption for 800-volt architectures. KBA type-approval records document accelerating steering-wheel and seat-track deployments ahead of other European programs. Stuttgart and Munich industrial clusters concentrate MEMS validation laboratories and crash-test facilities serving premium platform development.
Japan
METI carbon-neutrality roadmaps accelerate EV platform launches requiring electromagnetic-immune sensor architectures. Toyota Motor and Honda Motor validate supplier algorithms through proprietary crash-test protocols at Tsukuba and Tochigi facilities. Kyushu-based semiconductor packaging operations support sensor module integration for domestic and export vehicle programs.
China
MIIT new-energy vehicle mandates expand sensor node requirements across domestic EV architectures. BYD and NIO specify multi-axis MEMS units for central domain controller integration at Shenzhen and Hefei assembly hubs. Yangtze River Delta foundry capacity constraints expose supply continuity risks for automotive-grade accelerometer procurement.
India
PLI scheme cost-offsets for automotive components attract tier-1 suppliers to establish captive manufacturing near Chennai and Pune vehicle hubs. BIS certification requirements for crash-critical sensors extend validation timelines for non-domestic component vendors. Tamil Nadu and Maharashtra industrial corridors concentrate emerging two-wheeler airbag sensor demand as regulatory mandates expand.
Airbag Sensor Market Competitive Landscape
German producers anchor one tier; Japanese and South Korean specialists hold differentiated positions in module integration and semiconductor supply. The vendor base concentrates around integrated safety system providers with captive MEMS fabrication or long-term foundry partnerships. Three archetypes dominate: diversified automotive suppliers with vertical safety-module control, semiconductor specialists leveraging MEMS process expertise, and diversified industrial conglomerates with tier-1 vehicle manufacturer relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves as EV platform awards intensify.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated-module archetype through their control over specification-setting relationships with European premium OEMs. Autoliv Inc. represents the safety-system pure-play model, occupying a position defined by integrated restraint-module contracts rather than component supply. These three entities anchor competitive dynamics through their influence over algorithm validation pathways and type-approval documentation standards.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Autoliv Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| Joyson Safety Systems |
| Hyundai Mobis Co., Ltd. |
| Toyoda Gosei Co., Ltd. |
| NXP Semiconductors NV |
| Others |
Value Network & Pricing Analysis
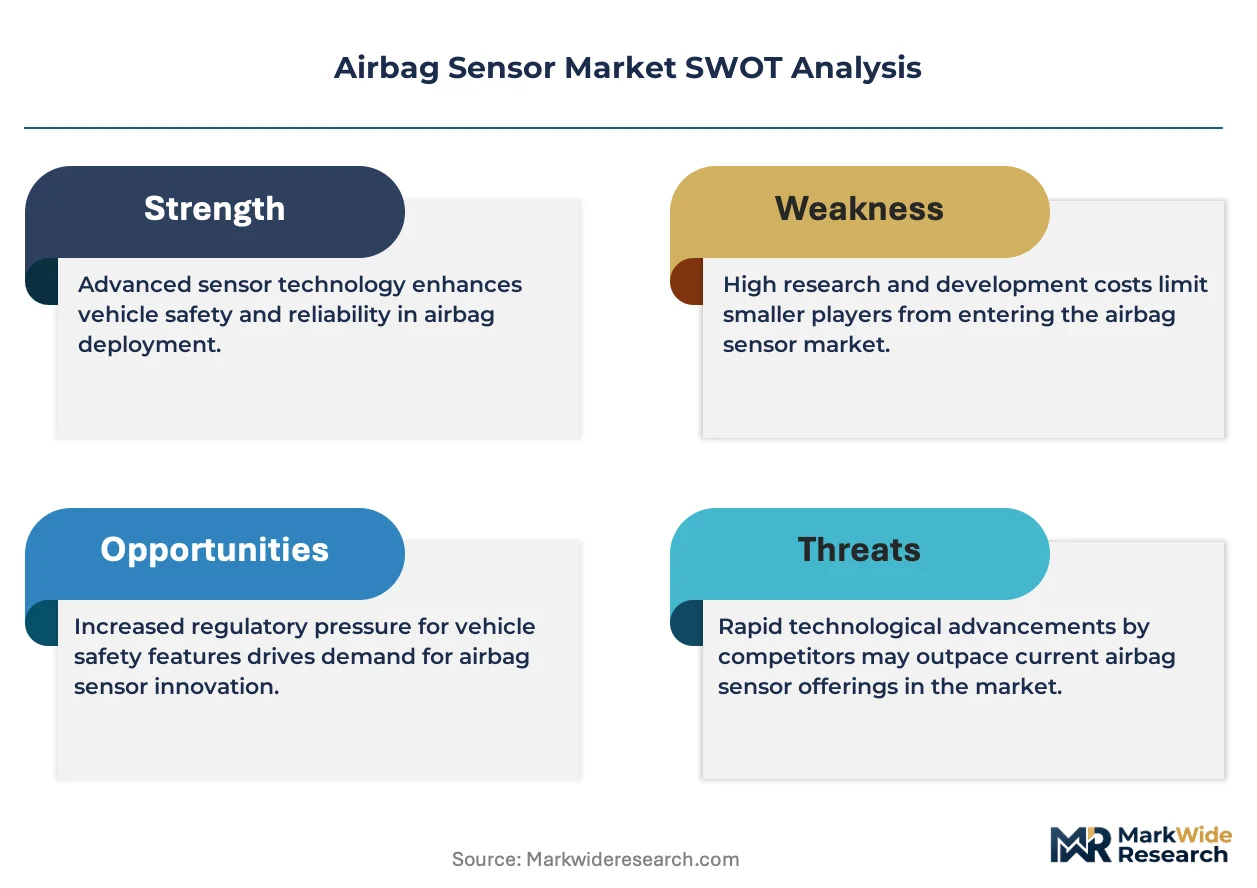
Euro NCAP 2026 pedestrian-protection mandates gate qualified supply access and premium-tier pricing power, as OEMs restrict procurement to suppliers with validated hood and bumper sensor portfolios while capacitive architectures command electromagnetic-immune premiums in 800-volt EV platforms.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-tier acceleration sensors, compressing margins on mature piezoelectric units while ASIL-D certified MEMS crash sensors sustain premium-mid-economy pricing differentiation driven by ISO 26262 validation depth and foundry partnership exclusivity. Cost compression in the piezoelectric tier intensifies because capacitive alternatives capture high-voltage platform design wins, with fleet operators and aftermarket distributors exhibiting highest price sensitivity versus premium OEMs prioritizing detection latency specifications.
Supply Chain Analysis
Dual-sourcing requirements from Volkswagen Group and Toyota Motor mandate multi-supplier qualification for MEMS front-end fabrication, drawing from Taiwan, South Korea, and Japan foundries while palladium and platinum group metals for piezoelectric electrodes hinge on South African mining output and Russian export flows. Single-source vulnerability concentrates in Taiwan semiconductor packaging, with distribution running through tier-1 safety module integrators co-located with vehicle assembly hubs in Germany, Japan, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airbag sensor market functions as a regulatory compounder, with Euro NCAP 2026 pedestrian-protection protocols forcing sensor densification across European vehicle programs and sustaining demand visibility independent of cyclical automotive production swings.
For Market Incumbents: Anticipate margin compression in legacy piezoelectric crash sensors as capacitive architectures displace incumbent technology in 800-volt EV platforms, and prioritize backward integration into MEMS foundry partnerships or captive Taiwan capacity to secure wafer allocation against geopolitical friction. For New Entrants and Emerging Players: Capture white-space in Indian two-wheeler airbag sensor demand as BIS certification mandates expand, targeting cost-optimized acceleration sensor supply through PLI scheme cost-offsets near Chennai assembly corridors with validation documentation partnerships for streamlined type-approval. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-2 semiconductor specialists lacking automotive qualification experience but possessing MEMS process expertise applicable to crash-detection firmware, with long-term viability contingent on ISO 26262 ASIL-D certification investment; watch KBA and ANSM joint inspection enforcement as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacitive Sensor Architecture Migration | Enables electromagnetic immunity certification for 800-volt EV platforms ahead of North American adoption curves. |
| India PLI Manufacturing Footprint | Captures cost-offsets for domestic sensor assembly near Chennai and Pune vehicle hubs. |
| Occupant Classification Module Integration | Reduces wiring harness complexity through unified seat-mounted pressure and capacitive detection systems. |
| UNECE Cybersecurity Compliance Investment | Creates aftermarket service revenue streams for sensor calibration and certificate management. |
| Central Domain Controller Partnership | Redistributes sensing intelligence from discrete nodes toward integrated architectures in software-defined vehicles. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down MEMS foundry capacity tracking forms the analytical core, combining primary interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and KBA type-approval officials with secondary validation through NHTSA FMVSS filings, Euro NCAP assessment protocols, vehicle registration databases, and IHS Markit production data.
Historical trendline analysis of sensor content per vehicle across propulsion architectures, regulatory test regimes, and regional production clusters anchors the projection framework, with CAGRs derived from segment-level modeling of crash sensor, pressure sensor, acceleration sensor, and impact sensor demand across passenger vehicle, commercial vehicle, two-wheeler, and off-road applications.
Geopolitical friction in Taiwan Strait semiconductor supply, palladium price volatility tied to South African mining disruptions, and Euro NCAP protocol implementation delays are the dominant revision risks to modeled outcomes; forecasts reflect assumptions about foundry capacity allocation and regulatory enforcement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market