
 Airbag Control Unit Sensor Market | 2026-2036
Airbag Control Unit Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Airbag Control Unit Sensor Market Outlook
Project finance and equipment leasing for semiconductor fabrication capacity is reconfiguring which tier-1 suppliers can secure long-term sensor supply agreements. Denso Corporation leverages captive foundry partnerships to anchor its position in Japanese OEM supply chains. Continental AG sustains R&D intensity across multi-stage sensor architectures for European premium platforms. NXP Semiconductors competes through its mixed-signal portfolio spanning analog-to-digital crash signal processing.
An airbag control unit sensor detects rapid deceleration, impact force, and collision angle through microelectromechanical systems, converting mechanical stress into electrical signals processed at sub-millisecond latency to trigger pyrotechnic inflators. Multi-stage sensors now lead volume shipments as automakers phase out single-point detection in favor of adaptive deployment algorithms. MEMS technology dominates the architecture landscape due to silicon batch fabrication economies, while hybrid analog-digital designs concentrate margin pools in safety-critical automotive grade certifications. OEM direct procurement channels are consolidating specification authority as vehicle assemblers internalize crash algorithm development.
NHTSA Federal Motor Vehicle Safety Standards and Euro NCAP assessment protocols mandate multi-axis crash detection, directly expanding sensor count per vehicle platform. Japan's METI vehicle safety directives and ISO 26262 functional safety standards shape product qualification timelines and barrier-to-entry economics for new entrants. Stakeholders must monitor how software-defined vehicle architectures redistribute sensing intelligence between dedicated airbag modules and centralized domain controllers.
Market Dynamics
Software-defined vehicle architectures are redistributing sensing intelligence from dedicated airbag modules toward centralized domain controllers, forcing sensor suppliers to recalibrate hardware-software value capture strategies.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Mandates for multi-axis crash detection expand sensor count per vehicle platform, compelling OEMs to integrate additional detection points across front, side, and curtain systems.
- MEMS batch fabrication:Silicon wafer economies reduce unit production costs while enabling higher precision accelerometers and gyroscopes for sub-millisecond latency requirements.
- German automotive electronics clusters:Concentrated R&D infrastructure around Stuttgart and Munich accelerates prototyping cycles for multi-stage sensor architectures.
Market Restraints
- Automotive-grade silicon foundry concentration:Taiwan and South Korea dominate semiconductor fabrication, creating supply vulnerability for sensor die procurement during capacity constraints.
- ISO 26262 functional safety certification:ASIL-D qualification timelines extend 18-24 months, elevating barrier-to-entry economics for new sensor entrants.
- Palladium and platinum price volatility:Pyrotechnic initiator materials expose inflator-integrated sensor modules to raw material cost swings.
Strategic Opportunities
- India vehicle safety mandate expansion:Bharat NCAP adoption and mandatory airbag regulations create greenfield sensor demand in a market transitioning from optional to standard fitment.
- Edge AI sensor fusion:Convergence of MEMS accelerometry with machine learning inference at the sensor node enables predictive crash classification before impact confirmation.
- Direct OEM procurement channels:Vehicle assemblers internalizing crash algorithm development bypass traditional tier-1 mediation, opening specification authority to specialized sensor developers.
Industry Challenges
- Embedded systems safety engineering talent:Shortage of engineers qualified in both MEMS physics and ISO 26262 fault analysis constrains product development velocity.
- Legacy vehicle platform integration:Retrofitting centralized domain controller architectures into existing electrical/electronic topologies requires backward-compatible sensor communication protocols.
- Patent thickets around crash detection algorithms:Dense intellectual property landscapes in adaptive deployment timing create licensing friction for multi-stage sensor innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airbag Control Unit Sensor Market |
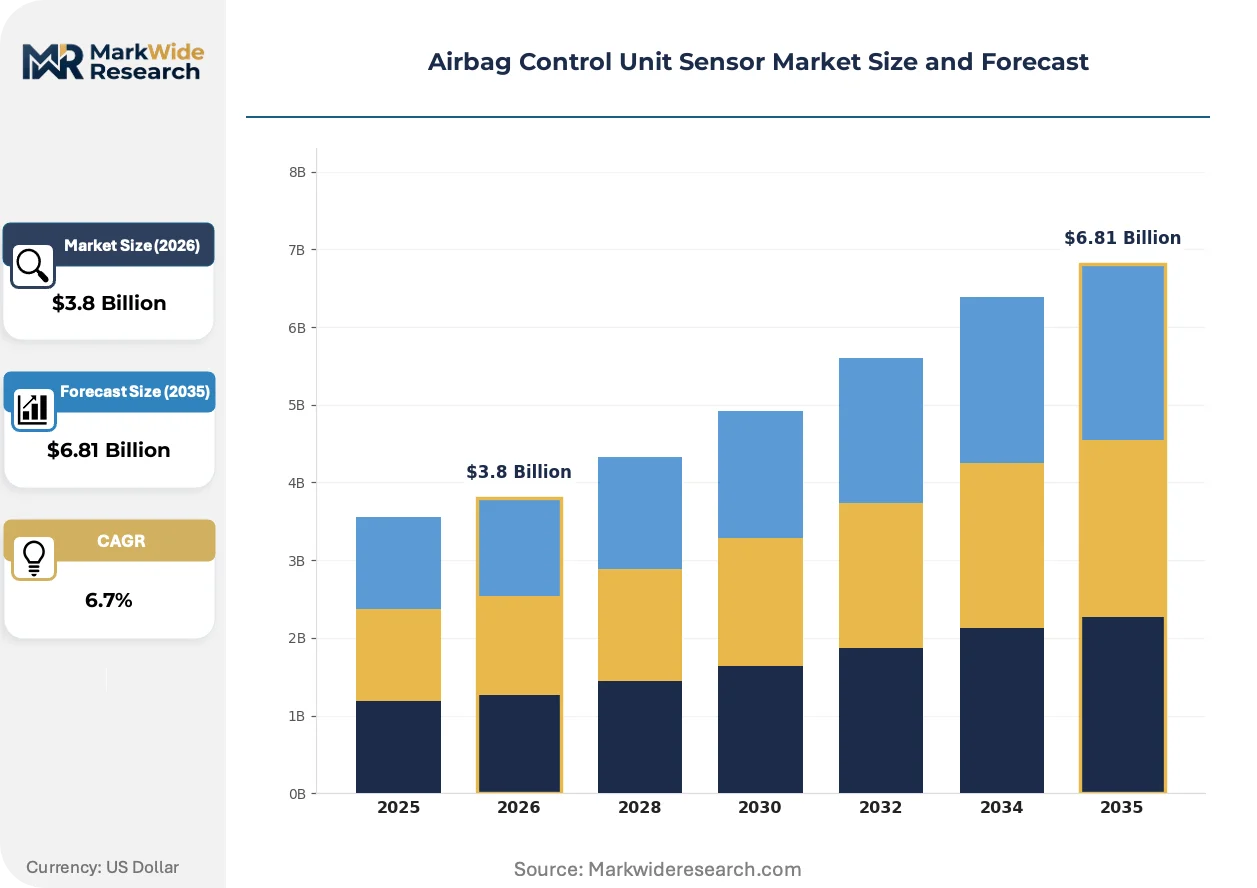
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage Sensors, Multi-stage Sensors, Pressure Sensors, Force Sensors Technology: MEMS, Analog, Digital, Hybrid End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Denso Corporation, STMicroelectronics, Continental AG, Analog Devices Inc., NXP Semiconductors, ZF Friedrichshafen AG, Robert Bosch GmbH, Hella GmbH & Co. KGaA, Autoliv, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airbag Control Unit Sensor Market Strategic Shifts
Crash detection intelligence is migrating from discrete hardware modules toward software-defined implementations, compressing traditional component boundaries and recalibrating supplier value propositions.
Virtualized sensor architectures are consolidating physical detection nodes into centralized computing substrates. Tier-1 suppliers deploy hypervisor-based partitioning to run multiple safety-critical applications on shared hardware. This compression is virtualizing the traditional airbag control unit as a software workload within zonal domain controllers.
Euro NCAP 2026 protocols mandate far-side impact detection and advanced restraint system coordination. European OEMs accelerate sensor specification updates to capture assessment points. Premium platforms in Germany and Sweden lead implementation, integrating additional lateral detection arrays to satisfy protocol requirements.
Fleet operators and leasing companies now specify sensor data transparency as a procurement criterion. Direct data access to crash event logs displaces black-box proprietary formats. This shift is most visible in North American commercial vehicle segments, where liability documentation requirements drive aftermarket telematics integration with OEM sensor streams.
Airbag Control Unit Sensor Market Segmentation
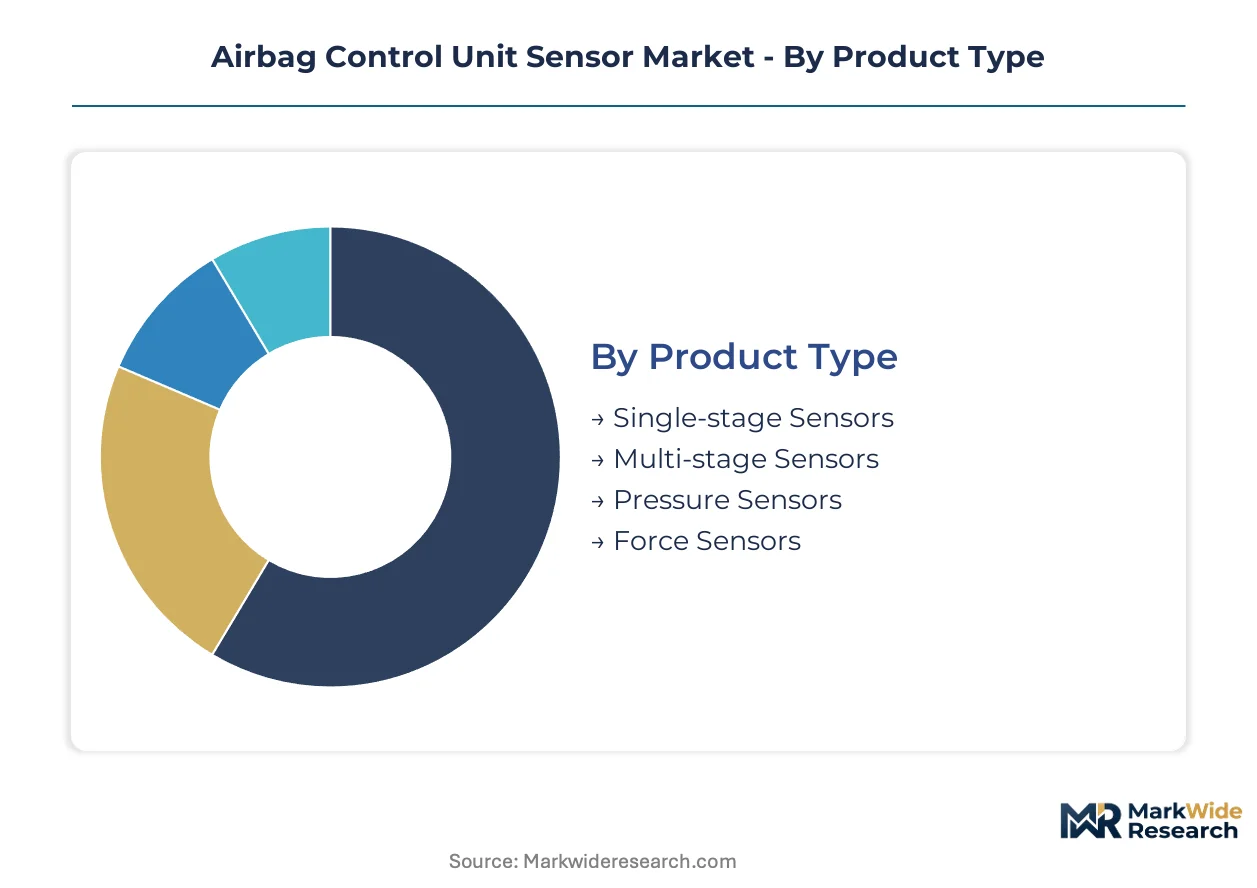
Sensor segmentation in automotive safety systems determines procurement hierarchies, certification pathways, and margin structures. Product architecture choices cascade through technology selection, end-user channel strategy, and vehicle platform integration requirements.
Product Type:
Mature single-point detection competes against emerging multi-stage architectures as OEMs reconfigure crash algorithm sophistication.
- Multi-stage Sensors:Adaptive deployment algorithms process variable impact severity through sequential signal thresholds. German and Japanese passenger vehicle OEMs concentrate procurement for premium platform integration where NHTSA and Euro NCAP mandates drive specification upgrades.
- Single-stage Sensors:Binary trigger mechanisms dominate economy vehicle segments with fixed deployment thresholds. Cost-sensitive markets in India and Southeast Asia sustain volume demand as Bharat NCAP expands mandatory fitment requirements.
- Pressure Sensors:Side-impact detection arrays measure cabin pressure differentials during collision events. European premium manufacturers specify these for curtain airbag coordination.
- Force Sensors:Pedestrian protection systems deploy these at bumper contact points to classify impact object mass and velocity.
Multi-stage sensors retain volume leadership; pressure sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates silicon batch fabrication from discrete component architectures across safety-critical applications.
- MEMS:Microelectromechanical systems leverage semiconductor wafer economies for accelerometer and gyroscope integration. Stuttgart and Munich automotive electronics clusters accelerate prototyping cycles for sub-millisecond latency requirements.
- Hybrid:Combined analog-digital signal paths optimize fault tolerance through redundant processing channels. ASIL-D qualification timelines concentrate margin pools in safety-critical automotive grade certifications.
- Digital:Pure digital signal processing enables direct integration with centralized domain controller architectures.
- Analog:Legacy architectures persist in cost-optimized vehicle platforms requiring minimal sensor count.
MEMS dominates production scale; hybrid configurations gain share fastest in premium safety systems.
End User:
Customer type fragmentation reflects redistribution of specification authority between vehicle assemblers and traditional tier-1 mediation channels.
- OEMs:Direct procurement channels bypass tier-1 suppliers as vehicle assemblers internalize crash algorithm development. NHTSA Federal Motor Vehicle Safety Standards mandate multi-axis detection, compelling OEM specification authority expansion.
- Tier-1 Suppliers:System integrators retain sensor module assembly and calibration expertise for mid-volume vehicle platforms.
- Vehicle Assemblers:Contract manufacturing relationships concentrate in emerging market production hubs.
- Aftermarket Providers:Retrofit sensor modules serve fleet operator liability documentation requirements in North American commercial segments.
OEM direct channels capture specification leadership; aftermarket providers climb the fastest on telematics integration demand.
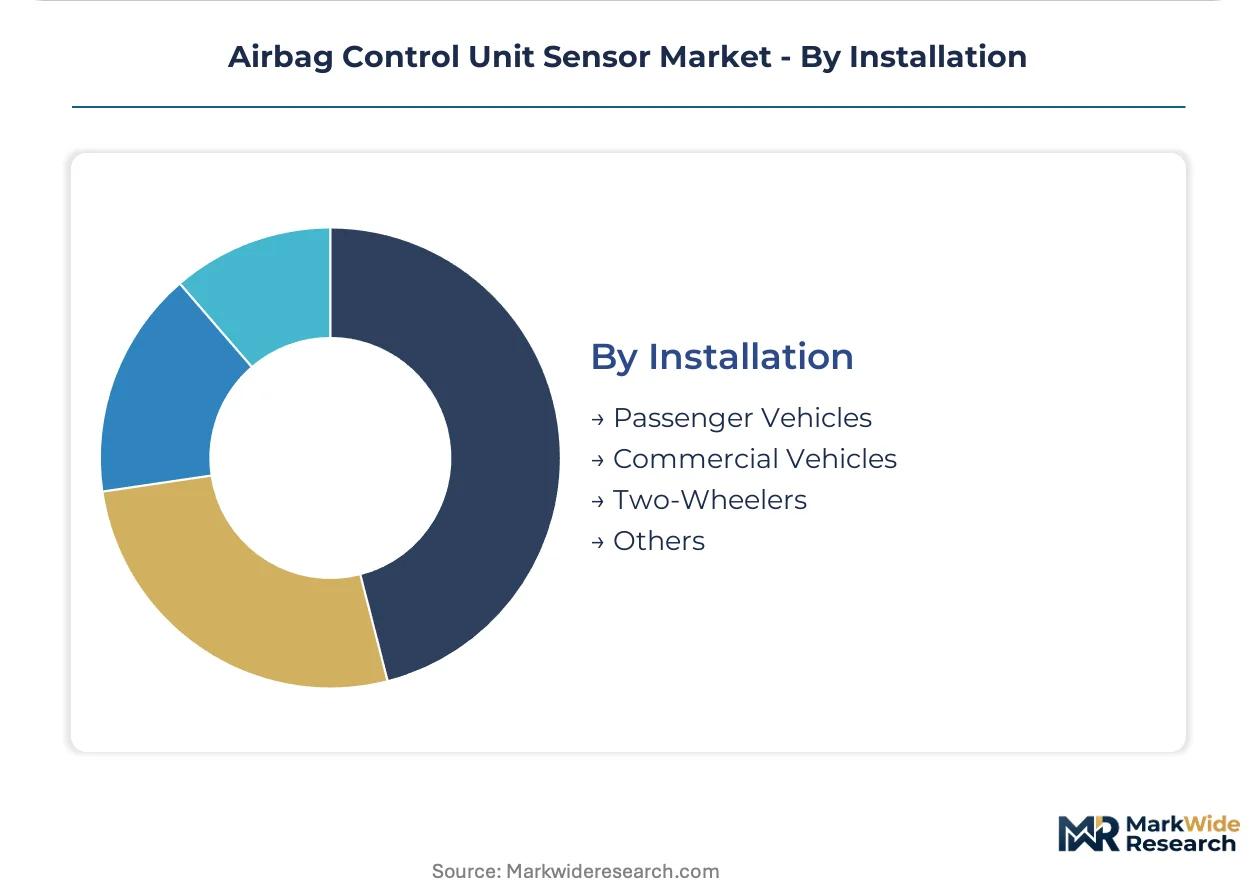
Installation:
Application volume concentrates in passenger vehicle platforms while emerging categories reshape unit economics.
- Passenger Vehicles:Front, side, and curtain airbag systems integrate multiple detection points per platform. United States, Germany, and Japan concentrate production where automotive electronics clusters dominate sensor procurement.
- Commercial Vehicles:Fleet operators specify sensor data transparency for crash event log access. METI vehicle safety directives in Japan shape heavy-duty platform qualification timelines.
- Two-Wheelers:Motorcycle airbag vests and mounted systems create compact sensor form factor demand.
- Others:Off-highway and agricultural equipment adopt adapted automotive sensor architectures for rollover protection.
Passenger vehicles retain volume leadership; commercial vehicles hold the steepest expansion curve on fleet telematics mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium OEM procurement teams, Japanese tier-1 system integrators, and United States fleet operators concentrate purchasing authority for airbag control unit sensors. These buyer archetypes drive specification standards across passenger vehicle, commercial vehicle, and emerging two-wheeler platforms.
Germany
Stuttgart and Munich automotive electronics clusters accelerate multi-stage sensor prototyping for Euro NCAP 2026 far-side impact mandates. KBA type-approval protocols enforce ASIL-D functional safety certification timelines. Baden-Württemberg suppliers coordinate lateral detection arrays for curtain airbag deployment across premium platforms.
United States
NHTSA Federal Motor Vehicle Safety Standards compel multi-axis crash detection expansion across front and side airbag systems. Detroit-area OEMs internalize crash algorithm development, bypassing traditional tier-1 mediation channels. Michigan and Ohio electronics corridors concentrate sensor module assembly for North American vehicle platforms.
Japan
METI vehicle safety directives shape heavy-duty platform qualification timelines for commercial vehicle sensor integration. Nagoya and Tokyo automotive clusters sustain captive foundry partnerships for MEMS accelerometer supply security. Denso Corporation anchors domestic OEM supply chains through backward integration into semiconductor fabrication capacity.
China
MIIT mandatory airbag regulations for passenger vehicles expand sensor fitment requirements across domestic and joint-venture platforms. Yangtze River Delta and Pearl River Delta electronics manufacturing hubs scale MEMS batch fabrication for cost-optimized vehicle segments. Shanghai and Shenzhen clusters prototype edge AI sensor fusion architectures for predictive crash classification.
India
Bharat NCAP adoption and mandatory dual-front-airbag regulations create greenfield sensor demand as the market transitions from optional to standard fitment. Tamil Nadu and Maharashtra vehicle assembly corridors attract tier-1 sensor module localization investments. Delhi-NCR and Pune electronics clusters develop single-stage sensor variants for economy vehicle price points.
Airbag Control Unit Sensor Market Competitive Environment
Channel-controlling players compete with product-specialist players across specification authority, foundry access, and algorithm integration depth. The market exhibits tiered consolidation with three to four dominant system integrators anchoring volume procurement alongside specialized MEMS fabricators capturing margin pools in safety-critical certifications. Strategic archetypes span captive semiconductor producers, mixed-signal portfolio specialists, and crash-system integrators with inflator manufacturing heritage. Competitive moves concentrate on foundry partnership anchoring and direct OEM procurement channel penetration.
Among Japanese and German diversified electronics conglomerates, Denso Corporation, Continental AG, and Robert Bosch GmbH occupy positions spanning tier-1 system integration through captive sensor die supply. Denso exemplifies the captive-foundry archetype through semiconductor fabrication partnerships that secure long-term supply agreements. Continental AG represents the multi-domain safety integrator with R&D intensity across multi-stage sensor architectures. Robert Bosch GmbH anchors the mixed-signal processing tier with heritage in automotive-grade MEMS accelerometry.
| Leading Market Players |
|---|
| Denso Corporation |
| STMicroelectronics |
| Continental AG |
| Analog Devices Inc. |
| NXP Semiconductors |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Hella GmbH & Co. KGaA |
| Autoliv, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Taiwanese automotive-grade silicon foundries during the analysis window has compressed wafer pricing, enabling sensor suppliers to secure multi-year die supply agreements while passing limited cost relief downstream. This utilization dynamic simultaneously tightens margin pools for MEMS fabricators and accelerates procurement consolidation among tier-1 system integrators.
Pricing Analysis
Cost-plus contracts with palladium indexation dominate pyrotechnic initiator procurement, tethering sensor module pricing to precious metal volatility. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified multi-stage architectures from single-stage variants. Cost compression in economy-tier single-stage sensors intensifies as Bharat NCAP mandates expand volume without specification upgrades. Fleet operators in North American commercial segments exhibit lowest price sensitivity due to liability documentation requirements.
Supply Chain Analysis
Upstream silicon wafer feedstock draws from Taiwan, South Korea, and Germany, with 300mm automotive-grade capacity concentrated in Hsinchu and Dresden clusters. Palladium and platinum for pyrotechnic initiators sources from South African and Russian mining operations, exposing inflator-integrated modules to commodity price swings. Single-source vulnerability in EUV lithography equipment constrains foundry expansion timelines. Distribution runs through tier-1 system integrators for OEM direct channels, with aftermarket providers bypassing traditional mediation for fleet telematics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centralized domain controller architectures threaten to displace discrete airbag control unit value capture, forcing incumbents to defend hardware-software boundaries against zonal computing substitution.
For Market Incumbents: Harden specification authority by deepening captive foundry partnerships in Taiwan and Japan to secure ASIL-D die supply against capacity constraints. Accelerate edge AI sensor fusion R&D to embed predictive crash classification at the node before domain controller virtualization erodes hardware value. Defend against software-defined vehicle substitution by anchoring crash algorithm co-development with OEM platform teams. For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra vehicle assembly corridors offer the most penetrable geography as Bharat NCAP transitions the market from optional to mandatory fitment. Target single-stage sensor variants for economy vehicle price points where established players underinvest. Pursue direct OEM procurement relationships in commercial vehicle segments where fleet operators demand sensor data transparency. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MEMS fab capacity additions, favoring asset-light fabless designers with ISO 26262 certification expertise over captive foundry operators. Long-term viability centers on specialized sensor developers with crash algorithm IP and direct OEM channel penetration. Monitor software-defined vehicle platform announcements as inflection signal for hardware value compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Partnership | Denso Corporation anchors Japanese OEM supply chains through backward integration into semiconductor fabrication capacity. |
| Multi-Stage Sensor R&D Intensity | Continental AG sustains prototyping cycles across Stuttgart and Munich clusters for Euro NCAP 2026 compliance. |
| Direct OEM Procurement Channel | Vehicle assemblers internalizing crash algorithm development bypass tier-1 mediation for specification authority. |
| Edge AI Sensor Fusion Development | Shanghai and Shenzhen clusters prototype machine learning inference at sensor nodes for predictive deployment. |
| Bharat NCAP Localization Investment | Tamil Nadu corridors attract tier-1 module assembly for mandatory dual-front-airbag regulation compliance. |
Study Parameters
The analysis maps MEMS accelerometer, hybrid analog-digital, and pressure sensor sub-sectors, each validated through tier-1 supplier procurement leads, OEM platform engineers, automotive semiconductor foundry managers, and aftermarket telematics integrators. Primary interview insights triangulate against NHTSA Federal Motor Vehicle Safety Standards filings, Euro NCAP assessment protocol documentation, METI vehicle safety directive records, and IHS Markit vehicle production databases. Bottom-up sensor unit economics reconcile with top-down automotive electronics spend estimates.
The assumption-set framing holds NHTSA and Euro NCAP mandate timelines as fixed while varying software-defined vehicle architecture adoption rates across OEM platforms. Segmentation dimensions span sensor architecture, technology type, end-user channel, and vehicle installation category. CAGRs derive from production volume projections crossed with content-per-vehicle sensor count trajectories. Forecast inputs incorporate MEMS wafer pricing indices and palladium spot market volatility bands.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese MIIT-aligned sensor developers or hyperscaler automotive entrants would shift outcomes. Cross-checking against vehicle registration data and OEM platform launch schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market