
 Asia-Pacific Airbag Market | 2026-2036
Asia-Pacific Airbag Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airbag Market Analytics
China's GB/T vehicle safety standards on frontal and side-impact protection is hardening fitment mandates across domestic and foreign-brand assembly plants. Autoliv leverages its integrated inflator and fabric operations to anchor supply contracts with major Japanese and Korean OEMs. ZF Friedrichshafen AG sustains technology leadership through advanced multi-stage deployment algorithms. Denso Corporation competes on sensor-to-airbag system integration for Toyota and Lexus platforms.
Asia-Pacific airbag systems incorporate woven nylon or polyester cushion fabrics, sodium azide or guanidinium nitrate-based gas generants, and electronic control units processing crash sensor inputs within milliseconds to protect vehicle occupants during collisions. Frontal airbags dominate volume due to universal regulatory mandates, while curtain airbags capture expanding fitment in C-segment sedans and compact SUVs. Smart airbags represent the fastest-growing technology segment as pressure and occupant-classification sensors enable adaptive deployment force.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces occupant protection regulations that mandate dual front airbags on all new passenger vehicles. India's Automotive Research Association administers Bharat NCAP protocols that accelerate side and curtain airbag adoption in domestically produced models. South Korea's Ministry of Trade, Industry and Energy coordinates KNCAP alignment with UN ECE harmonized standards. Stakeholders must monitor how India's expanding PLI scheme for auto components reshapes local sourcing requirements versus import dependency for inflator modules.
Market Dynamics
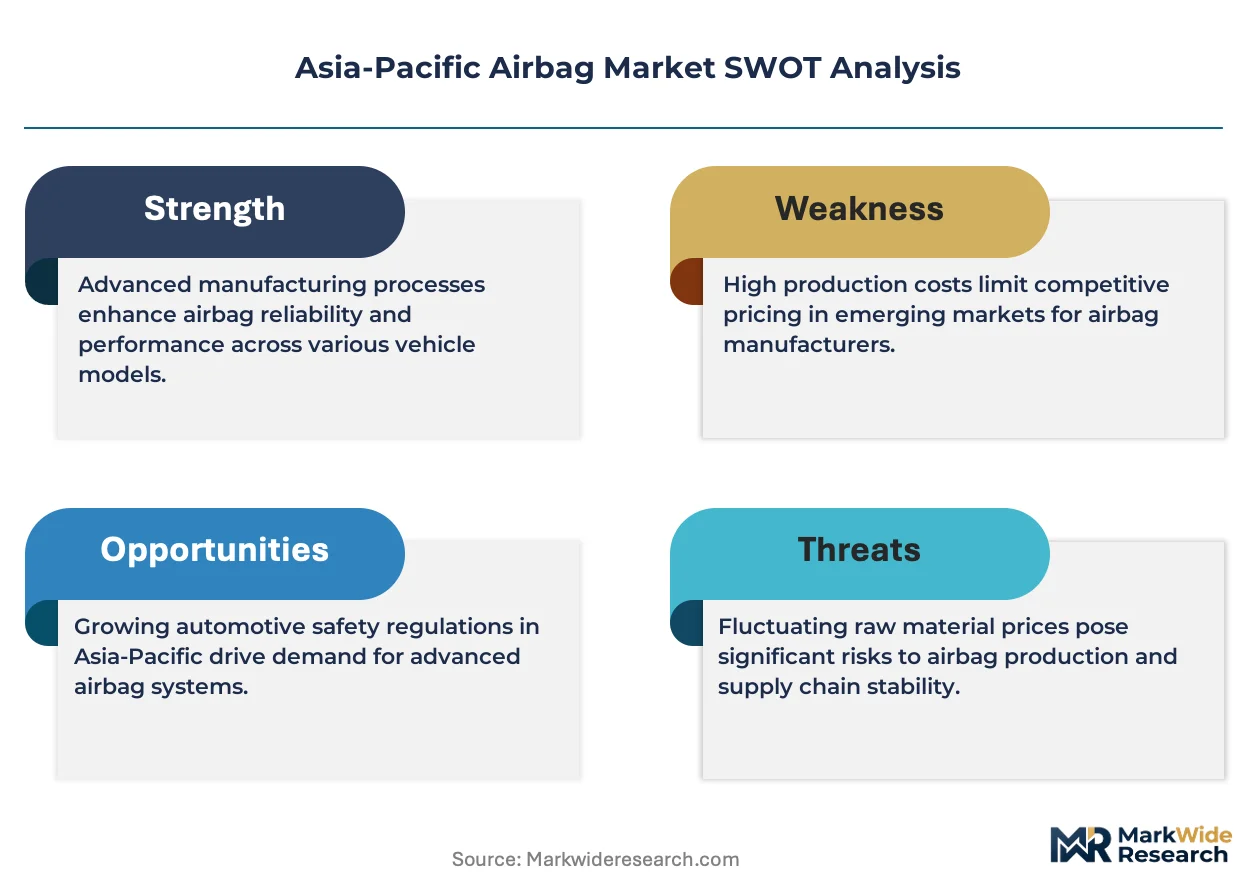
China's GB standards on occupant protection are hardening fitment mandates across domestic and foreign-brand assembly plants, forcing tier-1 suppliers to localize inflator production and sensor calibration capabilities within the eastern manufacturing corridor.
Growth Catalysts
- Bharat NCAP Protocols:India's Automotive Research Association mandates side and curtain airbag testing, accelerating adoption in domestically produced compact sedans and sub-four-meter SUVs.
- Pressure-Sensor Integration:Occupant-classification systems enable adaptive deployment force, reducing injury risk for children and small-stature adults in frontal collisions.
- Eastern China Manufacturing Corridor:Joint venture assembly plants scale multi-airbag fitment across C-segment platforms, creating concentrated demand for woven nylon cushion fabrics and electronic control units.
Market Restraints
- Sodium Azide Supply Concentration:Three Japanese chemical producers control refined gas generant output, exposing module assemblers to input cost volatility and currency fluctuation risk.
- Inflator Module Import Dependency:India's domestic supply base lacks precision metal stamping capacity for high-pressure vessel housings, forcing reliance on Korean and Taiwanese suppliers.
- Technical Limitation in Humid Climates:Guanidinium nitrate-based generants exhibit moisture sensitivity during monsoon storage, complicating inventory management for Thai and Indonesian assembly plants.
Strategic Opportunities
- PLI Scheme Localization:India's production-linked incentive program for auto components subsidizes capital equipment for inflator module manufacturing, reducing import dependency.
- Curtain Airbag Penetration in Vietnam:Underpenetrated passenger vehicle fleet and emerging NCAP-aligned safety protocols create whitespace for side-impact protection systems in locally assembled MPVs.
- Sensor-to-Deployment Convergence:Integration of radar and camera pre-crash sensing with multi-stage inflation algorithms enables predictive deployment milliseconds before physical impact.
Industry Challenges
- Embedded Software Certification:Functional safety validation under ISO 26262 for airbag control unit algorithms extends development timelines by eight to fourteen months.
- Legacy Platform Integration:Retrofitting advanced occupant-classification systems into existing vehicle architectures requires harness redesign and supplemental sensor mounting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airbag Market |
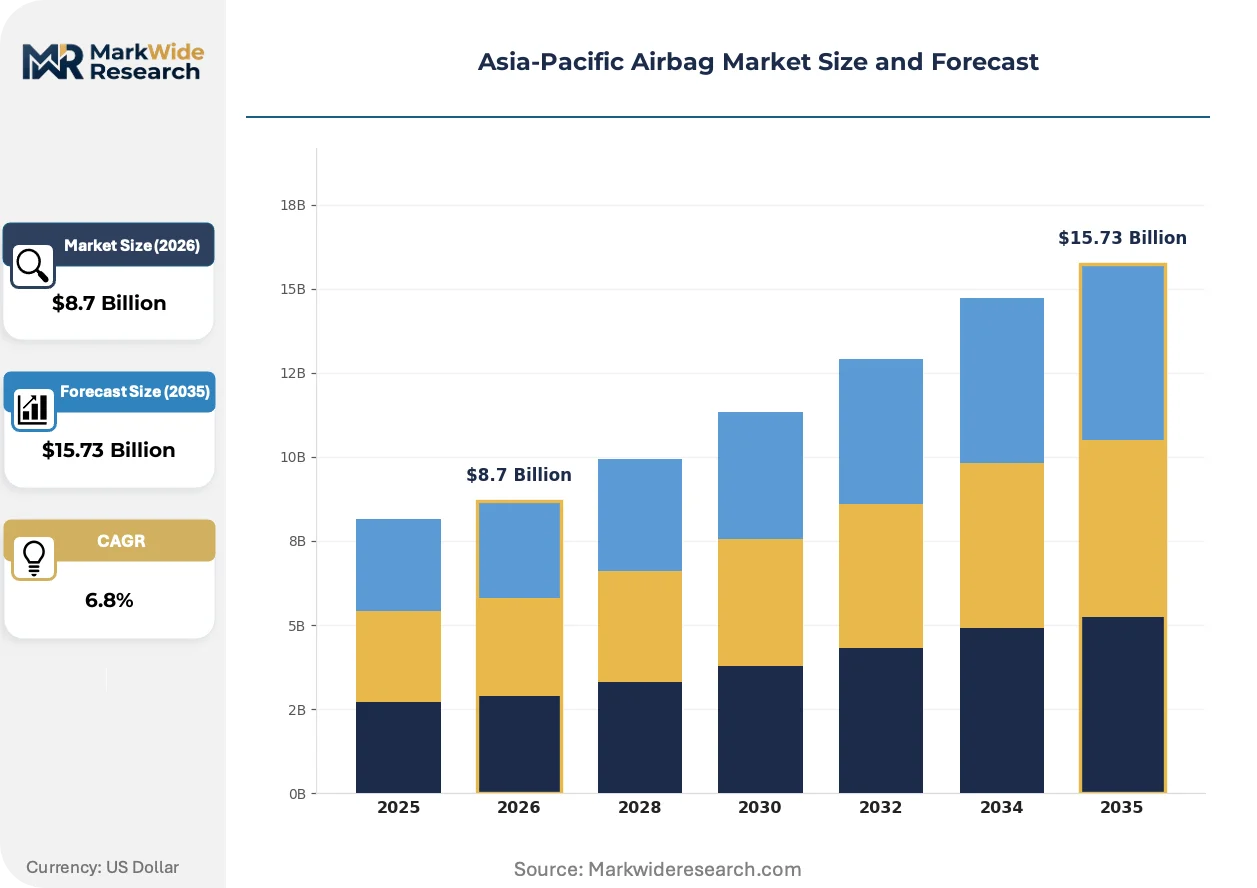
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles Technology: Smart Airbags, Deployable Airbags, Hybrid Airbags, Multi-Stage Airbags Installation Type: OEM Installation, Aftermarket Installation, Retrofit Installation, Custom Installation |
| Companies Covered | Autoliv, ZF Friedrichshafen AG, Continental AG, Denso Corporation, Hyundai Mobis, Toyoda Gosei, Robert Bosch GmbH, Joyson Safety Systems, Key Safety Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airbag Market Evolving Landscape
Adaptive deployment technologies are compressing the performance gap between premium and mid-range safety systems, while regulatory harmonization across East Asian economies accelerates specification standardization.
Smart airbag systems incorporating pressure-sensitive occupant detection and multi-stage inflation control are expanding into mass-market C-segment sedans and compact SUVs. Chinese domestic OEMs and Korean joint ventures adopt these configurations two to three model years faster than previous technology cycles. The shift is compressing pricing premiums for adaptive deployment, forcing suppliers to differentiate through sensor integration depth rather than hardware sophistication alone.
South Korea's Ministry of Trade, Industry and Energy coordinates KNCAP alignment with UN ECE harmonized standards, eliminating technical barriers for component sourcing across Japanese, Korean, and Chinese assembly networks. The convergence reduces redundant homologation testing for multi-regional suppliers. Tier-1 module producers now engineer single-specification inflator units certifiable across Japan, South Korea, and China, compressing variant complexity and inventory carrying costs.
Fleet procurement of safety systems is consolidating around integrated sensor-airbag packages rather than discrete component sourcing. Japanese and Korean OEMs specify complete occupant protection modules from single suppliers, displacing multi-vendor assembly relationships. The pattern concentrates contract value with system integrators possessing captive inflator, fabric, and electronics capabilities, most visible in Toyota and Hyundai platform sourcing decisions.
Asia-Pacific Airbag Market Segmentation
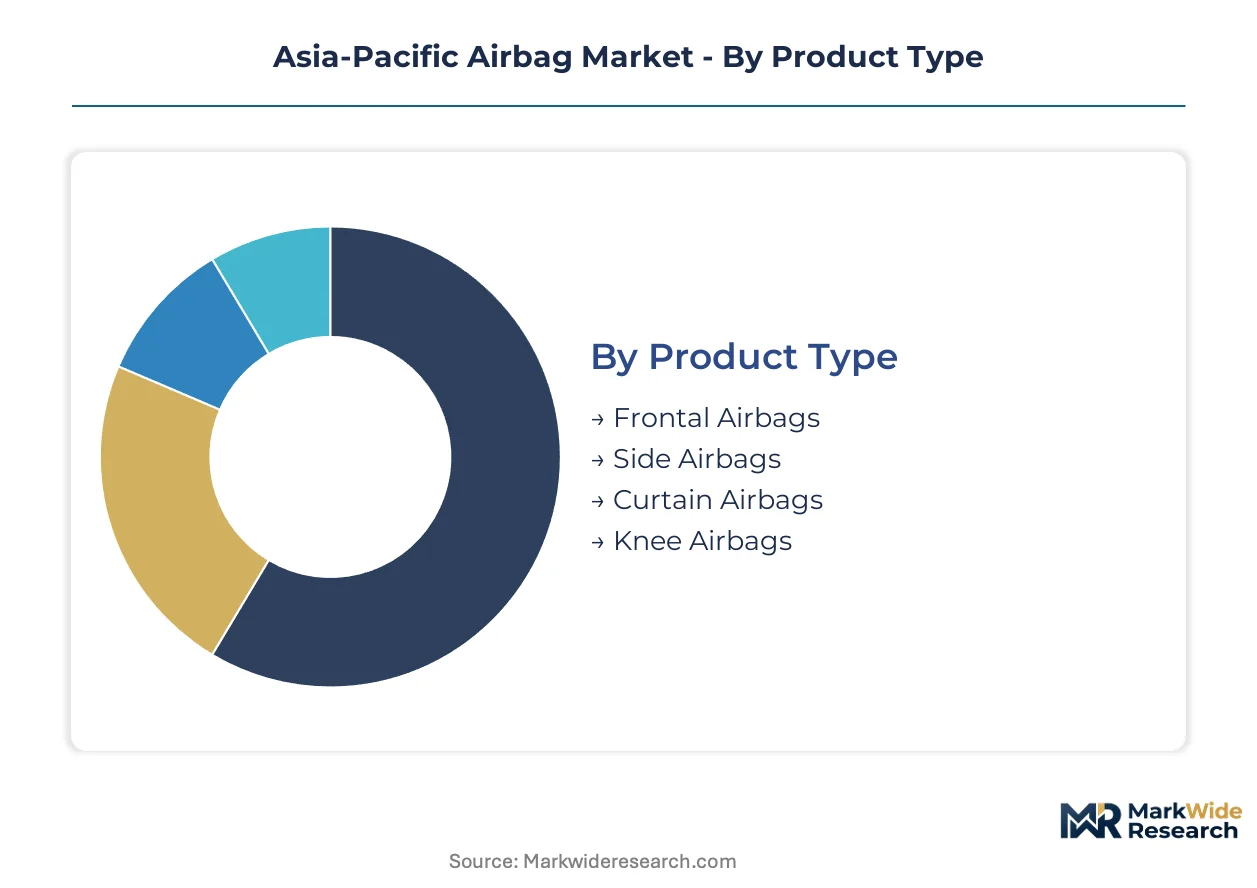
Segmentation reveals where capital deployment concentrates and which configurations command technology premiums. Supplier positioning and manufacturing footprint decisions flow directly from these structural divisions.
Product Type:
Capital intensity peaks with curtain airbag systems requiring woven fabric integration across roofline architectures, while frontal units benefit from scale economies in high-volume assembly.
- Frontal Airbags:Dual-chamber cushion designs using coated nylon 6,6 fabric dominate fitment mandates across China's GB standard-compliant production. India's Bharat NCAP frontal impact protocols lock in baseline demand for driver and passenger positions in compact sedans assembled near Chennai and Pune.
- Curtain Airbags:Extended-coverage side curtain systems demand precision folding and torsional rigidity engineering for rollover protection. Korean OEMs specify these for C-segment crossovers manufactured at Hyundai Motor's Asan and Beijing facilities, with fitment accelerating under KNCAP side-pole testing requirements.
- Side Airbags:Seat-mounted thorax protection modules integrate with occupant classification sensors in Toyota and Honda platforms.
- Knee Airbags:Lower dash-integrated units address femur load reduction in premium sedan architectures.
Most installed capacity flows through Frontal Airbags. Expansion is steepest in Curtain Airbags.
End User:
Application requirements diverge sharply between occupant-dense passenger configurations and durability-focused commercial specifications.
- Passenger Vehicles:Multi-point protection systems integrating frontal, side, and curtain modules represent the dominant revenue concentration. Japanese OEMs mandate complete occupant protection suites for all domestic market sedans and hatchbacks under MLIT regulations.
- Commercial Vehicles:Cab-integrated driver airbags face slower adoption due to cost sensitivity in fleet procurement across India's light commercial vehicle segment. Fitment concentrates in premium cab-over-engine trucks serving express logistics routes between Mumbai and Delhi.
- Two-Wheelers:Motorcycle airbag vests and jacket-integrated systems remain nascent, with limited homologation pathways.
- Off-Road Vehicles:Rollover-optimized curtain systems address side-impact risk in agricultural and construction equipment operating in Australia's mining corridors.
Passenger Vehicles absorb the majority of module output. Two-Wheelers present the longest development runway.
Technology:
Intelligence integration separates premium positioning from commodity supply, with algorithm sophistication determining contract value.
- Smart Airbags:Pressure-sensitive occupant detection and adaptive deployment force modulation enable child and small-stature protection. Chinese domestic OEMs BYD and Geely have compressed adoption timelines, specifying these systems two to three model years faster than previous technology cycles in mid-range EV platforms.
- Multi-Stage Airbags:Dual-threshold inflator control reduces injury severity through graduated pressure release. Korean joint ventures deploy these across Hyundai-Kia's K2 and K3 platform derivatives manufactured at Beijing Hyundai and Dongfeng Yueda Kia facilities.
- Hybrid Airbags:Combined pyrotechnic and stored gas generant architectures address extreme climate performance requirements.
- Deployable Airbags:External pedestrian protection systems remain pre-commercial, with regulatory pathways under development.
Smart Airbags command the steepest technology premium. Multi-Stage Airbags scale fastest across mass-market production.
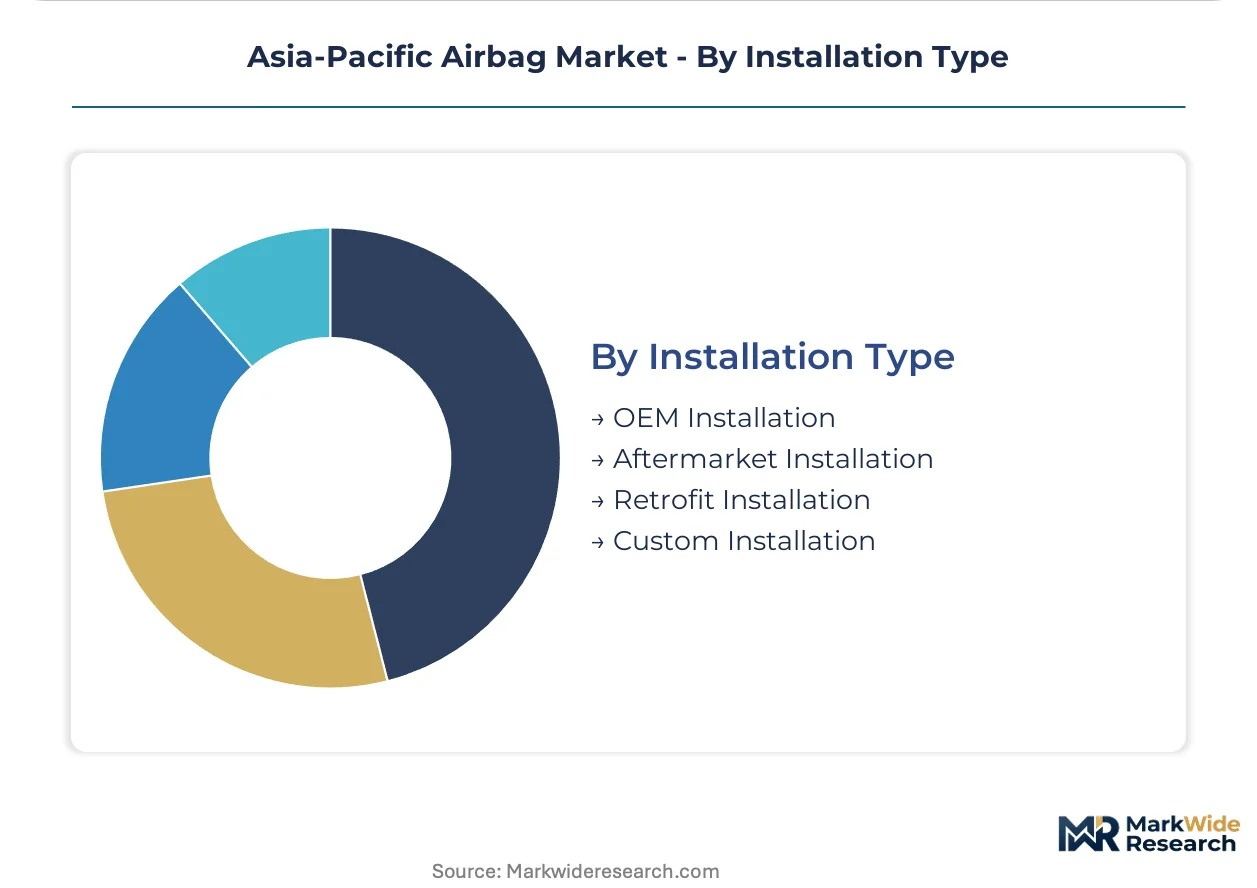
Installation Type:
Channel economics favor captive OEM supply relationships, with aftermarket and retrofit segments constrained by calibration complexity and liability exposure.
- OEM Installation:Factory-integrated module assembly with ECU-coded deployment algorithms locks in multi-year supply contracts. Toyota and Lexus platforms source complete sensor-to-airbag systems from single-tier integrators, displacing multi-vendor relationships.
- Aftermarket Installation:Post-production fitment faces ISO 26262 functional safety validation barriers and harness incompatibility with legacy vehicle architectures. Activity concentrates in Australia's specialist 4x4 modification sector for rollover protection upgrades.
- Retrofit Installation:Older fleet upgrades require supplemental sensor mounting and control unit reprogramming, extending installation timelines.
- Custom Installation:Low-volume specialty vehicle applications demand bespoke cushion geometry and mounting bracket engineering.
OEM Installation channels carry the highest contract value concentration. Aftermarket Installation faces the steepest regulatory barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered automotive airbag technology in the 1970s through domestic supplier development for Toyota and Nissan platforms. This engineering heritage established quality benchmarks that shaped regional procurement standards across East Asian manufacturing networks.
China
Domestic OEMs BYD and Geely specify smart airbag systems for mid-range EV platforms at compressed adoption timelines. GB standards on occupant protection harden fitment mandates across joint venture assembly plants in the eastern manufacturing corridor. Shanghai and Jiangsu province facilities scale multi-airbag production for C-segment sedans and compact SUVs.
India
Bharat NCAP protocols accelerate side and curtain airbag adoption in domestically produced compact sedans and sub-four-meter SUVs. The PLI scheme for auto components subsidizes capital equipment for inflator module manufacturing. Chennai and Pune assembly corridors concentrate demand for woven nylon cushion fabrics and electronic control units.
Japan
MLIT regulations mandate dual front airbags on all new passenger vehicles, locking in baseline demand for driver and passenger positions. Toyota and Lexus platforms source complete sensor-to-airbag systems from single-tier integrators. Kanto and Nagoya industrial clusters anchor precision metal stamping and sensor calibration capabilities.
South Korea
KNCAP alignment with UN ECE harmonized standards eliminates technical barriers for component sourcing across East Asian networks. Hyundai-Kia specify multi-stage airbags across K2 and K3 platform derivatives manufactured at Asan and Beijing facilities. Busan-Ulsan corridor concentrates inflator module assembly and woven fabric integration.
Vietnam
Underpenetrated passenger vehicle fleet and emerging NCAP-aligned safety protocols create whitespace for side-impact protection systems. Locally assembled MPVs face accelerating curtain airbag fitment requirements from regional OEM joint ventures. Hanoi and Ho Chi Minh City manufacturing zones attract module assembly investment from Korean and Japanese suppliers.
Asia-Pacific Airbag Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific airbag value chain. Integrated module assemblers with captive inflator and fabric operations command premium contract positions against component-specialized vendors. Three strategic archetypes dominate: system integrators delivering complete sensor-to-deployment packages, inflator specialists controlling gas generant chemistry, and electronics providers processing crash sensor inputs. Competitive moves concentrate on backward integration into gas generant production and geographic expansion through joint venture localization.
Within the integrated system tier, Autoliv and ZF Friedrichshafen AG exemplify capital-intensive positioning through combined inflator, fabric, and electronics capabilities. Denso Corporation occupies a distinct anchor position in sensor-to-airbag integration for Japanese OEM platforms. These three entities represent the structural concentration of contract value with suppliers possessing end-to-end occupant protection module engineering.
| Leading Market Players |
|---|
| Autoliv |
| ZF Friedrichshafen AG |
| Continental AG |
| Denso Corporation |
| Hyundai Mobis |
| Toyoda Gosei |
| Robert Bosch GmbH |
| Joyson Safety Systems |
| Key Safety Systems |
| Others |
Value Network & Pricing Analysis
Sodium azide and guanidinium nitrate gas generants flow from Japanese chemical refiners through tier-1 module assemblers to OEM pricing tiers, with raw material concentration in East Asia compressing margins at the commodity end while smart airbag integration commands technology premiums upstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates adaptive smart airbag systems from multi-stage and baseline frontal configurations. Price differentiation hinges on ISO 26262 certification grade and sensor integration depth, with Chinese domestic OEMs squeezing mid-tier suppliers through accelerated adoption timelines. Cost compression in economy frontal modules intensifies because sodium azide supply concentration exposes assemblers to currency fluctuation risk. Fleet procurement teams at Indian commercial vehicle manufacturers exhibit highest price sensitivity, while Japanese luxury platforms absorb premium sensor-to-airbag packages with minimal negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota, Hyundai-Kia, and BYD platform engineering teams, bypassing distributor markups for multi-year contract security. Manufacturing gravity centers on China, Japan, and South Korea, with inflator module assembly drawing from Korean and Taiwanese precision metal stamping for high-pressure vessel housings. Raw material dependencies rest on Japanese sodium azide refiners, Chinese woven nylon 6,6 fabric mills, and Korean electronic control unit foundries. Single-source vulnerability in gas generant chemistry exposes tier-1 suppliers to input cost volatility during yen appreciation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific airbag market functions as a stable compounder, with regulatory mandates across China, India, and Japan ensuring replacement-cycle demand regardless of macroeconomic volatility.
For Market Incumbents: Anchor contract renewals through captive inflator production in the eastern China manufacturing corridor, defending against emerging Korean electronics specialists seeking sensor-to-airbag integration roles. Backward integration into guanidinium nitrate generant chemistry reduces exposure to Japanese chemical producer pricing power. Capacity addition in Chennai and Pune assembly zones captures PLI scheme subsidies before local content requirements harden.
For New Entrants and Emerging Players: Bharat NCAP protocols in India open a window for curtain airbag specialists to penetrate the sub-four-meter SUV segment where incumbent coverage remains thin. Vietnam's emerging NCAP-aligned safety protocols create whitespace for side-impact protection systems in locally assembled MPVs. A go-to-market angle targeting Korean-Japanese joint venture procurement committees with single-specification inflator units certifiable across KNCAP, GB, and MLIT standards accelerates qualification timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where tier-2 module assemblers lack captive gas generant production and face elimination from Toyota and Hyundai single-source procurement policies. The five-to-ten year viability window favors integrated system providers with sensor calibration and fabric weaving capabilities under one roof. Acquisition targets include mid-cap inflator specialists in Busan-Ulsan possessing UN ECE harmonized certification but limited OEM channel access. The signal to watch is KNCAP-GB standard convergence completion, which will trigger procurement consolidation toward dual-certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Inflator Module Localization | PLI scheme subsidies in India reduce import dependency for high-pressure vessel housings. |
| Sensor-to-Deployment Integration | Radar and camera pre-crash sensing convergence enables predictive deployment algorithms for premium platforms. |
| Single-Specification Certification | KNCAP-GB-MLIT harmonization eliminates redundant homologation testing across Japanese, Korean, and Chinese assembly networks. |
| Smart Airbag Platform Standardization | BYD and Geely compressed adoption timelines force margin compression across mid-range EV production. |
| Occupant Classification R&D Investment | Pressure-sensitive detection systems address Bharat NCAP child protection protocols in compact sedan architectures. |
Research Methodology
Coverage spans China, India, Japan, South Korea, and Vietnam, with primary inputs from each market's manufacturing corridor. Primary interviews with tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distributors combined with secondary validation from vehicle production databases, IHS Markit registration data, and national NCAP protocol documentation. Bottom-up triangulation across inflator module shipment volumes and top-down reconciliation against OEM fitment rates anchored value estimates.
Rate-of-change decomposition across the analysis window separates volume growth from content-per-vehicle expansion and pricing tier migration. Segmentation dimensions modeled include product type, vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from regression analysis against regulatory mandate implementation schedules and platform refresh cycles, with specific inputs from GB standard compliance timelines and Bharat NCAP phase-in requirements.
Revisions become necessary when sodium azide supply disruptions, PLI scheme eligibility modifications, or KNCAP-GB harmonization delays materialize beyond base case assumptions. Forecasts reflect documented assumptions regarding joint venture production scaling and domestic OEM technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market