
 Biometric Driver Identification System Market | 2026-2036
Biometric Driver Identification System Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Driver Identification System Market Intelligence
Germany is rewriting competitive dynamics in automotive biometric hardware through concentrated R&D investment and Tier 1 supplier density. NEC Corporation leverages deep learning-based facial recognition algorithms to sustain technology leadership in fleet authentication systems. IDEMIA anchors European market access through its certified biometric enrollment platforms and partnerships with major automotive OEMs.
Biometric driver identification systems integrate physiological sensors and pattern-matching algorithms to verify operator identity through fingerprint ridges, iris structures, or facial geometry, typically operating with false acceptance rates below 0.001% in commercial automotive deployments. The technology prevents unauthorized vehicle access, enables personalized cabin settings, and supports real-time drowsiness detection through ocular tracking. Fingerprint recognition dominates current automotive integration due to mature sensor miniaturization and established supply chains, while facial recognition captures expanding share in premium vehicle segments where contactless authentication enhances user experience. Cloud-based deployment architectures are gaining traction among ride-hailing services and logistics fleets seeking centralized driver credential management across dispersed vehicle pools.
The European Union's General Safety Regulation and the U.S. NHTSA drowsiness detection guidelines are mandating driver monitoring capabilities in new vehicle categories, directly expanding addressable hardware demand. Japan's METI safety standards and South Korea's MFDS automotive biometrics certification frameworks add compliance layers for suppliers seeking multi-market access. Stakeholders must weigh hardware-versus-software margin trajectories as over-the-air biometric updates reduce replacement cycles for embedded sensors.
Market Dynamics
Fleet operators are consolidating biometric procurement around integrated driver monitoring platforms that combine authentication with fatigue detection, compressing vendor selection cycles and favoring suppliers with multi-sensor fusion capabilities.
Growth Catalysts
- EU General Safety Regulation:Mandates driver monitoring systems in new vehicle categories, forcing OEMs to embed biometric hardware during platform design phases rather than as aftermarket add-ons.
- Cloud-based credential management:Ride-hailing and logistics fleets are adopting centralized driver enrollment across dispersed vehicle pools, reducing per-unit authentication costs and enabling real-time access revocation.
- Germany's Tier 1 supplier density:Continental AG and Robert Bosch GmbH anchor production clusters that accelerate R&D feedback loops and shorten OEM qualification timelines for automotive-grade biometric modules.
Market Restraints
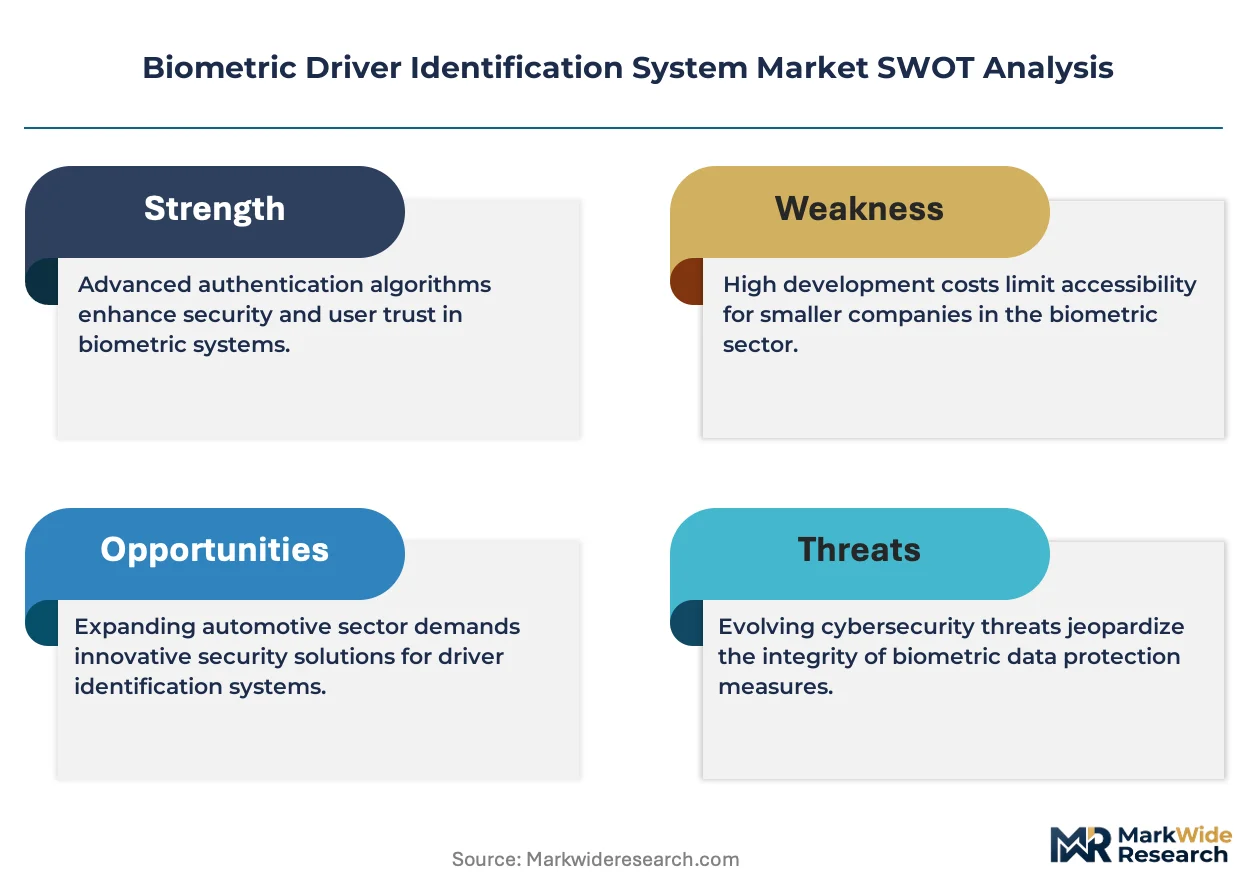
- Automotive-grade sensor cost premiums:Fingerprint and iris sensors meeting AEC-Q100 reliability standards command input costs that constrain adoption in economy vehicle segments.
- False acceptance rate thresholds:Commercial deployments require sub-0.001% FAR performance, demanding algorithmic refinement that extends development cycles and certification timelines.
- Data privacy compliance layering:GDPR in Europe and patchwork state-level biometric laws in the US create jurisdictional friction for cross-border fleet deployments.
Strategic Opportunities
- India's commercial vehicle safety mandates:The country's national automotive regulator is evaluating driver monitoring requirements for heavy-duty fleets, opening a large underpenetrated addressable base.
- Facial-recognition-plus-ocular-tracking fusion:Convergence of contactless authentication with drowsiness detection enables premium pricing in luxury vehicle segments where user experience differentiation commands priority.
- Over-the-air biometric updates:Software-defined authentication architectures reduce sensor replacement cycles and create recurring revenue streams through subscription-based algorithm licensing.
Industry Challenges
- Embedded systems integration complexity:Biometric modules must interface with legacy CAN bus architectures and emerging zonal E/E platforms simultaneously, multiplying validation matrices for Tier 1 suppliers.
- Functional safety certification timelines:ISO 26262 ASIL-B compliance for driver monitoring systems extends qualification periods, compressing window for design-in wins on upcoming vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Driver Identification System Market |
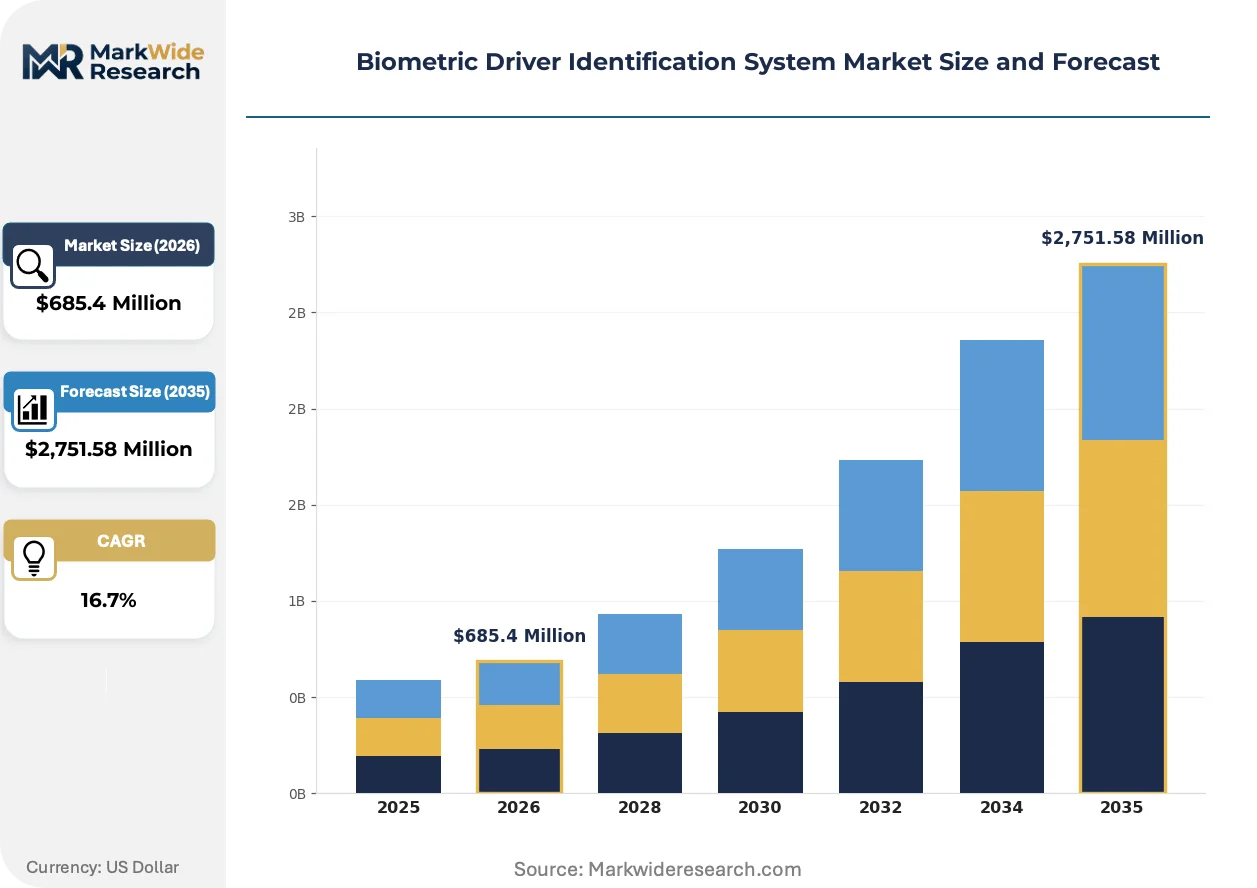
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,751.58 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Fleet Management, Vehicle Access Control, Driver Monitoring, Insurance End User: Logistics Companies, Ride-hailing Services, Public Transport, Car Rentals Deployment: On-premises, Cloud-based, Hybrid, Mobile |
| Companies Covered | NEC Corporation, IDEMIA, Thales Group, Continental AG, Robert Bosch GmbH, Denso Corporation, Fingerprint Cards AB, Synaptics Incorporated, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Driver Identification System Market Strategic Shifts & Innovations
Algorithmic advancement and regulatory mandates are converging to transform biometric systems from standalone authentication devices into integrated safety platforms that reshape OEM procurement specifications.
Deep learning-based facial recognition is digitizing driver identity verification through neural network architectures that process 3D facial geometry in real-time. Premium vehicle manufacturers are embedding these systems in steering column modules and rearview mirror housings. The technology is digitizing cabin personalization workflows by linking biometric signatures to seat position, climate preference, and infotainment profiles without driver intervention.
Europe's General Safety Regulation is mandating driver drowsiness and distraction monitoring as standard equipment in passenger cars and light commercial vehicles from mid-decade. The regulation forces Tier 1 suppliers to redesign interior sensing architectures around camera-based monitoring rather than steering torque or lane departure proxies. Heavy-duty truck OEMs in Germany and France are accelerating platform refreshes to comply ahead of enforcement deadlines.
Fleet operators are consolidating vendor relationships around full-stack biometric platform providers capable of unified enrollment, device management, and compliance reporting. This concentration displaces point-solution suppliers lacking cloud infrastructure or multi-sensor portfolios. The shift is most visible in North American logistics networks where dispersed vehicle pools demand centralized credential administration across state boundaries.
Biometric Driver Identification System Market Segmentation
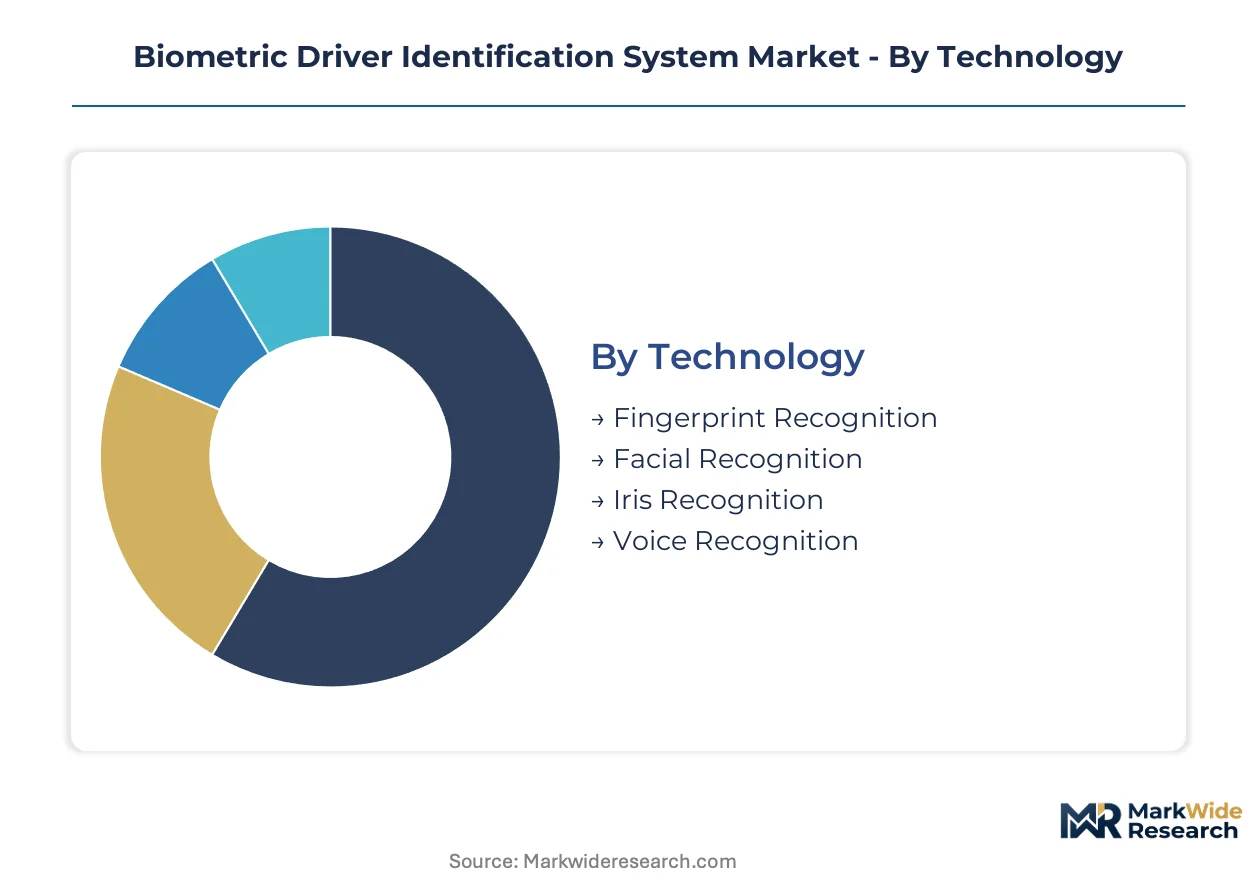
Technology choice dictates sensor cost, integration complexity, and regulatory compliance pathways for automotive biometric deployments. Application focus determines whether vendors optimize for real-time safety monitoring or identity verification workflows.
Technology:
Cost tier determines hardware margins and OEM design-in probability across vehicle segments.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture ridge patterns with mature AEC-Q100 qualification pathways. Logistics fleets in Germany and the US consolidate procurement around fingerprint modules for economy vehicle retrofits where unit cost sensitivity dominates specification decisions.
- Facial Recognition:Deep learning algorithms process 3D facial geometry through infrared and RGB camera arrays. Premium vehicle manufacturers in Japan embed steering-column modules enabling contactless authentication combined with drowsiness detection, commanding higher per-unit pricing through multi-function integration.
- Iris Recognition:Near-infrared imaging targets high-security applications with superior false acceptance rates.
- Voice Recognition:Speaker identification algorithms leverage cabin microphone arrays for hands-free authentication.
Fingerprint Recognition holds installed capacity. Facial Recognition is rotating up the share rankings.
Application:
End-use workflow determines whether biometric systems authenticate identity, monitor physiological state, or enforce access permissions.
- Fleet Management:Centralized credential administration across dispersed vehicle pools enables real-time driver authorization and trip logging. Ride-hailing operators in South Korea deploy cloud-linked facial recognition to satisfy MFDS certification while streamlining driver onboarding across metropolitan service territories.
- Vehicle Access Control:Biometric substitution for key fobs and PIN codes eliminates credential sharing and theft vectors. Car rental agencies at Frankfurt Airport anchor European adoption, replacing physical key handoffs with fingerprint enrollment kiosks that compress transaction times.
- Driver Monitoring:Ocular tracking and head pose estimation detect fatigue and distraction for safety compliance.
- Insurance:Verified driver identity links operating behavior to policy pricing and claims adjudication.
Fleet Management holds installed capacity. Vehicle Access Control is climbing the fastest.
End User:
Customer type shapes deployment scale, integration urgency, and procurement centralization patterns.
- Logistics Companies:Long-haul trucking fleets mandate biometric authentication for hours-of-service compliance and cargo security. US-based operators face NHTSA drowsiness detection guidelines while managing driver turnover that demands rapid credential provisioning across interstate routes.
- Ride-hailing Services:Platform economics favor contactless facial recognition that minimizes vehicle downtime between driver shifts. Operators in India evaluate driver monitoring mandates from the national automotive regulator as they scale fleet coverage across tier-2 and tier-3 cities.
- Public Transport:Municipal bus and rail operators pilot biometric access for operator cabins and fare collection.
- Car Rentals:Airport and urban location networks seek frictionless handoff experiences.
Logistics Companies hold installed capacity. Ride-hailing Services is gaining share fastest.
Deployment:
Architecture selection trades data sovereignty against operational flexibility and lifecycle cost.
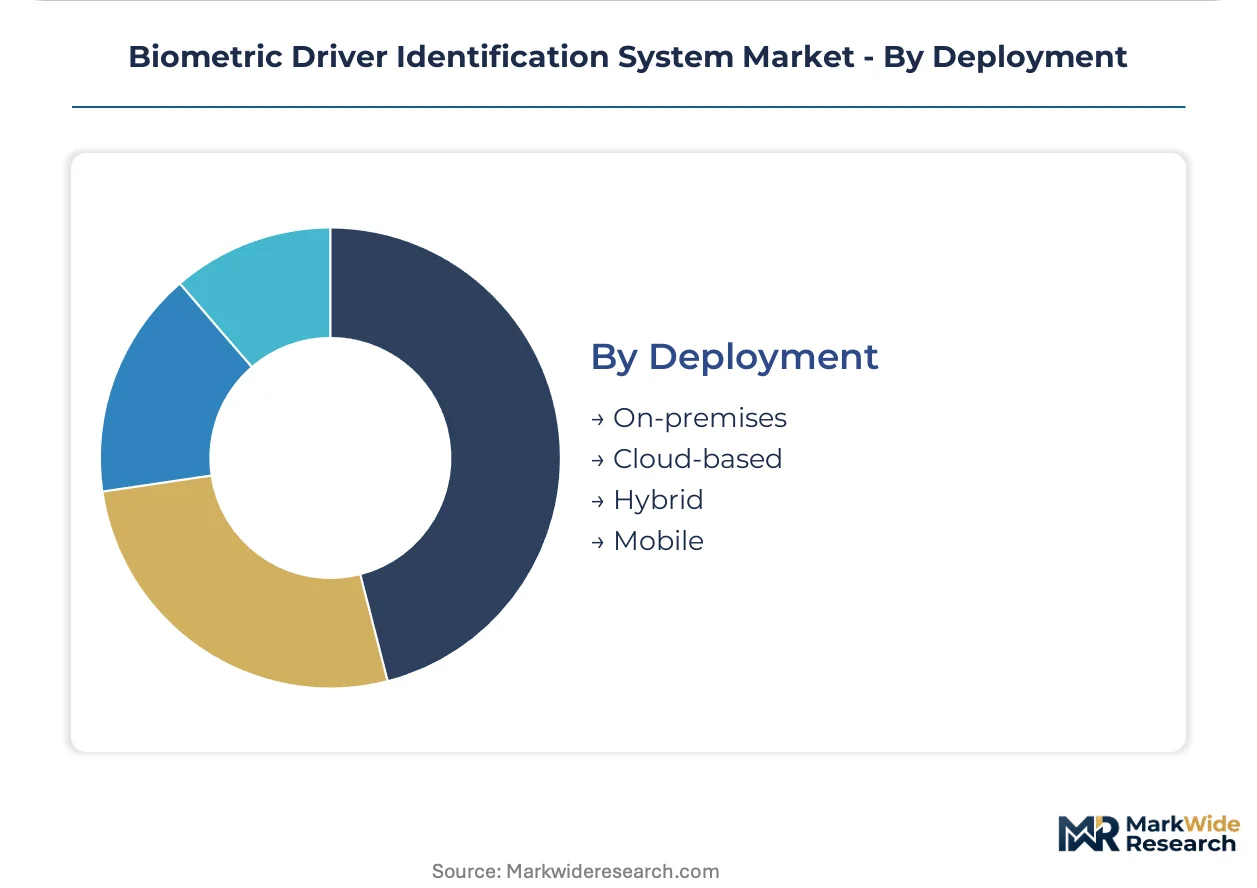
- Cloud-based:Centralized enrollment and algorithm updates reduce edge hardware replacement cycles. European logistics networks adopt cloud architectures to satisfy GDPR data residency requirements while enabling cross-border fleet administration under unified credential stores.
- On-premises:Local biometric processing eliminates network dependency and latency for authentication decisions. Japanese commercial vehicle manufacturers prefer edge-based facial recognition to satisfy METI safety standards without exposing driver biometric templates to external infrastructure.
- Hybrid:Split processing balances real-time response with centralized analytics.
- Mobile:Smartphone-based biometric verification extends authentication to temporary or occasional drivers.
On-premises holds installed capacity. Cloud-based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier 1 suppliers anchor biometric hardware production clusters that feed OEM procurement networks across multiple continents. Component manufacturing concentrates in Stuttgart and Ingolstadt corridors where sensor qualification timelines compress through co-located R&D facilities.
United States
Logistics operators deploy fingerprint modules for hours-of-service compliance across interstate trucking routes. NHTSA drowsiness detection guidelines mandate driver monitoring capabilities in commercial vehicle categories. Michigan-based engineering centers prototype multi-sensor fusion architectures for Detroit OEM platform integration.
Germany
Continental AG and Robert Bosch GmbH manufacture automotive-grade biometric sensors for European OEM qualification programs. The EU General Safety Regulation mandates driver monitoring systems in new passenger cars and light commercial vehicles. Bavarian production clusters accelerate AEC-Q100 certification cycles through integrated testing facilities.
Japan
Commercial vehicle manufacturers embed edge-based facial recognition to satisfy METI safety standards without external data exposure. Deep learning algorithm providers license neural network architectures to steering-column module integrators. Nagoya engineering corridors specialize in infrared camera arrays for cabin-mounted monitoring systems.
South Korea
Ride-hailing operators scale cloud-linked facial recognition across metropolitan service territories under MFDS automotive biometrics certification. Domestic semiconductor fabricators supply image signal processors for camera-based authentication modules. Seoul-based fleet management platforms centralize driver enrollment across dispersed vehicle pools.
India
Platform operators evaluate driver monitoring mandates from the national automotive regulator as they expand fleet coverage into tier-2 and tier-3 cities. Commercial vehicle safety regulations under review would create mandatory biometric authentication requirements for heavy-duty trucking segments. Tamil Nadu automotive corridors attract component sourcing for economy vehicle retrofit programs.
Biometric Driver Identification System Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying qualified sensors and algorithm licenses. Market structure tilts toward consolidation as fleet procurement concentrates around full-stack providers with cloud infrastructure and multi-sensor portfolios. Three archetypes dominate: Tier 1 automotive suppliers with OEM design-in relationships, biometric algorithm specialists licensing neural network architectures, and semiconductor fabricators producing AEC-Q100 qualified image sensors. Competitive dynamics revolve around strategic partnerships for sensor-algorithm integration and geographic expansion into emerging mandate jurisdictions.
Within the Tier 1 integration tier, Continental AG and Robert Bosch GmbH exemplify the automotive-grade hardware archetype through German production clusters. NEC Corporation occupies a position representing deep learning-based algorithm specialists, while IDEMIA anchors the certified enrollment platform segment for OEM compliance workflows.
| Leading Market Players |
|---|
| NEC Corporation |
| IDEMIA |
| Thales Group |
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Fingerprint Cards AB |
| Synaptics Incorporated |
| Harman International |
| Others |
Cost & Logistics Intelligence
AEC-Q100 certification bottlenecks determine both pricing tier spreads and supply chain shape by forcing Tier 1 suppliers to absorb extended validation costs while OEMs negotiate volume discounts for multi-platform design-ins. This regulatory chokepoint compresses margins on economy-grade fingerprint modules while enabling premium pricing for facial recognition systems with integrated drowsiness detection.
Pricing Analysis
The EU General Safety Regulation dictates the pricing tier structure by mandating driver monitoring capabilities as baseline equipment, eliminating economy-tier exemptions previously available to volume manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified multi-sensor fusion platforms from single-modality authentication modules and aftermarket retrofit kits. Cost compression in economy vehicle segments is intensifying because logistics fleet procurement concentrates around integrated platforms that bundle authentication with compliance reporting. Ride-hailing operators exhibit lowest price sensitivity due to platform economics favoring contactless facial recognition that minimizes vehicle downtime, while independent trucking contractors face acute cost pressure from thin operating margins.
Supply Chain Analysis
Near-infrared image sensors and neural network accelerator chips feed from concentrated fabrication capacity in Taiwan, South Korea, and Japan. German production clusters in Stuttgart and Ingolstadt anchor final module assembly, drawing from Taiwanese CMOS sensor foundries and South Korean memory suppliers for edge-based processing architectures. Single-source vulnerability around automotive-grade infrared emitters creates exposure to regional logistics disruptions. Distribution runs through Tier 1 supplier direct channels to OEM platform engineering teams, with aftermarket sales compressing through fleet management platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric driver identification is crossing into platform economics where fleet-scale enrollment ecosystems and cross-OEM interoperability standards determine competitive survival. The shift from standalone hardware sales to recurring algorithm licensing hinges on cloud-native architectures that centralize credential administration across dispersed vehicle pools.
For Market Incumbents: Build switching-cost moats through embedded integration into zonal E/E architectures that multiply replacement complexity for rival systems. Continental AG and Robert Bosch GmbH should deepen backward integration into infrared sensor fabrication to secure supply during automotive semiconductor allocation cycles. NEC Corporation must accelerate ISO 26262 ASIL-B certification for next-generation facial recognition modules before platform design-in windows close on upcoming vehicle architectures. For New Entrants and Emerging Players: Pursue white-space penetration in India's commercial vehicle retrofit segment where regulatory mandates are crystallizing but qualified supplier density remains thin. Target cloud-based credential management for mid-size logistics fleets seeking alternatives to Tier 1 supplier minimum order quantities. A software-first go-to-market angle that decouples algorithm licensing from hardware procurement bypasses capital-intensive sensor manufacturing barriers. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors algorithm specialists with automotive-grade certification pipelines over hardware-locked component vendors. Long-term viability centers on recurring revenue models where over-the-air biometric updates reduce sensor replacement cycles and create subscription attach rates. Acquisition targets should demonstrate MFDS or METI pre-certification progress and existing OEM pilot programs. Watch for enforcement deadline clarity on India's national automotive regulator driver monitoring proposals as the inflection signal for capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Development | Combines fingerprint, facial, and ocular modalities to satisfy EU General Safety Regulation mandates with single-supplier accountability. |
| Cloud-Native Credential Infrastructure | Enables ride-hailing operators like those in South Korea to centralize driver enrollment across metropolitan service territories under MFDS certification. |
| Backward Integration into Infrared Sensing | Secures supply of AEC-Q100 qualified emitters for cabin-mounted monitoring systems amid automotive semiconductor allocation constraints. |
| Over-the-Air Algorithm Licensing Model | Transforms one-time hardware sales into recurring revenue streams through subscription-based biometric template updates. |
| India Market Pre-Positioning | Establishes supplier relationships ahead of national automotive regulator mandates for heavy-duty fleet driver monitoring. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, fleet operations managers at logistics networks, and ride-hailing platform technical leads. Secondary validation drew from NHTSA drowsiness detection guideline filings, EU General Safety Regulation implementation timelines, MFDS automotive biometrics certification databases, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down market envelope estimates from automotive semiconductor trade flows.
Calibration anchored on historical biometric sensor shipment volumes and OEM platform design-in announcements across the projection horizon. Segmentation dimensions modeled include recognition modality, vehicle class integration tier, deployment architecture, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves that weight mandate enforcement schedules against fleet replacement cycles. Industry-specific inputs encompassed AEC-Q100 qualification timeline distributions and cloud infrastructure penetration rates among commercial vehicle operators.
Sensitivities concentrate around regulatory enforcement delays, automotive semiconductor allocation disruptions, and GDPR-derived data residency requirements that fragment cloud architecture economics. Cross-checking against IHS Markit vehicle production forecasts and automotive electronics bill-of-materials trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market