
 Germany Traffic Sign Recognition Market | 2026-2036
Germany Traffic Sign Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Traffic Sign Recognition Market Foresight
Fleet procurement across German logistics providers and ride-sharing operators is broadening the customer base beyond traditional automotive OEMs. Continental AG leverages its integrated sensor-to-software stack to dominate embedded system contracts with domestic vehicle manufacturers. Robert Bosch GmbH sustains technology leadership through deep R&D investment in camera-based classification algorithms trained on European sign databases. ZF Friedrichshafen AG anchors its position by supplying hybrid perception modules that fuse camera inputs with radar validation for highway-speed reliability.
Traffic sign recognition encompasses machine vision systems that detect, classify, and communicate regulatory, warning, and informational signage to vehicle control units using convolutional neural networks processing 1.3 to 8 megapixel image streams at 30-60 frames per second. These systems primarily enable speed limit compliance, intersection safety, and conditional automation handoff in advanced driver assistance architectures. Camera-based technology leads in unit volume due to mature supply chains and declining CMOS sensor costs, while hybrid systems capture expanding margin pools as OEMs demand sensor fusion for SAE Level 3 redundancy. Embedded systems dominate product type revenue by integrating directly into domain controller architectures, whereas standalone units face contraction as automakers consolidate computing into centralized zonal electronics.
KBA type-approval requirements for driver assistance systems mandate validated sign recognition performance under variable lighting and weather conditions, directly shaping product development priorities for German suppliers. The EU AI Act's risk classification framework for autonomous vehicle subsystems imposes documentation and conformity assessment obligations on algorithm training data and decision transparency. Stakeholders must monitor how forthcoming amendments to the EU General Safety Regulation expand mandatory sign recognition from commercial fleets to passenger vehicle segments.
Market Dynamics
German automotive OEMs are consolidating embedded perception computing into centralized zonal architectures, compressing standalone traffic sign recognition module demand while elevating performance requirements for domain-integrated software stacks.
Growth Catalysts
- KBA validation protocols:Tightened type-approval standards for camera-based driver assistance systems mandate higher real-time classification accuracy, forcing suppliers to upgrade algorithm performance and secure regulatory lock-in.
- Baden-Württemberg sensor cluster:Concentrated R&D operations by major Tier-1 suppliers create localized knowledge spillovers and accelerate prototype-to-production cycles for embedded recognition systems.
- Level 3 autonomy programs:German manufacturers' push into conditional automation requires redundant sign classification for highway-speed handoff scenarios, expanding specification scope for hybrid perception modules.
Market Restraints
- CMOS sensor cost volatility:Dependence on specialized image sensor foundries exposes margin pressure when semiconductor capacity tightens across Asian manufacturing hubs.
- Algorithm training data scarcity:European sign database completeness lags behind North American equivalents, limiting out-of-distribution generalization for rare regulatory signage.
- Standalone module obsolescence:Automaker consolidation of computing into zonal controllers threatens dedicated hardware suppliers without software integration capabilities.
Strategic Opportunities
- Bavaria logistics fleet mandate:Commercial vehicle segments face expanding compulsory sign recognition coverage, opening procurement channels beyond passenger car OEMs.
- Camera-radar fusion convergence:Hybrid perception architectures that validate visual classification through radar cross-section analysis command premium positioning in highway-speed applications.
- EU AI Act documentation requirements:Algorithm transparency obligations create service revenue streams for training data audit and conformity assessment capabilities.
Industry Challenges
- Convolutional neural network optimization talent:Scarce embedded systems engineers capable of balancing 30-60 frame-per-second throughput with sub-10-watt power budgets constrain development velocity.
- KBA certification timeline compression:Extended validation cycles for variable lighting and weather performance delay product launches and tie up capital in pre-revenue development phases.
- Legacy CAN bus integration friction:Domain controller architectures must maintain backward compatibility with older vehicle communication protocols, complicating software stack design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Traffic Sign Recognition Market |
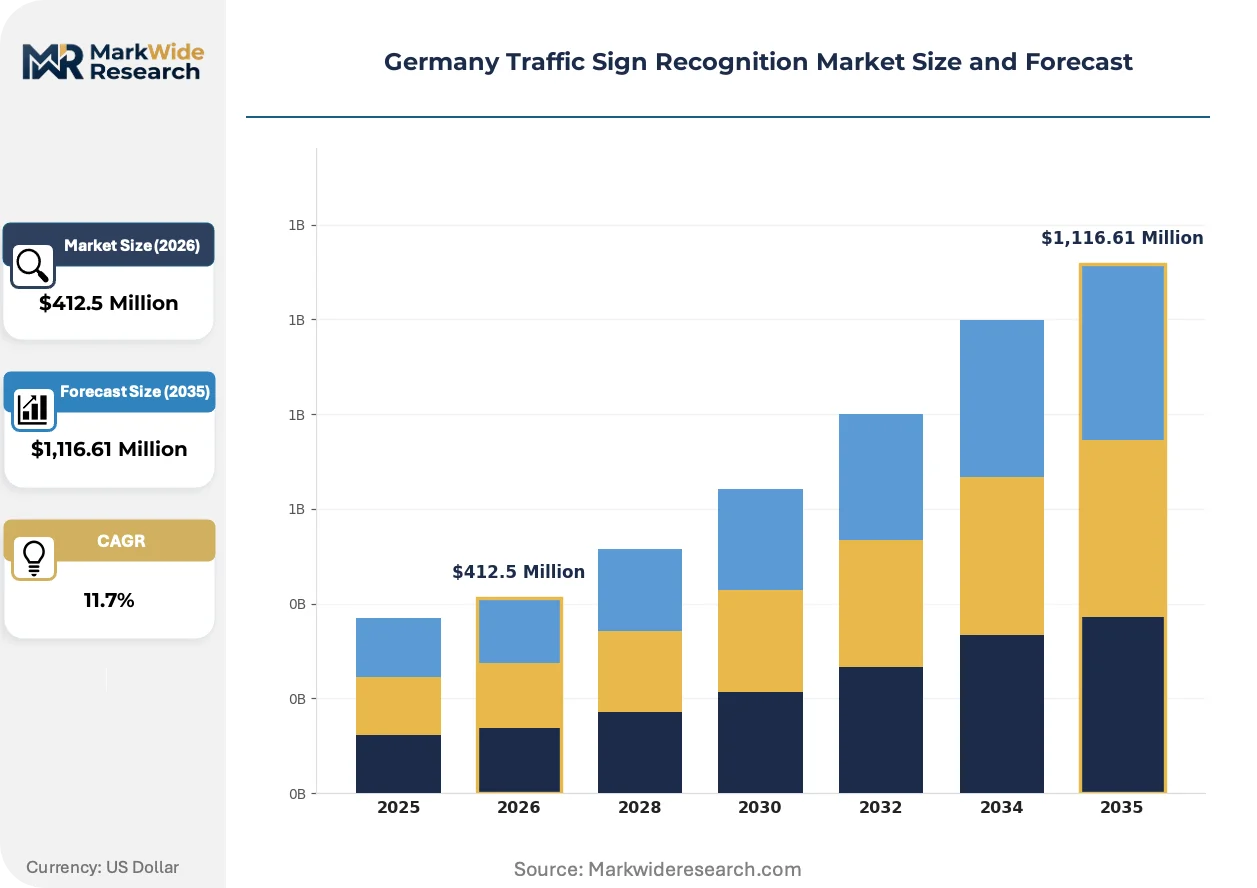
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,116.61 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Lidar-Based, Radar-Based, Ultrasonic-Based, Hybrid Systems Application: Advanced Driver Assistance Systems, Autonomous Vehicles, Fleet Management, Driver Monitoring Product Type: Standalone Units, Embedded Systems, Software Solutions, Hardware Modules End User: Vehicle Manufacturers, Transportation Authorities, Ride Sharing Operators, Logistics Providers |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, DENSO Corporation, HELLA GmbH & Co. KGaA, Mobileye Corporation, Aptiv PLC, Valeo Group, Infineon Technologies AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Traffic Sign Recognition Market Shifts & Advancements
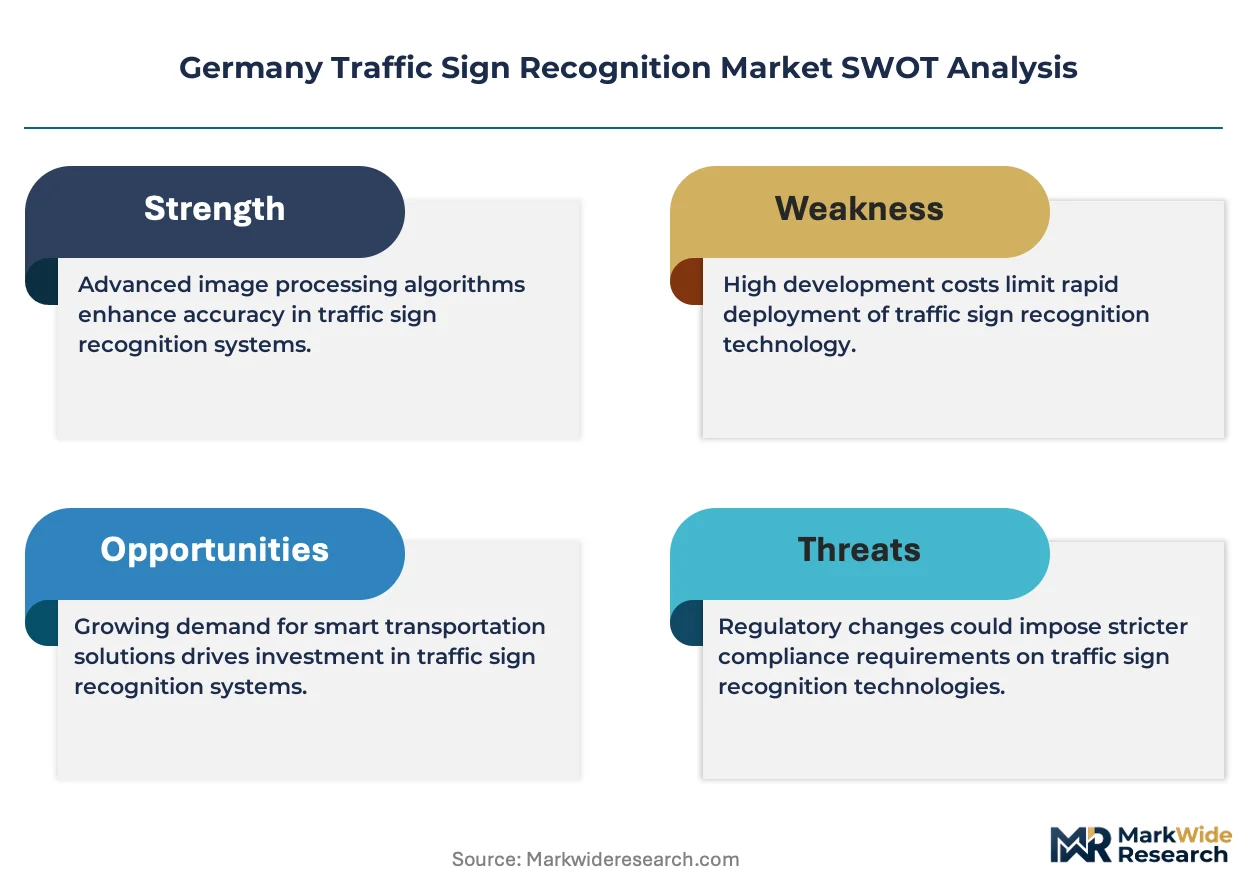
Traffic sign recognition technology is pivoting from standalone hardware boxes toward software-defined perception layers integrated into centralized vehicle computers, compressing supplier business models while elevating algorithmic performance requirements.
Convolutional neural networks with attention mechanisms are overtaking traditional region-based CNN architectures for real-time sign classification. German OEMs specify transformer-based vision models in Level 2+ procurement tenders, demanding higher computational throughput from domain controllers. This shift is overtaking fixed-function hardware acceleration in favor of programmable GPU and NPU fabrics that accommodate evolving network topologies.
KBA type-approval amendments for driver assistance systems now mandate validated performance under snow, fog, and direct sunlight glare conditions. Suppliers must demonstrate classification accuracy degradation curves across environmental parameter ranges, not just nominal performance metrics. Embedded system developers in Baden-Württemberg and Bavaria are responding with synthetic data augmentation pipelines and physical simulation environments.
Fleet operators in German logistics and ride-sharing segments now specify sign recognition capabilities directly in procurement contracts, bypassing traditional OEM specification channels. Tier-1 suppliers are establishing direct commercial vehicle relationships, unbundling from passenger car platform development cycles. This pattern concentrates in Baden-Württemberg, where Bosch and Continental maintain dedicated fleet solution divisions.
Germany Traffic Sign Recognition Market Segmentation
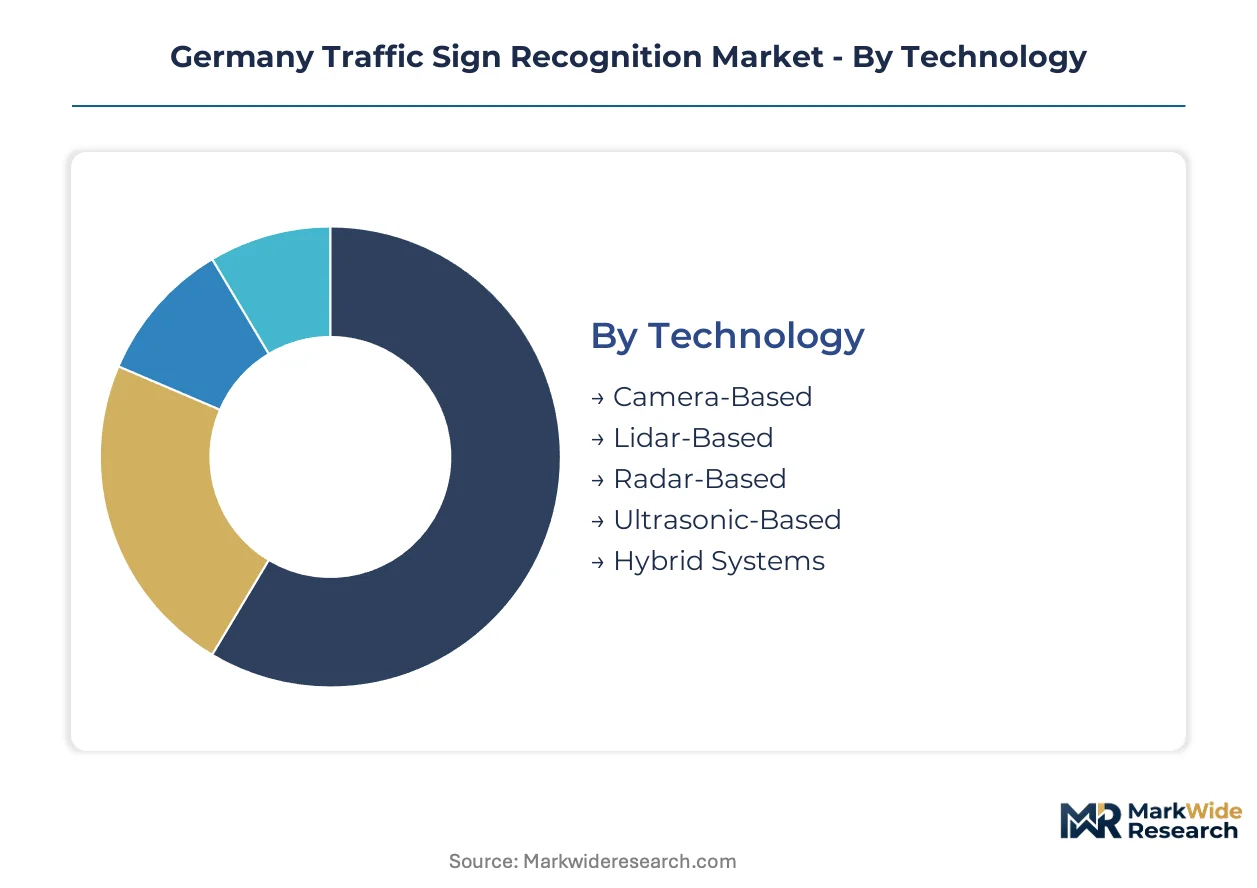
Technology architecture choices determine capital deployment patterns across German traffic sign recognition suppliers. Segment boundaries are blurring as domain controller consolidation forces hardware-software integration decisions.
Technology:
Capital intensity varies sharply across sensing modalities, with hybrid architectures demanding the most upfront investment in multi-sensor calibration and fusion algorithms.
- Camera-Based:CMOS image sensors process 1.3 to 8 megapixel streams at 30-60 frames per second through convolutional neural networks. Procurement concentrates among Baden-Württemberg automotive OEMs seeking mature supply chains and declining sensor costs for Level 2+ programs.
- Hybrid Systems:Multi-modal perception fuses camera classification with radar cross-section validation for highway-speed redundancy. Bavaria-based Tier-1 suppliers command premium positioning as German manufacturers advance Level 3 autonomy requiring environmental robustness.
- Lidar-Based:Time-of-flight laser scanning provides precise range data for 3D sign localization in urban autonomous navigation.
- Radar-Based:Frequency-modulated continuous wave sensors penetrate adverse weather where optical systems degrade.
- Ultrasonic-Based:Short-range acoustic sensing supplements close-proximity maneuvers in parking and low-speed scenarios.
Most installed capacity flows through Camera-Based systems. Expansion is steepest in Hybrid Systems.
Application:
Functional requirements diverge between assisted driving and full automation, reshaping performance specifications and validation protocols.
- Advanced Driver Assistance Systems:Speed limit compliance and intersection safety functions integrate into domain controllers with sub-10-watt power budgets. German OEM procurement in Stuttgart and Munich drives specification scope for real-time classification under KBA type-approval mandates.
- Autonomous Vehicles:Conditional automation handoff scenarios demand redundant perception validated across snow, fog, and direct sunlight glare. Development timelines concentrate in Bavaria where ZF and Bosch prototype highway-speed reliability systems.
- Fleet Management:Logistics operators specify sign recognition directly in procurement contracts, bypassing traditional OEM channels.
- Driver Monitoring:Cabin-facing systems cross-reference recognized signage with driver attention states for safety interventions.
Volume concentration sits with Advanced Driver Assistance Systems. Specification complexity is climbing fastest in Autonomous Vehicles.
Product Type:
Margin structures invert as computing consolidation eliminates standalone hardware positions.
- Embedded Systems:Software stacks integrate directly into zonal domain controllers, capturing dominant revenue share through algorithm licensing and update services. German automaker consolidation into centralized architectures elevates supplier dependency on integration capabilities.
- Software Solutions:Perception layers deploy over-the-air, decoupling feature releases from hardware cycles. Procurement from Baden-Württemberg sensor clusters emphasizes transformer-based vision models requiring programmable GPU and NPU fabrics.
- Standalone Units:Dedicated processing boxes face contraction as automakers eliminate redundant computing.
- Hardware Modules:Fixed-function accelerators lose share to programmable architectures accommodating evolving network topologies.
Revenue gravity centers on Embedded Systems. Software Solutions are gaining share fastest.
End User:
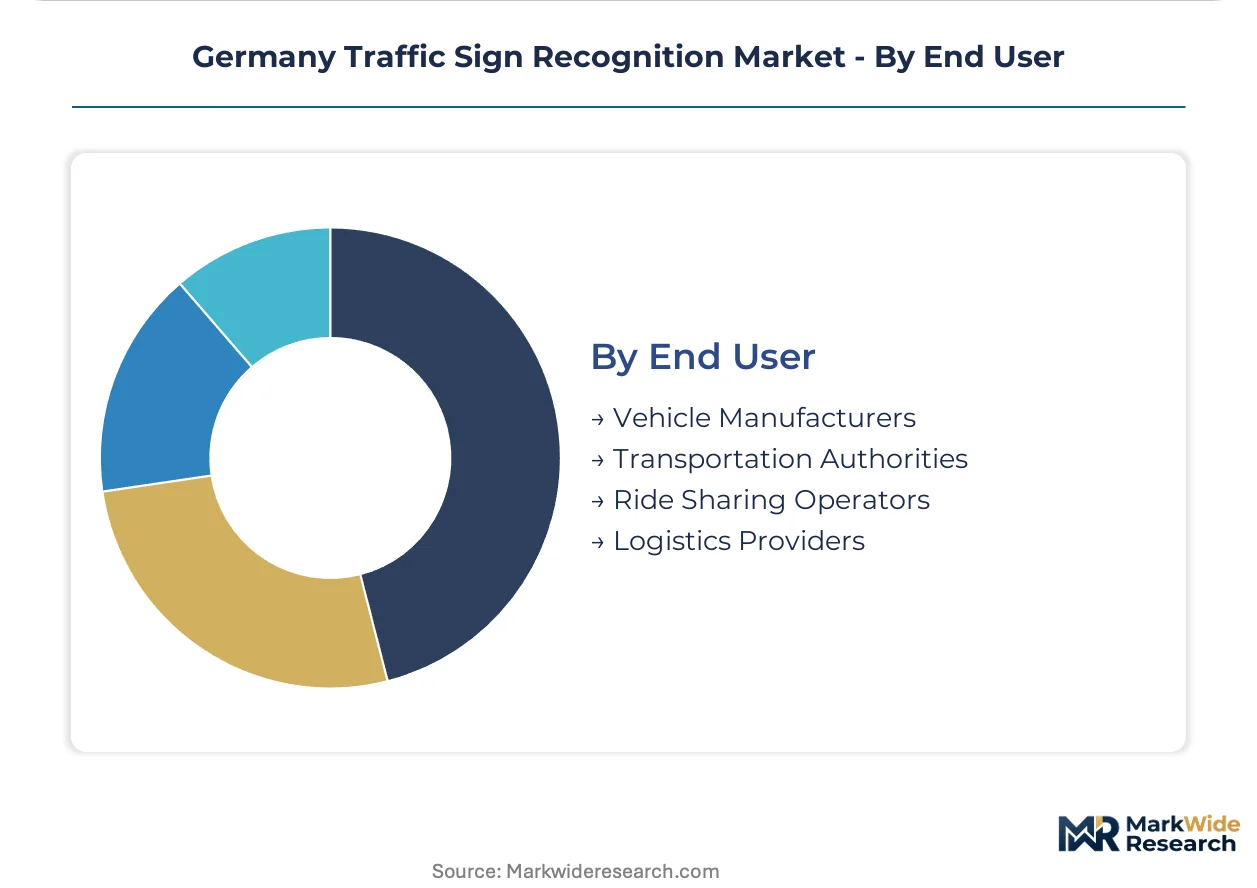
Procurement authority is fragmenting beyond traditional OEM channels into fleet operators and public authorities.
- Vehicle Manufacturers:Passenger car and commercial vehicle divisions in Wolfsburg, Stuttgart, and Munich specify embedded perception for platform-scale deployment. KBA validation protocols mandate documented performance degradation curves across environmental parameter ranges.
- Logistics Providers:Fleet operators in Bavaria and Baden-Württemberg now contract directly with Tier-1 suppliers for sign recognition capabilities, unbundling from passenger car development cycles.
- Transportation Authorities:Public infrastructure integration projects require standardized communication protocols between roadside units and vehicle systems.
- Ride Sharing Operators:Urban mobility services specify conditional automation features for highway corridor operations.
Contract volume flows predominantly through Vehicle Manufacturers. Direct procurement is expanding most quickly among Logistics Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers outpace French and Italian counterparts in embedded perception procurement, while regulatory frameworks in neighboring markets create divergent validation requirements for cross-border system deployment.
Bavaria
Level 3 autonomy programs at Munich-headquartered OEMs drive specification scope for redundant sign classification systems. KBA type-approval mandates for highway-speed handoff scenarios compress development timelines for Tier-1 suppliers. Ingolstadt and Munich anchor concentrated R&D operations where ZF Friedrichshafen AG and Robert Bosch GmbH prototype hybrid perception modules.
Baden-Württemberg
Camera-based recognition system procurement concentrates among Stuttgart-area manufacturers seeking mature CMOS sensor supply chains. The EU AI Act's risk classification framework imposes documentation obligations on algorithm training data transparency. Bosch and Continental AG maintain dedicated fleet solution divisions in the region, accelerating direct commercial vehicle contracting.
North Rhine-Westphalia
Logistics fleet operators in the Rhine-Ruhr corridor specify sign recognition capabilities directly in procurement contracts, bypassing traditional OEM channels. Germany's General Safety Regulation amendments expand mandatory coverage to commercial vehicle segments. Cologne and Dortmund host transportation authority pilot programs integrating roadside units with vehicle perception systems.
Lower Saxony
Domain controller consolidation among Wolfsburg-based vehicle manufacturers compresses standalone module demand while elevating software stack performance requirements. KBA validation protocols mandate documented classification accuracy degradation curves across snow, fog, and direct sunlight conditions. Hanover anchors supplier engineering centers focused on zonal architecture integration.
Hesse
Ride-sharing operators in the Frankfurt Rhine-Main metro specify conditional automation features for highway corridor fleet operations. Federal Ministry of Transport funding programs accelerate infrastructure-to-vehicle communication standardization. Darmstadt's technical university cluster feeds embedded systems engineering talent into regional Tier-1 development centers.
Germany Traffic Sign Recognition Market Competitive Landscape
Baden-Württemberg producers anchor one tier; Bavaria specialists hold differentiated positions in hybrid perception architectures. The supplier base concentrates around three dominant Tier-1 conglomerates with integrated sensor-to-software capabilities, while smaller specialists face compression from domain controller consolidation. Strategic archetypes include full-stack integrators, algorithm-focused software licensors, and sensor hardware purveyors. Competitive dynamics center on M&A activity targeting software-defined perception capabilities and strategic partnerships securing semiconductor foundry capacity.
Within the full-stack integrator tier, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG exemplify divergent strategic positioning. Continental AG occupies a dominant embedded system contract position with domestic vehicle manufacturers through its integrated sensor-to-software stack. Robert Bosch GmbH anchors technology leadership representation through sustained R&D investment in camera-based classification algorithms. ZF Friedrichshafen AG exemplifies hybrid perception module supply, fusing camera inputs with radar validation for highway-speed reliability requirements.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| HELLA GmbH & Co. KGaA |
| Mobileye Corporation |
| Aptiv PLC |
| Valeo Group |
| Infineon Technologies AG |
| Others |
Supply & Pricing Matrix
Transformer-based vision model deployment into zonal domain controllers is compressing standalone hardware margins while elevating software licensing premiums, concentrating pricing power among algorithm suppliers with KBA certification lock-in. This technology pivot simultaneously reduces CMOS sensor procurement volumes and raises NPU foundry dependencies, reshaping cost structures across Baden-Württemberg and Bavaria production clusters.
Pricing Analysis
Capacity additions in Taiwanese semiconductor foundries are reshaping price floors for automotive-grade NPUs, compressing embedded system hardware margins while algorithm licensing fees hold firmer. Three-tier pricing structure across premium hybrid-perception, standard camera-based, and economy standalone modules separates highway-speed redundancy validation from basic Level 2+ compliance. Cost compression in economy tiers is intensifying because zonal controller consolidation eliminates dedicated processing box demand. Logistics providers exhibit highest price sensitivity due to fleet-scale procurement volumes, whereas Munich-headquartered OEMs prioritize performance validation over unit cost.
Supply Chain Analysis
KBA type-approval documentation requirements function as qualification gates that filter supplier participation, extending validation timelines and tying up working capital in pre-certification phases. CMOS image sensors draw from Taiwan and South Korea foundries, while automotive-grade radar modules source from German and Japanese component specialists. Single-source vulnerability concentrates in specialized NPU fabrication for transformer-based vision models. Tier-1 suppliers distribute through direct OEM platform integration contracts and emerging fleet operator procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German traffic sign recognition represents a late-cycle quality story where KBA validation protocols and Level 3 autonomy specifications are filtering demand toward premium hybrid-perception systems with documented environmental robustness.
For Market Incumbents: Extend software-defined perception capabilities through over-the-air update infrastructure, locking in recurring revenue streams as hardware margins compress. Deepen backward integration into European sign database curation to defend against algorithm training data scarcity threats. Secure captive NPU foundry capacity through long-term offtake agreements with Taiwanese semiconductor suppliers. For New Entrants and Emerging Players: Fleet-direct digital procurement platforms offer the most penetrable route for bypassing entrenched OEM-Tier-1 relationships. Target commercial vehicle segments in North Rhine-Westphalia logistics corridors where compulsory coverage expansion creates specification windows outside passenger car platform cycles. Lead with AI Act conformity assessment services as a wedge for subsequent algorithm licensing discussions. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone hardware module specialists facing zonal controller obsolescence. Long-term viability centers on software-embedded business models with regulatory certification moats. Monitor EU General Safety Regulation amendment timing as the critical inflection signal for mandatory passenger vehicle segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Perception Module Development | Camera-radar fusion architectures command premium positioning in Bavaria Level 3 programs. |
| KBA Certification Pre-Investment | Early validation documentation secures regulatory lock-in before protocol tightening. |
| Fleet Solution Division Establishment | Direct logistics contracting in Baden-Württemberg bypasses traditional OEM channels. |
| Synthetic Data Pipeline Construction | Environmental augmentation capabilities satisfy amended type-approval performance mandates. |
| Domain Controller Software Integration | Embedded stack positioning captures revenue as standalone hardware contracts. |
Research Methodology
Multiple input streams — Tier-1 supplier procurement directors, OEM platform engineering leads, KBA regulatory affairs specialists, and commercial vehicle fleet managers — were reconciled against vehicle production databases, KBA type-approval filings, and EU regulatory amendment trackers. Primary fieldwork with embedded systems engineers and domain controller architects was validated through secondary analysis of SEC filings from listed automotive suppliers and IHS Markit vehicle registration data. Bottom-up segment sizing was cross-referenced against top-down market aggregation across technology, application, and product type dimensions.
Historical revenue trajectories were cross-referenced against expert panel inputs regarding Level 2+ and Level 3 program timelines. Segmentation modeling captured technology architecture, functional application, product integration depth, and end-user procurement authority across the projection horizon. CAGRs were derived from fitted growth curves incorporating KBA regulatory amendment probability weights and semiconductor capacity expansion schedules. Forecast inputs included CMOS sensor cost decline curves and transformer model computational throughput requirements.
Regulatory amendment delays, NPU foundry capacity constraints, and autonomous vehicle program cancellations are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding KBA protocol implementation timing and EU AI Act enforcement sequencing. A model refresh is warranted upon material change in German General Safety Regulation amendment passage or Level 3 highway-speed deployment authorization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market