
 Automatic Tire Changer Market | 2026-2036
Automatic Tire Changer Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Tire Changer Market Analytics
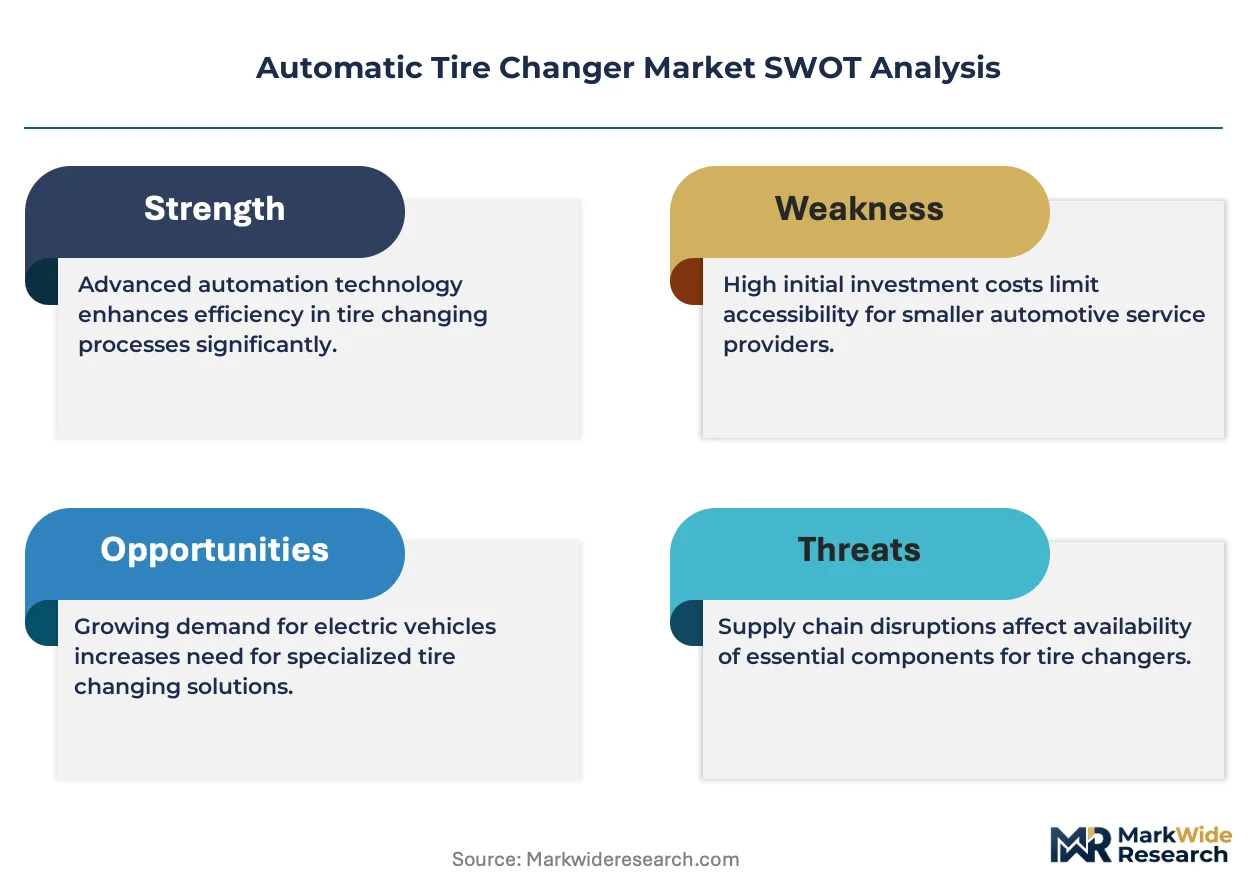
The capital-intensity divergence between automated and semi-automated product lines is rotating competitive investment toward servo-electric architectures and integrated wheel-handling systems. Hunter Engineering Company leverages its vertical integration into diagnostic and alignment equipment to bundle tire changer sales with service bay ecosystems. Robert Bosch GmbH sustains channel control through its automotive aftermarket distribution network across Europe and North America. Corghi S.p.A. specializes in premium fully automatic systems for high-volume tire retailers, anchoring its position in the Italian and broader European workshop segments.
An automatic tire changer is a powered workshop machine designed to remove and mount tires onto wheel rims without manual prying tools, typically employing a rotating turntable, bead breaker arm, and mounting head with clamping forces between 1,500 and 3,500 pounds to accommodate passenger through heavy-duty commercial wheels. Its primary commercial purpose is to reduce technician labor time, minimize wheel damage, and enable consistent throughput in high-volume automotive service environments. Fully automatic systems command the dominant share of value due to labor substitution economics, while heavy-duty configurations represent the fastest-expanding category as commercial fleet maintenance outsourcing accelerates. Floor-mounted installations retain the largest installed base, though mobile units are gaining traction among roadside assistance providers and decentralized fleet operators seeking field-service capability.
The EPA oversees workshop chemical handling standards affecting tire changer lubricants and cleaning agents, while OSHA mandates machine guarding and lockout protocols that shape equipment design requirements in the United States. The EU Machinery Directive and CE marking requirements enforce safety interlocks and electromagnetic compatibility standards for equipment sold across European member states. Stakeholders must monitor evolving electrification standards for commercial vehicle fleets, as heavier EV wheel assemblies and torque specifications will force recalibration of changer clamping and lifting specifications across product portfolios.
Market Dynamics
Servo-electric drive systems are displacing traditional pneumatic architectures across workshop equipment portfolios, compressing maintenance intervals and energy consumption while forcing incumbent manufacturers to retool production lines.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-handling compliance costs are pushing independent workshops to consolidate service bays, expanding automatic tire changer deployment as bundled equipment investments.
- Commercial fleet outsourcing:Third-party maintenance providers in the United States are scaling automated tire service capacity to capture long-term service contracts from logistics operators.
- EV wheel assembly weight:Heavier electric vehicle rims are exceeding conventional changer specifications, forcing equipment replacement cycles among early-adopter service networks.
Market Restraints
- Steel and aluminum price volatility:Raw material input costs for changer frames and clamping mechanisms create margin compression for equipment assemblers without captive metal supply.
- Controller chip supply concentration:Servo motor drivers and PLC modules depend on concentrated semiconductor fabrication in East Asia, exposing delivery timelines to geopolitical friction.
- Manual lever tool persistence:Low-volume rural workshops continue using traditional tire irons for cost reasons, limiting addressable market penetration in price-sensitive segments.
Strategic Opportunities
- Roadside assistance mobile units:Decentralized fleet operators in Germany are field-testing trailer-mounted automatic changers for emergency tire service outside fixed facilities.
- China aftermarket expansion:Domestic automotive production scale is accelerating independent workshop formation, creating first-time equipment demand outside OEM-captive service networks.
- Alignment system convergence:Integration of tire changers with wheel alignment diagnostics creates bundled service bay propositions for high-throughput retailers.
Industry Challenges
- Servo-electric technician training:Maintenance staff accustomed to pneumatic troubleshooting require reskilling for electronic fault diagnosis and encoder calibration.
- CE marking compliance timelines:Machinery Directive safety interlock documentation and electromagnetic compatibility testing extend product launch schedules for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Tire Changer Market |
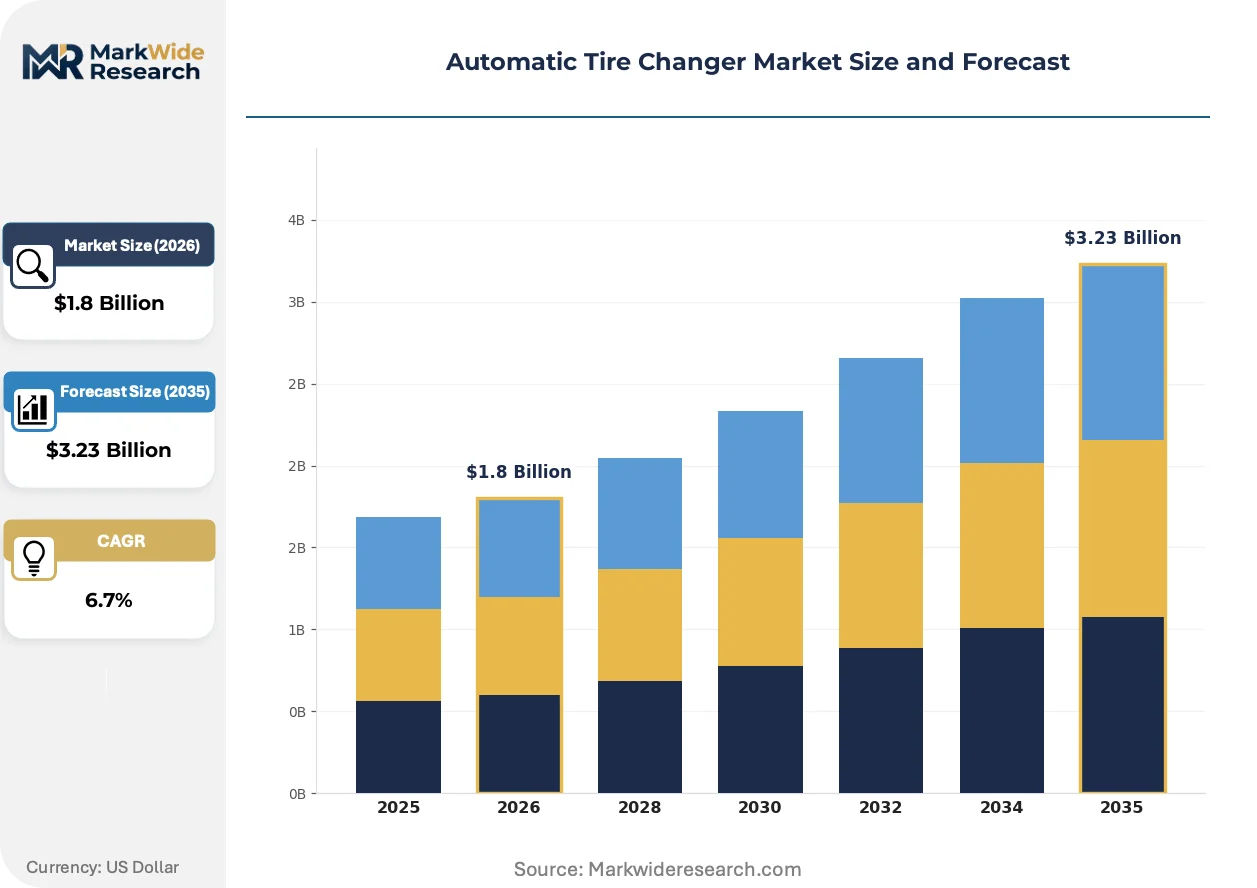
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Wheel, Heavy-Duty, Semi-Automatic, Fully Automatic End User: Automotive Workshops, Tire Retailers, Gas Stations, Service Centers Technology: Hydraulic, Pneumatic, Electric, Manual Installation: Floor-Mounted, Portable, Mobile, Bench-Mounted |
| Companies Covered | Hunter Engineering Company, Robert Bosch GmbH, Corghi S.p.A., Snap-on Incorporated, CEMB S.p.A., GIULIANO INDUSTRIAL S.p.A, Hofmann GmbH & Co. KG, Ravaglioli S.p.A., Hennessy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Tire Changer Market Evolving Landscape
Equipment architecture is bifurcating between integrated service bay ecosystems and standalone modular units, with connectivity features and predictive maintenance capabilities becoming baseline specifications rather than premium differentiators.
Touchless bead breaking technology is fragmenting the traditional mounting head market by eliminating wheel contact during tire removal. High-volume tire retailers in Japan are adopting these systems to protect premium alloy rims from cosmetic damage. The technology is compressing warranty claim rates while extending serviceable wheel size ranges without mechanical retooling.
The EU Machinery Directive's 2023 update to safety interlock standards is forcing redesign of turntable guarding and emergency stop circuits. Italian equipment manufacturers are accelerating CE recertification programs to maintain continental distribution access. Heavy-duty commercial configurations face the steepest redesign burden due to higher clamping force thresholds and operator proximity risks.
Fleet procurement departments are consolidating vendor relationships through multi-year equipment lease arrangements rather than capital purchase. Logistics operators in the United States are favoring suppliers offering bundled maintenance and software update commitments. This shift is visible most acutely among national trucking networks seeking to standardize service bay configurations across distributed terminal locations.
Automatic Tire Changer Market Segmentation
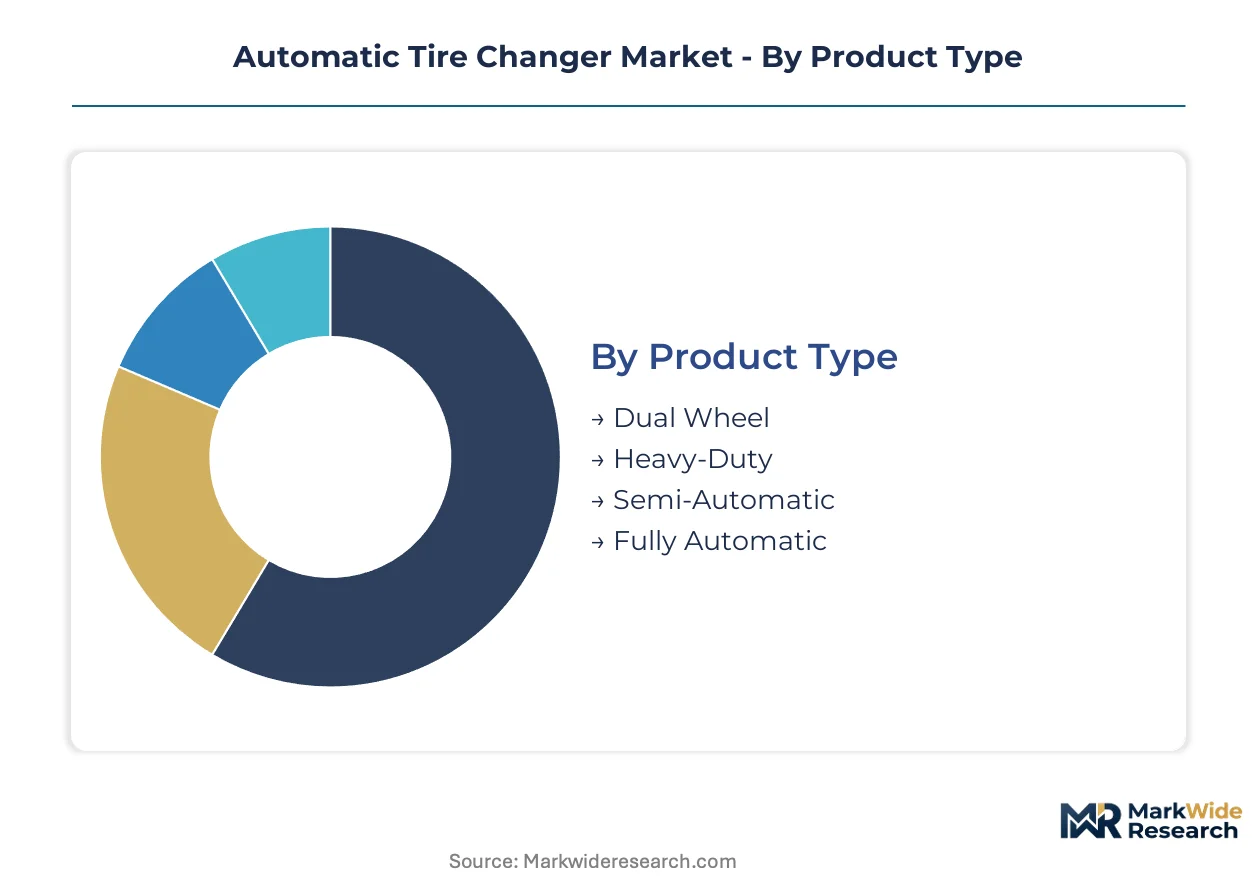
Automatic tire changer procurement patterns diverge sharply between high-volume commercial operators and low-throughput independents. Equipment specifications, technology choices, and installation formats each respond to distinct labor economics, facility constraints, and service mix requirements across end-use segments.
Product Type:
Domestic production in China and Italy dominates standard configurations, while heavy-duty and fully automatic systems flow through specialized export channels serving fleet operators in Germany, the United States, and Brazil.
- Fully Automatic:Systems integrate servo-electric turntable drives, automated bead breaking, and programmable clamping sequences that eliminate manual intervention. Demand concentrates in high-volume tire retailers across Japan and Germany, where labor cost structures justify premium capital expenditure and technician throughput targets exceed 40 wheel assemblies per shift.
- Heavy-Duty:Configurations accommodate commercial truck, bus, and agricultural tires with clamping forces exceeding 3,500 pounds and reinforced mounting heads. Fleet maintenance outsourcing in the United States is accelerating procurement among third-party logistics providers seeking standardized service bay equipment across distributed terminal networks.
- Semi-Automatic:Hybrid designs retain pneumatic bead breaking with manual wheel positioning, serving mid-tier automotive workshops in India and Southeast Asia where capital constraints limit full automation.
- Dual Wheel:Specialized units simultaneously service paired wheels on multi-axle commercial vehicles, finding niche application in mining fleet operations across Australia and Chile.
Fully automatic configurations hold the largest share; momentum sits with heavy-duty systems as commercial fleet electrification forces equipment replacement cycles.
End User:
Customer procurement authority ranges from centralized fleet engineering departments to individual workshop owner-operators, shaping pricing tolerance and service contract structures.
- Automotive Workshops:Independent repair facilities prioritize equipment versatility across passenger and light commercial applications. Workshop consolidation trends in Italy and Spain are driving bundled tire changer and wheel alignment system purchases.
- Tire Retailers:High-throughput chains demand touchless bead breaking and integrated diagnostic capabilities to protect premium alloy rims and reduce warranty exposure. Volume commitments in Japan support direct manufacturer relationships bypassing traditional distribution.
- Service Centers:OEM-captive facilities follow manufacturer-mandated equipment specifications, creating locked procurement relationships with approved suppliers in Germany and South Korea.
- Gas Stations:Convenience-driven locations favor compact semi-automatic units for emergency roadside service, with deployment concentrated along highway corridors in France and the United States.
Automotive workshops retain the dominant installed base; tire retailers are expanding most quickly as alloy wheel penetration accelerates cosmetic damage liability concerns.
Technology:
Drive system selection determines maintenance burden, energy consumption profiles, and technician reskilling requirements across equipment lifecycles.
- Electric:Servo motor architectures deliver programmable torque curves and encoder-based position feedback, compressing energy consumption by 40% versus pneumatic equivalents. Regulatory pressure from the EU F-Gas Regulation is indirectly accelerating electric adoption as workshops consolidate service capabilities under environmental compliance frameworks.
- Pneumatic:Compressed air systems retain installed base dominance in legacy facilities across Brazil and Mexico, where maintenance staff familiarity and spare parts availability delay replacement cycles despite higher operating costs.
- Hydraulic:High-force configurations persist in heavy-duty commercial applications requiring sustained clamping pressure, with Italian manufacturers maintaining specialized production lines for mining and construction fleet operators.
- Manual:Lever-operated tools survive in rural India and sub-Saharan Africa where electrification remains inconsistent and labor cost structures preclude powered equipment investment.
Electric systems command the value premium; pneumatic equipment retains volume leadership in price-sensitive emerging markets.
Installation:
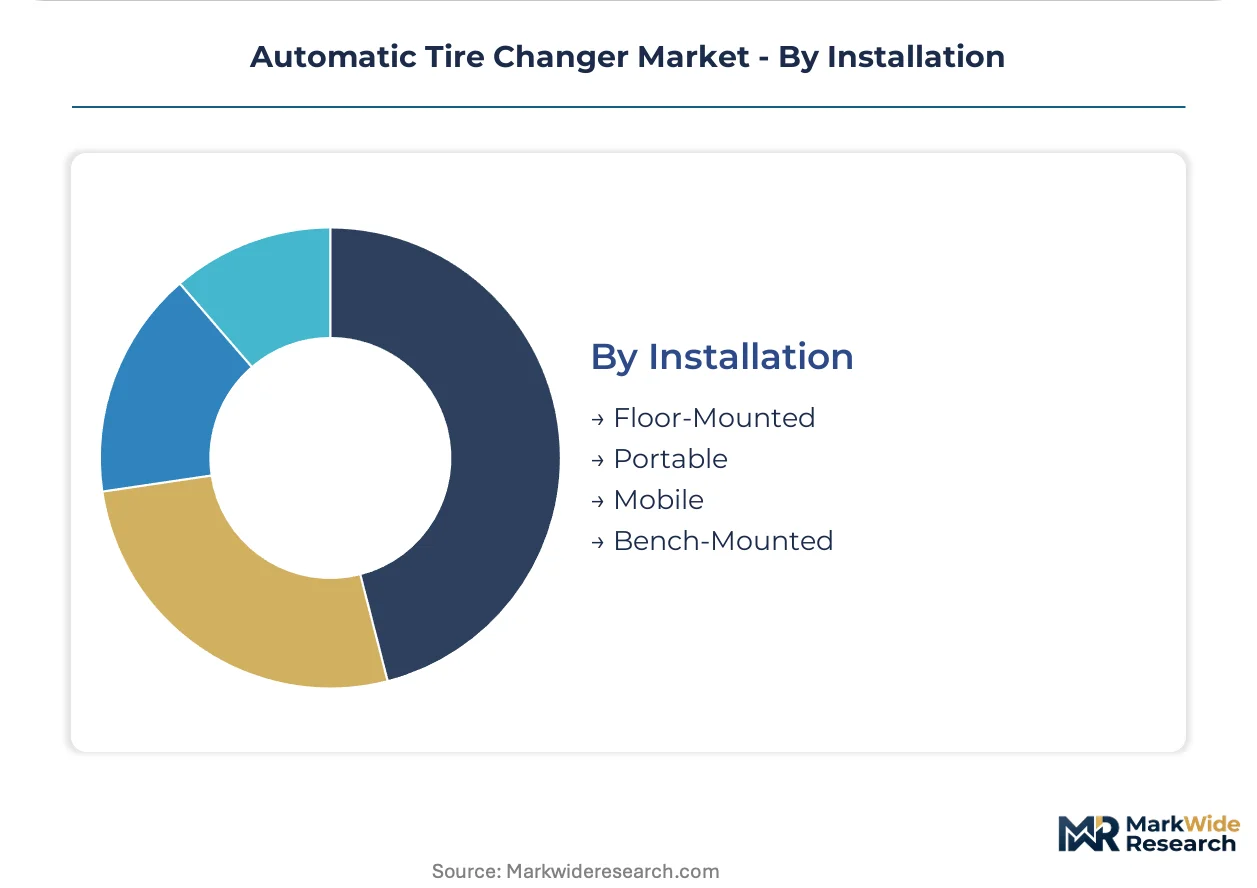
Facility configuration and service mobility requirements dictate mounting format selection, with floor-mounted systems anchoring fixed infrastructure and mobile units enabling field service expansion.
- Floor-Mounted:Permanent installations with bolted subframes and dedicated electrical supply dominate high-volume service environments. German workshop chains specify standardized bay dimensions that lock in equipment form factors across multi-site rollouts.
- Mobile:Trailer-mounted and vehicle-integrated configurations are gaining traction among roadside assistance providers in Germany and fleet operators in Australia seeking decentralized tire service capability outside fixed facilities.
- Portable:Compact units with caster-based mobility serve multi-bay workshops requiring equipment repositioning, with demand concentrated in independent facilities across Italy and Poland.
- Bench-Mounted:Elevated installations for motorcycle and small utility tire service occupy niche positions in Japanese and Taiwanese markets with high two-wheeler density.
Floor-mounted systems retain the largest installed base; mobile configurations are climbing the fastest as fleet operators field-test decentralized maintenance models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement elasticity varies sharply across geographies, with German and Japanese buyers prioritizing servo-electric throughput over capital outlay while Indian and Mexican workshops favor semi-automatic configurations that minimize upfront investment.
United States
Third-party logistics providers are scaling automated tire service capacity to capture fleet maintenance outsourcing contracts from national trucking networks. OSHA machine guarding mandates and lockout protocols shape equipment design requirements for workshop installations. Dallas-Fort Worth anchors commercial fleet service hub expansion, with regional equipment distributors reporting accelerated changer procurement among decentralized terminal operators.
Germany
Workshop consolidation under EU F-Gas Regulation compliance costs is driving bundled tire changer and wheel alignment system purchases among independent repair chains. The Machinery Directive's updated safety interlock standards force CE recertification timelines that extend product launch schedules. Stuttgart's automotive engineering cluster hosts field-testing of trailer-mounted mobile changers for roadside assistance providers seeking decentralized service capability.
China
Domestic automotive production scale and aftermarket expansion are accelerating independent workshop formation outside OEM-captive service networks. MIIT industrial equipment standards and local environmental compliance frameworks indirectly pressure service bay consolidation. Shanghai and Guangzhou manufacturing clusters concentrate domestic changer production, with equipment replacement cycles shortening as production volumes strain legacy pneumatic installations.
Italy
Premium fully automatic systems command sustained demand among high-volume tire retailers protecting alloy rim cosmetics from mounting damage. CE marking documentation and electromagnetic compatibility testing requirements enforce redesign cycles for turntable guarding and emergency stop circuits. Emilia-Romagna's machinery manufacturing belt anchors specialized production lines for heavy-duty commercial configurations serving mining and construction fleet operators.
Japan
High-throughput tire chains specify touchless bead breaking technology to compress warranty claim rates and extend serviceable wheel size ranges without mechanical retooling. METI energy efficiency guidelines and industrial equipment standards shape servo-electric adoption curves. Nagoya's automotive supplier ecosystem integrates changer procurement with wheel alignment diagnostic bundling for standardized service bay rollouts.
Automatic Tire Changer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with servo-electric innovators competing against pneumatic legacy manufacturers for distinct customer segments. The vendor base stratifies across three tiers: integrated service bay ecosystem providers, standalone equipment specialists, and regional fabrication houses serving price-sensitive emerging markets. Dominant competitive moves include backward integration into diagnostic and alignment equipment portfolios and multi-year lease arrangements replacing capital purchase models among fleet procurement departments.
Among North American equipment providers, Hunter Engineering Company and Hennessy Industries occupy positions within the integrated ecosystem tier, leveraging service bay bundling capabilities. European specialists including Corghi S.p.A., CEMB S.p.A., and Ravaglioli S.p.A. exemplify the premium fully automatic archetype, with Italian S.p.A. structures dominating high-volume retailer segments. Robert Bosch GmbH anchors channel control through aftermarket distribution networks, while Snap-on Incorporated represents the tool and equipment conglomerate model with diversified workshop product portfolios.
| Leading Market Players |
|---|
| Hunter Engineering Company |
| Robert Bosch GmbH |
| Corghi S.p.A. |
| Snap-on Incorporated |
| CEMB S.p.A. |
| GIULIANO INDUSTRIAL S.p.A |
| Hofmann GmbH & Co. KG |
| Ravaglioli S.p.A. |
| Hennessy Industries |
| Others |
Value Network & Pricing Analysis
Servo-electric actuator adoption displacing pneumatic drive systems is redrawing procurement geography toward East Asian motor manufacturers while compressing aftermarket service margins for legacy equipment fleets. This substitution dynamic concentrates pricing power among suppliers with captive controller firmware development, forcing European and North American assemblers to absorb component cost volatility or cede share to integrated Chinese producers.
Pricing Analysis
Software update subscriptions and predictive maintenance contracts generate lifetime value multiples exceeding original equipment margins for tier-one manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with fleet procurement departments least sensitive and independent rural workshops most price-constrained. Pricing pressure stems from semiconductor supply concentration in Taiwan and South Korea, which feeds through to servo driver module costs. After-sales bundling separates premium-tier vendors with diagnostic integration from standard-tier standalone equipment providers.
Supply Chain Analysis
China and Italy anchor frame fabrication and final assembly, while Germany and Japan concentrate precision servo motor and encoder production. Controller chip supply draws from concentrated semiconductor fabrication in Taiwan and South Korea, exposing delivery timelines to geopolitical friction. Steel and aluminum price volatility creates margin compression for equipment assemblers without captive metal supply. Distribution runs through automotive aftermarket networks and direct manufacturer relationships with high-volume tire retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switching costs embedded in technician training and service bay standardization create defensive moats for established players, with regulatory certification requirements deepening entrenchment.
For Market Incumbents: Consolidate control over diagnostic and alignment equipment portfolios to lock in bundled tire changer procurement from high-throughput retailers. Deepen backward integration into servo motor and controller production to insulate margins from East Asian semiconductor supply volatility. CE marking compliance timelines and Machinery Directive recertification burdens favor incumbents with dedicated regulatory affairs capacity over emerging competitors. For New Entrants and Emerging Players: Mobile roadside assistance configurations represent an underserved service layer where decentralized fleet operators field-test trailer-mounted units outside fixed facility infrastructure. Target semi-automatic equipment segments in India and Southeast Asia where capital constraints limit full automation penetration among independent workshops. Pursue direct e-commerce distribution to bypass entrenched aftermarket channel gatekeepers in price-sensitive emerging markets. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors servo-electric specialists with software-defined service capabilities over pneumatic legacy manufacturers. Long-term viability hinges on equipment-as-a-service revenue models and predictive maintenance platform monetization. Monitor EV wheel assembly weight specifications as the inflection signal forcing replacement cycles among early-adopter service networks.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | Reduces energy consumption and maintenance burden for high-throughput tire retailers in Germany and Japan. |
| Touchless Bead Breaking Technology Adoption | Compresses warranty claim rates for premium alloy rim protection in Japanese tire retail chains. |
| Mobile Unit Field Deployment | Enables decentralized fleet maintenance outsourcing for roadside assistance providers in Germany and Australia. |
| Alignment System Integration | Creates bundled service bay propositions leveraging Hunter Engineering Company's diagnostic ecosystem control. |
| CE Marking Recertification Acceleration | Maintains continental distribution access for Italian manufacturers under updated Machinery Directive safety standards. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, automotive production databases, SEC equipment manufacturer filings, and EU regulatory documentation. Interviews with maintenance directors at commercial fleet operators, aftermarket service heads at tire retail chains, OEM procurement teams, and plant engineers at equipment manufacturing facilities informed demand-side and supply-side validation. Bottom-up equipment shipment analysis triangulates against top-down service bay capacity modeling.
Segmentation dimensions modeled include product automation level, end-user facility type, drive system technology, and installation format across the projection horizon. CAGRs derive from equipment replacement cycle analysis, fleet outsourcing penetration curves, and EV adoption impacts on wheel assembly specifications. Forecast inputs incorporate MIIT industrial equipment standards compliance trajectories and EU F-Gas Regulation consolidation effects on workshop service bay economics.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and OSHA machine guarding protocols; material policy shifts would require re-modeling. Semiconductor supply concentration and steel price volatility represent primary revision risks. Recalibration cycles align with material shifts in commercial fleet electrification timelines and servo-electric technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
United States Automotive Service Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Europe Car Wash Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Americas MAP Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Vehicle Conversion Market
Automotive Services
France Car Rental Market
Automotive Services
Automotive Repair and Service Market