
 Bumper Beam Market | 2026-2036
Bumper Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Bumper Beam Market Outlook
The EU Green Deal's embodied carbon requirements for automotive components is broadening the addressable market for recycled aluminum and fiber-reinforced polymer bumper beam solutions. Gestamp leverages its hot-stamping expertise to maintain steel bumper beam competitiveness while expanding aluminum capacity across Spanish and German plants. Plastic Omnium anchors its position through vertical control over injection molding cell technology for large-format plastic crash beams. Benteler Deutschland sustains R&D intensity in roll-formed hybrid structures that bridge steel cost economics with aluminum weight savings.
A bumper beam is a structural reinforcement member mounted transversely behind the vehicle fascia, engineered to absorb and distribute impact energy during frontal and rear collisions while typically measuring 1.2–2.0 meters in span and 1.5–3.0 millimeters in wall thickness depending on material class. Steel variants dominate entry-segment vehicle platforms due to established stamping infrastructure and raw material cost structures, while aluminum and composite grades command premium positioning in electrified SUVs and sedans where mass reduction directly extends battery range. The manufacturing process dimension reveals injection molding as the fastest-growing fabrication route for plastic bumper beams serving OEMs with high-volume platform standardization, whereas stamping retains margin concentration in aftermarket channels where steel replacement parts sustain legacy fleet demand.
NHTSA's Federal Motor Vehicle Safety Standards in the United States, ECE R42 regulations administered under United Nations Economic Commission for Europe frameworks, and China's GB standards enforced by SAMR collectively define crash pulse and pedestrian protection criteria that dictate bumper beam design envelopes and material qualification protocols. These regulatory architectures directly shape supplier certification timelines, testing expenditure burdens, and cross-border homologation strategies for component manufacturers seeking multi-region OEM contracts. Stakeholders must monitor evolving side-impact and autonomous vehicle crash scenarios where active sensor integration is forcing redesign of traditional bumper beam mounting geometries and material electromagnetic transparency properties.
Market Dynamics
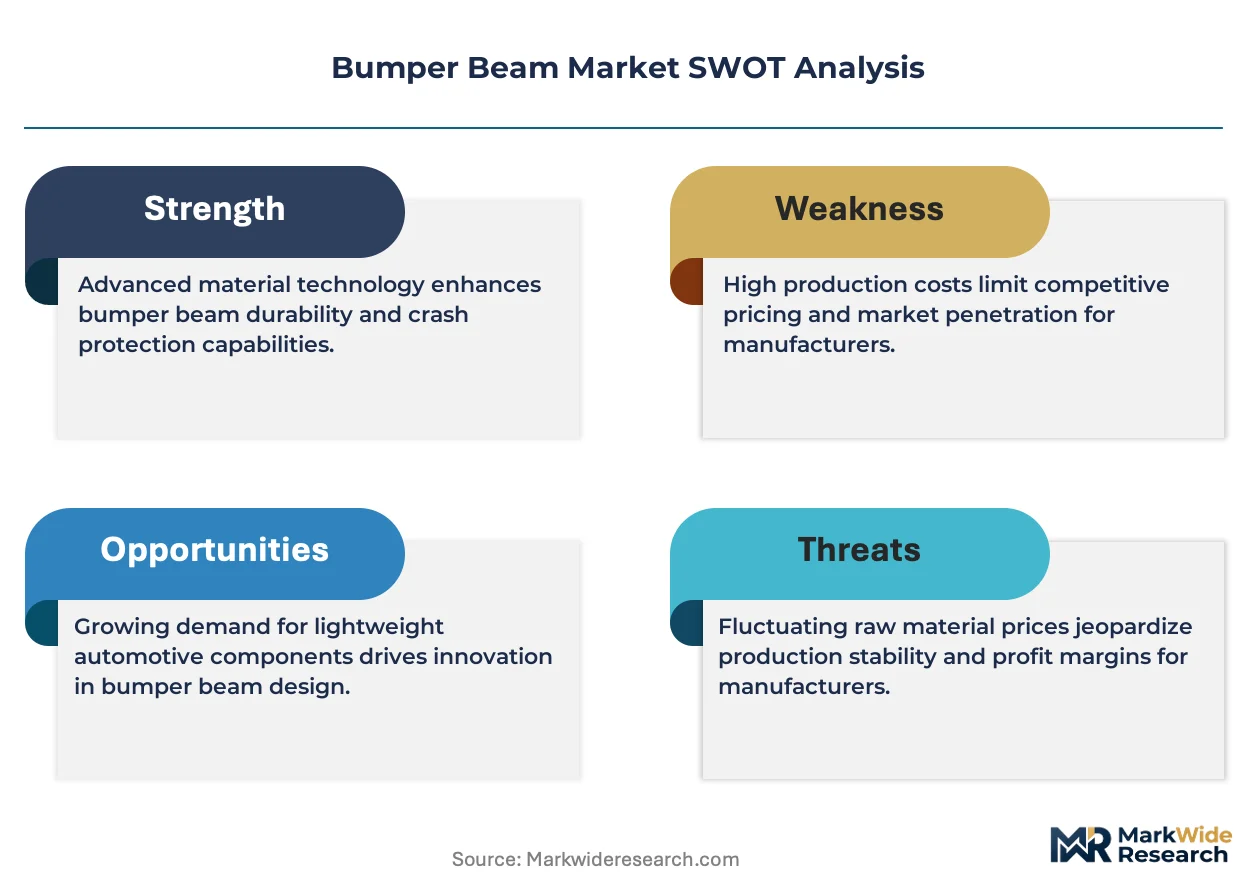
The collision between EU Green Deal embodied carbon mandates and electric vehicle platform proliferation is forcing material requalification across OEM supply chains, compressing supplier certification timelines while expanding addressable demand for lightweight architectures.
Growth Catalysts
- EU Green Deal Embodied Carbon Requirements:Recycled aluminum and fiber-reinforced polymer bumper beam solutions gain qualified supplier status as OEMs requalify crash management systems for compliance with automotive component carbon accounting frameworks.
- Electric Vehicle Platform Expansion:Battery range extension imperatives drive aluminum and composite bumper beam specification in electrified SUVs and sedans where mass reduction directly extends driving range per kilowatt-hour.
- Injection Molding Process Maturation:High-volume platform standardization enables plastic bumper beam fabrication routes that reduce per-unit cycle times while maintaining ECE R42 crash pulse compliance for European OEM contracts.
Market Restraints
- Primary Aluminum Price Volatility:London Metal Exchange aluminum price swings compress margin predictability for suppliers committed to lightweight material capacity expansion in Germany and Spain.
- Steel Stamping Infrastructure Lock-in:Entry-segment vehicle platforms maintain established stamping infrastructure and raw material cost structures that delay aluminum substitution in price-sensitive market tiers.
- Cross-border Homologation Burden:NHTSA Federal Motor Vehicle Safety Standards, ECE R42 frameworks, and China GB standards impose divergent testing expenditure burdens that extend supplier certification timelines for multi-region OEM contracts.
Strategic Opportunities
- India Automotive Manufacturing Expansion:PLI scheme incentives for advanced automotive components create qualified supplier entry points for aluminum bumper beam architectures serving domestic OEM electrification programs.
- Autonomous Vehicle Sensor Integration:Active sensor mounting requirements force redesign of traditional bumper beam geometries, opening specification windows for electromagnetically transparent composite materials in premium platform segments.
- Aftermarket Channel Digitization:E-commerce platforms for crash replacement parts enable direct-to-repair-shop distribution that bypasses traditional tiered distribution markups for steel bumper beam legacy fleet demand.
Industry Challenges
- Multi-material Joining Expertise Scarcity:Hybrid steel-aluminum bumper beam architectures require specialized welding and adhesive process capabilities that outpace current technical workforce development pipelines in European manufacturing clusters.
- Active Safety System Integration Complexity:Radar and lidar sensor mounting specifications force simultaneous redesign of bumper beam structural performance and electromagnetic transparency properties, compressing development cycles.
- Recycled Material Certification Delays:Post-consumer aluminum feedstock qualification protocols extend testing timelines for suppliers seeking OEM approval under EU Green Deal carbon accounting methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bumper Beam Market |
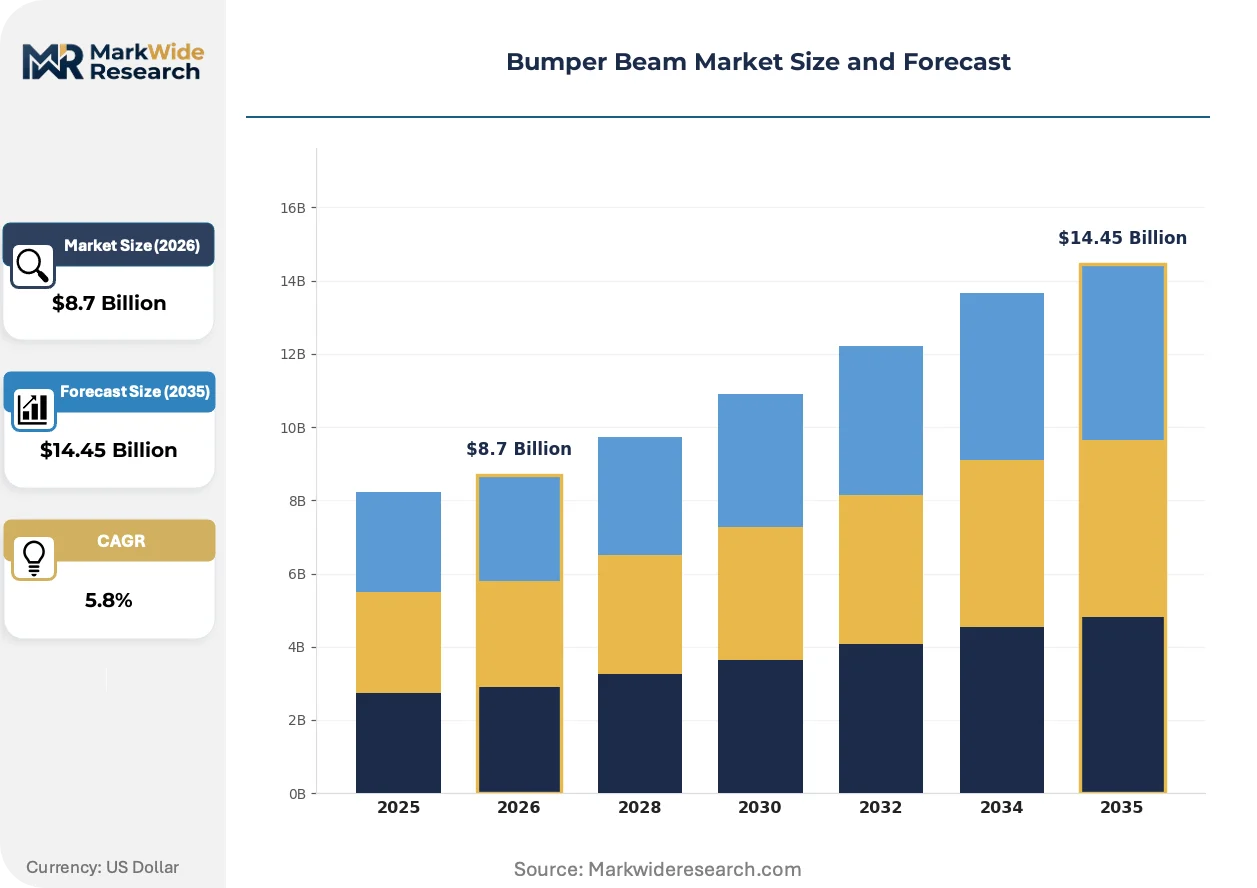
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Plastic, Composite Vehicle Type: SUVs, Sedans, Hatchbacks, Trucks Manufacturing Process: Injection Molding, Extrusion, Stamping, Casting End User: OEMs, Aftermarket Providers, Distributors, Customs |
| Companies Covered | Flex-N-Gate Corporation, Gestamp, Aisin Takaoka, KIRCHHOFF Automotive, Plastic Omnium, Benteler Deutschland, Magna International, Futaba Industrial, CIE Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bumper Beam Market Strategic Shifts
Material science convergence with active safety integration requirements is restructuring bumper beam specification criteria across OEM engineering departments, elevating electromagnetic performance alongside mechanical crash management.
Continuous fiber-reinforced thermoplastic composites deliver specific strength ratios that enable wall thickness reduction below 2.0 millimeters while maintaining ECE R42 energy absorption envelopes. Premium electrified platforms in Germany and the United States specify these materials for frontal crash structures where mass reduction preserves battery range. Aluminum stamping is overtaking steel in mid-luxury SUV segments as OEMs requalify supplier bases for 2030 platform architectures.
EU Green Deal carbon border adjustment mechanisms extend embodied carbon tracking to imported automotive components, compelling non-European suppliers to document recycled content percentages and production energy intensities. This regulatory architecture favors European-based aluminum recycling infrastructure and compresses qualification timelines for Asian suppliers lacking certified carbon accounting systems. German OEMs now mandate supplier-specific carbon disclosure as a contract precondition.
Platform engineering teams consolidate bumper beam specifications across multiple nameplates to achieve injection molding cell utilization rates above 85 percent, compressing per-unit fixed cost allocation. This procurement consolidation concentrates volume with suppliers possessing large-format plastic crash beam production capabilities, marginalizing smaller stamping houses dependent on single-platform contracts. The concentration is most visible in China where domestic OEMs pursue aggressive platform standardization strategies.
Bumper Beam Market Segmentation
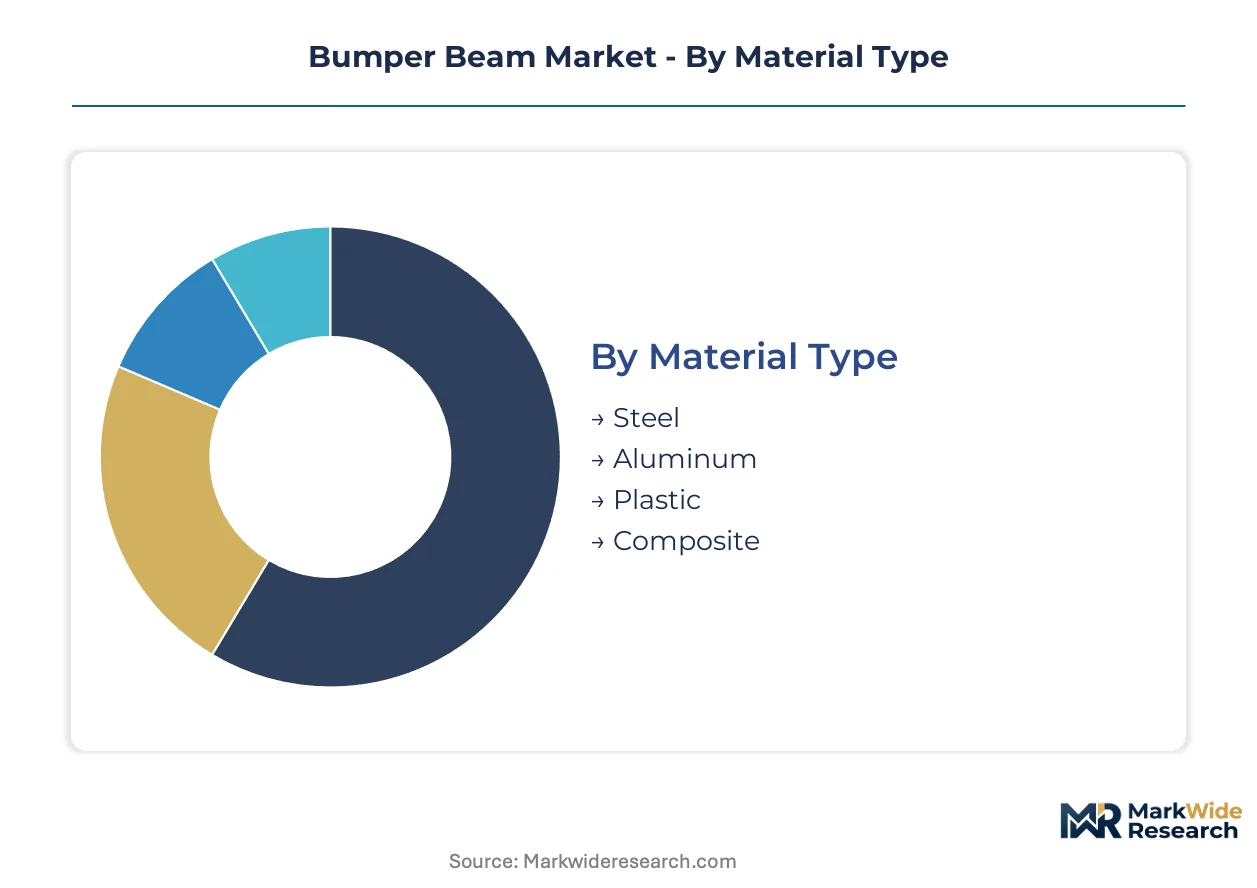
Bumper beam procurement strategies diverge sharply across material classes and manufacturing routes, with OEM qualification protocols forcing tiered supplier certification timelines that reshape competitive access. Understanding segment-level technical requirements and regulatory burdens enables suppliers to prioritize capacity investments against contract win probabilities.
Material Type:
Steel grades require only NHTSA FMVSS and ECE R42 homologation, while aluminum and composite architectures must additionally document EU Green Deal embodied carbon compliance and electromagnetic transparency for sensor integration platforms.
- Steel:Hot-rolled and cold-rolled variants utilize established stamping infrastructure with wall thickness ranging 1.8–3.0 millimeters. Entry-segment vehicle platforms in China and India specify steel for cost containment, though margin compression from aluminum substitution intensifies in European electrified SUVs.
- Aluminum:6xxx-series extrusions and stampings achieve 30–40% mass reduction versus steel equivalents at 1.5–2.5 millimeter wall thickness. German OEMs mandate recycled content certification under EU Green Deal frameworks, compressing supplier qualification timelines for primary aluminum-dependent producers.
- Plastic:Glass-fiber-reinforced polypropylene compounds serve high-volume platform standardization through injection molding cells with cycle times below 90 seconds.
- Composite:Continuous carbon-fiber thermoplastics deliver specific strength ratios enabling sub-2.0 millimeter wall thickness for premium battery-electric platforms.
Steel sits at the top of the volume ranking, with aluminum climbing the fastest as OEMs requalify supplier bases for electrified platform architectures.
Vehicle Type:
Platform engineering teams calibrate bumper beam specifications against crash pulse requirements that scale with vehicle mass and frontal impact surface area, creating tiered performance envelopes across body styles.
- SUVs:Higher mass and elevated ride height demand reinforced aluminum or hybrid steel-aluminum architectures to manage pedestrian protection compliance under ECE R42 protocols. Battery-electric SUV platforms in the United States and Germany specify composite frontal beams to offset battery pack mass.
- Sedans:Lower hood lines and reduced frontal area enable thinner-wall aluminum stampings that maintain crash energy absorption while preserving trunk volume.
- Hatchbacks:Compact segment platforms prioritize plastic bumper beams for rear impact structures where repair cost minimization drives OEM specification.
- Trucks:Commercial and heavy-duty applications retain steel architectures for durability under low-speed impact cycles and aftermarket replacement part availability.
SUVs command the highest absolute consumption value, with sedans gaining share fastest as electrified platforms proliferate in mid-luxury segments.
Manufacturing Process:
Process selection determines capital intensity, cycle economics, and OEM contract accessibility, with injection molding and stamping representing divergent competitive moats.
- Injection Molding:Large-format plastic crash beam production achieves per-unit fixed cost allocation below stamping equivalents at volumes exceeding 200,000 units annually. Chinese OEM platform consolidation drives cell utilization rates above 85 percent for qualified suppliers.
- Stamping:Progressive die and transfer press operations dominate steel and aluminum fabrication, with hot-stamping lines commanding premium positioning for ultra-high-strength steel grades.
- Extrusion:Aluminum profile production serves bumper beam applications requiring complex cross-sectional geometries for sensor mounting integration.
- Casting:High-pressure die casting enables integrated mounting bracket designs that reduce assembly complexity for premium platform segments.
Stamping retains volume leadership, with injection molding expanding most quickly as platform standardization concentrates procurement with large-format plastic beam specialists.
End User:
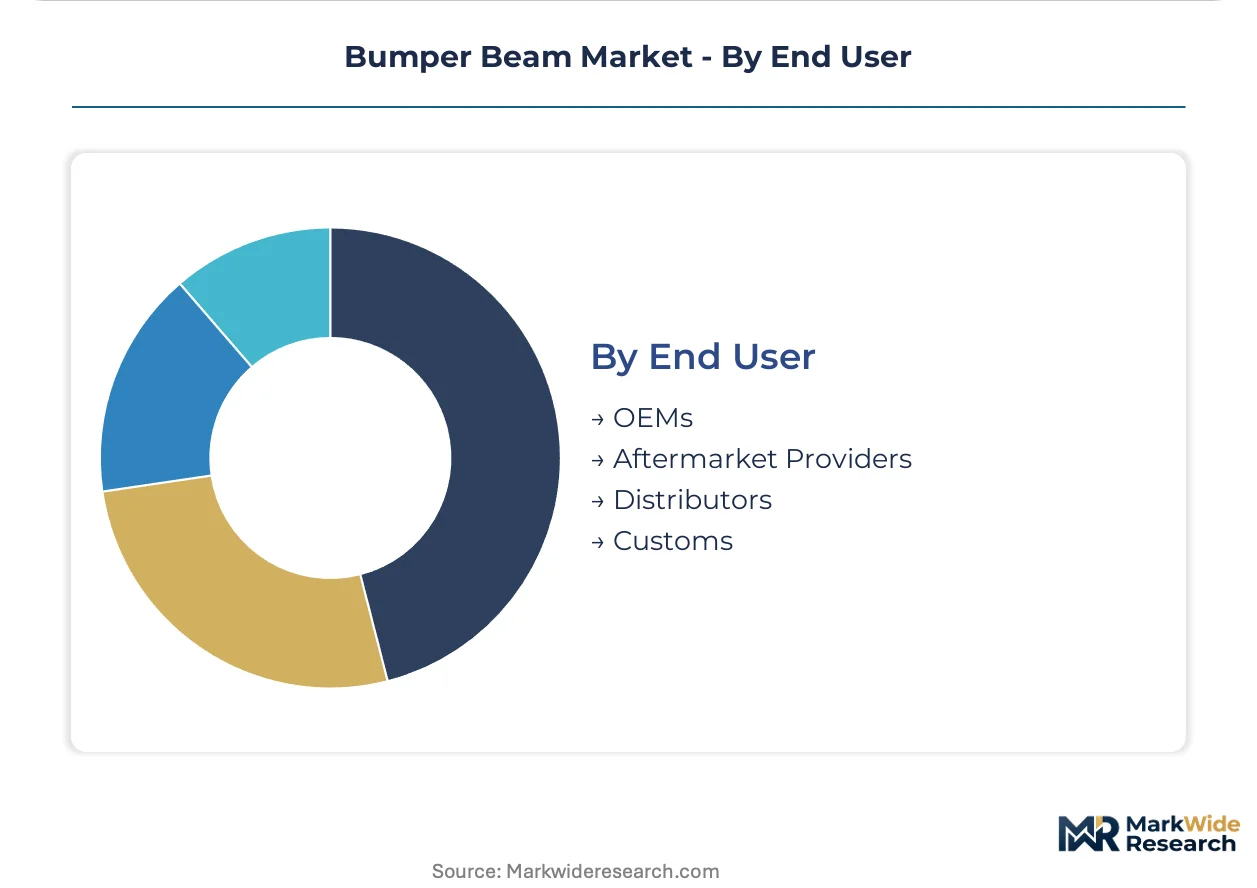
Channel structure determines margin capture and technical specification authority, with OEM direct contracts requiring full homologation investment versus aftermarket channels serving legacy fleet replacement demand.
- OEMs:Direct platform engineering engagement mandates full NHTSA, ECE R42, and China GB certification with multi-year contract horizons. German and US OEMs now require supplier carbon disclosure as contractual preconditions under EU Green Deal frameworks.
- Aftermarket Providers:E-commerce distribution platforms enable direct-to-repair-shop steel bumper beam sales that bypass traditional tiered distribution markups for legacy fleet maintenance.
- Distributors:Regional inventory holding and logistics services bridge OEM supply chains with smaller repair networks lacking direct manufacturer relationships.
- Customs:Specialized vehicle modification and armoring segments specify reinforced bumper beam architectures outside standard OEM performance envelopes.
OEMs dominate value capture, with aftermarket providers gaining operational leverage fastest through digital channel disintermediation of traditional distribution tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern automotive crash management engineering through supplier clusters in Baden-Württemberg and Bavaria, establishing technical protocols that shaped bumper beam qualification standards across export markets.
China
Domestic OEM electrification programs in Shanghai and Guangzhou drive aluminum bumper beam specification for battery-electric SUVs. SAMR enforces GB standards that align with UN ECE R42 crash pulse protocols. Yangtze River Delta manufacturing clusters host injection molding specialists serving platform-standardized procurement contracts.
Germany
EU Green Deal embodied carbon mandates force supplier requalification for recycled aluminum architectures in Stuttgart and Wolfsburg engineering centers. KBA administers type approval under ECE R42 frameworks with additional carbon disclosure preconditions. North Rhine-Westphalia stamping houses retrofit hot-forming lines for ultra-high-strength steel competitiveness.
United States
Detroit Three electrified truck platforms specify hybrid steel-aluminum bumper beams for mass management. NHTSA Federal Motor Vehicle Safety Standards govern frontal impact energy absorption with pending updates for autonomous vehicle sensor integration. Michigan and Ohio supplier parks concentrate stamping and aluminum extrusion capacity for domestic OEM contracts.
India
PLI scheme incentives for advanced automotive components attract aluminum bumper beam investment for Maruti Suzuki and Tata Motors electrification programs. BIS harmonizes crash test protocols with UN regulations under Automotive Industry Standards. Tamil Nadu and Gujarat manufacturing corridors host emerging tier-1 supplier qualification for export-oriented OEM supply chains.
Japan
Keiretsu supply relationships sustain steel bumper beam dominance in entry-segment platforms while aluminum gains share in premium battery-electric nameplates. METI coordinates JIS standards alignment with international crash safety frameworks. Aichi Prefecture engineering clusters specialize in integrated sensor mounting solutions for autonomous vehicle programs.
Bumper Beam Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification and OEM platform access tiers. The vendor base stratifies between integrated multi-material specialists and single-process stamping houses dependent on legacy steel contracts. Three archetypes dominate: aluminum recycling-integrated suppliers, large-format plastic injection molders, and hybrid structure engineering houses. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for 2030 platform requalification windows.
Among European-integrated specialists, Gestamp and Benteler Deutschland occupy positions spanning steel hot-stamping and aluminum capacity expansion. Plastic Omnium anchors the plastic beam tier through injection molding cell control. These three exemplify divergent strategic postures: Gestamp represents steel-aluminum hybrid competitiveness, Benteler Deutschland exemplifies roll-formed lightweight structures, and Plastic Omnium sits within the polymer consolidation vector.
| Leading Market Players |
|---|
| Flex-N-Gate Corporation |
| Gestamp |
| Aisin Takaoka |
| KIRCHHOFF Automotive |
| Plastic Omnium |
| Benteler Deutschland |
| Magna International |
| Futaba Industrial |
| CIE Automotive |
| Others |
Value Chain & Pricing Dynamics
Primary aluminum ingot costs transmit directly from London Metal Exchange pricing through to Tier 1 supplier quotations, with volatility in that upstream input compressing margin predictability for European stamping houses committed to lightweight capacity expansion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates composite beam specifications for battery-electric SUVs from aluminum stampings in mid-luxury sedans and steel variants serving entry-segment platforms in India and China. Price differentiation rests on EU Green Deal carbon certification status and electromagnetic transparency ratings for sensor-integrated architectures. Cost compression in steel replacement channels is intensifying because aftermarket e-commerce platforms disintermediate traditional distribution markups. OEM direct contracts show lowest price sensitivity due to multi-year platform engineering commitments, whereas independent repair shops drive hardest bargaining for legacy fleet steel components.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta injection molding cell operators serving Chinese OEM platform consolidation strategies. Manufacturing concentration clusters in Germany, China, and the United States, with secondary nodes emerging in Tamil Nadu and Gujarat corridors under India's PLI scheme. Raw material feeds draw from primary aluminum smelters in the Middle East, recycled aluminum processors in Spain, and glass-fiber compounders serving polypropylene beam production. Tariff exposure on aluminum extrusions threatens margin stability for North American suppliers dependent on Canadian and Mexican cross-border feedstock. Distribution runs through OEM direct procurement for new vehicle platforms, with aftermarket channels fragmenting toward direct-to-repair-shop digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification authority is concentrating with suppliers possessing EU Green Deal carbon certification and large-format plastic beam production capabilities. OEM procurement consolidation across platform architectures favors multi-material specialists over single-process stamping houses.
For Market Incumbents: Anticipate margin compression from aluminum substitution in European electrified SUVs by retrofitting hot-forming lines for ultra-high-strength steel competitiveness while expanding recycled aluminum capacity across Spanish and German plants. Defensive consolidation through backward integration into post-consumer aluminum feedstock processing secures carbon certification timelines under EU Green Deal frameworks. Channel control through captive aftermarket distribution platforms protects legacy steel replacement revenue against e-commerce disintermediation.
For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for advanced automotive components, targeting aluminum bumper beam qualification for Maruti Suzuki and Tata Motors electrification programs where domestic supplier bases remain underdeveloped. White-space concentration sits with electromagnetically transparent composite architectures for autonomous vehicle sensor integration platforms in premium German and US nameplates. Go-to-market leverage flows from partnership with injection molding cell technology licensors rather than greenfield capacity construction.
For Investors and Strategic Acquirers: Consolidation pressure builds where single-platform stamping houses face procurement volume concentration toward large-format plastic beam specialists with 85 percent cell utilization rates. Long-term viability favors aluminum recycling-integrated suppliers with documented carbon accounting systems and hybrid structure engineering capabilities spanning steel hot-stamping and composite design. Watch for inflection in OEM mandates requiring supplier-specific carbon disclosure as contractual preconditions under evolving EU border adjustment mechanisms.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Aluminum Capacity Expansion | Secures EU Green Deal carbon certification for German OEM platform requalification windows. |
| Injection Molding Cell Technology Licensing | Enables new entrant qualification for Chinese OEM platform standardization contracts. |
| Hybrid Steel-Aluminum Structure Development | Bridges cost economics of steel with mass savings for Detroit Three electrified truck platforms. |
| Aftermarket E-Commerce Platform Launch | Bypasses tiered distribution markups for legacy fleet steel bumper beam replacement demand. |
| Sensor Integration Design Partnership | Opens specification windows for electromagnetically transparent composite materials in premium segments. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down supplier capacity tracking forms the analytical core, combining primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and regulatory affairs specialists with secondary validation from NHTSA FMVSS filings, ECE R42 type approval databases, SAMR GB standard enforcement records, and vehicle registration data from IHS Markit production tracking systems.
Input-output matrices map material-grade demand against manufacturing process capacity across vehicle class, propulsion architecture, and regional production cluster dimensions throughout the forecast period. CAGRs derive from segment-level volume trajectories weighted by content-per-vehicle assumptions and OEM platform lifecycle phasing, with aluminum substitution elasticity and EU carbon border adjustment implementation timelines serving as key sensitivity inputs.
Inputs from OEM engineering centers and Tier 1 supplier technical directors were available through the study window; gaps in post-consumer aluminum feedstock qualification protocol documentation introduce uncertainty bands around recycled content penetration assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market
Automotive Parts
Air Springs Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Hydraulic Lash Adjuster Market
Automotive Parts
Mobile Emission Catalysts Market