
 South America Electric Vehicle Battery Manufacturing Market | 2026-2036
South America Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Battery Manufacturing Market Insights
Cell refurbishment and second-life battery services is rewriting margin allocation across the value chain. BYD Co Ltd leverages integrated cell-to-pack architectures to dominate Brazil's OEM supply channels. Albemarle Corporation anchors lithium hydroxide output from Chilean salares, sustaining upstream feedstock security for regional cathode plants. Umicore SA specializes in precursor chemistries, positioning its Antwerp-developed know-how within South American tolling arrangements.
South America electric vehicle battery manufacturing encompasses the industrial production of electrochemical energy storage devices, typically employing lithium iron phosphate or nickel-manganese-cobalt cathode formulations with graphite or silicon-composite anodes, assembled through electrode coating, cell formation, and module integration processes designed to power traction motors in road vehicles. Lithium-ion chemistries currently occupy the majority of regional capacity commitments due to proven energy density and cycle life metrics. Fast Charging technology leads investment prioritization among fleet operators seeking depot turnaround minimization, while Battery Management Systems represents the fastest-growing technology segment as thermal runaway prevention becomes mandatory for OEM homologation. Small Scale and Medium Scale capacity tiers concentrate near research institutions in São Paulo and Santiago, whereas Large Scale manufacturing clusters around automotive OEM demand in southern Brazil.
Brazil's ANP biofuel-electric convergence policies and Argentina's mining secretariat lithium export frameworks, alongside Chile's CORFO concession terms for salar brine extraction, collectively shape feedstock access and cell production economics across the region. ANVISA in Brazil and the national standards bodies in Chile and Argentina enforce cell safety testing protocols that determine market entry timelines for imported versus locally assembled packs. Stakeholders must monitor lithium carbonate-hydroxide conversion capacity commitments against cathode plant construction schedules to assess regional supply chain completion.
Market Dynamics
Argentina's lithium extraction governance under its national mining secretariat is redirecting cathode supply chains toward domestic processing, compressing feedstock transit times and altering margin allocation across the regional value chain.
Growth Catalysts
- Fleet Electrification Mandates:Brazil's São Paulo industrial corridor hosts automotive OEMs anchoring cell assembly investments, pulling demand from logistics operators scaling electrified procurement.
- Lithium Hydroxide Conversion:Chilean salares brine extraction under CORFO concession terms sustains upstream feedstock security for regional cathode plants.
- Fast Charging Infrastructure:Depot turnaround minimization requirements from Brazilian and Argentine fleet operators prioritize high-power charging technology deployment.
Market Restraints
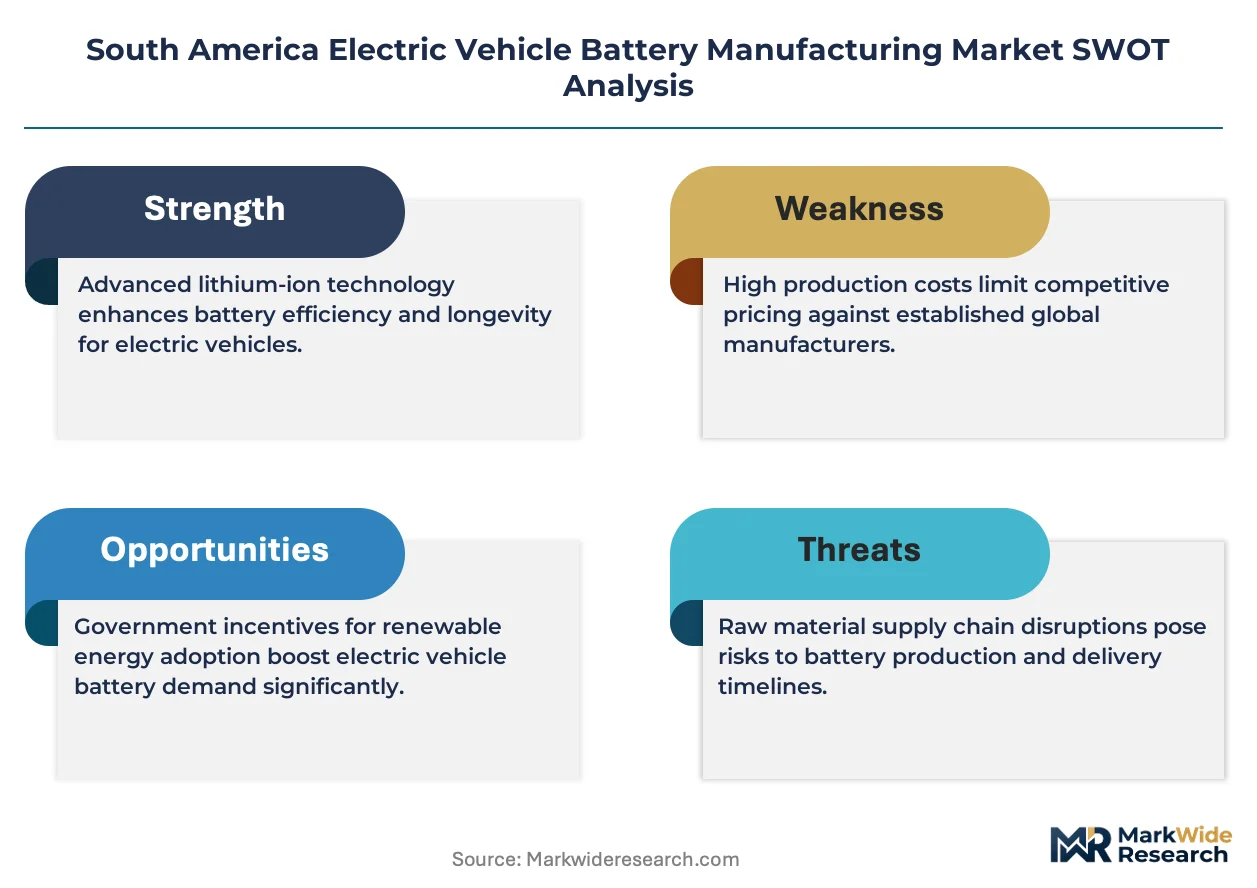
- Lithium Carbonate Price Volatility:Salar brine extraction concentration in Chile's Atacama basin exposes cathode precursor economics to single-source supply risk.
- ANVISA Cell Safety Protocols:Brazil's national health surveillance agency enforces testing timelines that delay market entry for imported versus locally assembled battery packs.
- Graphite Anode Dependence:Synthetic and natural graphite supply concentration outside the region constrains anode material localization efforts.
Strategic Opportunities
- Second-Life Battery Services:Cell refurbishment capabilities near São Paulo and Santiago research institutions capture margin from end-of-life electric bus and truck packs.
- Biofuel-Electric Convergence:Brazil's ANP policy frameworks create hybrid powertrain applications bridging ethanol infrastructure with battery electric deployment.
- Battery Management Systems Localization:Thermal runaway prevention mandates for OEM homologation drive domestic BMS software and hardware assembly.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell formation and electrode coating process expertise concentrates in São Paulo and Santiago, constraining workforce scaling for new plant construction.
- Cathode Plant Synchronization:Lithium carbonate-hydroxide conversion capacity commitments must align with regional precursor chemistry facility buildout schedules.
- Module Integration Standardization:Divergent automotive OEM pack specifications complicate tolling arrangements and contract manufacturing economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Battery Manufacturing Market |
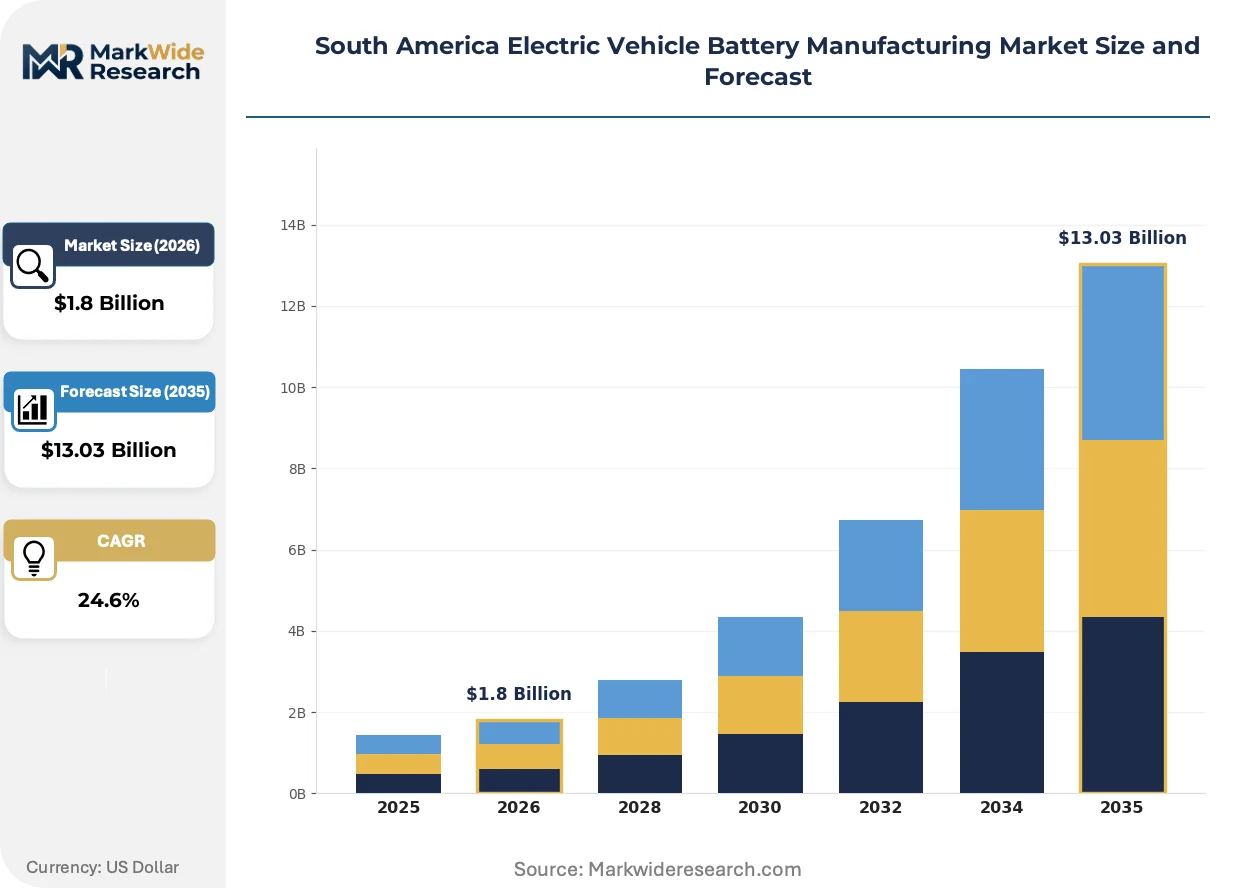
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
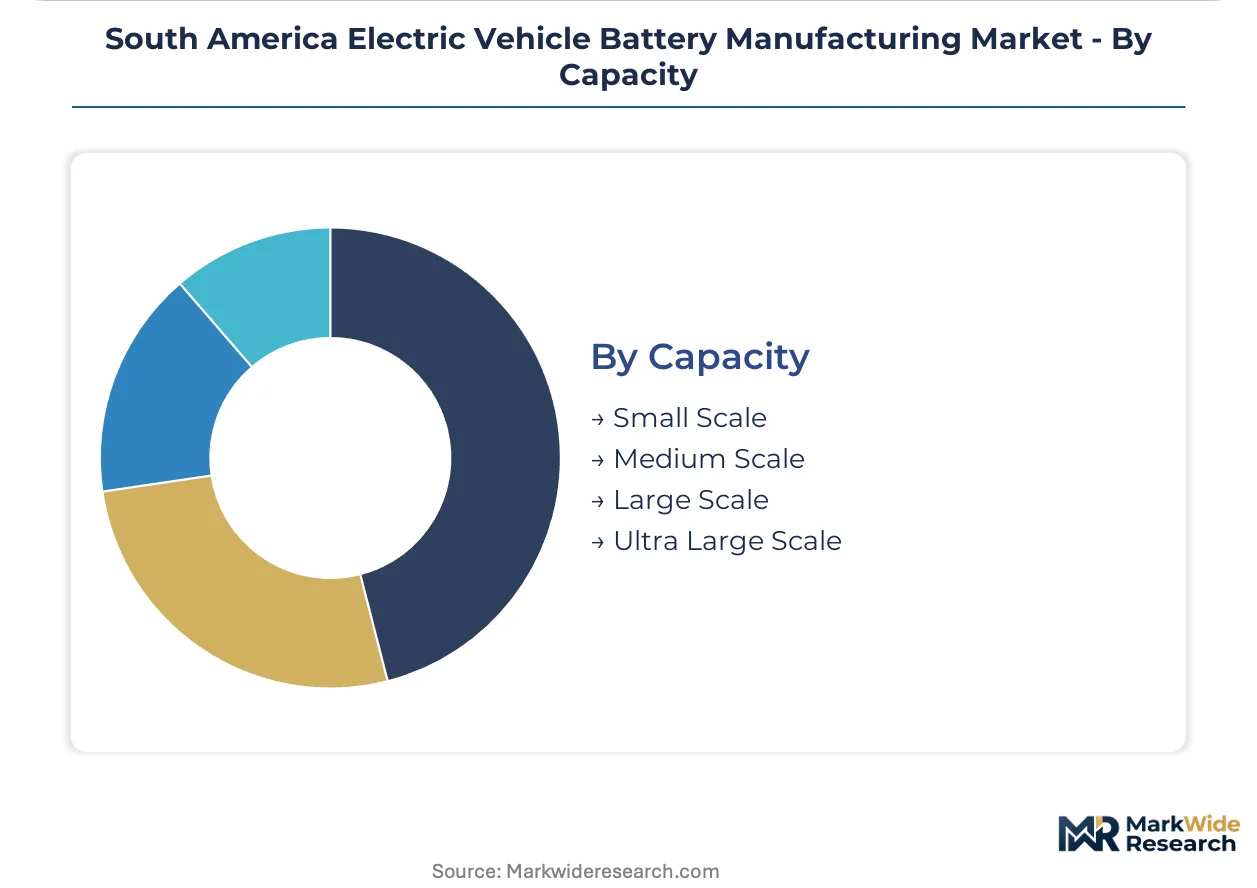
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state End User: Automotive OEMs, Battery Manufacturers, Research Institutions, Fleet Operators Technology: Fast Charging, Battery Management Systems, Thermal Management, Energy Density Improvement Capacity: Small Scale, Medium Scale, Large Scale, Ultra Large Scale |
| Companies Covered | BYD Co Ltd, BASF SE, Albemarle Corporation, Umicore SA, Mitsubishi Chemical Group Corporation, UBE Corporation, Livent, Hitachi Ltd., Duerr AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell-to-pack architectures and silicon-composite anode formulations are compressing traditional module integration steps, while thermal management software and fast charging protocols reshape competitive differentiation across the regional manufacturing base.
Lithium iron phosphate cathode formulations are migrating from energy storage backup applications into Brazil's electric bus and commercial vehicle segments. Fleet operators in São Paulo and Rio de Janeiro procurement channels specify LFP cells for depot-charged logistics vehicles, prioritizing cycle life over energy density. This chemistry shift is migrating from niche stationary storage into high-utilization mobility applications, compressing nickel-manganese-cobalt dominance in the medium-duty commercial segment.
Argentina's national mining secretariat lithium export frameworks now mandate domestic value-add processing before raw brine or spodumene concentrate exit. Industrial consequence includes cathode precursor plant siting decisions clustering near Salta and Jujuy provincial extraction zones. Brazilian and Chilean cathode manufacturers are responding by negotiating tolling partnerships with Argentine lithium hydroxide converters rather than importing unprocessed feedstock.
Logistics fleet procurement committees now specify battery residual value guarantees and second-life service contracts as standard tender requirements. Traditional pack-only sales models face displacement from lifecycle service agreements bundling cell monitoring, refurbishment, and material recovery. This contractual evolution is most visible in Brazil's São Paulo state freight corridor, where electrified last-mile operators negotiate total-cost-of-ownership structures with cell assemblers.
South America Electric Vehicle Battery Manufacturing Market Segmentation
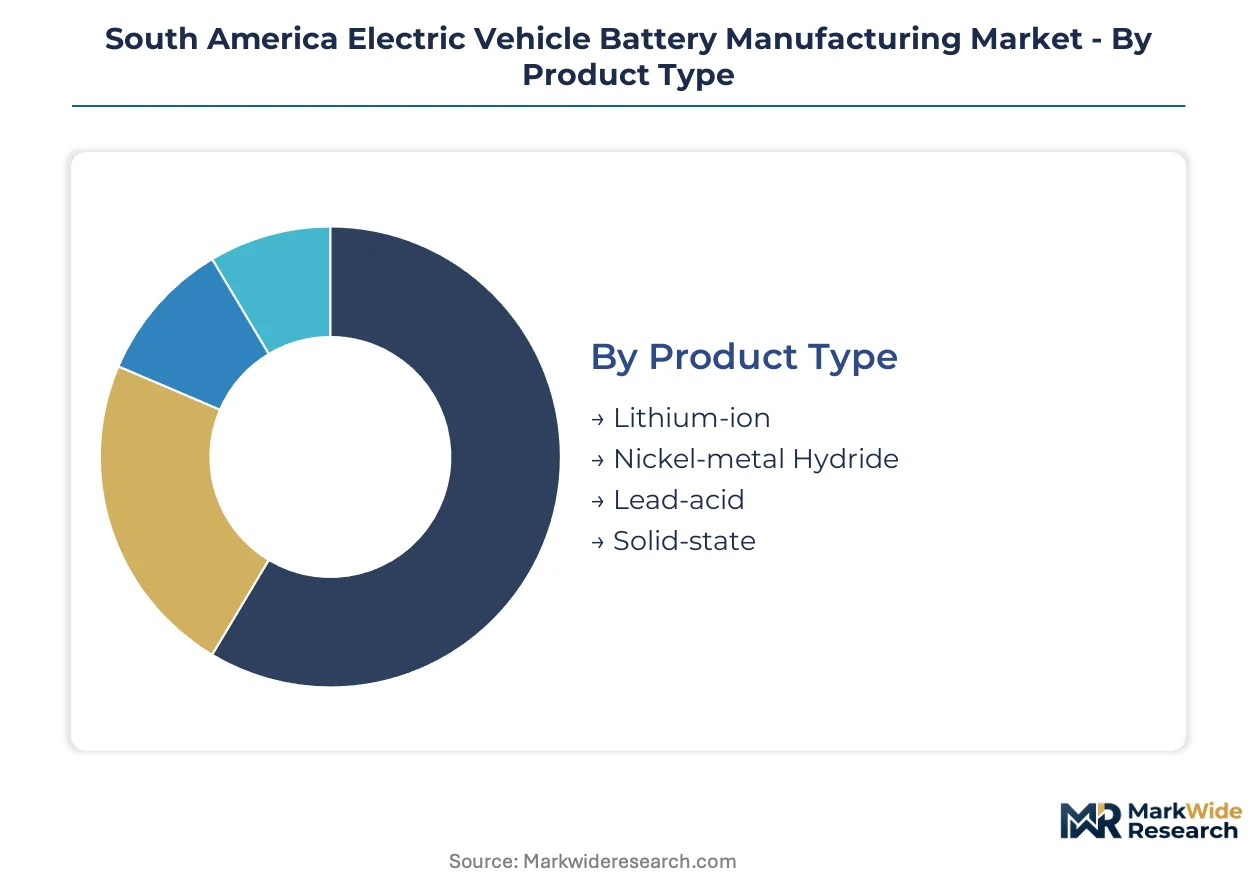
Segmentation in South America electric vehicle battery manufacturing reveals how distinct technical specifications, customer procurement patterns, and production scale tiers create specialized competitive arenas. Each dimension carries unique regulatory, talent, and capital requirements that shape investment allocation across Brazil, Argentina, and Chile.
Product Type:
Chemistry selection determines energy density, cycle life, and thermal stability profiles that align with specific mobility applications and local feedstock availability.
- Lithium-ion:Lithium iron phosphate and nickel-manganese-cobalt formulations dominate regional cell assembly, leveraging Chilean salar brine and Argentine spodumene extraction. São Paulo automotive OEMs anchor procurement for electric bus and commercial vehicle integration, prioritizing proven cycle life metrics over experimental chemistries.
- Solid-state:Sulfide and oxide electrolyte architectures promise enhanced energy density and fire-safety profiles, though manufacturing scale remains constrained by electrode-electrolyte interface engineering challenges. Research institutions in Santiago and São Paulo concentrate pilot-line validation work for future OEM qualification.
- Nickel-metal Hydride:Mature chemistry retains niche deployment in hybrid electric vehicle auxiliary power units where cost sensitivity outweighs energy density requirements.
- Lead-acid:Conventional flooded and absorbed glass mat designs persist in low-voltage starter battery replacement markets and industrial forklift applications.
Lithium-ion holds installed capacity across Brazilian and Chilean cell assembly corridors. Solid-state is rotating up the share rankings as ANVISA safety protocols tighten thermal runaway prevention requirements.
End User:
Customer type dictates contract structure, volume commitment patterns, and technical specification authority across the value chain.
- Automotive OEMs:Volkswagen, BYD, and Stellantis anchor demand through São Paulo industrial corridor investments, specifying pack dimensions, thermal management interfaces, and homologation testing protocols that determine cell supplier qualification timelines.
- Fleet Operators:Brazilian last-mile logistics and Argentine mining transport procurement committees negotiate total-cost-of-ownership contracts bundling residual value guarantees with second-life battery service agreements.
- Battery Manufacturers:Regional cell assemblers purchase electrode materials, separators, and electrolyte formulations from upstream chemical processors under tolling arrangements or captive supply contracts.
- Research Institutions:Universidade de São Paulo and Universidad de Chile host pilot-scale electrode coating and cell formation facilities that validate next-generation chemistries for technology transfer to commercial manufacturers.
Automotive OEMs concentrate specification authority and volume commitments. Fleet operators are climbing the fastest as electrified logistics procurement scales across Mercosur freight corridors.
Technology:
Functional technology layers determine charging performance, safety compliance, and thermal control capabilities that differentiate competitive offerings.
- Fast Charging:High-power charging protocols and cooled cable architectures minimize depot turnaround times for Brazilian and Argentine commercial vehicle operators running double-shift utilization patterns.
- Battery Management Systems:Cell monitoring firmware and hardware assemblies track state-of-charge, state-of-health, and thermal runaway precursors, with ANVISA and Chilean standards bodies mandating functional safety certification for OEM homologation.
- Thermal Management:Liquid cooling plates, phase change materials, and active heating circuits maintain cell operating windows across Brazil's tropical temperature excursions and Argentine Andean altitude variations.
- Energy Density Improvement:Silicon-composite anode and high-nickel cathode research programs target gravimetric and volumetric performance gains for premium passenger vehicle range extension.
Fast Charging commands capital allocation from fleet electrification mandates. Battery Management Systems is gaining share fastest as regulatory safety requirements harden across Mercosur markets.
Capacity:
Production scale tiers align with customer order volumes, capital intensity thresholds, and geographic proximity to demand clusters or research talent pools.
- Large Scale:Giga-scale cell and module assembly facilities cluster near automotive OEM plants in southern Brazil, deploying electrode coating lines and formation chambers that serve continental vehicle production programs.
- Small Scale:Pilot and demonstration lines concentrate near São Paulo and Santiago universities, validating new chemistries and manufacturing processes before capital-intensive scale-up commitments.
- Medium Scale:Regional contract manufacturers assemble packs from imported cells for niche commercial vehicle and stationary storage applications.
- Ultra Large Scale:Integrated mining-to-cell vertical complexes remain aspirational, contingent on Argentine lithium hydroxide conversion capacity synchronization with Brazilian cathode precursor plant schedules.
Large Scale commands committed capacity investments from São Paulo OEM demand. Small Scale is ascending fastest as research-commercialization pipelines shorten across regional innovation clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian fleet operators prioritize depot-charged logistics configurations, while Argentine mining corridors favor high-cycle-life chemistries for altitude-variable terrain. Chilean OEM integration demands diverge from both, emphasizing fast-charging compatibility for passenger vehicle range anxiety mitigation.
Brazil
São Paulo's freight corridor drives electrified last-mile procurement from logistics operators running double-shift utilization. ANP biofuel-electric convergence policies create hybrid powertrain pathways bridging ethanol infrastructure with battery deployment. The ABC Paulista industrial belt anchors cell assembly investments from Volkswagen and Stellantis, pulling electrode coating capacity toward southeastern manufacturing zones.
Argentina
Salta and Jujuy provincial mining transport fleets specify lithium iron phosphate cells for high-altitude thermal stability. The national mining secretariat mandates domestic hydroxide conversion before raw brine export, compressing cathode precursor plant siting decisions near extraction zones. Córdoba's automotive component cluster hosts pilot-scale module integration for Mercosur vehicle assembly programs.
Chile
Santiago-based research institutions validate silicon-composite anode formulations for premium passenger vehicle applications. CORFO concession terms for Atacama salar brine extraction sustain upstream carbonate-hydroxide feedstock security. Antofagasta's northern logistics operators test fast-charging protocols for copper mine haulage electrification pilots.
Colombia
Bogotá's urban bus rapid transit procurement specifies battery residual value guarantees in tender documentation. The national mining and energy planning unit frames lithium-ion storage as grid stabilization adjunct to hydroelectric generation. Medellín's manufacturing corridor attracts medium-scale pack assemblers serving Andean commercial vehicle retrofit markets.
South America Electric Vehicle Battery Manufacturing Market Competitive Landscape
Capability concentration sits with integrated chemistry developers; scale advantage sits with automotive-aligned cell assemblers. The market structures around three tiers: upstream lithium converters anchoring feedstock security, cathode precursor specialists tolling regional arrangements, and OEM-captive pack integrators controlling specification authority. Dominant competitive moves include backward integration into hydroxide conversion and strategic partnerships bridging Argentine extraction with Brazilian assembly capacity.
Within the integrated cell-to-pack tier, BYD Co Ltd anchors OEM supply channel positioning through São Paulo industrial corridor proximity. Albemarle Corporation exemplifies upstream feedstock concentration, leveraging Chilean salar concessions for regional carbonate-hydroxide output. Umicore SA occupies the precursor chemistry specialist position, deploying Antwerp-developed know-how within South American tolling structures.
| Leading Market Players |
|---|
| BYD Co Ltd |
| BASF SE |
| Albemarle Corporation |
| Umicore SA |
| Mitsubishi Chemical Group Corporation |
| UBE Corporation |
| Livent |
| Hitachi Ltd. |
| Duerr AG |
| Others |
Pricing and Supply Chain Analysis
Single-source graphite anode dependency determines both pricing tier spreads and supply chain shape across South American cell assembly corridors. ANVISA certification timelines for imported versus locally assembled packs compress margin structures at the economy tier while premium pricing sustains backward integration into Argentine lithium hydroxide conversion.
Pricing Analysis
Long-term offtake contracts dominate cathode precursor procurement, with Chilean carbonate-hydroxide converters locking annual volume commitments from Brazilian cell assemblers. Price differentiation rests on ANVISA homologation tier and cathode chemistry grade, with LFP-certified packs commanding premium spreads over uncertified NMC alternatives. Cost compression in the economy tier intensifies as Argentine mining secretariat mandates force tolling arrangement renegotiations. Fleet operators exhibit highest price sensitivity, while automotive OEMs absorb premium tier spreads for specification authority.
Supply Chain Analysis
Toll manufacturing concentrates with Umicore's Antwerp-developed precursor know-how deployed through South American partnerships, alongside BYD's integrated cell-to-pack facilities anchoring São Paulo corridor capacity. Geographic supply concentration centers on Chile for lithium carbonate, Argentina for hydroxide conversion, and China for synthetic graphite anodes. Raw material dependencies span spodumene concentrate, electrolyte salts, and separator membranes. Single-source vulnerability in graphite supply constrains anode localization timelines. Distribution runs through OEM-captive channels for large-scale volume and regional contract manufacturers for medium-scale retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service platform economics are displacing pack-only transactions, with interoperability standards across Mercosur freight corridors enabling residual value monetization at end-of-life.
For Market Incumbents: Pre-empt second-life service displacement by acquiring cell refurbishment capabilities near São Paulo research clusters. Secure captive lithium hydroxide offtake from Salta-Jujuy conversion plants before Argentine export restrictions harden. ANVISA thermal runaway prevention mandates threaten import-dependent margin structures. For New Entrants and Emerging Players: Colombia's Andean commercial vehicle retrofit markets offer lowest competitive density for medium-scale pack assemblers. Target Bogotá bus rapid transit procurement channels specifying residual value guarantees as entry wedge. Partner with Medellín manufacturing corridor distributors for aftermarket service reach. For Investors and Strategic Acquirers: The market sits at a feedstock-security phase that favors upstream-integrated specialists over pure-play assemblers. Five-to-ten year viability hinges on lithium carbonate-hydroxide conversion capacity synchronization with cathode plant schedules. Monitor Argentine mining secretariat processing mandate enforcement as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Hydroxide | Argentine mining secretariat mandates compress margin capture for domestic converters. |
| Second-Life Battery Service Platform | São Paulo fleet operators now specify residual value guarantees in standard tenders. |
| ANVISA Thermal Runaway Certification | Homologation timelines differentiate imported from locally assembled pack pricing tiers. |
| Fast Charging Infrastructure Partnership | Brazilian depot turnaround requirements pull high-power protocol deployment. |
| Cell-to-Pack Architecture Standardization | BYD's integrated designs compress module integration steps across OEM supply channels. |
Research Methodology
A standing panel of cathode plant engineering directors, ANVISA regulatory affairs leads, fleet procurement managers at São Paulo logistics operators, and lithium extraction project developers provided ongoing calibration. Primary interview findings triangulated against CORFO concession documentation, Argentine mining secretariat export framework filings, Brazilian customs trade data, and automotive OEM SEC disclosures. Bottom-up cell formation capacity estimates reconciled with top-down vehicle production program commitments.
Scenario-bracketing around lithium carbonate price volatility and ANVISA certification timeline variations shaped projection outputs across the analysis window. Segmentation dimensions modeled include cathode chemistry formulation, end-user contract structure, production capacity tier, and Mercosur regulatory cluster. CAGRs derived from electrolyte demand elasticity and fleet electrification procurement trajectories. Silicon-composite anode pilot validation timelines and solid-state electrolyte interface engineering milestones informed technology adoption curves.
Practitioners should monitor Argentine hydroxide conversion capacity construction delays and Chilean salar brine extraction quota adjustments for early signals of feedstock constraint. Forecasts reflect assumptions on OEM localization commitments and fleet operator residual value guarantee adoption. Quarterly review of ANVISA homologation queue lengths and CORFO concession renegotiation outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United States Electric Vehicle Battery Materials Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Canada EV Battery Pack Market