
 Lead Acid Battery Recycling Market | 2026-2036
Lead Acid Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Acid Battery Recycling Market Intelligence
Market Context
Chinese secondary lead smelters is expanding capacity to process spent automotive batteries from domestic OEM take-back programs. Gravita India Limited leverages integrated lead smelting and plastic recovery operations across Rajasthan and Gujarat to capture margin from both metal and polypropylene outputs. Exide Industries Limited anchors its recycling footprint through captive collection tied to its original equipment battery distribution network. Aqua Metals, Inc. differentiates via electrochemical recycling technology that eliminates high-temperature smelting from its Nevada operations.
Technical Definition and Segment Structure
Lead acid battery recycling recovers lead metal, lead alloys, and polypropylene casings from spent flooded, AGM, and gel-cell batteries through smelting, hydrometallurgical extraction, or mechanical separation, yielding secondary lead suitable for new battery production with purity exceeding 99.97 percent. Automotive battery types dominate feedstock inflows due to high vehicle parc turnover and established dealer return channels, while hydrometallurgical processes represent the fastest-expanding technology segment as operators seek lower-emission alternatives to conventional blast furnaces. Pyrometallurgical routes retain margin concentration in regions with permissive emissions frameworks and existing smelter infrastructure.
Regulatory Environment and Outlook
The EPA enforces RCRA subtitle C requirements for spent lead acid battery handling, while the EU REACH regulation and Battery Directive constrain lead content thresholds and mandate collection rate minimums across member states. India's Ministry of Environment, Forest and Climate Change implements hazardous waste management rules that classify used batteries as mandated return goods, compelling OEMs to establish authorized collection centers. Stakeholders must monitor evolving carbon border adjustments and state-level extended producer responsibility expansions that will reshape feedstock access economics and processing site selection.
Market Dynamics
Electrochemical recycling technology is absorbing capital flows that previously fed conventional blast furnace retrofits, compressing the investment timeline for zero-emission lead recovery and forcing incumbents to defend smelter-based margins against lower-carbon entrants.
Growth Catalysts
- Extended Producer Responsibility Mandates:India's hazardous waste management rules compel OEMs to establish authorized collection centers, tightening feedstock capture rates and reducing informal sector arbitrage.
- Automotive Fleet Electrification Residual:Internal combustion vehicle parc turnover generates sustained spent battery volumes even as EV penetration rises, with dealer return channels ensuring predictable collection inflows.
- Carbon Border Adjustment Mechanisms:The EU's CBAM is redirecting secondary lead trade flows toward certified low-emission sources, rewarding operators with verified Scope 1-3 reductions.
Market Restraints
- Lead Price Volatility:London Metal Exchange lead pricing swings compress smelter margins and destabilize long-term offtake contracting for secondary producers.
- Smelter Concentration Risk:Chinese secondary lead capacity dominates global processing volumes, creating single-point vulnerability for feedstock pricing and export quota disruptions.
- Technical Limitation in Electrochemical Scale:Aqua Metals-type modular units face throughput ceilings versus blast furnace batch sizes, constraining unit economics at industrial scale.
Strategic Opportunities
- Underpenetrated African Collection Networks:Informal recycling dominates across Nigeria, Egypt, and South Africa, presenting structured investment openings for compliant collection infrastructure.
- Polypropylene Upcycling Integration:Battery casing recovery streams can feed automotive-grade recycled plastic specifications, capturing margin from circular material mandates.
- State-Level EPR Expansions:California and New York extended producer responsibility frameworks are tightening collection rate floors, advantaging operators with established reverse logistics.
Industry Challenges
- Smelter Operator Skill Migration:Electrochemical process chemistry demands electrochemical engineering competencies distinct from pyrometallurgical traditions, constraining workforce transition.
- Capex Intensity for Emissions Compliance:Baghouse upgrades and acid mist containment systems require substantial retrofit investment at legacy facilities.
- RCRA Manifesting Complexity:EPA hazardous waste documentation creates administrative friction for multi-state collection networks and cross-border feedstock movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Acid Battery Recycling Market |
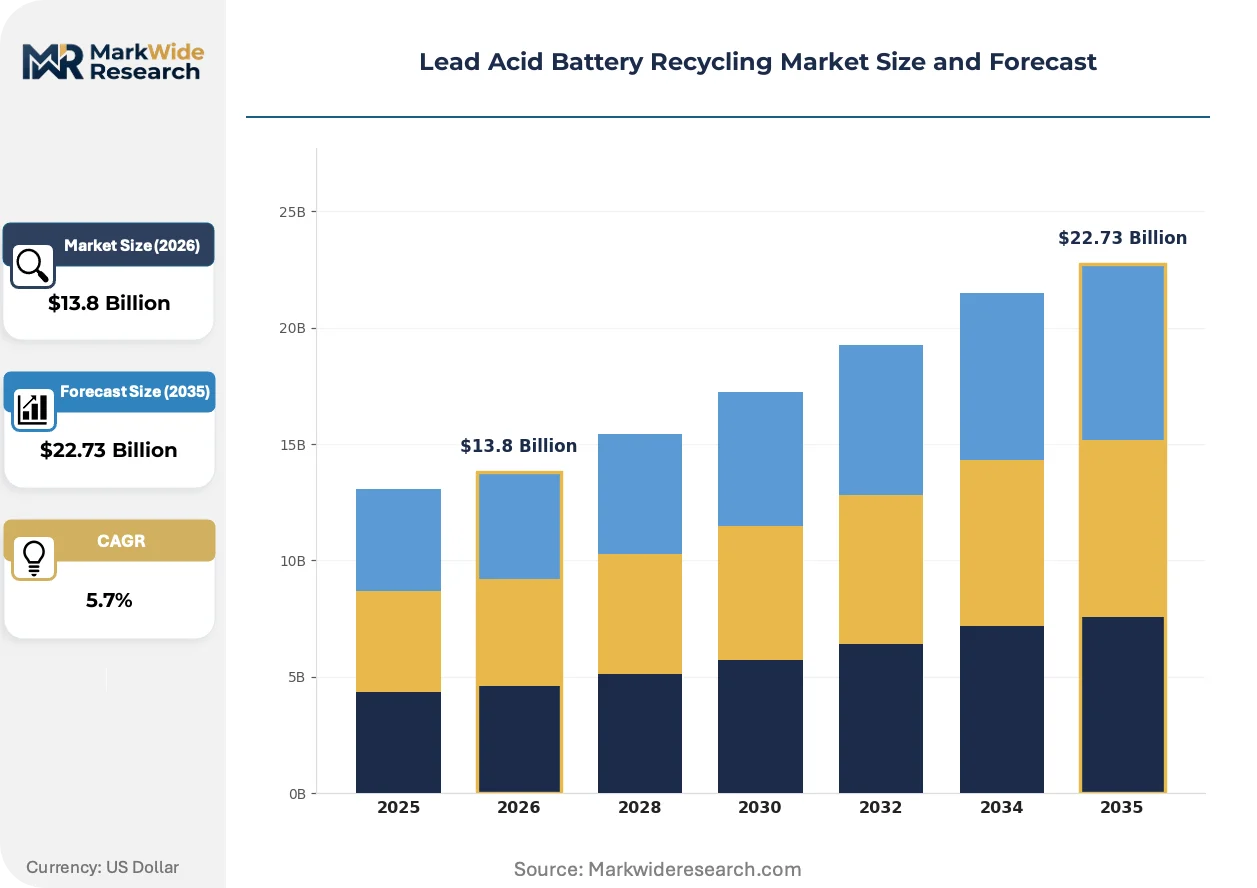
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Automotive, Industrial, Solar, UPS, Telecommunications Recycling Process: Pyrometallurgical, Hydrometallurgical, Mechanical, Electrochemical End Use Sector: Vehicle Fleet Operators, Telecom Service Providers, Renewable Energy Installers, Data Center Managers Collection Channel: Retail Drop-Offs, Authorized Collection Centers, Special Waste Handlers, Domestic Pickups |
| Companies Covered | Gravita India Limited, Exide Industries Limited, Call2Recycle, Inc., Ecobat, Element Resources, Cirba Solutions, The Doe Run Company, Aqua Metals, Inc., East Penn Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Acid Battery Recycling Market Strategic Shifts & Innovations
Processing technology trajectories are bifurcating between emissions-intensive incumbent routes and capital-light electrochemical alternatives, with regulatory carbon accounting becoming the decisive selection criterion for new capacity deployment.
Electrochemical lead recovery is absorbing engineering talent and pilot-scale investment from conventional hydrometallurgy, with automotive OEM sustainability procurement teams mandating verified low-carbon secondary lead in battery supply agreements. The technology is absorbing market share from blast furnace operators in jurisdictions with binding industrial emissions caps, compressing the viable operating window for unabated smelting.
REACH regulation amendments are tightening lead content thresholds in consumer applications and mandating recycled content verification across battery supply chains, forcing smelters to invest in mass-balance certification systems. The EU Battery Directive collection rate minimums are accelerating formal sector consolidation, with member states most affected responding through authorized producer compliance schemes that exclude informal collectors.
Fleet operator procurement is consolidating around lifecycle carbon metrics rather than unit pricing alone, with sustainability-linked contracting displacing spot-market purchasing for secondary lead offtake. Logistics providers are responding with certified chain-of-custody services, and this shift is most visible in German and French automotive supply chains where OEM decarbonization targets cascade to tier-n battery suppliers.
Lead Acid Battery Recycling Market Segmentation
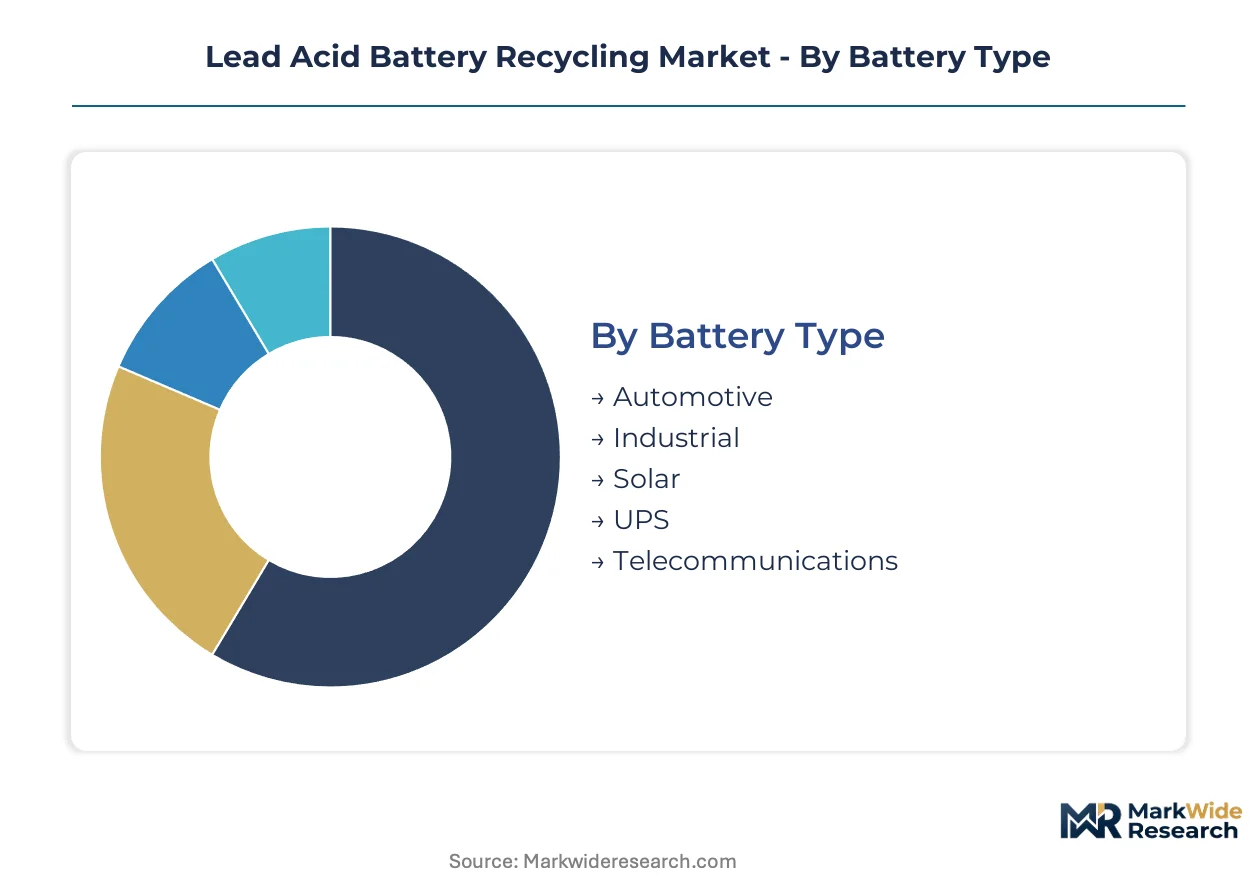
Lead acid battery recycling operators configure processing lines and logistics networks around distinct feedstock chemistries and customer return behaviors. Segment-specific recovery economics vary substantially across battery types and collection channels, dictating capital allocation for smelter retrofits versus electrochemical pilot deployments.
Battery Type:
Volume concentration versus premium recovery margins defines operator strategy across the five battery categories, with automotive feedstock dominating tonnage inflows.
- Automotive:Flooded, AGM, and EFB batteries from passenger vehicles and commercial trucks constitute the majority of spent feedstock globally. Dealer return programs in China, India, and the United States channel predictable volumes into formal collection networks, though lead price volatility compresses smelter margins on this commoditized stream.
- Industrial:Heavy-duty motive power batteries for forklifts and material handling equipment yield higher lead content per unit and longer service cycles that concentrate collection timing. Manufacturing clusters in Germany and Japan generate concentrated industrial battery returns that reward specialized logistics providers with scheduled pickup contracts.
- Solar:Off-grid and backup power installations in rural India and sub-Saharan Africa produce dispersed, low-density collection challenges that informal sector operators currently dominate.
- UPS:Data center and critical infrastructure backup batteries follow enterprise asset replacement cycles with certified disposal requirements that favor authorized collection center channels.
- Telecommunications:Tower backup batteries in emerging markets present compliance gaps where unlicensed dismantling persists outside formal producer take-back schemes.
Mature deployment sits with Automotive. Newer deployment is concentrated in Solar.
Recycling Process:
Technology selection hinges on emissions compliance costs and access to renewable electricity for electrochemical operations.
- Pyrometallurgical:Blast furnace and rotary kiln smelting remains the dominant industrial route, achieving 99.97 percent lead purity through high-temperature reduction. Chinese secondary lead capacity relies heavily on this method, though carbon border adjustments in the EU are redirecting trade flows toward certified lower-emission alternatives.
- Hydrometallurgical:Acid leaching and solvent extraction circuits recover lead compounds without thermal emissions, gaining traction in jurisdictions with binding industrial emissions caps. European operators are retrofitting hydrometallurgical lines to meet EU Green Deal decarbonization targets while maintaining throughput economics.
- Mechanical:Crushing and density separation systems preprocess batteries for metal liberation and plastic casing recovery. This capital-light approach serves smaller-scale operators in India and Southeast Asia where manual dismantling labor costs remain competitive.
- Electrochemical:Aqua Metals-type modular units use electricity to deposit pure lead from spent electrolyte, eliminating smelter emissions entirely. Nevada-based deployment demonstrates viability for automotive OEM sustainability procurement teams demanding verified Scope 1-3 reductions.
Emissions-intensive routes dominate established capacity. Electrochemical deployment is expanding most quickly in carbon-regulated markets.
End Use Sector:
Customer procurement patterns diverge between fleet-scale contractual returns and fragmented individual generator streams.
- Vehicle Fleet Operators:Commercial trucking and rental car fleets generate scheduled, high-volume battery replacements with centralized collection points. OEM take-back programs in India leverage this concentration through authorized service center networks.
- Telecom Service Providers:Tower infrastructure operators in Nigeria and Egypt face regulatory pressure to formalize battery disposal outside current informal recycling dominance.
- Renewable Energy Installers:Solar and wind farm developers are emerging as structured return channels as off-grid installation warranties expire across East Africa.
- Data Center Managers:Hyperscale facility operators demand certified chain-of-custody documentation for UPS battery disposal, creating premium pricing for compliant handlers.
Structured contracting prevails with Vehicle Fleet Operators. Regulatory enforcement gaps persist with Telecom Service Providers.
Collection Channel:
Channel economics reflect the tradeoff between consumer convenience and compliance documentation rigor.
- Retail Drop-Offs:Auto parts stores and battery retailers serve as accessible return points for consumer automotive batteries, though RCRA manifesting complexity creates administrative friction for multi-state networks in the United States.
- Authorized Collection Centers:OEM-branded facilities in India and EU member states capture formal sector feedstock under extended producer responsibility mandates, excluding informal competitors.
- Special Waste Handlers:Licensed hazardous waste transporters manage industrial battery streams with EPA-compliant documentation for large generators.
- Domestic Pickups:Direct collection from fleet and industrial sites minimizes handling stages and contamination risk, commanding logistics premiums in dispersed geographies.
Regulatory compliance concentrates in Authorized Collection Centers. Convenience-driven volume flows through Retail Drop-Offs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secondary lead smelters cluster where automotive manufacturing generates spent battery feedstock and emissions regulations permit high-temperature processing. China, India, and the United States anchor capacity deployment through distinct regulatory and industrial logics.
China
Domestic OEM take-back programs channel spent automotive batteries into secondary lead smelters expanding capacity across Anhui and Henan provinces. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions permits for blast furnace operators. Jiangsu province hosts the densest concentration of integrated battery manufacturing and recycling clusters.
India
Rajasthan and Gujarat generate concentrated feedstock flows from Gravita India Limited's integrated smelting and plastic recovery operations. The Ministry of Environment, Forest and Climate Change classifies used batteries as mandated return goods under hazardous waste management rules. Delhi-NCR automotive service networks feed authorized collection centers with predictable replacement volumes.
United States
Nevada-based electrochemical recycling demonstrates viability for automotive OEM sustainability procurement teams demanding verified Scope 1-3 reductions. The EPA enforces RCRA subtitle C requirements for spent lead acid battery handling and manifesting. Missouri retains legacy smelter infrastructure tied to regional mining heritage.
Germany
Industrial battery returns from forklift fleets and material handling equipment concentrate in manufacturing clusters around Stuttgart and Munich. The EU Battery Directive mandates collection rate minimums that accelerate formal sector consolidation. North Rhine-Westphalia hosts specialized logistics providers with scheduled pickup contracts for heavy-duty motive power batteries.
Brazil
São Paulo state generates automotive battery turnover through commercial trucking and rental car fleet operations with centralized collection points. ANVISA coordinates with environmental regulators on hazardous waste classification for lead-containing materials. The informal recycling sector dominates in northern and northeastern regions outside formal producer take-back schemes.
Lead Acid Battery Recycling Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electrochemical and low-emission processing routes. Chinese and Indian operators concentrate pyrometallurgical capacity where emissions frameworks remain permissive. Three archetypes define competitive positioning: integrated metal-plastic recovery specialists, captive collection network operators, and electrochemical technology disruptors. Capacity expansion and strategic partnerships dominate competitive moves as operators defend smelter-based margins against lower-carbon entrants.
Among India-based integrated operators, Gravita India Limited and Exide Industries Limited exemplify distinct strategic archetypes—one emphasizing backward integration into lead smelting and polypropylene recovery, the other anchoring recycling footprint through captive collection tied to original equipment distribution. Aqua Metals, Inc. occupies a position representing the electrochemical alternative, demonstrating modular deployment for jurisdictions with binding industrial emissions caps.
| Leading Market Players |
|---|
| Gravita India Limited |
| Exide Industries Limited |
| Call2Recycle, Inc. |
| Ecobat |
| Element Resources |
| Cirba Solutions |
| The Doe Run Company |
| Aqua Metals, Inc. |
| East Penn Manufacturing Company |
| Others |
Cost & Logistics Intelligence
Blast furnace operator skill concentration in Henan and Anhui provinces creates labor-cost differentials that widen pricing spreads between certified low-emission electrochemical output and legacy smelter product. Chinese secondary lead capacity draws from this workforce pool, compressing margin structures for operators lacking emissions compliance documentation.
Pricing Analysis
Warranty-backed collection guarantees versus spot-market feedstock purchases define how recyclers structure customer contracts. Three-tier pricing structure across certified low-carbon, standard secondary, and unverified smelter output reflects carbon accounting rigor and chain-of-custody documentation quality. Cost compression in standard smelter tiers is intensifying because EU carbon border adjustments redirect buyer procurement toward verified Scope 1-3 reductions. Automotive OEM sustainability teams show lowest price sensitivity, while independent battery distributors face margin pressure from lead price volatility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet operator demand through authorized service center networks in India and the United States. Feedstock sourcing draws from China, India, and the United States where automotive manufacturing clusters generate spent battery volumes. Sulfuric acid neutralization capacity, polypropylene separation infrastructure, and electrolyte handling permits constitute critical input dependencies. Single-source vulnerability concentrates in Chinese secondary lead processing dominance, with distribution running through authorized collection centers under extended producer responsibility mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical recycling capacity constraints prop pricing premiums for verified low-carbon secondary lead, as blast furnace retrofit timelines lag regulatory emissions tightening. Formal sector collection infrastructure bottlenecks in underpenetrated African markets sustain feedstock access premiums.
For Market Incumbents: To counter electrochemical technology displacement, retrofit legacy smelters with baghouse upgrades and acid mist containment systems in permissive emissions jurisdictions, while securing mass-balance certification systems to meet EU Battery Directive recycled content verification requirements. For New Entrants and Emerging Players: Telecom tower operators in Nigeria and Egypt represent an underserved buyer archetype with regulatory pressure mounting for formalized battery disposal outside informal recycling dominance. Solar off-grid installers across East Africa present white-space collection opportunities as installation warranties expire. State-level extended producer responsibility expansions in California and New York offer regulatory tailwinds for compliant reverse logistics deployment. For Investors and Strategic Acquirers: Re-rating potential sits with electrochemical technology operators given carbon border adjustment mechanisms redirecting trade flows toward certified low-emission sources. Long-term viability centers on modular deployment scalability and renewable electricity access. Watch for automotive OEM sustainability procurement mandates cascading to tier-n battery suppliers as the inflection indicator for accelerated capital rotation.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochemical Capacity Deployment | Eliminates blast furnace emissions for automotive OEMs facing EU CBAM compliance. |
| Backward Integration into Collection Networks | Captures margin from both metal recovery and polypropylene casing upcycling streams. |
| Mass-Balance Certification Investment | Enables EU Battery Directive recycled content verification for battery supply agreements. |
| African Collection Infrastructure Buildout | Structures compliant feedstock capture in markets currently dominated by informal dismantling. |
| Renewable Electricity Power Purchase Agreements | Secures Scope 2 reductions for electrochemical operations in carbon-regulated markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with secondary lead smelter operators, hazardous waste transporters, automotive OEM procurement teams, and extended producer responsibility scheme administrators. EPA RCRA manifests, EU Battery Directive implementation reports, Indian hazardous waste management filings, and London Metal Exchange lead price archives provided validation. Bottom-up feedstock flow modeling and top-down capacity installation tracking enabled triangulation across estimation approaches.
Segmentation granularity modeled battery type, recycling process technology, end-use sector, and collection channel dimensions across the analysis window. CAGRs derived from installed capacity trajectories, regulatory implementation timelines, and automotive fleet turnover projections. Electrochemical technology adoption curves and carbon border adjustment phase-in schedules constituted industry-specific forecast inputs alongside lead price volatility assumptions.
Revisions become necessary when carbon border adjustment implementation timelines accelerate, electrochemical technology throughput ceilings resolve differently than pilot-scale demonstrations suggest, or informal sector collection networks formalize faster than regulatory enforcement capacity expands. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market