
 Copper in Electric Vehicle Charging Infrastructure Market | 2026-2036
Copper in Electric Vehicle Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Copper in Electric Vehicle Charging Infrastructure Market Intelligence
The upgrade to high-conductivity, larger-gauge copper cabling for DC fast charging stations is rotating market value towards premium materials. Siemens AG leverages its extensive industrial automation and power grid expertise to supply integrated charging solutions for this segment. Schneider Electric SE specializes in energy management components essential for both public and private charging installations. ABB Ltd. competes on the basis of its Terra HP high-power charging technology portfolio, which requires significant copper content for thermal and electrical performance.
Copper in electric vehicle charging infrastructure refers to the high-purity conductors, cables, connectors, and busbars essential for transferring electrical energy from the grid to an EV's battery. These components often utilize oxygen-free copper with conductivity ratings exceeding 100% IACS to minimize energy loss and manage thermal loads. Within product types, copper cables and connectors command the largest value share due to high material content. The rapid charging application segment drives demand for more sophisticated and robust copper components to handle increased power levels.
Government policies like the US National Electric Vehicle Infrastructure (NEVI) program and the EU's Alternative Fuels Infrastructure Regulation (AFIR) directly subsidize and mandate charger deployment. Simultaneously, standards from bodies like the IEC and China's GB/T define safety and interoperability protocols for copper-based components in charging hardware. Stakeholder success depends on securing stable copper supply chains while innovating on thermal management for next-generation ultra-fast charging systems.
Market Dynamics
The imperative for faster charging times is the central force shaping the market. This demand for reduced dwell times at charging stations directly escalates the technical requirements for all copper components, pushing the industry towards higher-grade materials and more complex thermal management solutions to handle escalating power levels.
Growth Catalysts
- Fleet Electrification:The transition of commercial fleets, including delivery vans and long-haul trucks, to electric power requires extensive high-power charging infrastructure, significantly increasing copper demand per vehicle served compared to passenger cars.
- Regulatory Mandates:Government policies like the EU's Alternative Fuels Infrastructure Regulation (AFIR) and the US NEVI program enforce the build-out of public fast-charging corridors, creating a guaranteed, subsidized demand base for charging hardware.
- National Infrastructure Goals:Aggressive national targets, particularly in China, for EV adoption and charging point density are driving massive, state-supported investments in public and private charging networks, anchoring global copper consumption.
Market Restraints
- Raw Material Volatility:The pricing of charging components is directly exposed to fluctuations in the global price of copper traded on exchanges like the LME, creating margin pressure and planning uncertainty for manufacturers.
- Substitution Research:Ongoing R&D into aluminum conductors and advanced non-metallic cooling technologies presents a long-term substitution threat that could reduce the overall copper content required in future charging systems.
- Grid Integration Limits:The deployment of DC fast chargers is often constrained by the capacity of local electricity grids, with costly and time-consuming grid upgrades acting as a structural barrier to network expansion in many areas.
Strategic Opportunities
- Ultra-Fast Charging Systems:Developing and commercializing copper components and alloys specifically for next-generation 400kW+ ultra-fast charging (UFC) systems represents a significant value-add opportunity.
- Emerging Mobility Applications:The electrification of niche sectors such as marine vessels, mining equipment, and aviation creates new markets for specialized, high-durability copper charging connectors and cables.
- New Geographic Markets:Infrastructure build-outs in currently underpenetrated regions like South America, Southeast Asia, and the Middle East offer greenfield opportunities for component suppliers as EV adoption begins to accelerate.
Industry Challenges
- Standards Compliance Burden:Component manufacturers face the operational challenge of designing and certifying products to meet a complex and sometimes divergent web of international standards, including IEC, GB/T, and SAE.
- Supply Chain Security:Securing a stable and verifiable supply of high-purity, oxygen-free copper is a persistent challenge, as demand from the EV sector competes with other major industrial applications.
- Skilled Labor Shortages:A lack of qualified electrical engineers and technicians capable of designing, installing, and maintaining high-voltage DC fast charging systems creates bottlenecks in project execution and deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper in Electric Vehicle Charging Infrastructure Market |
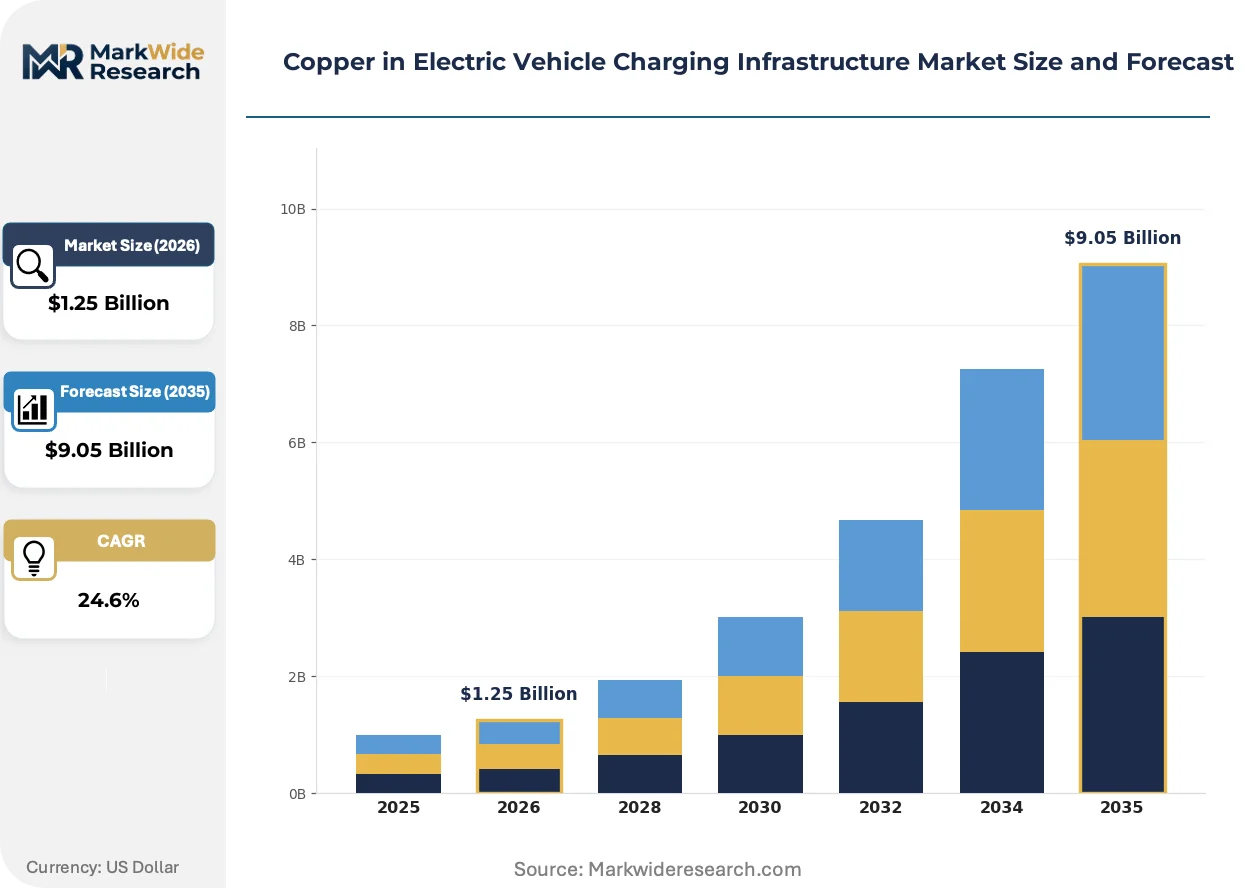
| Market Size in 2026 | $1.25 Billion |
| Market Size in 2035 | $9.05 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Cables, Connectors, Conductors, Charging Stations Application: Public Charging, Private Charging, Fleet Charging, Rapid Charging Installation Type: Wall-Mounted, Standalone, Portable, Integrated Customer Type: Manufacturers, Fleet Owners, Municipalities, Consumers |
| Companies Covered | Schneider Electric SE, Delta Electronics, Inc., ABB Ltd., BP Pulse, Shell Recharge Solutions, Tesla, Inc., ChargePoint Holdings, Inc., EVgo Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper in Electric Vehicle Charging Infrastructure Market Strategic Shifts & Innovations
Material science and system-level intelligence are converging to redefine performance benchmarks. The market is moving beyond basic component supply towards integrated power delivery systems where the thermal and electrical properties of copper are optimized through advanced engineering and software controls.
Liquid-cooled charging cables enable power transfer well above 350 kW by actively managing the intense heat generated. Operators of public high-power charging corridors and private electric truck depots are the primary adopters of this advanced technology. The introduction of these systems is fragmenting the cable market, creating a distinct premium segment for high-throughput applications separate from traditional air-cooled products.
The IEC 62196 series of standards governs the design of plugs, socket-outlets, and connectors for EV charging. This regulatory framework enforces global interoperability, compelling manufacturers to adhere to common specifications for physical dimensions and electrical communication protocols. Consequently, the connector and inlet segment is most affected, with suppliers prioritizing compliance to ensure their products gain access to major automotive markets in Europe and Asia.
A notable shift in buying behavior involves customers procuring turnkey charging solutions rather than individual hardware components. This disrupts the traditional sales channel where charge point operators would source power electronics, cables, and software from separate vendors. This integrated procurement model is most prominent in large-scale fleet and public network deployments across North America and Europe, where it simplifies project management and accountability.
Copper in Electric Vehicle Charging Infrastructure Market Segmentation
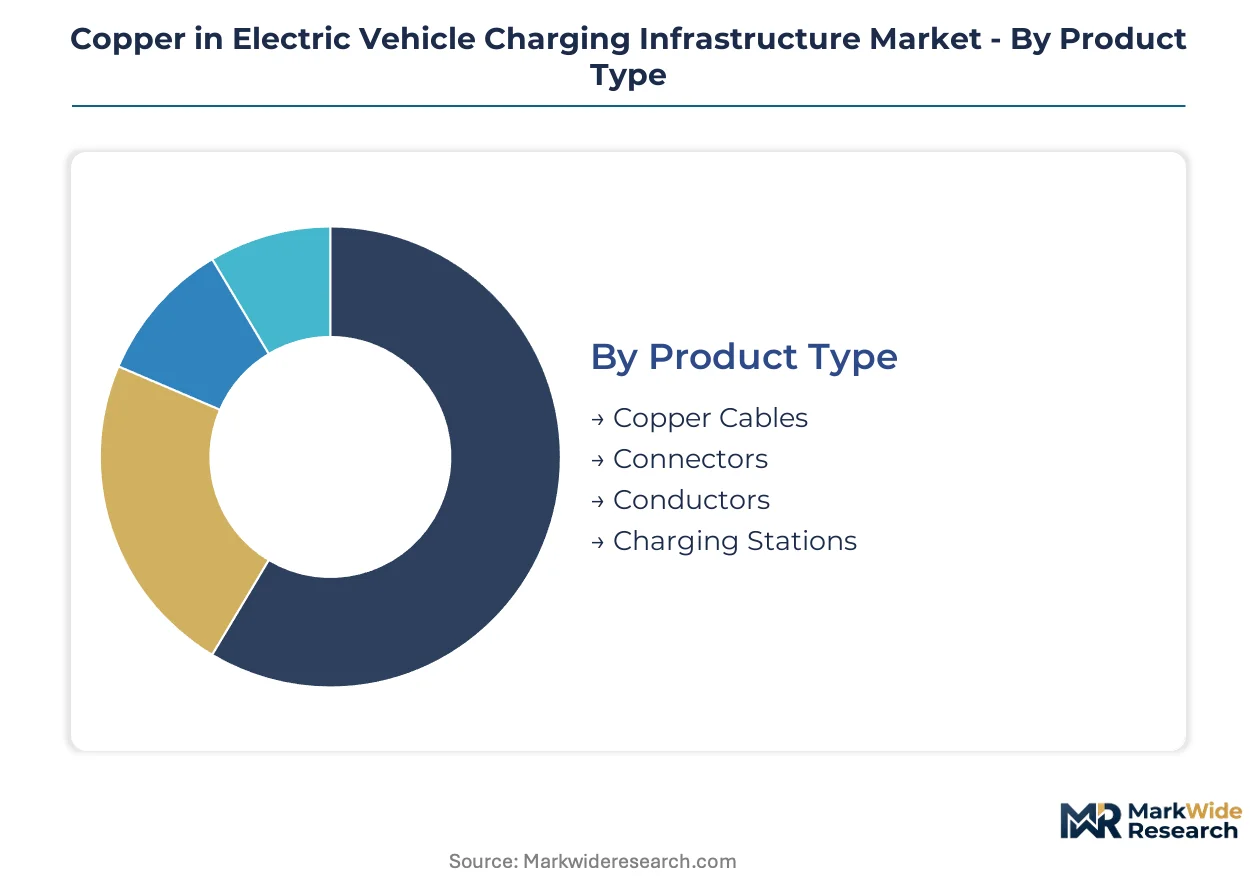
Understanding the Copper in Electric Vehicle Charging Infrastructure Market through segmentation reveals where value is generated and how different product types, applications, installation methods, and customer groups drive demand. This granular view helps stakeholders align product development and market strategies with specific industry requirements.
Product Type:
Margin pools in copper EV charging components are particularly concentrated in high-performance cables and advanced connectors, reflecting their critical role in power transfer and safety. These premium materials are essential for managing thermal loads in high-power applications.
- Copper Cables:These high-purity conductors often exceed 100% IACS, essential for low-loss power transfer from the grid to the EV. Demand concentrates in public fast-charging corridors, driven by the EU's Alternative Fuels Infrastructure Regulation and the US NEVI program.
- Connectors:Crucial interface components ensuring safe and efficient power delivery between the charger and the electric vehicle. Demand is high in global automotive markets, influenced by IEC 62196 standards for interoperability across Europe and Asia.
- Conductors:Raw copper elements forming the core of cables and busbars, optimized for electrical conductivity and thermal management.
- Charging Stations:Integrated systems housing power electronics, software, and copper components for EV charging, representing the complete end-user solution.
The dominant share belongs to Copper Cables, while Connectors are closing the gap fastest.
Application:
Volume requirements vary significantly across different EV charging applications, influencing copper component specifications and market size. Each application presents unique technical demands for copper materials.
- Public Charging:Chargers installed in public spaces like highways and urban centers, often requiring robust, weather-resistant copper components for durability.
- Private Charging:Charging solutions for residential or workplace use, typically lower power and focused on cost-effectiveness and ease of installation.
- Fleet Charging:Dedicated charging infrastructure for commercial vehicle fleets, demanding high-power, durable copper systems for rapid turnaround times. The electrification of commercial fleets, including delivery vans, significantly increases copper demand per vehicle served compared to passenger cars.
- Rapid Charging:High-power DC charging delivering fast energy replenishment, requiring advanced thermal management in copper cables and connectors. This application drives the need for high-conductivity copper alloys to handle escalating power levels and minimize energy loss.
This segment sees substantial investment in public infrastructure, reflecting the push for widespread EV adoption and regulatory compliance in countries like China and Germany.
Installation Type:
Different installation types cater to distinct customer needs and site constraints, impacting copper component design and the complexity of deployment. Solutions range from simple home units to complex public networks.
- Wall-Mounted:Compact charging units fixed to a wall, primarily for residential or commercial private use. These typically use smaller gauge copper cables and simpler connectors, focusing on ease of installation and cost efficiency.
- Standalone:Freestanding charging pedestals common in public and fleet depots, often supporting higher power levels. These require robust copper busbars and liquid-cooled cables for optimal thermal performance and durability in varied environments.
- Portable:Mobile charging devices offering flexibility for emergency or temporary power needs, utilizing flexible copper conductors for easy transport.
- Integrated:Charging systems seamlessly built into existing infrastructure, such as lampposts or parking bollards, optimizing space and urban aesthetics.
The growth trajectory is notably steeper in Standalone installations, driven by public infrastructure expansion across North America and Europe.
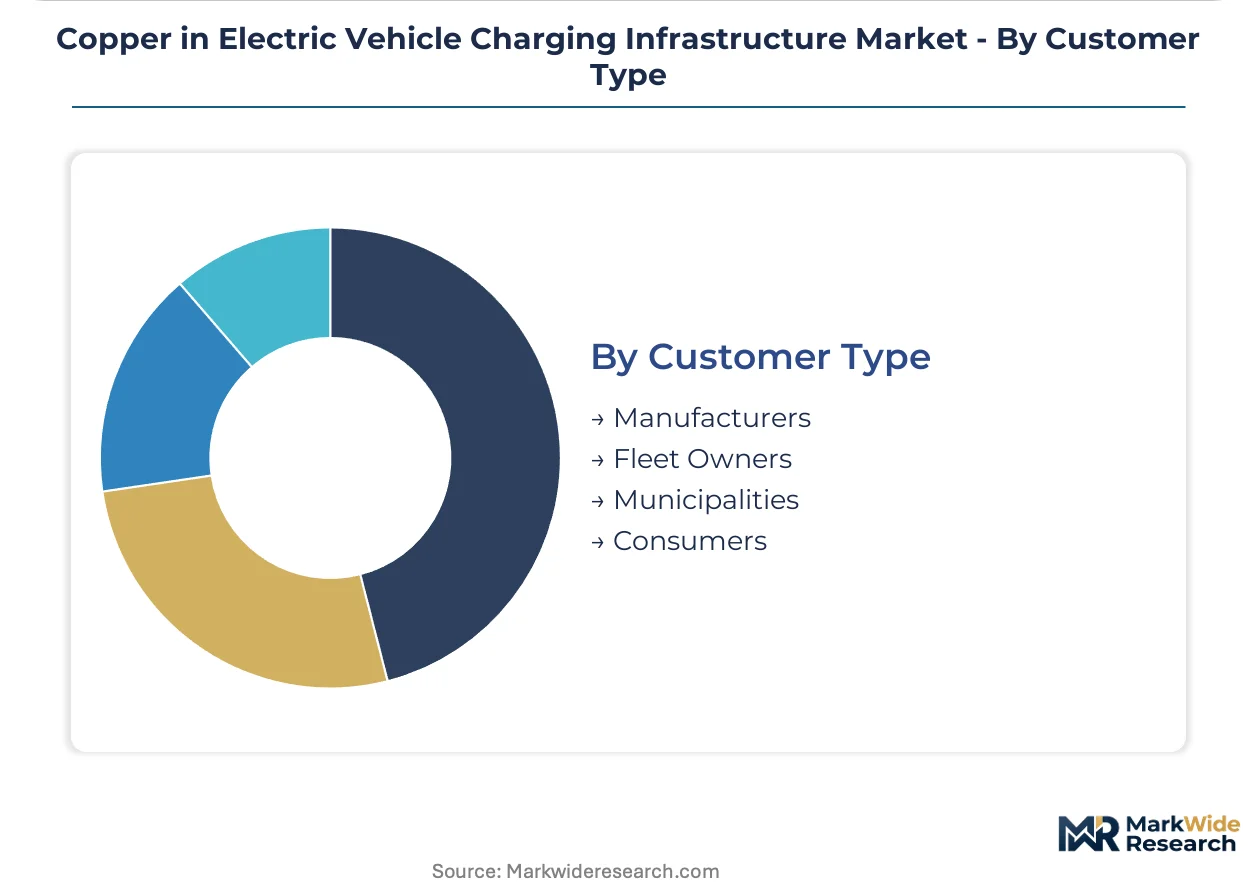
Customer Type:
Supply chain relationships for copper components are shaped by the procurement strategies and technical requirements of different customer types. Each segment has specific needs influencing copper product specifications.
- Manufacturers:Companies producing EV charging hardware, sourcing bulk copper cables, connectors, and conductors for their product lines. Siemens AG and ABB Ltd. are prominent examples integrating these components into their integrated solutions.
- Fleet Owners:Operators of commercial vehicle fleets requiring dedicated charging infrastructure for their electric trucks and vans. Their demand drives specialized high-power copper solutions for rapid depot charging, essential for operational efficiency.
- Municipalities:Local government bodies investing in public charging networks to support urban EV adoption and meet regulatory mandates.
- Consumers:Individual EV owners purchasing home charging solutions, typically requiring simpler, lower-power copper cable assemblies for personal use.
Future expansion is heavily influenced by the purchasing power of Fleet Owners and the regulatory support for Municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper components from China supply a significant portion of global EV charging infrastructure. This trade flow underpins the widespread deployment of charging solutions across various geographies. European and North American markets often import these critical materials for their expanding networks.
China
China's aggressive national EV adoption targets drive substantial copper demand for charging infrastructure. The GB/T standards define technical specifications for charging hardware components, ensuring interoperability. The Yangtze River Delta region sees significant investment in manufacturing capacity for these materials and integrated charging systems.
United States
United States fleet electrification initiatives generate significant copper demand for heavy-duty charging applications. The US NEVI program provides substantial funding for public fast-charging corridor deployment. California leads in EV infrastructure build-out, establishing a high concentration of charging points and related copper component demand.
Germany
Germany's commitment to the European Green Deal necessitates robust EV charging infrastructure development. The EU's Alternative Fuels Infrastructure Regulation (AFIR) mandates high-power charging along main transport corridors. Bavaria focuses on advanced automotive manufacturing and related charging solutions, driving demand for premium copper materials.
Japan
Japan's advanced automotive sector requires high-performance copper components for EV charging systems. METI policies support the expansion of charging networks for both passenger and commercial vehicles. The Kanto region, including Tokyo, concentrates significant R&D for next-generation charging technologies and their copper requirements.
India
India's rapid urbanization and government incentives are accelerating EV adoption and the associated charging infrastructure build-out. The PLI scheme supports domestic manufacturing of automotive components, including high-purity copper elements. Maharashtra and Gujarat are emerging as key hubs for EV battery and charging equipment production.
Copper in Electric Vehicle Charging Infrastructure Market Key Industry Players
Listed leaders compete with private specialists across the spectrum of integrated charging solutions and component supply. The market structure exhibits a tiered consolidation, with large industrial conglomerates operating alongside specialized EV charging pure-plays focused on niche applications. Strategic partnerships and technology licensing represent prevalent competitive moves. Companies also pursue geographic expansion to capture emerging market opportunities and diversify their customer bases across continents.
On the premium-tier vector, European industrial powerhouses exemplify integrated solution provision. Schneider Electric SE, a French-based corporation, represents expertise in energy management components essential for both public and private installations. ABB Ltd., a Swiss-Swedish multinational, anchors high-power charging technology, particularly for DC fast charging systems. Siemens AG, a German industrial manufacturing company, occupies a position in industrial automation and power grid expertise. These entities leverage their broad portfolios to offer comprehensive charging infrastructure solutions to fleet operators and municipalities.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Delta Electronics, Inc. |
| ABB Ltd. |
| BP Pulse |
| Shell Recharge Solutions |
| Tesla, Inc. |
| ChargePoint Holdings, Inc. |
| EVgo Inc. |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Economies of scale in high-volume copper processing and component manufacturing shape both supply concentration and pricing floors. This dynamic favors large-scale producers capable of meeting the escalating demand for EV charging infrastructure.
Pricing Analysis
The technology-generation pricing gap widens between standard air-cooled cables and advanced liquid-cooled ultra-fast charging systems. Pricing in this market operates on a project-based and long-term contract model for large deployments. Price differentiation stems from the oxygen-free copper grade and the specific IEC/GB/T certification level required. Pricing pressure stems from raw material volatility, particularly LME copper prices. Fleet owners often demonstrate the least price sensitivity due to operational uptime requirements.
Supply Chain Analysis
China anchors global copper cable and connector production for EV charging, leveraging extensive manufacturing capacity. The supply chain relies heavily on high-purity copper cathodes and specialized insulating polymers. Single-source vulnerability for specific high-performance components presents a structural risk. Distribution runs through a mix of direct sales to charge point operators and OEM partnerships with integrated solution providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Copper in Electric Vehicle Charging Infrastructure market represents an early-cycle expansion story, justified by the accelerating electrification of commercial vehicle fleets. This market offers significant growth prospects for various stakeholders.
For Market Incumbents:Compound existing power grid expertise with advanced thermal management solutions for ultra-fast charging systems. Invest in securing stable, certified oxygen-free copper supply chains to mitigate raw material volatility. Develop integrated software platforms that manage both charging hardware and grid-side energy flow, protecting against new entrants focused solely on components. Prioritize compliance with evolving international standards like IEC 62196 to maintain market access.
For New Entrants and Emerging Players:Lead with specialized, high-durability copper components for niche sectors like marine or mining electrification. Target underpenetrated regions such as South America and Southeast Asia, focusing on rapid charging applications. Develop innovative cooling technologies for cables and connectors to differentiate from established players. Offer modular, scalable solutions that simplify deployment for smaller fleet operators.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among integrated solution providers offering managed charging services to fleets and municipalities. Long-term viability hinges on companies with strong intellectual property in thermal management and robust supply chain security for high-purity copper. Target acquisition archetypes include specialized component manufacturers with proprietary cooling technologies or regional charging network operators. The signal to watch is the acceleration of commercial fleet electrification mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secure stable, high-purity copper supply for escalating EV charging demand. |
| Technology Licensing | Accelerate adoption of liquid-cooled cable designs for ultra-fast charging. |
| Strategic Partnership | Integrate energy management software with charging hardware for turnkey solutions. |
| Geographic Expansion | Capture greenfield opportunities in emerging EV markets like India. |
| Green Manufacturing Transition | Enhance brand reputation and meet sustainability targets for copper sourcing. |
Research Approach
A spread of perspectives from charge point operators, component manufacturers, fleet managers, and grid infrastructure planners converged on the working assumptions. Primary interviews validated market dynamics, complemented by secondary data from industry association reports, government energy agencies, and technical standards bodies. This approach ensured a robust bottom-up and top-down triangulation of market size and growth drivers.
Product type, application, installation type, and customer type constituted the primary segmentation dimensions modeled over the projection horizon. Volume and value CAGRs were derived using historical growth trends and projected EV adoption rates. Key forecast inputs included copper price volatility and global charging point deployment targets.
Forecasts assume regulatory continuity in US NEVI, EU AFIR, and China's GB/T standards; material policy shifts would require re-modeling. Geopolitical events impacting copper supply chains or grid integration limits represent significant risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market