
 Nickel-Cadmium Battery Recycling Market | 2026-2036
Nickel-Cadmium Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel-Cadmium Battery Recycling Market Insights
Modular recycling unit deployment is restructuring how industrial buyers contract for nickel-cadmium recovery services, shifting from centralized long-term agreements to scalable on-site processing modules. Umicore N.V. leverages its integrated smelter-refinery network in Belgium to dominate European feedstock flows. Retriev Technologies Inc. anchors North American collection through its multi-state battery logistics platform. Gravita India Ltd. specializes in pyrometallurgical recovery at its Rajasthan facility, competing on cost for Asian industrial battery streams.
Nickel-cadmium battery recycling encompasses the recovery of metallic cadmium, nickel hydroxide, and steel from spent Ni-Cd cells through thermal or chemical separation, with typical cadmium purity targets exceeding 99.95% for battery-grade reuse. The process serves primarily to eliminate toxic cadmium leachate risks while returning critical metals to industrial supply chains. Aviation and military battery types command premium recovery economics due to stringent traceability requirements and concentrated collection points at defense depots and airline maintenance hubs. Hydrometallurgical technology leads investment flows as environmental regulators tighten emissions thresholds that disadvantage pyrometallurgical smelters, though mechanical preprocessing retains cost advantages for consumer electronics feedstocks with simpler cell geometries.
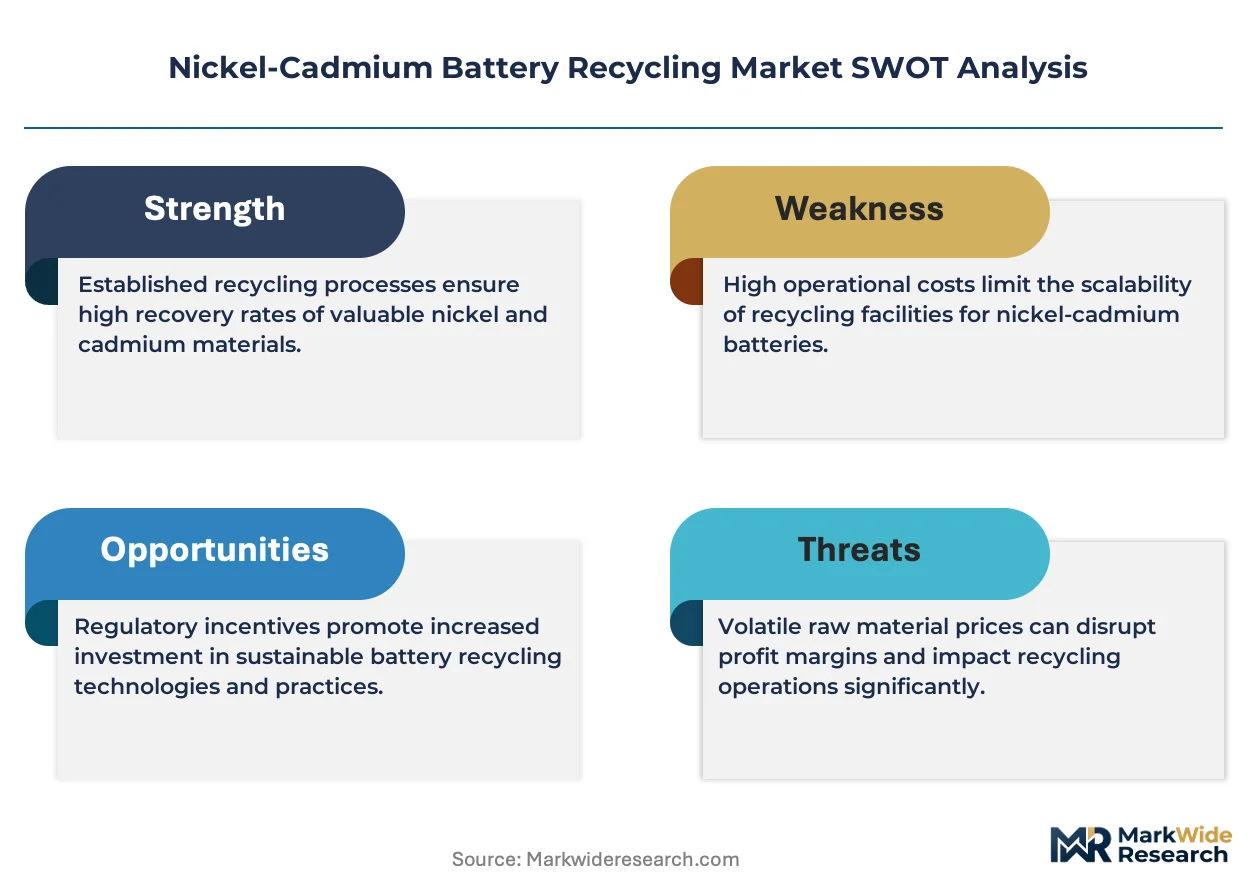
The EPA hazardous waste rules and EU REACH cadmium restrictions shape compliance costs and collection mandates across North American and European operations, while India's BIS standards for secondary metals create certification barriers for imported recycled material. China's MEE solid waste import bans have redirected Southeast Asian Ni-Cd scrap flows toward domestic recyclers, altering regional competitive dynamics. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between capital-intensive hydrometallurgical upgrades versus partnerships with technology licensors to maintain licensed capacity.
Market Dynamics
Closed-loop hydrometallurgical systems are displacing pyrometallurgical smelters as REACH cadmium emission thresholds tighten, forcing capital reallocation toward aqueous chemistry infrastructure that eliminates toxic off-gas handling.
Growth Catalysts
- EU Battery Regulation mandates:Extended producer responsibility frameworks now require aviation battery generators to fund certified recycling streams, creating guaranteed feedstock pipelines for licensed operators.
- Rhine-Ruhr industrial clustering:Germany's concentrated manufacturing belt generates dense collection networks that reduce logistics costs for smelter-refinery complexes serving European industrial battery streams.
- Aviation sector traceability requirements:Airlines face hazardous waste disposal audits that favor contracted recycling partnerships with documented chain-of-custody protocols.
Market Restraints
- Cadmium price volatility:Primary cadmium supply fluctuations from zinc smelting byproduct economics create margin compression for recyclers dependent on metal sales revenue.
- China MEE import bans:Southeast Asian Ni-Cd scrap flows now face restricted export pathways, limiting feedstock arbitrage opportunities for non-domestic processors.
- Lithium-ion substitution:Industrial and consumer applications are migrating toward nickel-metal hydride and lithium iron phosphate chemistries that eliminate cadmium toxicity concerns entirely.
Strategic Opportunities
- Modular on-site deployment:Containerized hydrometallurgical units allow industrial battery users to process spent cells at generation points, bypassing centralized smelter logistics.
- India BIS secondary metal certification:Domestic recyclers can capture import-restricted demand from Indian industrial buyers requiring certified recycled nickel and cadmium feedstock.
- Defense depot concentration:Military battery maintenance hubs in the United States and Europe offer premium recovery economics through consolidated collection and classified material handling protocols.
Industry Challenges
- Hydrometallurgical chemical engineering talent:Specialized expertise in solvent extraction and electrowinning circuit design remains scarce relative to pyrometallurgical skill bases.
- Licensed capacity timelines:EPA hazardous waste treatment permits and ECHA authorization processes extend facility commissioning by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel-Cadmium Battery Recycling Market |
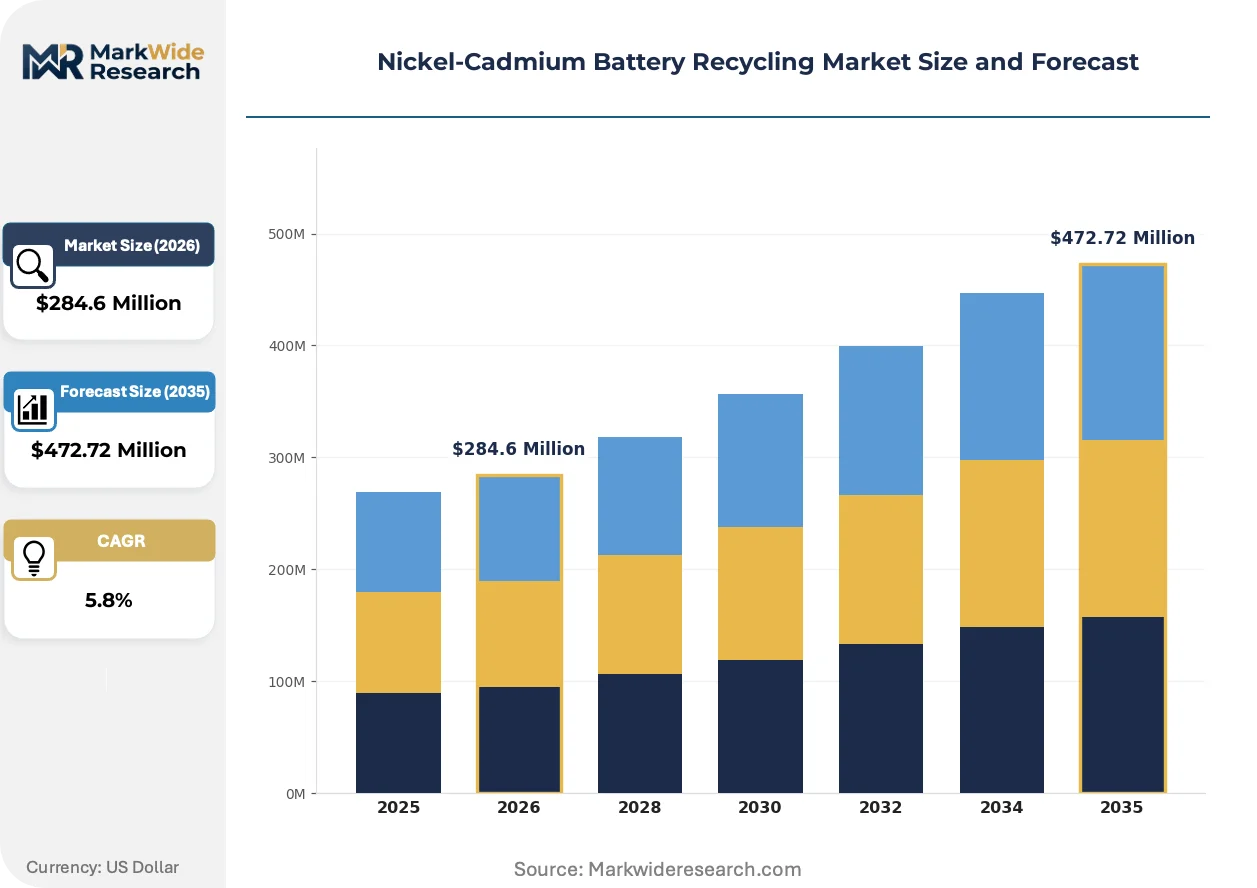
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $472.72 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Consumer Electronics, Power Tools, Aviation, Military, Medical Devices Recycling Technology: Hydrometallurgical, Pyrometallurgical, Mechanical, Biological, Electrochemical Application: Renewable Energy Storage, Electric Vehicles, Portable Equipment, Aerospace, Telecommunications End User: Electronic Manufacturers, Tool Manufacturers, Defense Sector, Healthcare Providers, Telecom Operators |
| Companies Covered | Umicore N.V., Retriev Technologies Inc., Call2Recycle, Inc., Li-Cycle Corp., Battery Solutions LLC, East Penn Manufacturing Company, EnerSys, Exide Technologies, Gravita India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel-Cadmium Battery Recycling Market Trends and Innovations
Recycling technology is bifurcating between capital-intensive closed-loop systems for industrial batteries and distributed mechanical preprocessing for consumer electronics, with regulatory pressure accelerating the technology split.
Hydrometallurgical recovery circuits employing selective precipitation and solvent extraction are rewriting competitive economics for aviation-grade cadmium recovery. Airlines and defense contractors are adopting these systems to meet traceability mandates. The technology is compressing acceptable pyrometallurgical market share to consumer feedstocks with simpler metallurgy.
REACH cadmium restrictions and the EU Battery Regulation's recycled content mandates are restructuring European collection economics. Industrial battery generators now face compliance costs that favor long-term offtake contracts with licensed hydrometallurgical operators. Aviation and rail sectors in Germany, France, and Belgium are consolidating procurement around certified recyclers with ECHA authorization.
Industrial buyers are unbundling recycling services from battery supply contracts and contracting directly with specialized processors. This disintermediation eliminates distributor markups and enables transparent mass-balance accounting. German automotive suppliers and French rail operators are pioneering direct processor relationships that bypass traditional battery distributor channels.
Nickel-Cadmium Battery Recycling Market Segmentation
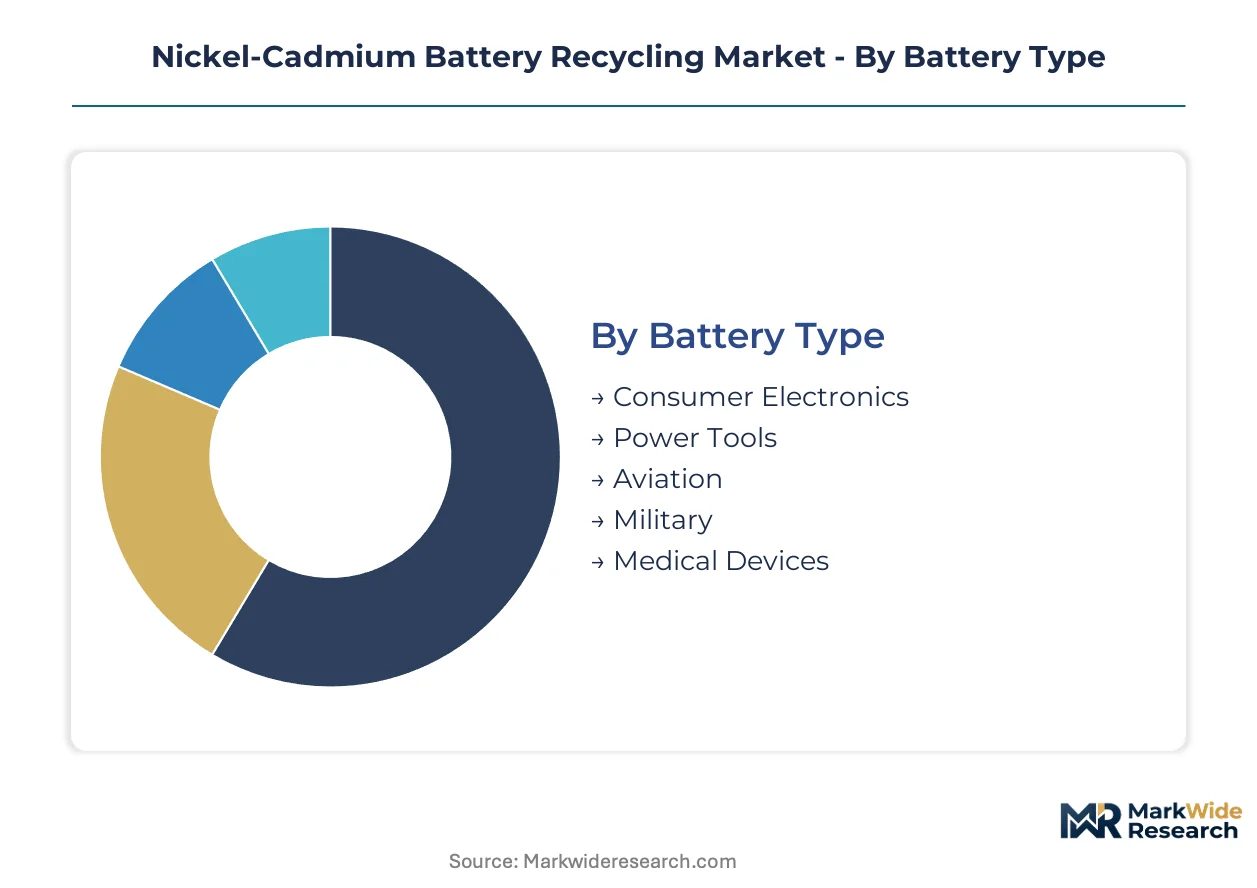
Segmentation in nickel-cadmium battery recycling reflects divergent technical requirements across battery chemistries and end-use traceability mandates. Recovery economics vary dramatically between consumer electronics feedstocks and aviation-grade cells with documented chain-of-custody protocols.
Battery Type:
Cell construction and cadmium concentration levels determine preprocessing routes and purity specifications for recovered metals.
- Aviation:Sealed cells with high nickel-cadmium ratios require specialized thermal treatment to meet FAA hazardous material documentation standards. German and French airlines now mandate certified recycling partnerships with ECHA-authorized processors to satisfy EU Battery Regulation audit requirements.
- Military:Defense depot batteries carry classified material handling protocols that compress collection logistics and command premium recovery economics. United States military maintenance hubs in California and Virginia consolidate procurement around processors with security clearances.
- Consumer Electronics:Low-cost cylindrical and button cells with simpler geometries favor mechanical preprocessing for steel recovery.
- Power Tools:Industrial-grade sub-C and D cells from construction equipment generate steady feedstock volumes through manufacturer take-back programs.
- Medical Devices:Implantable and portable equipment batteries face FDA hazardous waste disposal rules that limit processor eligibility.
Aviation leads on scale; military leads on momentum.
Recycling Technology:
Capital intensity and emission profiles separate commercially viable approaches from legacy smelting operations facing regulatory pressure.
- Hydrometallurgical:Aqueous chemistry circuits employing solvent extraction and electrowinning achieve battery-grade cadmium purity exceeding 99.95% without toxic off-gas generation. REACH cadmium emission thresholds are accelerating investment in closed-loop systems across Belgium and Germany.
- Pyrometallurgical:High-temperature smelting remains cost-competitive for consumer electronics feedstocks with simpler metallurgy but faces margin compression from tightening EPA hazardous waste treatment permits.
- Mechanical:Crushing and magnetic separation recover steel casings at lowest capital cost for high-volume consumer streams.
- Electrochemical:Direct metal electrodeposition from spent electrolyte offers emerging efficiency gains for concentrated industrial battery flows.
- Biological:Bioleaching using acidophilic bacteria remains experimental for cadmium recovery with limited commercial deployment.
Hydrometallurgical leads on scale; electrochemical leads on momentum.
Application:
End-use performance requirements dictate acceptable purity thresholds and documentation standards for recycled metal offtake.
- Aerospace:Aviation battery replacement cycles generate concentrated feedstock with stringent traceability mandates. German rail operators and French aircraft maintenance facilities now contract directly with licensed hydrometallurgical processors rather than battery distributors.
- Telecommunications:Backup power systems for cellular infrastructure create predictable collection volumes across India's tower networks, where BIS secondary metal certification restricts imported recycled material.
- Renewable Energy Storage:Grid-scale battery installations favor lower-cost recovered nickel for non-critical applications.
- Portable Equipment:Consumer device replacement cycles generate fragmented but high-volume feedstock through retail collection points.
- Electric Vehicles:Legacy nickel-cadmium traction batteries in industrial forklifts and airport ground support equipment create niche recovery demand.
Telecommunications leads on scale; aerospace leads on momentum.
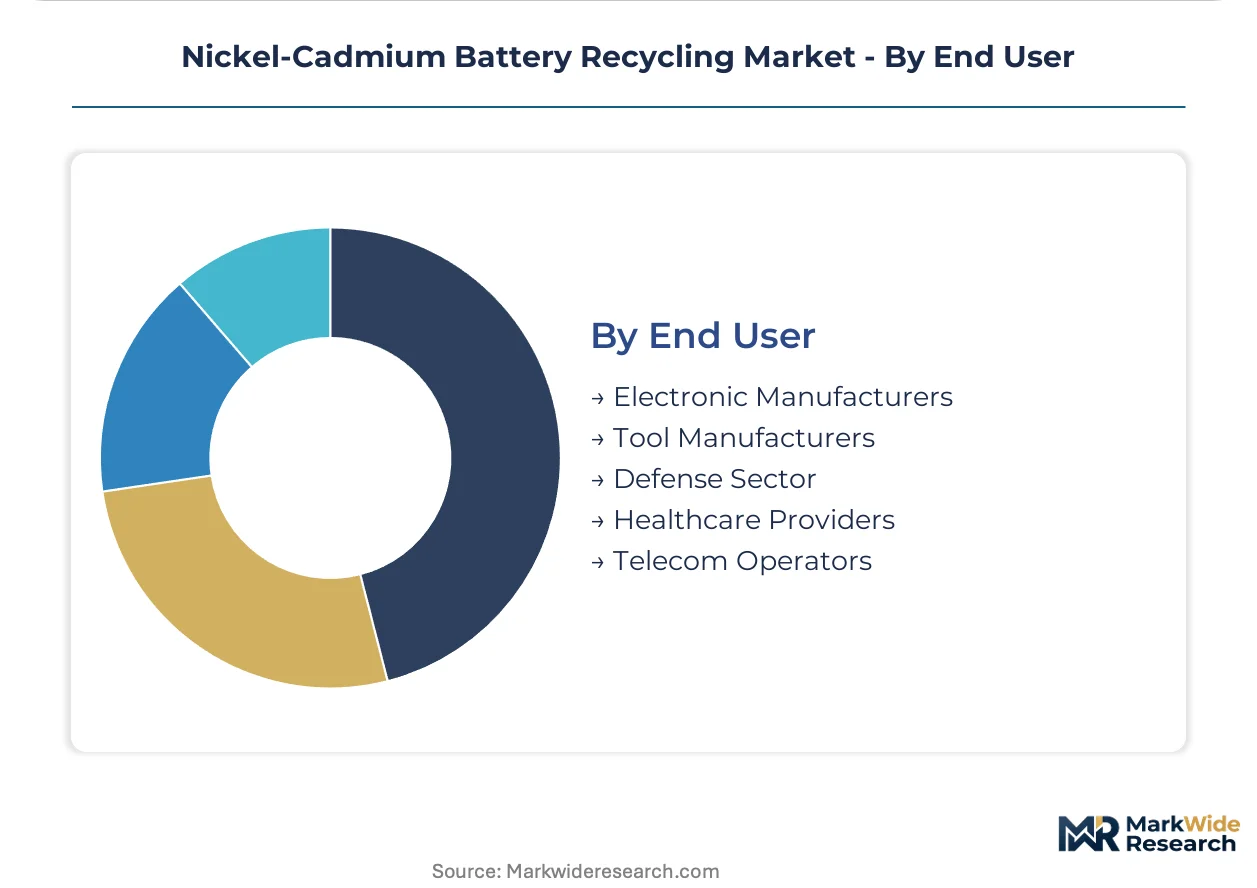
End User:
Procurement authority and compliance liability determine whether recycling services are bundled with battery supply or contracted directly with processors.
- Defense Sector:United States and European military battery procurement offices unbundle recycling from supply contracts to enable transparent mass-balance accounting and security-cleared material handling. Defense depot concentration in Texas and Bavaria offers premium economics through consolidated collection.
- Telecom Operators:Indian and German network infrastructure operators face extended producer responsibility frameworks that mandate certified recycling streams and fund guaranteed feedstock pipelines.
- Electronic Manufacturers:Consumer device brands manage take-back logistics through distributor networks with mechanical preprocessing at lowest cost.
- Tool Manufacturers:Industrial power tool brands in Germany's Rhine-Ruhr belt leverage dense manufacturing clustering to reduce collection logistics costs.
- Healthcare Providers:Hospital systems face FDA hazardous waste disposal rules that limit eligible processors and compress margin structures.
Telecom operators lead on scale; defense sector leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale nickel-cadmium battery recycling first achieved commercial scale in Belgium during the 1990s through integrated smelter-refinery investments. Today, processing capacity clusters around three regulatory jurisdictions with distinct compliance architectures.
Germany
Aviation maintenance hubs in Hamburg and Frankfurt generate concentrated feedstock streams from Lufthansa Group and Air France-KLM operations. The EU Battery Regulation's extended producer responsibility mandates now require airlines to fund certified recycling partnerships. The Rhine-Ruhr manufacturing belt around Düsseldorf and Dortmund hosts dense industrial battery collection networks that reduce logistics costs for smelter complexes.
United States
Defense depot concentration in California and Virginia creates premium recovery economics through consolidated military battery flows and security-cleared material handling protocols. EPA hazardous waste treatment permits extend facility commissioning timelines by 18-36 months, compressing licensed capacity expansion. Retriev Technologies anchors North American collection through multi-state logistics infrastructure serving aviation and industrial streams.
Belgium
Umicore's integrated smelter-refinery network in Hoboken dominates European feedstock flows through closed-loop hydrometallurgical systems. REACH cadmium emission thresholds have accelerated capital reallocation toward aqueous chemistry infrastructure that eliminates toxic off-gas handling. The Antwerp port complex enables efficient import processing of spent industrial batteries from neighboring jurisdictions.
India
Telecommunications backup power systems across tower networks create predictable collection volumes from Reliance Jio and Bharti Airtel infrastructure. BIS standards for secondary metals create certification barriers for imported recycled material, protecting domestic processors. Gravita India operates pyrometallurgical recovery at its Rajasthan facility, competing on cost for Asian industrial battery streams.
Nickel-Cadmium Battery Recycling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory compliance depth. The market structures into three tiers: integrated smelter-refinery operators with ECHA authorization, regional collection-logistics platforms with multi-state permits, and specialized pyrometallurgical processors competing on feedstock cost. Dominant competitive moves include hydrometallurgical technology licensing partnerships and backward integration into battery collection networks.
Among European integrated operators, Umicore N.V. exemplifies the closed-loop hydrometallurgical archetype through its Belgian smelter-refinery complex. Retriev Technologies Inc. represents the North American collection-logistics model with multi-state infrastructure serving aviation and defense feedstock streams. Gravita India Ltd. occupies the cost-competitive pyrometallurgical position for Asian industrial battery flows.
| Leading Market Players |
|---|
| Umicore N.V. |
| Retriev Technologies Inc. |
| Call2Recycle, Inc. |
| Li-Cycle Corp. |
| Battery Solutions LLC |
| East Penn Manufacturing Company |
| EnerSys |
| Exide Technologies |
| Gravita India Ltd. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into battery collection networks anchors competitive positioning for licensed hydrometallurgical operators, compressing feedstock acquisition costs while creating pricing power through ECHA-authorized capacity scarcity. Umicore's captive control over Belgian smelter-refinery complexes and Retriev's multi-state logistics infrastructure exemplify how upstream control over spent cell flows translates into margin protection against cadmium price volatility.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between aviation battery generators and certified recyclers, with price differentiation separating ECHA-authorized hydrometallurgical output from pyrometallurgical commodity grades. Cadmium purity certification above 99.95% commands substantial premiums from aerospace buyers facing FAA hazardous material documentation requirements. Cost compression in consumer electronics feedstock recovery is intensifying because mechanical preprocessing faces margin pressure from simpler lithium-ion substitution economics. Defense sector buyers exhibit least price sensitivity due to classified material handling protocols and consolidated collection logistics, while power tool manufacturers demonstrate highest sensitivity through distributor-negotiated volume contracts.
Supply Chain Analysis
ECHA authorization and EPA hazardous waste treatment permits function as qualification gates that restrict licensed processing capacity to Belgium, Germany, and the United States. Feedstock supply draws from aviation maintenance hubs in Hamburg and Frankfurt, defense depots in California and Virginia, and telecommunications tower networks across India. Single-source vulnerability concentrates in Belgian smelter-refinery complexes where Umicore processes dominant European flows. Distribution runs through certified logistics partnerships with documented chain-of-custody protocols rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's extended producer responsibility mandates compound recycling demand through guaranteed feedstock pipelines, creating structural pull for licensed hydrometallurgical capacity.
For Market Incumbents: Anchor market position through hydrometallurgical technology licensing partnerships that extend ECHA-authorized capacity without 18-36 month permitting timelines. Lithium-ion substitution in industrial applications threatens pyrometallurgical revenue streams; prioritize backward integration into aviation and defense collection networks where traceability requirements sustain premium pricing. For New Entrants and Emerging Players: Defense logistics contractors represent the most penetrable channel partner type for bypassing established distributor relationships. Target Indian telecommunications infrastructure operators facing BIS secondary metal certification barriers against imported recycled material. A modular on-site deployment model containerizing hydrometallurgical units at generation points offers direct contracting leverage against centralized smelter competition. For Investors and Strategic Acquirers: Consolidation pressure builds where licensed capacity scarcity meets extended producer responsibility mandates forcing generator-processor partnerships. Long-term viability favors integrated smelter-refinery operators with ECHA authorization and captive collection networks over regional mechanical preprocessors. Watch for EPA permit approval velocity as inflection indicator for North American capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Technology Licensing | Accelerates ECHA-authorized capacity deployment without full permitting timelines for Belgian and German operators. |
| Backward Integration into Collection Networks | Captures aviation maintenance hub feedstock flows from Lufthansa Group and Air France-KLM operations. |
| Modular On-Site Deployment | Containerized units bypass centralized smelter logistics for defense depot and airline maintenance point processing. |
| Defense Logistics Partnership | Security-cleared material handling protocols unlock premium recovery economics at California and Virginia depots. |
| India BIS Certification Investment | Captures import-restricted demand from Reliance Jio and Bharti Airtel telecommunications infrastructure operators. |
Research Methodology
Coverage spans Belgium, Germany, the United States, and India, with primary inputs from each jurisdiction's regulatory cluster. Interviews with hydrometallurgical plant managers, aviation procurement officers at Lufthansa Group and Air France-KLM, defense depot logistics coordinators, and Indian telecommunications infrastructure operators combined with secondary validation from EPA hazardous waste filings, ECHA authorization registries, BIS secondary metal standards, and EU Battery Regulation implementation guidance. Bottom-up feedstock flow modeling triangulated against top-down market sizing across technology and application segments.
Segment-level granularity modeled battery type, recycling technology, application, and end user dimensions across the analysis window. Aerospace and military segments incorporated FAA hazardous material documentation standards and classified handling protocol requirements. CAGRs derived from installed base retirement curves, substitution elasticity estimates for lithium-ion chemistries, and regulatory mandate implementation schedules. Forecast inputs included aviation battery replacement cycle data from German and French maintenance hubs, defense procurement patterns from United States depot concentration, and Indian telecommunications tower network expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion substitution velocity in industrial applications and REACH cadmium emission threshold tightening schedules. Forecasts reflect assumptions regarding ECHA authorization timelines, EPA permit approval velocities, and BIS certification barrier persistence. A model refresh is warranted upon material change in EU Battery Regulation enforcement intensity or Chinese MEE solid waste import policy adjustments affecting Southeast Asian scrap flow redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market