
 Global Turbine Oil Market | 2026-2036
Global Turbine Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Turbine Oil Market Outlook
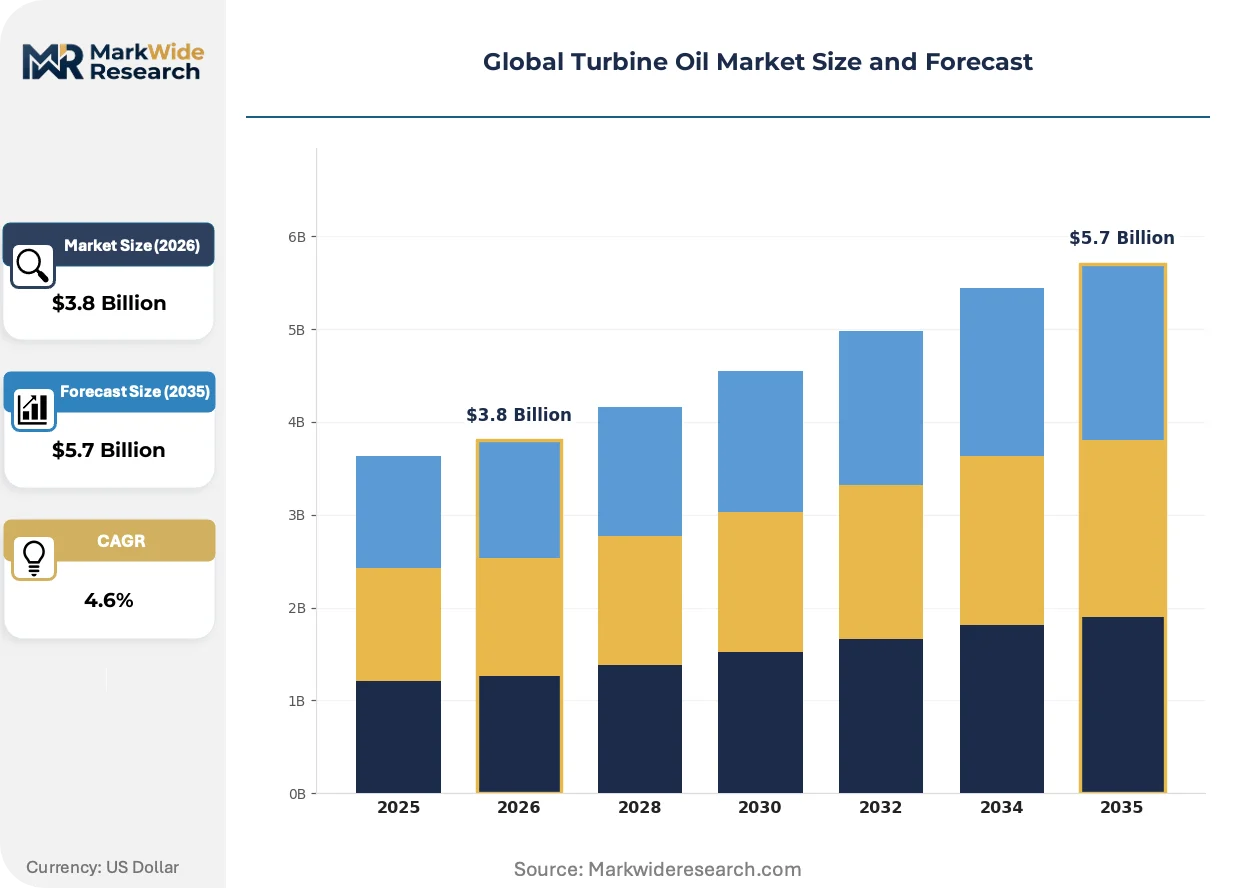
Fluid analysis subscriptions and predictive maintenance software bundles is broadening what turbine oil suppliers monetize beyond barrel sales. ExxonMobil Corporation leverages its Mobil Serv condition monitoring platform to anchor long-term utility contracts. Shell plc sustains competitive positioning through synthetic formulation leadership for high-temperature gas turbine applications. FUCHS SE specializes in customized turbine oil blends for European OEM specifications, occupying a defensible niche in precision manufacturing.
Turbine oil comprises refined base stocks fortified with oxidation inhibitors, rust preventives, and anti-foam agents, formulated to maintain thermal stability under sustained operating temperatures exceeding 90°C in steam and gas turbine bearing systems. Synthetic oil commands premium positioning due to extended drain intervals and superior oxidative resistance in peaking power plants. Gas turbine applications absorb disproportionate volume growth as utilities favor flexible generation assets, while hydro turbine lubricant demand remains mature with predictable replacement cycles.
The EPA governs waste oil handling and spill containment protocols for US power generators, while REACH restricts certain additive chemistries in European formulations. China's MEE enforces emissions-linked equipment audits that indirectly elevate lubricant performance standards for domestic turbine operators. Stakeholders must track evolving chemical compliance thresholds and condition-based service economics to calibrate portfolio investments between commodity mineral oils and advanced synthetic platforms.
Market Dynamics
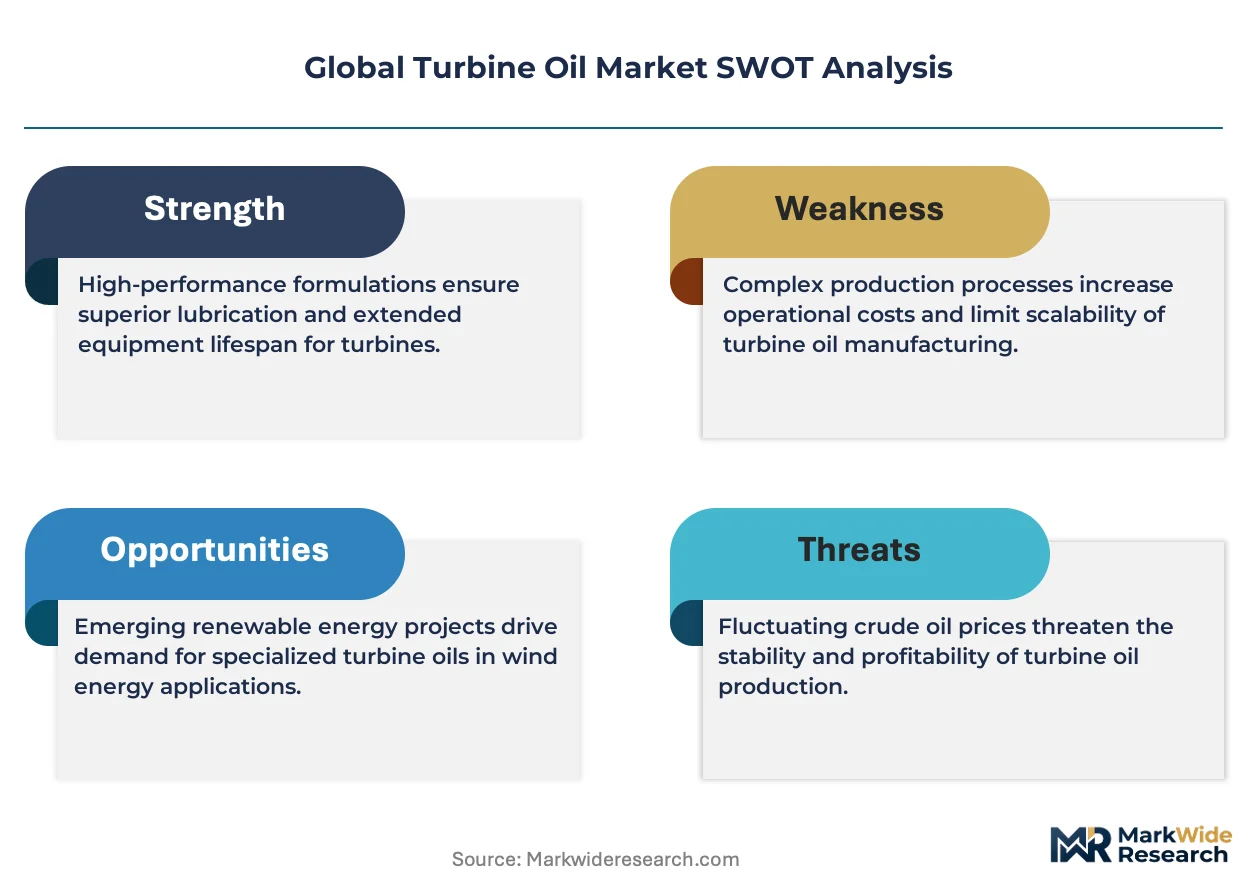
Combined-cycle gas turbine fleet expansion is compressing lubricant procurement cycles while REACH and F-Gas Regulation revisions force additive reformulation across European thermal assets. Fluid analysis subscriptions now anchor multi-year utility contracts.
Growth Catalysts
- EU F-Gas Regulation:Tightened fluorinated gas rules compel turbine operators to source low-emission synthetic lubricants for peaking plants.
- China grid modernization:State Power Investment Corporation and State Grid drive bulk supply contracts for steam turbine lubricants across provincial generation clusters.
- Predictive maintenance platforms:Condition monitoring software bundles expand supplier monetization beyond barrel sales into recurring service revenue.
Market Restraints
- Group II/III base oil supply concentration:Refinery capacity in the US Gulf Coast and Singapore creates input cost volatility for blenders.
- REACH additive restrictions:ECHA scrutiny of zinc dialkyldithiophosphate and phenolic antioxidants forces costly reformulation cycles.
- Extended drain interval technology:Synthetic formulations lasting 80,000+ hours compress replacement volume in mature hydro turbine fleets.
Strategic Opportunities
- India PLI scheme for power equipment:Domestic manufacturing incentives attract lubricant suppliers to localize blending for NTPC and Adani thermal assets.
- Offshore wind turbine gearboxes:Synthetic lubricant demand emerges for floating wind installations in the North Sea and Taiwan Strait.
- EPA waste oil handling rules:Spill containment and recycling mandates create service revenue streams for US-based fluid management providers.
Industry Challenges
- Tribology specialist scarcity:Universities in Germany and Japan produce insufficient lubricant formulation chemists for OEM specification work.
- ISO 8068 certification timelines:Gas turbine OEM approval processes extend 18-24 months, delaying market entry for new synthetic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Turbine Oil Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Bio-based Oil, Recycled Oil End User: Power Generation, Marine, Oil & Gas, Industrial Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Application: Steam Turbines, Gas Turbines, Hydro Turbines, Wind Turbines |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, BP plc, TotalEnergies SE, FUCHS SE, Phillips 66, Sinopec Corp., Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Turbine Oil Market Strategic Shifts
Digital fluid monitoring is compressing maintenance intervals while regulatory chemistry bans force base stock substitution. Synthetic formulations now dominate high-temperature gas turbine specifications.
Online particle counters and moisture sensors embedded in turbine bearing loops transmit real-time viscosity and oxidation data to cloud dashboards. US utilities including Duke Energy and Southern California Edison deploy these systems across combined-cycle fleets. Continuous monitoring is decentralizing scheduled oil changes toward condition-based replacement, shrinking planned outage windows.
REACH Annex XVII restrictions on boron and chlorine-containing additives took effect across EU member states in 2025. Formulators must substitute with ashless phosphorus and sulfur compounds for steam turbine applications. German power utilities RWE and Uniper accelerate qualification of new additive packages to maintain turbine warranties under OEM specifications.
Power generators unbundle fluid analysis from lubricant supply contracts, sourcing diagnostics from third-party laboratories. Independent testing houses in Houston and Rotterdam capture recurring revenue previously retained by oil majors. This procurement fragmentation concentrates in North American independent power producers seeking ISO 17025-certified compliance documentation for insurance underwriting.
Global Turbine Oil Market Segmentation
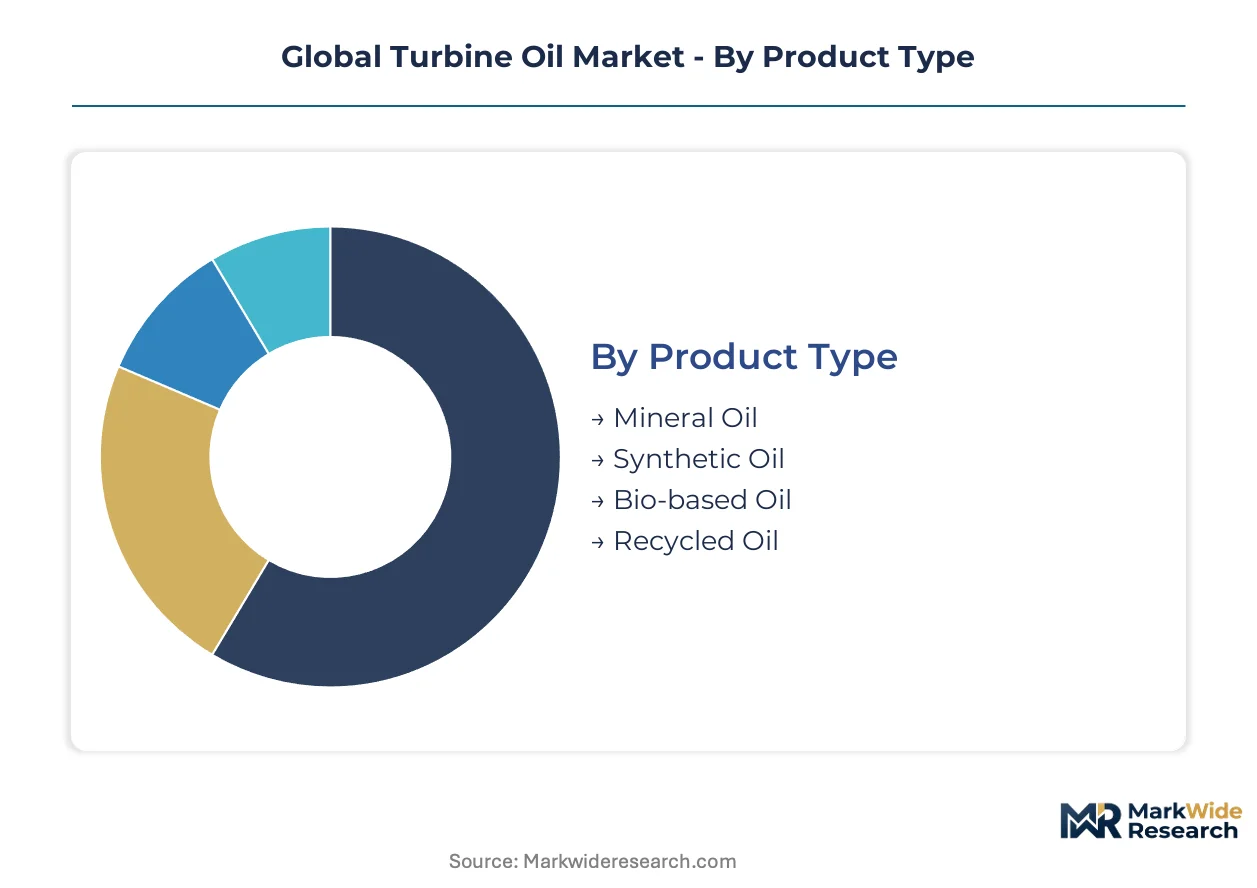
Turbine oil procurement patterns diverge sharply between utilities seeking long-term supply security and industrial operators prioritizing spot availability. Segmentation reveals where formulation complexity commands premium pricing versus where commodity logistics dominate purchasing decisions.
Product Type:
Customization intensity spans from off-the-shelf mineral formulations to engineered synthetic blends requiring OEM co-development and extended qualification cycles.
- Mineral Oil:Refined Group I/II base stocks with standard antioxidant packages serve mature steam turbine fleets where drain intervals remain fixed. Chinese provincial utilities under State Grid procurement frameworks absorb the largest mineral oil volumes for legacy coal-fired assets.
- Synthetic Oil:Polyalphaolefin and ester-based formulations deliver oxidative stability exceeding 80,000 hours in combined-cycle gas turbines. Demand concentrates in peaking plants across the US Gulf Coast and North Sea offshore installations where unplanned outages carry severe financial penalties.
- Bio-based Oil:Vegetable-derived base stocks with synthetic additive packages target European utilities facing Scope 3 emissions disclosure under CSRD.
- Recycled Oil:Re-refined base stocks with virgin additive replenishment serve cost-sensitive industrial cogeneration operators in India.
Most installed capacity flows through Mineral Oil. Expansion is steepest in Synthetic Oil.
End User:
Volume concentration versus margin capture separates utility procurement from marine and industrial segments.
- Power Generation:Combined-cycle gas turbine operators negotiate multi-year fluid analysis bundles with predictive maintenance software. Duke Energy and RWE specify synthetic formulations with 18-24 month OEM approval timelines.
- Marine:Two-stroke diesel-electric propulsion systems and auxiliary turbines on container vessels require high-base-number formulations for salt-air corrosion resistance. Singapore and Rotterdam bunkering hubs concentrate procurement.
- Oil & Gas:Mechanical drive gas turbines on pipeline compression stations prioritize extended drain intervals over thermal efficiency.
- Industrial:Paper mills and steelworks with captive cogeneration plants source through distributors rather than direct OEM relationships.
Power Generation commands the largest volume share. Marine applications are climbing the fastest on synthetic conversion.
Distribution Channel:
Service integration depth determines channel selection, from bare barrel sales to comprehensive fluid management programs.
- Direct Sales:ExxonMobil and Shell anchor utility contracts through Mobil Serv and Shell LubeAnalyst platforms bundling condition monitoring with supply agreements.
- Distributors:Independent blenders including FUCHS SE reach European OEM specification work through specialized technical service networks.
- Online Retail:Maintenance procurement managers at smaller industrial facilities source standard ISO viscosity grades through B2B platforms.
- Wholesalers:Volume resellers serve marine operators in Singapore and Houston with spot availability for emergency top-offs.
Distributors handle the majority of specification-grade volume. Direct sales channels are gaining share fastest on predictive maintenance bundling.
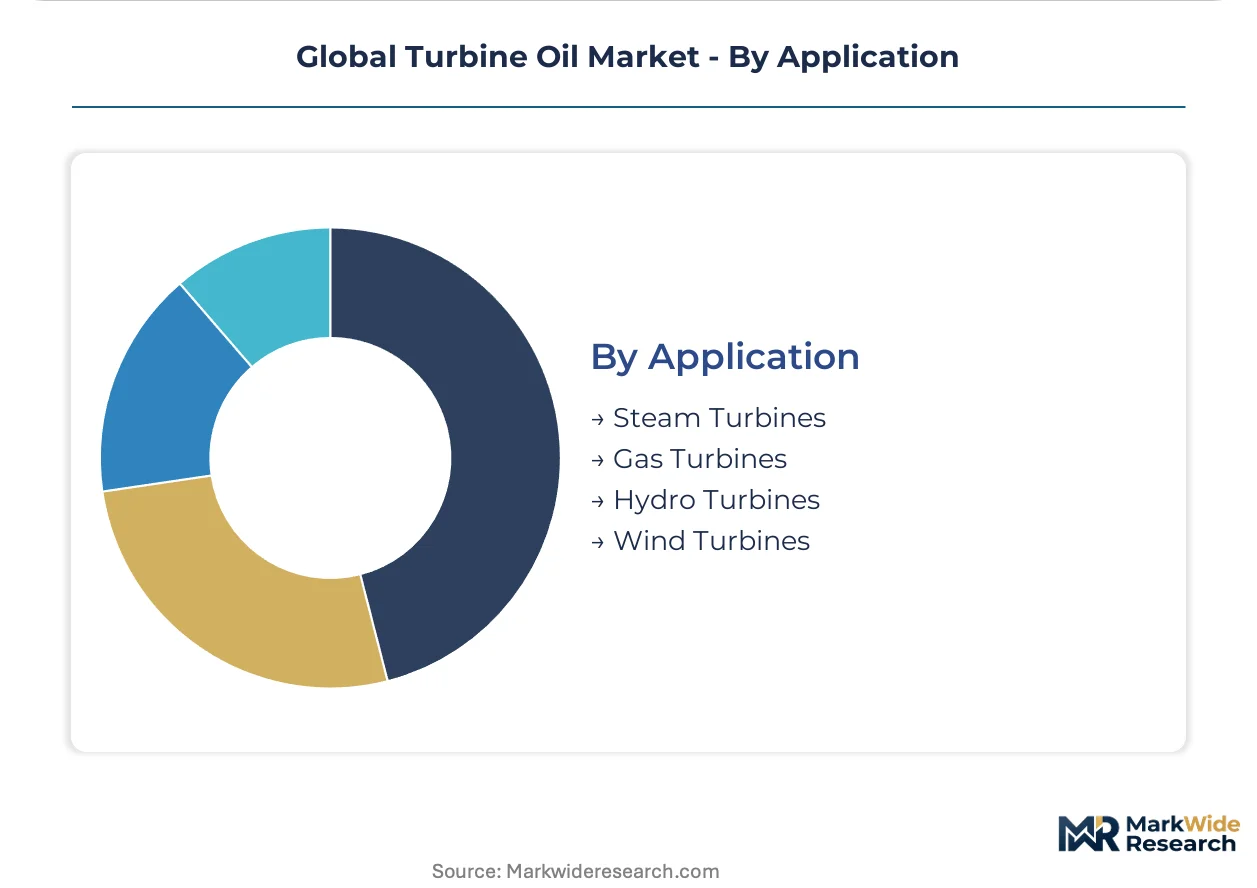
Application:
Thermal stress profiles and bearing system architectures dictate formulation requirements across turbine categories.
- Gas Turbines:Peaking plants and combined-cycle blocks expose lubricants to thermal spikes exceeding 150°C. F-class and H-class turbines from GE Vernova and Siemens Energy specify synthetic formulations with stringent oxidation resistance.
- Steam Turbines:Base-load coal and nuclear plants operate at stable temperatures below 100°C, permitting mineral oil with standard drain intervals. State Power Investment Corporation in China maintains the largest steam turbine lubricant inventory.
- Hydro Turbines:Kaplan and Francis turbine wicket gate mechanisms require environmentally acceptable lubricants for potential water contact applications.
- Wind Turbines:Gearbox lubrication for offshore floating installations in the North Sea and Taiwan Strait drives synthetic demand for high-load bearing protection.
Steam Turbines retain the largest installed base. Gas Turbines are expanding most quickly on flexible generation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed procurement dwarfs individual European markets, yet Germany's OEM specification work commands disproportionate formulation premiums.
United States
Duke Energy and Southern California Edison deploy predictive maintenance platforms across combined-cycle fleets. The EPA enforces waste oil handling and spill containment protocols for power generators. Gulf Coast refining clusters near Houston supply Group II/III base stocks to domestic blenders serving utility contracts.
China
State Power Investment Corporation and State Grid drive bulk supply agreements for steam turbine lubricants across provincial generation assets. The MEE enforces emissions-linked equipment audits that elevate lubricant performance standards. Yangtze River Delta manufacturing hubs concentrate blending capacity for domestic turbine operators.
Germany
RWE and Uniper accelerate qualification of new additive packages to maintain turbine warranties under OEM specifications. REACH Annex XVII restrictions on boron and chlorine-containing additives took effect in 2025. Industrial clusters in North Rhine-Westphalia host formulation laboratories serving European power utilities.
India
NTPC and Adani thermal assets attract lubricant suppliers localizing blending under the PLI scheme for power equipment. The CEA mandates equipment reliability standards that indirectly shape lubricant procurement specifications. Gujarat and Maharashtra host emerging blending facilities serving western regional generation clusters.
United Kingdom
North Sea offshore wind installations drive synthetic lubricant demand for floating turbine gearboxes. The CSRD requires Scope 3 emissions disclosure that elevates bio-based oil interest among utilities. Aberdeen and Scottish coastal ports concentrate marine lubricant logistics for offshore energy infrastructure.
Global Turbine Oil Market Competitive Environment
Top-tier vendors anchor multi-year utility contracts, while mid-scale blenders occupy specification niches. The market structures around three tiers: integrated oil majors with predictive maintenance platforms, European specialists in OEM co-development, and regional blenders serving cost-sensitive industrial operators. Strategic moves concentrate on fluid analysis subscription bundling and additive reformulation for regulatory compliance.
Within the integrated major tier, ExxonMobil Corporation and Shell plc exemplify platform-based competition through condition monitoring ecosystems. FUCHS SE occupies a position among European specialists delivering customized blends for precision manufacturing specifications. These three anchors demonstrate how competitive positioning stratifies between recurring service revenue models and specification-grade formulation expertise.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP plc |
| TotalEnergies SE |
| FUCHS SE |
| Phillips 66 |
| Sinopec Corp. |
| Idemitsu Kosan Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Group II/III base oil costs transmit directly from US Gulf Coast and Singapore refinery clusters through three pricing tiers that separate synthetic formulations for peaking plants from mineral oils for legacy steam turbines. REACH-driven additive reformulation in Europe and EPA spill-containment mandates in the United States compound procurement complexity by embedding compliance premiums into landed costs.
Pricing Analysis
Capacity additions in Singapore are reshaping price floors for Group II/III base stocks while contract-based long-term offtake agreements dominate utility procurement. Price differentiation rests on ISO 8068 certification tier and after-sales fluid analysis bundling. Cost compression in mineral oil tiers is intensifying because Chinese state-backed utilities leverage bulk procurement scale. Industrial cogeneration operators in India exhibit highest price sensitivity; North Sea offshore wind developers show least.
Supply Chain Analysis
Re-refined base stock returns from industrial operators in India feed circular supply loops that reduce virgin additive replenishment costs. Geographic supply concentrates in the United States, Singapore, and China. Raw material dependencies draw from polyalphaolefin base stocks, ashless phosphorus additives, and ester synthetic packages. Single-source vulnerability runs through Singapore refinery capacity for Asian blenders. Distribution runs through direct sales channels bundling predictive maintenance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Turbine Oil Market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed formulation premiums recoverable in Asia-Pacific utility contracts.
For Market Incumbents: Anchor multi-year utility contracts through fluid analysis subscription bundling that locks out competitors. Defend against independent testing houses in Houston and Rotterdam by deepening OEM specification relationships. Prioritize certification investment for F-class and H-class gas turbine approvals from GE Vernova and Siemens Energy.
For New Entrants and Emerging Players: India's PLI scheme for power equipment opens a window for localized blending partnerships with NTPC and Adani thermal assets. Target bio-based oil formulations for European utilities facing CSRD Scope 3 disclosure requirements. Pursue joint qualification programs with German OEM specification laboratories in North Rhine-Westphalia.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale blenders lack capital for 18-24 month ISO 8068 certification timelines. Long-term viability favors acquisition targets with established OEM co-development relationships and recurring service revenue from condition monitoring platforms. Monitor REACH Annex XVII additive restriction expansions as inflection indicators for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply of Group II/III stocks insulates blenders from Singapore refinery volatility. |
| Predictive Maintenance Platform Launch | Shell LubeAnalyst and Mobil Serv demonstrate how software bundling converts barrel sales to recurring revenue. |
| OEM Specification Joint Development | FUCHS SE's customized blends for European turbine manufacturers command formulation premiums. |
| Regulatory Compliance Certification Investment | REACH and EPA mandates elevate barriers for non-compliant mineral oil suppliers. |
| Geographic Manufacturing Footprint Expansion | Yangtze River Delta and Gujarat blending facilities position suppliers for state-backed procurement. |
Study Parameters
Multiple input streams — primary interviews with lubricant formulation chemists, utility procurement officers, and OEM specification engineers; secondary validation through ECHA regulatory filings, SEC 10-K disclosures, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Conversations with plant managers at combined-cycle facilities, technical R&D directors at additive suppliers, and aftermarket service heads at turbine OEMs supplied operational context. EIA power generation statistics, IEA energy transition reports, and State Grid procurement announcements provided demand-side benchmarks.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, end-use application, distribution channel depth, and regional regulatory framework cluster. CAGRs were derived from installed capacity growth trajectories, drain interval technology diffusion curves, and synthetic conversion rates in peaking plant deployments. Forecast inputs incorporated REACH additive restriction timelines and China's MEE emissions audit enforcement patterns.
Revisions become necessary when regulatory chemistry bans accelerate, refinery capacity disruptions materialize, or utility predictive maintenance adoption curves steepen beyond modeled parameters. Practitioners should monitor ECHA substance restriction proposals and Gulf Coast refinery utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Japan Bunker Fuel Market
Fuels
Coal Gasification Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Solid Recovered Fuel Market
Fuels
Europe Coal Market
Fuels
Canada Coal Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
China LNG Bunkering Market
Fuels
Chafing Fuel Market
Fuels
White Coal Market
Fuels
Emulsified Fuel Market
Fuels
Refuse Derived Fuel Market
Fuels
City Gas Distribution Market
Fuels
United States Coal Market
Fuels
Biobutanol Market