
 Automotive Heated Steering Wheel Market | 2026-2036
Automotive Heated Steering Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heated Steering Wheel Market Analysis
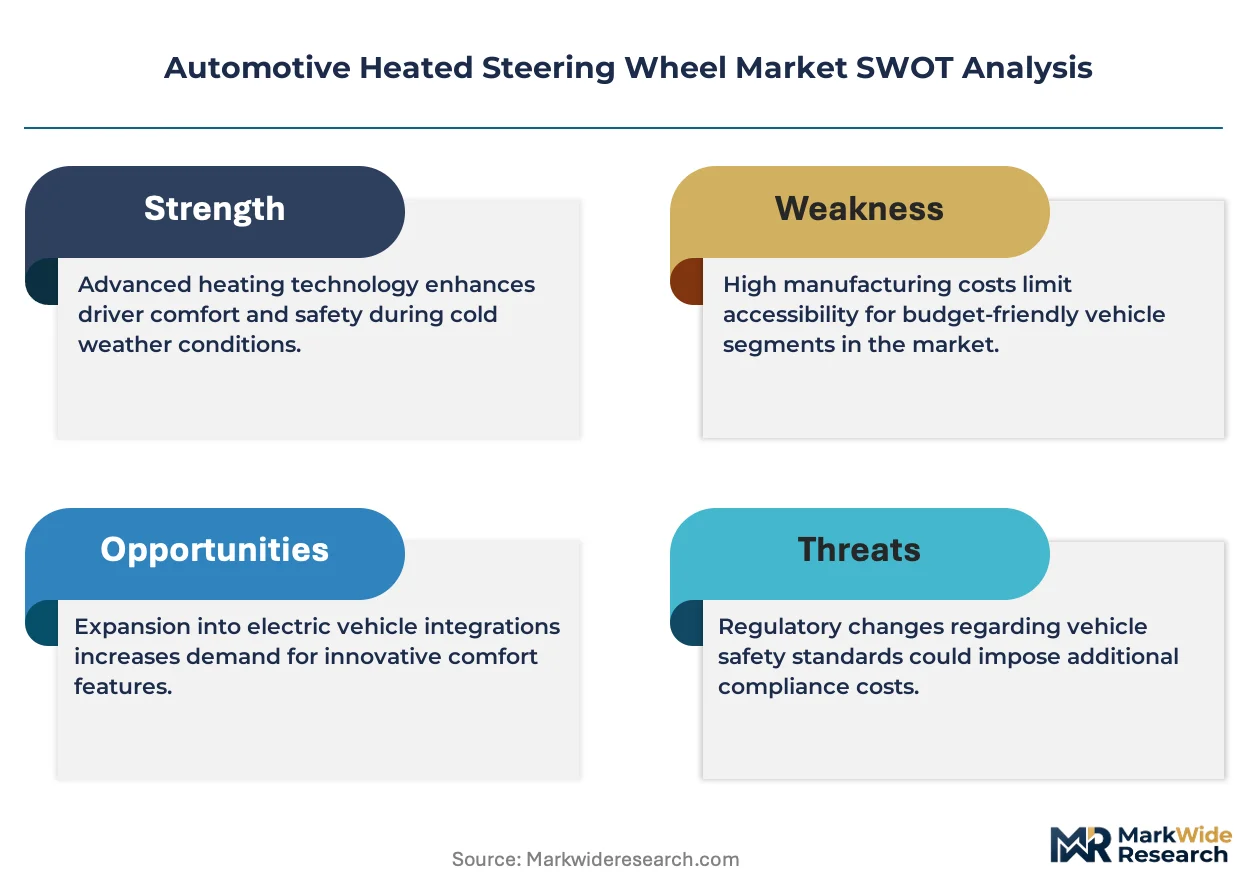
Heated steering wheel bundling with climate-comfort packages is shifting buyer choice from standalone options to integrated cabin thermal systems. Gentherm leverages its specialized thermal management portfolio to anchor premium OEM contracts in North America. Lear Corporation sustains manufacturing scale across multiple vehicle platforms. Continental competes through backward integration into sensor and control module production.
An automotive heated steering wheel is a steering assembly incorporating embedded resistive or positive temperature coefficient heating elements, typically operating at 12V or 48V, designed to maintain surface temperatures between 30°C and 40°C for occupant thermal comfort in cold ambient conditions. The primary commercial purpose is reducing driver distraction and improving ergonomic safety during winter operation while supporting cabin energy efficiency by localizing heat delivery. Integrated heated steering wheels dominate OEM fitment due to embedded wiring harness compatibility and vehicle network integration, while retrofit solutions occupy the aftermarket channel where installation simplicity determines margin pools. Conductive heating technology leads volume production, though PTC configurations are gaining traction in electric vehicle architectures where precise thermal control protects battery system efficiency.
Federal Motor Vehicle Safety Standards administered by NHTSA govern steering system integrity and occupant protection, directly affecting heated element placement and material flammability requirements. EPA Corporate Average Fuel Economy regulations incentivize localized heating strategies that reduce overall cabin HVAC load. Stakeholders must monitor evolving 48V electrical architecture standards and cold-climate homologation protocols across multiple jurisdictions to align product roadmaps with platform electrification timelines.
Market Dynamics
The automotive heated steering wheel sector is experiencing structural pressure from platform electrification, as 48V architectures and battery thermal management priorities force suppliers to redesign heating element integration and control logic for next-generation vehicle networks.
Growth Catalysts
- EPA CAFE Standards:Localized heating strategies reduce cabin HVAC energy draw, aligning heated steering wheels with fuel-efficiency compliance pathways in the US market.
- Cold-Climate Bundling:Luxury OEMs in Germany and Scandinavia package heated steering wheels with climate-comfort systems, converting optional uptake into standard fitment.
- Resistive-to-PTC Migration:Positive temperature coefficient elements enable precise thermal control that protects battery efficiency in electric vehicle architectures.
Market Restraints
- Copper and Polymer Input Volatility:Wiring harness and heating element materials face commodity price swings that compress supplier margins without OEM price pass-through mechanisms.
- NHTSA Occupant Protection Friction:Federal Motor Vehicle Safety Standards impose strict material flammability and steering integrity testing that extends development cycles and certification costs.
- Aftermarket Retrofit Substitution:Low-cost clip-on heating solutions capture price-sensitive consumers, limiting OEM replacement part revenue pools.
Strategic Opportunities
- Underpenetrated Southern China:Rising disposable income in provinces like Guangdong and Fujian creates first-time demand for comfort features previously concentrated in northern markets.
- 48V Architecture Convergence:Integration of heating controls with vehicle energy management systems opens software-defined thermal optimization contracts.
- EU Green Deal Thermal Efficiency:Cabin localization mandates incentivize European OEMs to specify heated steering wheels as standard efficiency equipment.
Industry Challenges
- Embedded Software Talent Scarcity:Vehicle network integration requires controls engineers fluent in AUTOSAR and functional safety protocols that suppliers struggle to recruit.
- Homologation Timeline Compression:Multi-jurisdiction cold-climate certification protocols delay platform launches when regional testing requirements diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heated Steering Wheel Market |
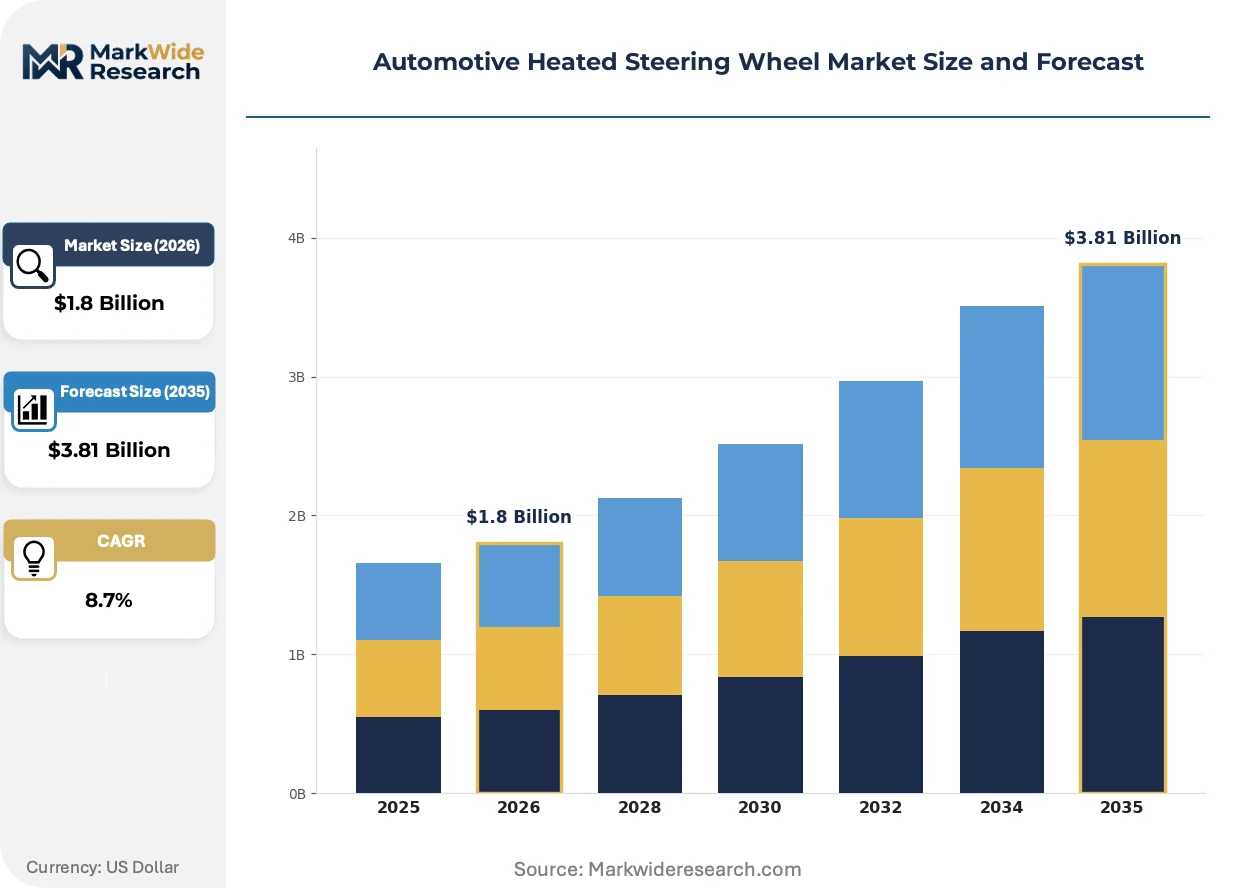
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated, Retrofit, Steering Wheel Cover, Wireless End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Fleet Operators Technology: Conductive Heating, Radiant Heating, PTC, Infrared Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Electric Vehicles |
| Companies Covered | Magna International, Lear Corporation, Gentherm, Autoliv, Continental, ZF Friedrichshafen, Hyundai Mobis, Key Safety Systems, Joyson Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heated Steering Wheel Market Emerging Trajectories
Electrification and software-defined vehicle architectures are compressing traditional component boundaries, forcing heated steering wheel suppliers to reposition as thermal management subsystem integrators rather than discrete hardware vendors.
Positive temperature coefficient heating elements are rewriting competitive positioning in electric vehicle supply chains. PTC technology self-regulates resistance as temperature rises, eliminating external control modules and reducing wiring complexity. Premium European and North American EV platforms are adopting PTC configurations at accelerating rates. This displacement of resistive heating is compressing supplier margins on legacy architectures while rewarding backward integration into sensor and control module production.
REACH chemical substance restrictions in Europe are reshaping material selection for heating element encapsulants and steering wheel substrates. The regulation's SVHC candidate list now captures several flame retardants and plasticizers common in automotive interiors. Suppliers serving EU-bound production must reformulate compounds or source alternative chemistries. German and Swedish OEMs are responding by mandating full material disclosure from tier-two heating element providers.
Fleet procurement of comfort packages is fragmenting traditional retail-driven option uptake. Rental and subscription vehicle operators in Japan and South Korea now specify heated steering wheels as standard equipment to reduce customer churn in winter months. Direct fleet contracts are displacing dealer-option ordering channels. This pattern is most visible in corporate leasing segments where total cost of ownership calculations prioritize driver retention metrics over upfront specification savings.
Automotive Heated Steering Wheel Market Segmentation
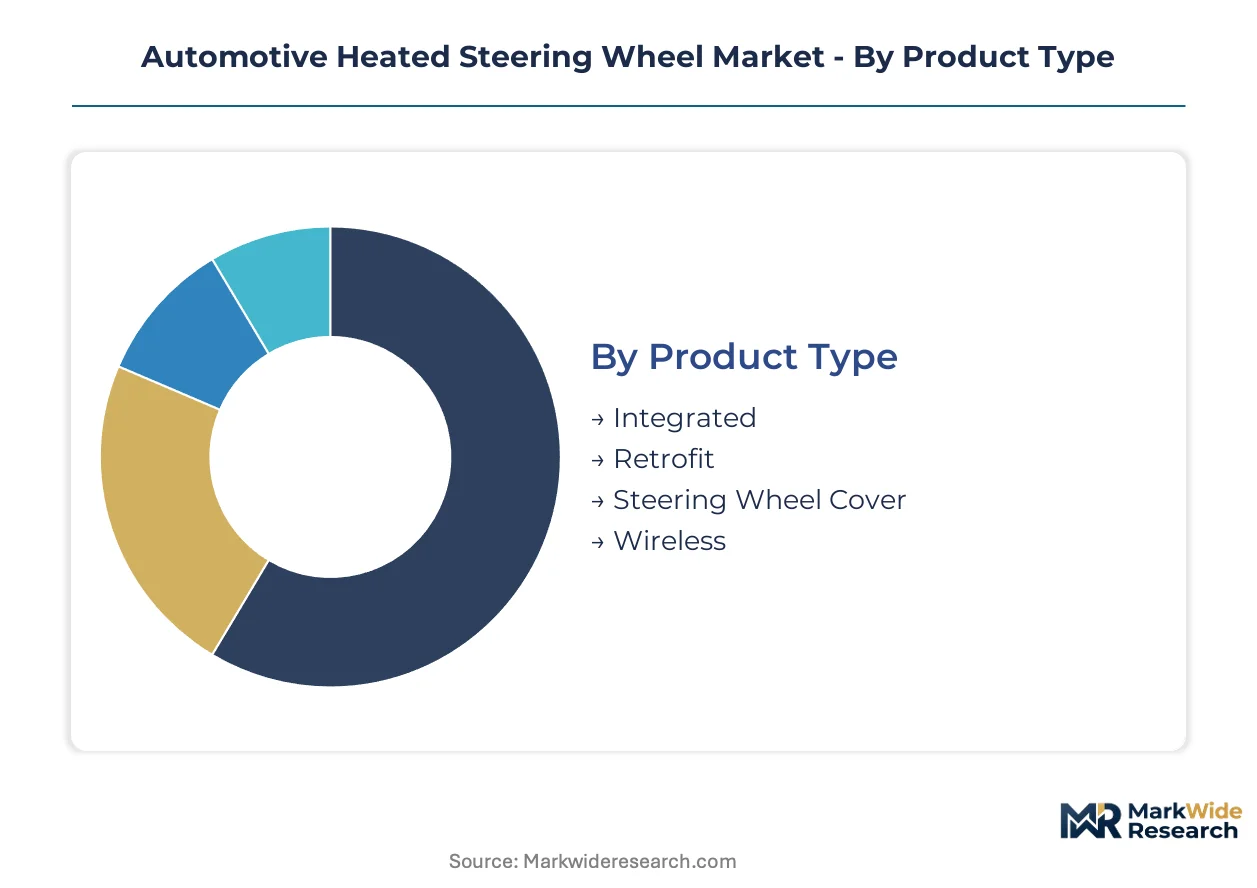
Segmentation in the automotive heated steering wheel market reveals how thermal comfort specifications diverge across vehicle electrification tiers and procurement channels. Buyers prioritize integration depth, energy efficiency compliance, and climate-zone bundling patterns when selecting product configurations.
Product Type:
Procurement is shifting toward factory-integrated solutions as OEMs consolidate climate-comfort packages and reduce dealer-option complexity.
- Integrated:Embedded heating elements with dedicated wiring harnesses and vehicle network integration dominate OEM fitment. German and Scandinavian luxury manufacturers specify these as standard equipment in cold-climate packages, eliminating standalone option uptake.
- Retrofit:Aftermarket solutions with simplified installation protocols target price-sensitive consumers and aging vehicle fleets. Low-cost clip-on alternatives capture replacement demand where OEM part pricing lacks pass-through elasticity.
- Steering Wheel Cover:Slip-on thermal accessories with elasticized mounting serve temporary comfort needs without permanent modification. These products concentrate in online retail channels with minimal regulatory compliance overhead.
- Wireless:Inductive or battery-powered configurations eliminate harness integration entirely, appealing to leased vehicles and subscription fleet operators seeking reversible upgrades.
Volume sits with Integrated; growth tilts toward Wireless as fleet procurement fragments traditional retail channels.
End User:
Customer type determines specification authority and contract structure across the value chain.
- OEMs:Original equipment manufacturers hold design control and platform integration responsibility. NHTSA steering integrity standards and EPA fuel-efficiency benchmarks directly shape their thermal system sourcing criteria.
- Aftermarket Suppliers:Independent distributors and repair networks source replacement units and retrofit kits. REACH chemical disclosure requirements from ECHA now extend to steering wheel substrate materials in EU-bound aftermarket channels.
- Vehicle Assemblers:Contract manufacturers and regional assembly plants procure heating modules as part of interior trim consolidation. Their procurement prioritizes logistics efficiency and single-source bundling over technical differentiation.
- Fleet Operators:Rental and subscription vehicle managers in Japan and South Korea now mandate heated steering wheels as standard equipment to reduce winter customer churn. Direct fleet contracts displace dealer-option ordering channels.
Contract concentration favors OEMs; expansion is climbing the fastest in Fleet Operators as total cost of ownership calculations prioritize driver retention.
Technology:
Architecture voltage migration from 12V to 48V systems is forcing heating element redesign and control logic requalification.
- Conductive Heating:Resistive wire elements operating at 12V represent legacy volume production. Copper input volatility and external control module requirements compress supplier margins on these established configurations.
- PTC:Positive temperature coefficient elements self-regulate resistance as temperature rises, eliminating external controls and reducing wiring complexity. Premium European and North American EV platforms are adopting PTC configurations at accelerating rates.
- Radiant Heating:Distributed thermal emission across steering wheel surfaces provides uniform comfort but requires higher power draw. Applications concentrate in luxury segments where energy efficiency trade-offs are secondary to tactile experience.
- Infrared:Targeted wavelength heating penetrates surface materials for rapid warm-up without full thermal mass conditioning. Niche adoption in high-performance vehicles prioritizes immediate tactile response over sustained efficiency.
Production scale rests with Conductive Heating; technology transition is gaining share fastest in PTC as electric vehicle architectures demand precise thermal management.
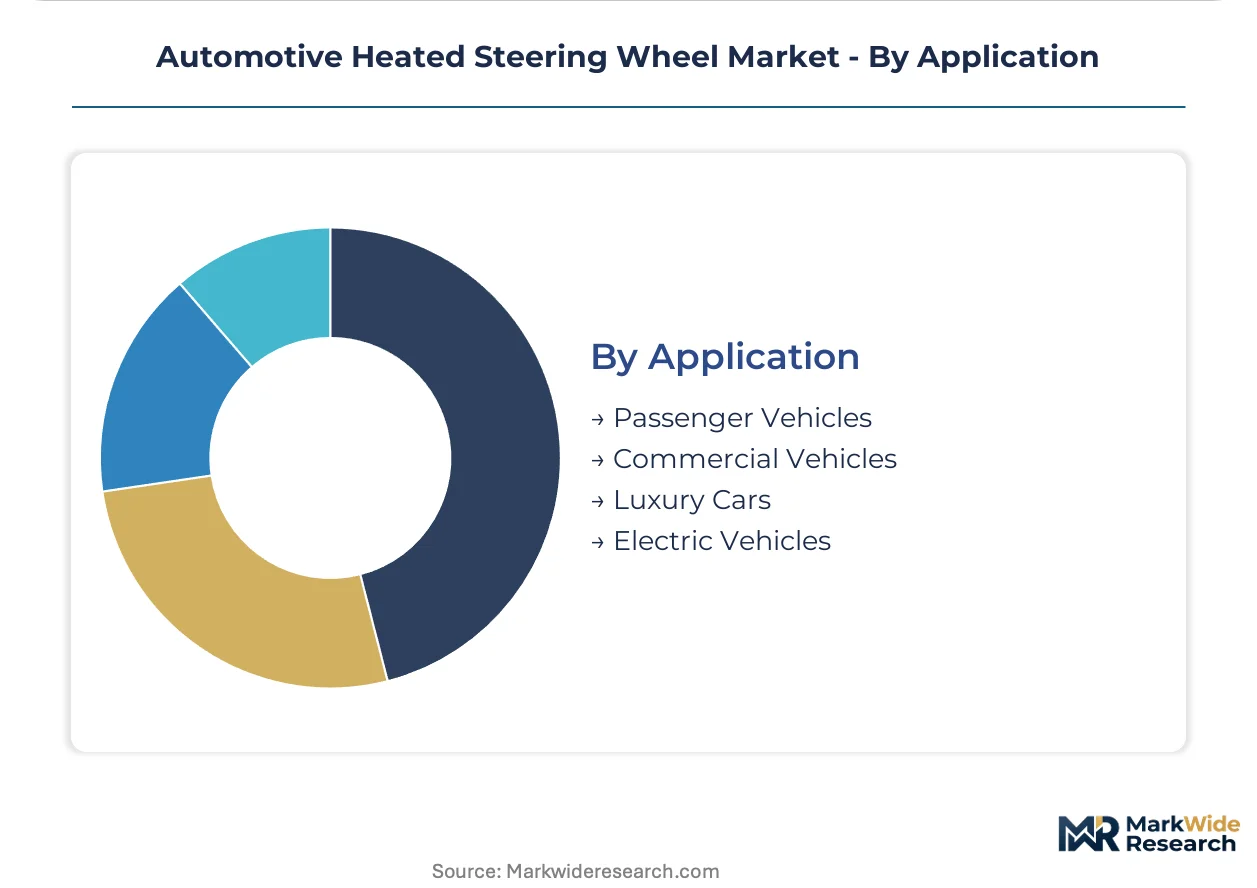
Application:
Vehicle category dictates thermal load requirements, energy budget allocation, and regulatory compliance scope.
- Passenger Vehicles:Mass-market sedans, SUVs, and crossovers represent baseline volume demand. EPA CAFE standards incentivize localized heating strategies that reduce overall cabin HVAC energy draw in this segment.
- Electric Vehicles:Battery thermal management priorities force heating element integration with vehicle energy management systems. PTC technology displacement is most advanced here due to precise thermal control requirements.
- Luxury Cars:Premium European OEMs bundle heated steering wheels with comprehensive climate-comfort packages as standard equipment. Material disclosure mandates from German and Swedish manufacturers extend to tier-two heating element providers.
- Commercial Vehicles:Long-haul trucks and vocational equipment prioritize driver alertness and ergonomic safety over occupant comfort. Uptake concentrates in cold-climate logistics corridors where winter operation sustains consistent demand.
Unit volume concentrates in Passenger Vehicles; specification intensity is expanding most quickly in Electric Vehicles as platform electrification compresses traditional component boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates manufacturing capacity for thermal management subsystems, while consumption tilts toward northern China, Japan, and South Korea where winter climates sustain consistent OEM demand. Production clusters in Bavaria and Baden-Württemberg supply integrated heating modules to luxury vehicle platforms across multiple continents.
China
Northern provinces including Heilongjiang and Jilin generate sustained demand for cold-climate comfort packages, with Beijing-Tianjin-Hebei anchoring domestic OEM specification authority. The Ministry of Industry and Information Technology enforces GB standards for vehicle electrical safety that govern heating element certification timelines. Shanghai-based tier-one suppliers coordinate wiring harness integration for both domestic brands and joint-venture platforms.
Germany
Bavarian luxury manufacturers bundle heated steering wheels as standard equipment across climate-comfort packages, eliminating standalone option uptake. The Kraftfahrt-Bundesamt administers type-approval protocols that extend development cycles for steering system modifications. Stuttgart and Ingolstadt industrial corridors host concentrated supplier engineering centers serving premium EV architectures migrating to 48V systems.
United States
EPA Corporate Average Fuel Economy standards incentivize localized heating strategies that reduce cabin HVAC energy draw in mass-market vehicles. NHTSA Federal Motor Vehicle Safety Standards govern steering integrity and material flammability requirements for embedded heating elements. Michigan-based tier-one suppliers anchor North American production networks serving Detroit Three and transplant OEM platforms.
Japan
Fleet operators in Tokyo and Osaka mandate heated steering wheels as standard equipment to reduce winter customer churn in rental and subscription segments. METI oversees JIS standards for automotive electrical components that influence heating element design specifications. Nagoya industrial clusters concentrate manufacturing scale for integrated thermal modules serving domestic and export vehicle production.
South Korea
Seoul Capital Area OEMs specify heated steering wheels across premium and mass-market segments to meet consumer expectations for cold-climate comfort. The Ministry of Trade, Industry and Energy coordinates with MFDS on material safety standards affecting steering wheel substrate chemistries. Busan-Ulsan manufacturing corridors supply integrated heating modules to both domestic brands and global platform partners.
Automotive Heated Steering Wheel Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated thermal management subsystem providers, discrete component fabricators, and climate-comfort package consolidators. Consolidation pressure is accelerating as platform electrification forces heating element redesign for 48V architectures. Dominant competitive moves include backward integration into sensor production and strategic partnerships with battery thermal management specialists.
Within the integrated subsystem tier, Gentherm and Lear Corporation exemplify divergent scale strategies. Gentherm occupies a position as a pure-play thermal specialist with concentrated expertise in resistive and PTC heating technologies. Lear Corporation represents diversified interior systems consolidation, leveraging manufacturing scale across multiple vehicle platforms and geographic markets. Continental anchors a third archetype as a diversified conglomerate with backward integration into control module production.
| Leading Market Players |
|---|
| Magna International |
| Lear Corporation |
| Gentherm |
| Autoliv |
| Continental |
| ZF Friedrichshafen |
| Hyundai Mobis |
| Key Safety Systems |
| Joyson Safety Systems |
| Others |
Supply Flow & Price Mechanics
Controls engineers fluent in AUTOSAR and functional safety protocols concentrate in Stuttgart and Ingolstadt industrial corridors, and labor-cost differentials between these German engineering clusters and Eastern European manufacturing zones widen pricing-tier spreads across integrated thermal modules and aftermarket retrofit solutions.
Pricing Analysis
Margin tightening in aftermarket retrofit tiers traces to low-cost clip-on heating solutions from unbranded Asian manufacturers. Three-tier pricing structure across premium OEM-integrated, standard dealer-option, and economy aftermarket levels separates Gentherm and Lear contract values from independent distributor SKUs. Price differentiation hinges on NHTSA certification grade and copper input hedging strategies. Fleet operators in Japan and South Korea exhibit lowest price sensitivity due to total cost of ownership calculations prioritizing driver retention metrics.
Supply Chain Analysis
NHTSA material flammability certification and KBA type-approval protocols gate supplier entry into premium OEM channels. Manufacturing concentrates in Germany, China, and South Korea. Copper wiring harnesses, PTC ceramic elements, and polymer steering wheel substrates draw from commodity markets with volatile spot pricing. Single-source vulnerability concentrates in Bavarian sensor module production. Distribution runs through tier-one interior systems consolidators to vehicle assembly plants, with aftermarket channels fragmenting across online retail and independent repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification is forcing heated steering wheel redesign for 48V architectures, squeezing weaker component fabricators without backward integration capabilities or software-defined thermal optimization expertise.
For Market Incumbents: Deepen captive supply of PTC ceramic elements and sensor control modules to defend margin position against Continental's backward integration strategy. Acquire AUTOSAR-capable engineering teams in Stuttgart and Nagoya industrial clusters before talent scarcity worsens. Prioritize 48V architecture pre-qualification contracts with premium European EV platforms to lock out mid-tier competitors.
For New Entrants and Emerging Players: Begin with wireless inductive heating configurations targeting subscription fleet operators in Japan and South Korea seeking reversible upgrades without harness integration. Target underpenetrated southern Chinese provinces where rising disposable income creates first-time comfort feature demand. Pursue direct fleet procurement channels displacing traditional dealer-option ordering.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play thermal specialists possessing PTC technology portfolios and OEM pre-qualification status given accelerating resistive-to-PTC migration in electric vehicle architectures. Long-term viability favors suppliers with software-defined vehicle integration capabilities and multi-jurisdiction homologation expertise. Monitor 48V platform launch timelines at German and North American OEMs as inflection indicator for contract award velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| PTC Technology Migration | Self-regulating heating elements eliminate external control modules and reduce wiring complexity in 48V EV architectures. |
| Software-Defined Thermal Integration | Heating controls merged with vehicle energy management systems enable precise battery thermal protection and cabin efficiency optimization. |
| Fleet Direct Contracting | Subscription vehicle operators in Tokyo and Osaka now bypass dealer channels to mandate heated steering wheels as standard equipment. |
| EU REACH Compliance Investment | Material disclosure mandates from German and Swedish OEMs extend to tier-two heating element providers serving EU-bound production. |
| 48V Architecture Pre-Qualification | Early platform engineering engagement with Stuttgart and Ingolstadt OEMs locks in multi-year supply positions before competitor redesign cycles complete. |
Methodological Framework
Multi-period observation of vehicle platform electrification timelines, thermal content per vehicle trajectories, and OEM climate-package bundling patterns anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from NHTSA FMVSS filings, EPA CAFE compliance databases, vehicle production registries, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Input-output matrices mapped heating element unit demand to vehicle production forecasts across passenger, electric, luxury, and commercial vehicle categories. Segmentation dimensions modeled include product integration depth, end-user procurement authority, heating technology architecture, and regional production cluster. CAGRs were derived from slope analysis of historical fitment rates projected against platform launch schedules. Industry-specific forecast inputs incorporated 48V electrical architecture migration curves and cold-climate package standardization trends.
Underlying measurement precision varies by segment; integrated OEM fitment data carries tighter precision than aftermarket retrofit estimates due to fragmented channel reporting. Forecasts reflect documented assumptions regarding platform electrification timelines and regulatory compliance cost pass-through. A model refresh is warranted upon material change in 48V architecture adoption velocity or REACH chemical restriction expansion affecting steering wheel substrate materials.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market