
 Heated Steering Wheel Market | 2026-2036
Heated Steering Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Steering Wheel Market Outlook
China is fragmenting as domestic EV suppliers build heated steering wheel capacity alongside established tier-1 auto parts corridors. Gentherm Inc. anchors North American thermal comfort supply through its specialized heating element manufacturing. Valeo competes in European premium OEM channels with integrated cockpit climate systems. Lear Corporation extends its seating thermal expertise into steering wheel applications through modular electronics platforms.
A heated steering wheel integrates resistive heating elements—typically carbon fiber mats, metal wire grids, or flexible printed circuits—beneath leather or synthetic wrap materials, drawing 20-60 watts from the vehicle electrical system to maintain surface temperatures between 30°C and 40°C for driver hand comfort in cold ambient conditions. OEM solutions dominate value capture due to embedded electronics architecture and warranty integration, while aftermarket kits serve vehicle customization channels with simpler clip-on or wrap designs. Carbon fiber heating leads technology adoption for its rapid warm-up and uniform heat distribution, though flex circuit heating gains traction in cost-optimized mid-range platforms.
NHTSA guidelines influence heated steering wheel design through electrical safety and driver distraction protocols, while EPA corporate average fuel economy standards push suppliers toward lower-wattage heating technologies that reduce auxiliary power draw. China's MIIT enforces GB standards for automotive electrical component reliability that shape export qualification requirements. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking as these frameworks begin to touch interior component sourcing decisions.
Market Dynamics
EPA fuel-efficiency standards and China's dual carbon goals are compressing auxiliary power budgets, forcing automakers to redesign heated steering wheel architectures around sub-40-watt heating elements and intelligent thermal management circuits.
Growth Catalysts
- Cold-Climate EV Differentiation:Premium electric vehicle platforms in China now bundle heated steering wheels with battery preconditioning systems as standard cold-weather packages, elevating the feature from luxury option to competitive necessity.
- NHTSA Electrical Safety Protocols:Updated guidelines for automotive cabin electronics are accelerating OEM adoption of integrated heating modules with embedded fault detection, reducing liability exposure and warranty costs.
- Carbon Fiber Mat Technology:Rapid warm-up characteristics and uniform heat distribution are displacing metal wire grids in mid-range vehicle platforms, expanding addressable market beyond luxury segments.
Market Restraints
- Copper and Silver Input Volatility:Conductive materials in flex circuit heating elements face price instability from mining supply disruptions, compressing margins for cost-optimized platform suppliers.
- German Supply Concentration:Factory capacity expansion for heated steering wheel modules remains concentrated in Baden-Württemberg and Bavaria, creating geographic vulnerability to energy cost spikes and logistics constraints.
- Seat Heating Substitution:Rapidly improving seat-based thermal comfort systems in entry-level vehicles reduce perceived value of steering wheel heating as a standalone feature.
Strategic Opportunities
- India Premium Vehicle Penetration:Domestic luxury automakers are introducing heated steering wheels as climate-comfort differentiators in northern mountain markets where cold-start conditions persist.
- EU Green Deal Embodied Carbon Tracking:Suppliers with verified low-carbon leather sourcing and recycled synthetic wrap materials gain preferential qualification status with European OEM sustainability procurement teams.
- Smartphone-Enabled Aftermarket Kits:Bluetooth-controlled clip-on heating elements with app-based temperature scheduling are opening direct-to-consumer channels outside traditional automotive distribution.
Industry Challenges
- Embedded Software Certification:Functional safety validation for heating control algorithms under ISO 26262 extends development timelines and requires specialized automotive software engineering talent.
- Legacy 12V Electrical Architecture Integration:Heated steering wheel modules must maintain compatibility with aging vehicle electrical systems while optimizing for 48V mild-hybrid platforms, doubling validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Steering Wheel Market |
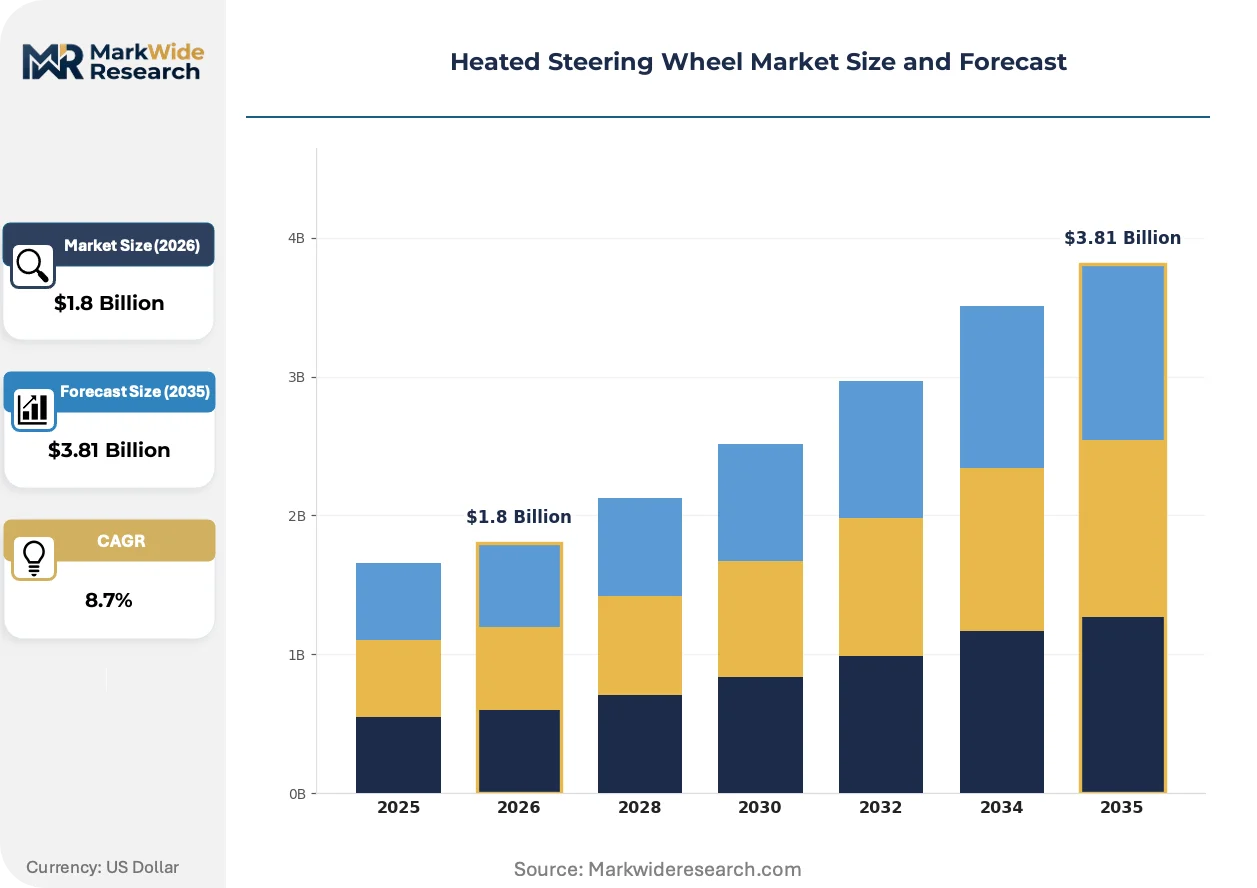
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Aftermarket Kits, OEM Solutions, Custom Designs End User: Luxury Vehicles, Mid-Range Cars, SUVs, Commercial Trucks Technology: Carbon Fiber Heating, Metal Wire Heating, Heated Gel, Flex Circuit Heating Application: Passenger Comfort, Safety Enhancement, Sports Models, Vehicle Customization |
| Companies Covered | Hyundai Mobis, Denso, Gentherm Inc., Lear Corporation, Valeo, ZF Friedrichshafen AG, Robert Bosch, Autoliv Inc., Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Steering Wheel Market Strategic Shifts
Technology convergence between thermal management systems and vehicle electrical architectures is redefining component boundaries, with heating elements increasingly treated as intelligent nodes within distributed cabin comfort networks rather than passive accessories.
Flex circuit heating technology is migrating from cost-optimized mid-range platforms toward premium electric vehicle applications as automakers seek weight reduction and form-factor flexibility for steering wheel designs with integrated capacitive touch controls and haptic feedback surfaces. European OEMs are adopting this technology fastest, using it to consolidate multiple electronic functions within a single substrate layer.
China's MIIT enforcement of updated GB standards for automotive electrical component reliability is compelling export-oriented suppliers to redesign heating element enclosures and connector systems, with particular pressure on wire-to-board termination methods and moisture ingress protection. Domestic EV manufacturers are using this compliance barrier to disadvantage smaller international competitors lacking in-country testing facilities.
Buyer procurement patterns are fragmenting as fleet operators and vehicle subscription services unbundle cabin comfort features from base vehicle specifications, creating spot-market demand for heated steering wheel retrofits and modular upgrade paths. This behavior is most visible in Scandinavian corporate fleet channels where seasonal equipment flexibility reduces total cost of ownership calculations.
Heated Steering Wheel Market Segmentation
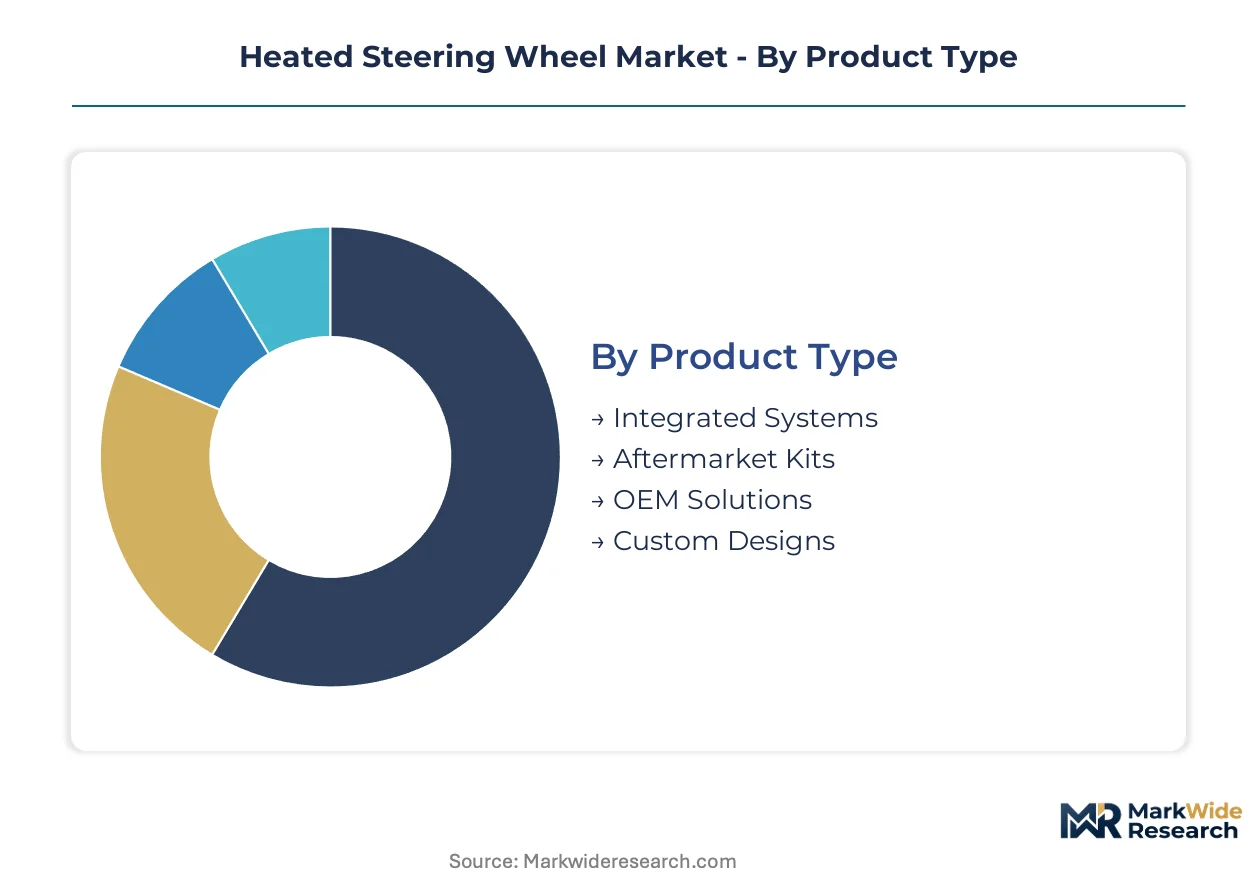
Segmentation in the heated steering wheel market reveals how warranty integration, retrofit complexity, and thermal performance specifications reshape supplier economics across installation channels. Understanding these divides exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
After-sales-service intensity varies dramatically across installation channels, with embedded electronics architectures demanding specialized diagnostic capabilities and modular aftermarket kits requiring minimal technical intervention.
- Integrated Systems:Factory-installed heating modules with embedded control electronics and vehicle network integration command premium pricing through warranty bundling and dealer service lock-in. Demand concentrates in German luxury OEM supply chains where thermal management systems merge with cockpit electronics platforms.
- OEM Solutions:Original equipment specifications featuring carbon fiber mat heating and ISO 26262-compliant control algorithms dominate value capture through multi-year supply agreements and design-in exclusivity. North American thermal comfort specialists anchor production capacity for these configurations.
- Aftermarket Kits:Clip-on or wrap-based heating elements with simplified 12V power connections serve vehicle customization channels with lower technical barriers.
- Custom Designs:Bespoke heating configurations for specialty vehicle builders and restoration projects occupy niche volume tiers with elongated lead times.
OEM Solutions holds the largest share; momentum sits with Integrated Systems as cockpit electronics consolidation accelerates.
End User:
Cost tier stratification separates warranty-integrated premium installations from price-sensitive retrofit applications, with thermal comfort specifications scaling directly with vehicle transaction values.
- Luxury Vehicles:Factory-standard heated steering wheels with carbon fiber heating and leather-wrapped surfaces represent baseline equipment rather than optional upgrades. Chinese premium EV manufacturers bundle these with battery preconditioning systems as cold-climate competitive differentiators.
- SUVs:Family-oriented utility vehicles increasingly specify heated steering wheels across trim levels, with flex circuit heating gaining traction for weight reduction in electrified platforms. European OEMs lead adoption of consolidated substrate designs.
- Mid-Range Cars:Cost-optimized platforms prioritize seat heating over steering wheel thermal comfort, compressing addressable volume for standalone heating modules.
- Commercial Trucks:Fleet procurement patterns treat cabin comfort as seasonal equipment with retrofit flexibility, creating spot-market demand patterns distinct from retail vehicle channels.
Luxury Vehicles commands the dominant revenue position; SUVs are expanding most quickly as electrification drives thermal feature standardization.
Technology:
Volume concentration in carbon fiber mat production has created supply bottlenecks, while flex circuit manufacturing scales more readily across automotive electronics suppliers.
- Carbon Fiber Heating:Woven resistive mats delivering rapid warm-up and uniform surface temperature distribution dominate premium applications. German factory capacity expansions in Baden-Württemberg concentrate supply for European OEM channels.
- Flex Circuit Heating:Flexible printed circuit substrates with etched copper traces enable weight reduction and form-factor adaptability for steering wheels integrating capacitive touch and haptic feedback. MIIT GB standards compliance pressures reshape wire-to-board termination designs for export qualification.
- Metal Wire Heating:Traditional wire grid configurations face displacement in mid-range segments as carbon fiber costs decline.
- Heated Gel:Phase-change thermal media occupy limited application niches where surface conformability outweighs warm-up speed requirements.
Carbon Fiber Heating retains the largest installed base; Flex Circuit Heating gains share fastest as cockpit electronics integration demands substrate consolidation.
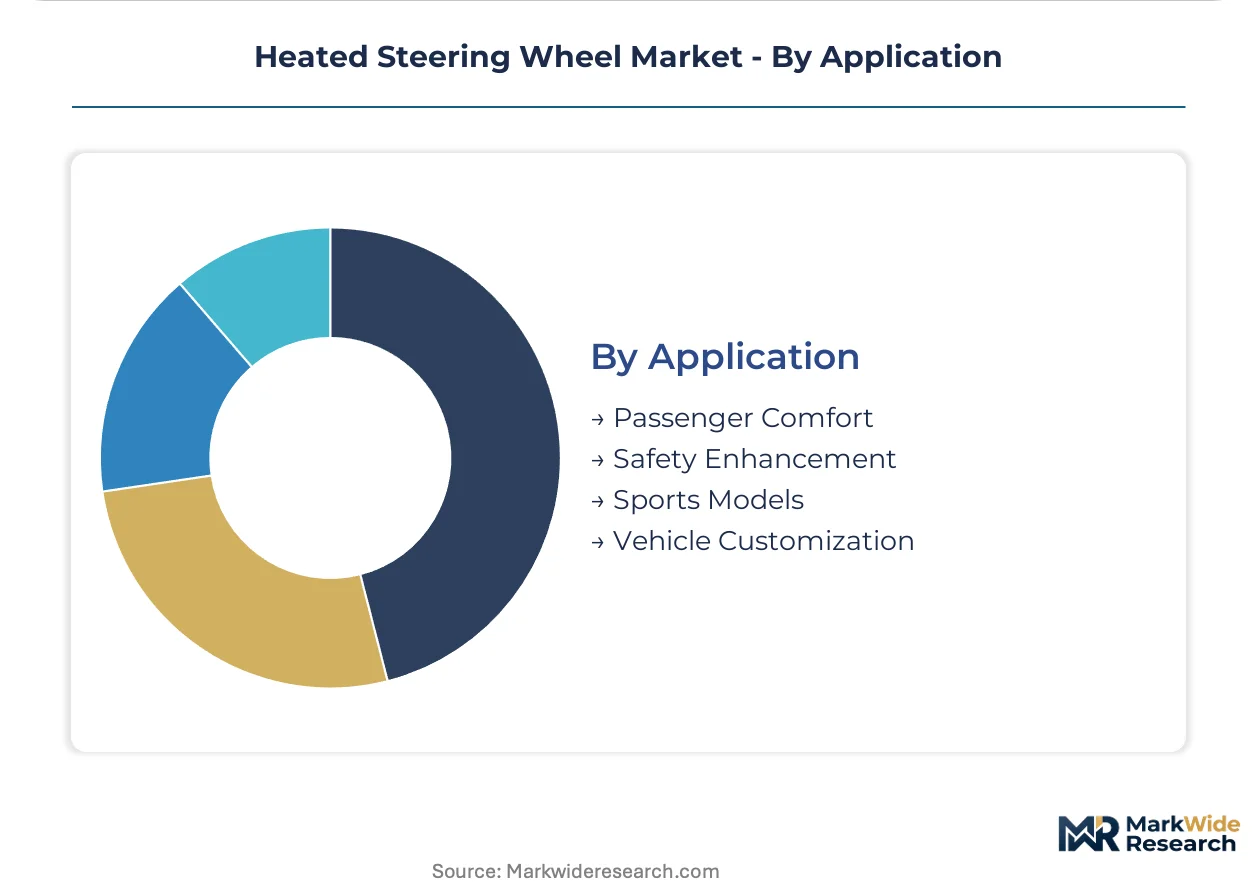
Application:
Customer type fragmentation separates fleet procurement flexibility from retail buyer expectations of permanent feature integration, with safety regulation emerging as a distinct demand driver.
- Passenger Comfort:Thermal comfort specifications targeting cold-climate driver hand warming represent the foundational use case, with NHTSA electrical safety protocols accelerating fault-detection module adoption.
- Safety Enhancement:Reduced driver distraction from cold-induced discomfort supports regulatory acceptance of heated steering wheels as active safety adjuncts. EPA fuel-efficiency standards favor lower-wattage implementations in this framing.
- Sports Models:Performance-oriented vehicles specify lightweight heating elements with minimal steering feel compromise.
- Vehicle Customization:Enthusiast and restoration markets sustain demand for retrofit-compatible heating solutions outside OEM distribution channels.
Passenger Comfort dominates volume; Safety Enhancement shows the steepest expansion trajectory as regulatory frameworks incorporate thermal ergonomics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA electrical safety protocols and EPA fuel-efficiency standards anchor United States market development, while Germany's factory capacity expansions and China's MIIT enforcement reshape supply-side geography across the forecast window.
United States
Premium electric vehicle platforms from domestic automakers bundle heated steering wheels with battery preconditioning systems as cold-weather competitive necessities. NHTSA updated guidelines for automotive cabin electronics accelerate OEM adoption of integrated heating modules with embedded fault detection. Thermal comfort specialists concentrate manufacturing capacity in Michigan and Ohio to serve Detroit Three supply chains.
Germany
Luxury vehicle manufacturers expand factory capacity for heated steering wheel modules in Baden-Württemberg and Bavaria to meet European premium OEM demand. KBA type-approval processes enforce electrical safety validation that shapes control algorithm development timelines. Stuttgart and Munich industrial corridors concentrate carbon fiber mat production capacity for cockpit climate integration.
China
Domestic EV suppliers build heated steering wheel capacity alongside established tier-1 auto parts corridors in the Yangtze River Delta. MIIT enforcement of updated GB standards for automotive electrical component reliability compels export-oriented suppliers to redesign heating element enclosures. Shanghai and Suzhou testing facilities advantage domestic manufacturers over smaller international competitors lacking in-country certification infrastructure.
Japan
Automotive electronics specialists develop flex circuit heating substrates for steering wheels integrating capacitive touch and haptic feedback surfaces. METI technology roadmaps for vehicle electrification push suppliers toward lower-wattage heating implementations. Nagoya and Tokyo industrial basins concentrate substrate manufacturing for cockpit electronics consolidation.
India
Domestic luxury automakers introduce heated steering wheels as climate-comfort differentiators in northern mountain markets where cold-start conditions persist. BIS automotive electrical component standards shape import qualification requirements for heating module suppliers. Maharashtra and Gujarat manufacturing corridors attract component assembly investments from multinational tier-1 suppliers.
Heated Steering Wheel Market Competitive Environment
Capability concentration sits with specialized thermal comfort engineers; scale advantage sits with diversified cockpit electronics platforms. The vendor base separates into three tiers: integrated module specialists commanding warranty-embedded supply agreements, diversified tier-1 suppliers leveraging seating and electronics expertise, and regional aftermarket fabricators serving customization channels. Dominant competitive moves include capacity expansion in Germany's automotive corridors and technology licensing partnerships for flex circuit substrate integration.
Among North American thermal comfort specialists, Gentherm Inc. and Lear Corporation exemplify the integrated module archetype through specialized heating element manufacturing and modular electronics platforms respectively. Valeo occupies a position representing European premium-tier cockpit climate integration. These three anchors illustrate how geographic specialization and end-market focus stratify competitive positioning across OEM supply chains.
| Leading Market Players |
|---|
| Hyundai Mobis |
| Denso |
| Gentherm Inc. |
| Lear Corporation |
| Valeo |
| ZF Friedrichshafen AG |
| Robert Bosch |
| Autoliv Inc. |
| Continental |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg and Bavaria factory capacity expansions for carbon fiber mat production concentrate upstream supply, anchoring margin capture with German luxury OEMs while compressing pricing power for tier-2 suppliers serving cost-optimized platforms. This geographic concentration shapes how value distributes across integrated systems versus aftermarket channels.
Pricing Analysis
North American OEMs command 15-25% price premiums over European counterparts for equivalent heated steering wheel specifications, reflecting warranty bundling and embedded electronics architecture. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber heating with ISO 26262-compliant fault detection from flex circuit mid-range implementations and basic metal wire aftermarket kits. Cost compression in mid-range segments is intensifying because seat heating substitution reduces perceived standalone value. Fleet operators and vehicle subscription services exhibit highest price sensitivity, while luxury vehicle manufacturers remain least sensitive due to design-in exclusivity and multi-year supply agreements.
Supply Chain Analysis
Extended payment terms from German luxury OEMs now stretch to 90-120 days, forcing tier-1 suppliers to utilize supply-chain finance facilities and compressing working capital for carbon fiber mat producers. Manufacturing concentrates in Germany, China, and Japan, with Yangtze River Delta capacity expanding fastest for domestic EV supply. Conductive copper and silver traces, leather wrap materials, and specialized connector systems constitute critical input dependencies. Single-source vulnerability around German carbon fiber mat production creates geographic concentration risk. Distribution runs through OEM direct supply agreements for integrated systems, while aftermarket kits reach consumers through automotive retailers and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heated steering wheel market is recovering from cyclical compression in entry-level vehicle specifications, driven by electrification-driven thermal feature standardization across SUV and premium EV platforms.
For Market Incumbents: Entrench carbon fiber heating technology leadership through backward integration into specialized mat manufacturing in Baden-Württemberg, securing supply continuity against emerging flex circuit substitution. Deepen embedded software certification capabilities under ISO 26262 to extend development timeline barriers against new entrants lacking automotive functional safety expertise.
For New Entrants and Emerging Players: Northern Indian mountain markets present underpenetrated white space where domestic luxury automakers are introducing climate-comfort differentiators with minimal established supplier presence. Smartphone-enabled aftermarket kits with Bluetooth-controlled clip-on heating elements offer the most penetrable entry path, leveraging direct-to-consumer distribution outside traditional automotive channels and app-based temperature scheduling as a go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward flex circuit substrate specialists with MIIT GB standards compliance capabilities and established relationships with Japanese automotive electronics integrators. Long-term viability hinges on cockpit electronics consolidation trends treating heating elements as intelligent nodes within distributed cabin comfort networks. Watch for fleet procurement pattern shifts toward seasonal equipment flexibility as an inflection indicator for modular upgrade path demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation burden across 12V and 48V electrical architectures for OEM supply chains. |
| Flex Circuit Substrate Integration | Enables weight reduction and form-factor consolidation with capacitive touch controls for European OEMs. |
| MIIT GB Standards Compliance Investment | Secures export qualification for wire-to-board termination and moisture ingress protection redesigns. |
| Low-Carbon Material Sourcing Certification | Grants preferential qualification status with European OEM sustainability procurement teams under EU Green Deal. |
| Intelligent Thermal Management Circuit Development | Addresses EPA fuel-efficiency standards through sub-40-watt heating element architectures. |
Study Parameters
Cross-validation between OEM platform engineering interviews and Tier 1 supplier procurement disclosures anchors the qualitative findings, supplemented by secondary validation from NHTSA guideline documentation, EPA fuel-efficiency standard filings, and MIIT GB standards enforcement records. Primary engagement spanned thermal comfort engineering directors, automotive electronics procurement managers, aftermarket distribution channel heads, and vehicle fleet operations specialists. Bottom-up build from heating element production capacity and top-down triangulation from vehicle production databases established volume baselines.
Calibration against historical technology transitions in automotive cabin comfort systems informed adoption curve assumptions across the projection horizon. Segmentation dimensions modeled include installation channel, vehicle class, heating technology type, propulsion architecture, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating battery preconditioning system bundling trends and cold-climate EV differentiation intensity. Industry-specific inputs encompassed copper and silver price volatility indices, German factory capacity utilization rates, and China domestic EV production forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic EV suppliers or accelerated flex circuit technology licensing by Japanese substrate manufacturers would shift outcomes. Macroeconomic deviation in conductive materials pricing, regulatory tightening in embodied carbon tracking, or breakthroughs in seat-based thermal comfort substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market