
 US Automotive Wrap Films Market | 2026-2036
US Automotive Wrap Films Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Wrap Films Market Intelligence
California's Air Resources Board (CARB) VOC emission standards for adhesive products is repositioning formulation priorities across the US automotive wrap films supply base. Avery Dennison Corporation leverages its materials science heritage to sustain premium positioning in cast vinyl solutions. 3M anchors the performance segment through proprietary pressure-sensitive adhesive platforms. ORAFOL Americas Inc. differentiates via regional manufacturing presence and rapid fulfillment to domestic installers.
US automotive wrap films comprise multi-layer polymer constructions—typically calendered or cast vinyl films with pigmented or printed face stocks, pressure-sensitive adhesive layers, and release liners—engineered for conformability to complex vehicle geometries and removability without substrate damage. Their primary commercial purpose spans fleet branding, paint protection, and consumer aesthetic customization. Cast vinyl dominates margin pools due to superior conformability and durability, while polyurethane films represent the fastest-growing substrate as paint protection film adoption accelerates among luxury vehicle owners. Wet application methods retain volume leadership in professional channels, though dry application gains share through simplified installer training requirements.
NHTSA surface visibility standards and EPA VOC regulations under the Clean Air Act shape product compliance requirements for domestic manufacturers and importers. OSHA workplace exposure limits for solvent-based adhesives influence installer safety protocols and product selection criteria. State-level environmental mandates, particularly California's SCAQMD Rule 1168, create additional formulation constraints that favor water-based and low-VOC alternatives. Stakeholders must monitor evolving state-by-state regulatory divergence and assess whether centralized formulation strategies or regional product variants offer superior compliance economics.
Market Dynamics
Fleet operators across Texas, Florida, and California are consolidating vehicle procurement under national branding contracts, compressing installer margins while expanding volume throughput requirements for wrap film distributors.
Growth Catalysts
- CARB VOC Regulations:California's Air Resources Board mandates on adhesive formulations are accelerating water-based and low-emission product development, creating first-mover advantages for compliant suppliers.
- Luxury Vehicle Owners:Polyurethane paint protection film adoption among high-end automotive consumers is expanding addressable market scope beyond traditional commercial fleet segments.
- Dry Application Methods:Simplified installer training protocols are reducing labor certification barriers and broadening the qualified technician base across secondary metropolitan markets.
Market Restraints
- Petrochemical Input Volatility:Vinyl resin and adhesive precursor costs fluctuate with crude oil derivatives, compressing formulation margins without corresponding pricing elasticity in fleet contracts.
- Midwest Supply Concentration:Domestic manufacturing of cast vinyl films clusters in Ohio and Illinois, creating regional fulfillment bottlenecks for West Coast installer networks.
- Removability Performance Thresholds:NHTSA surface visibility standards constrain adhesive aggression levels, limiting film durability on complex vehicle geometries versus international formulations.
Strategic Opportunities
- Paint Protection Film Convergence:Polyurethane substrates are integrating with self-healing topcoat technologies, opening premium positioning in luxury dealer channel partnerships.
- SCAQMD Rule 1168 Compliance:South Coast Air Quality Management District mandates create regulatory tailwinds for water-based adhesive specialists serving Southern California's dense fleet markets.
- Direct-to-Installer Platforms:Digital procurement channels are disintermediating traditional distributor networks, enabling faster fulfillment and customized roll-width offerings for specialized applicators.
Industry Challenges
- Certified Installer Scarcity:OSHA solvent-exposure training requirements and manufacturer warranty certification programs create multi-month qualification timelines that throttle service expansion.
- Application Method Standardization:Wet versus dry technique disputes between regional installer associations delay national service protocol unification and cross-market labor mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Wrap Films Market |
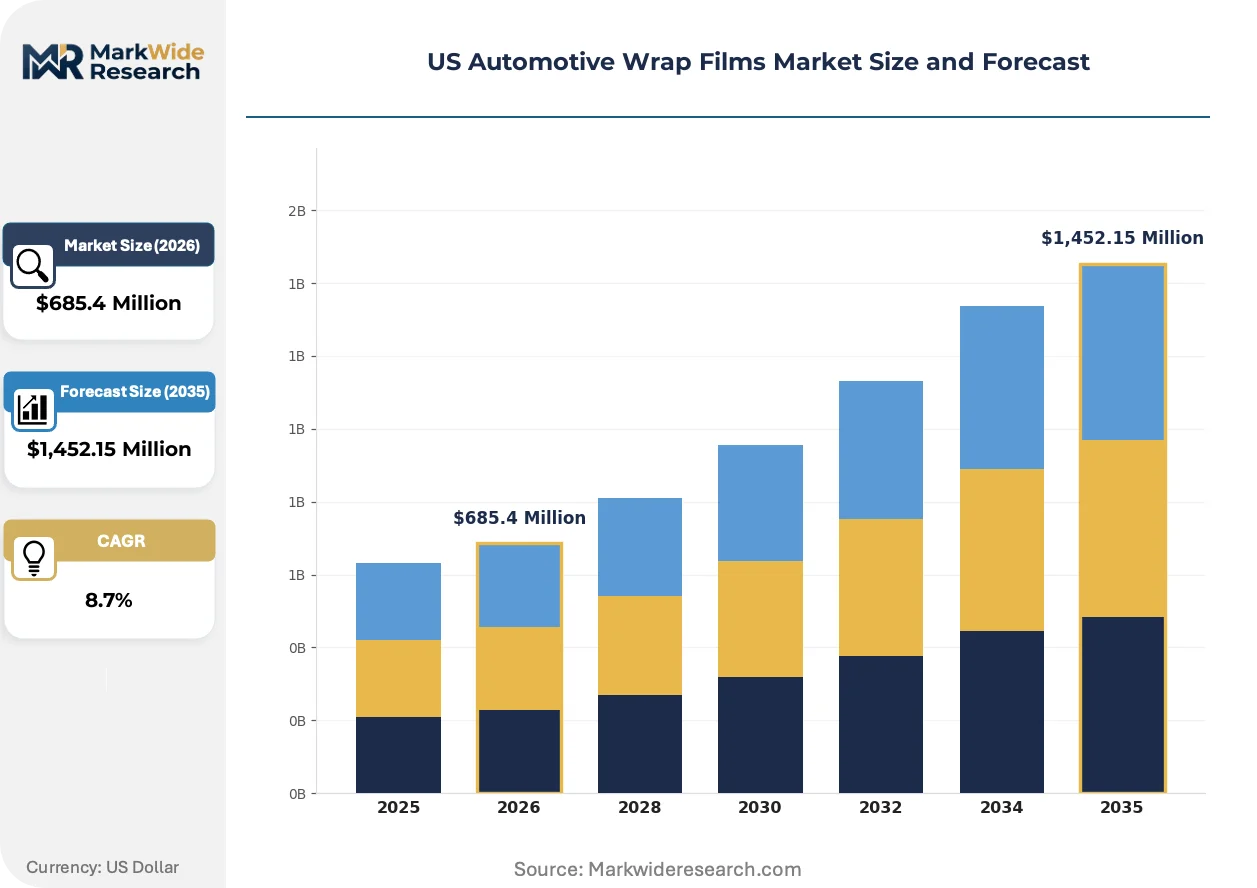
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, PVC, Polyurethane, Others Application: OEMs, Dealerships, Aftermarket Providers, Fleet Owners Installation Method: Wet Application, Dry Application, Spray Application, Heat Activation Finish Type: Gloss, Matte, Satin, Textured |
| Companies Covered | Avery Dennison Corporation, 3M, Arlon Graphics, LLC, ORAFOL Americas Inc., Hexis S.A.S., KPMF, Vvivid Vinyl, Fedrigoni S.P.A., JMR Graphics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Wrap Films Market Strategic Shifts & Innovations
Digital color-matching systems and automated cutting plotters are compressing design-to-installation timelines, while regulatory pressure on volatile compounds is forcing reformulation investments across adhesive supply chains.
Self-healing polyurethane topcoats are integrating with nanoceramic protective layers to extend paint protection film service life beyond five years. Luxury vehicle owners in Texas and Florida are adopting these hybrid constructions at accelerated rates. The technology is integrating aesthetic customization with functional surface preservation, collapsing the distinction between wrap films and traditional clear bra products.
EPA enforcement of Clean Air Act VOC thresholds is tightening adhesive emission allowances for imported film products. Domestic manufacturers with in-house water-based formulation capabilities are capturing share from solvent-dependent imports. California's SCAQMD Rule 1168 is the most restrictive sub-federal standard, forcing regional product variants or nationwide compliance upgrades.
Fleet procurement departments are consolidating vendor relationships under multi-year national contracts with standardized color libraries and volume-based pricing tiers. Traditional regional distributor networks face disintermediation pressure from manufacturer-direct digital platforms offering real-time inventory visibility. The Southwest corridor from Phoenix to Houston exhibits the most pronounced channel consolidation as oilfield service fleets standardize branding across dispersed operations.
US Automotive Wrap Films Market Segmentation
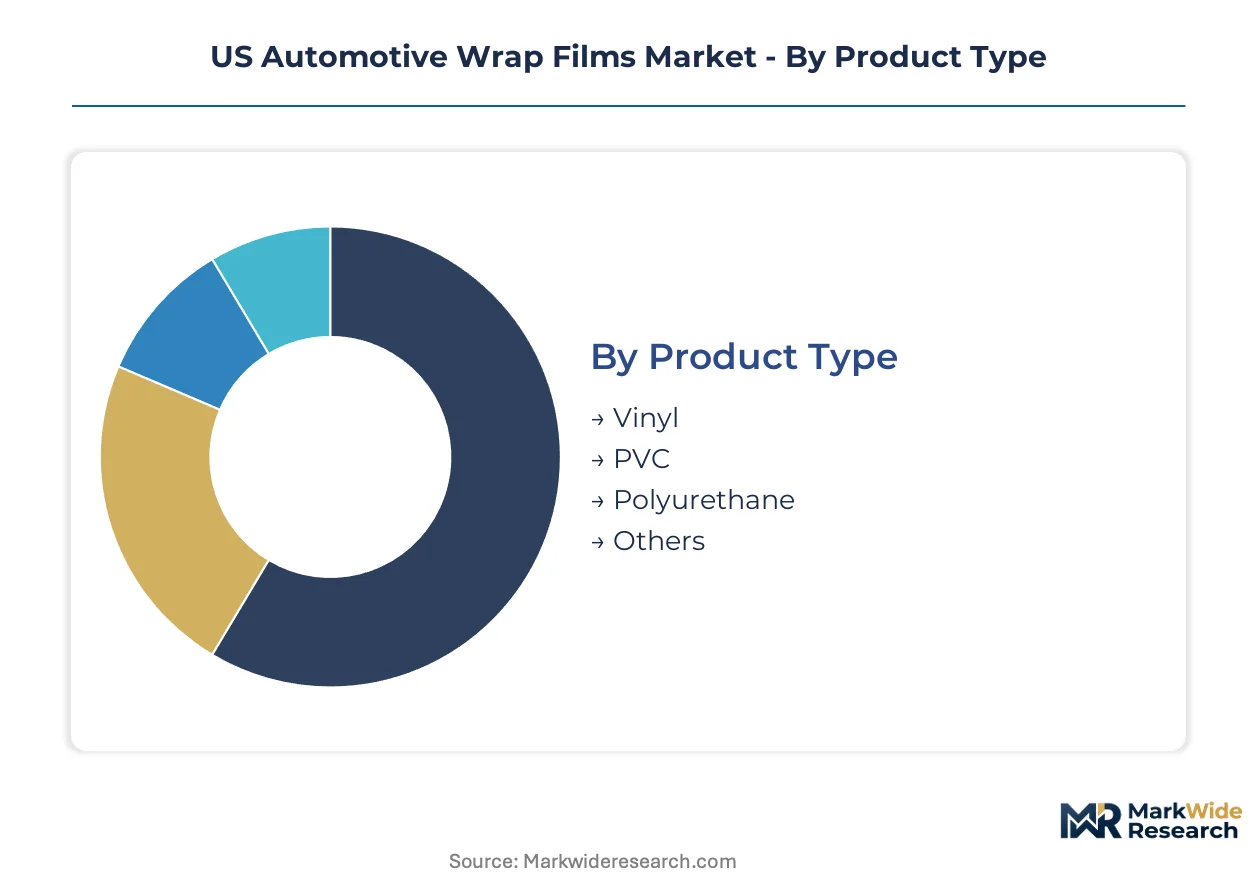
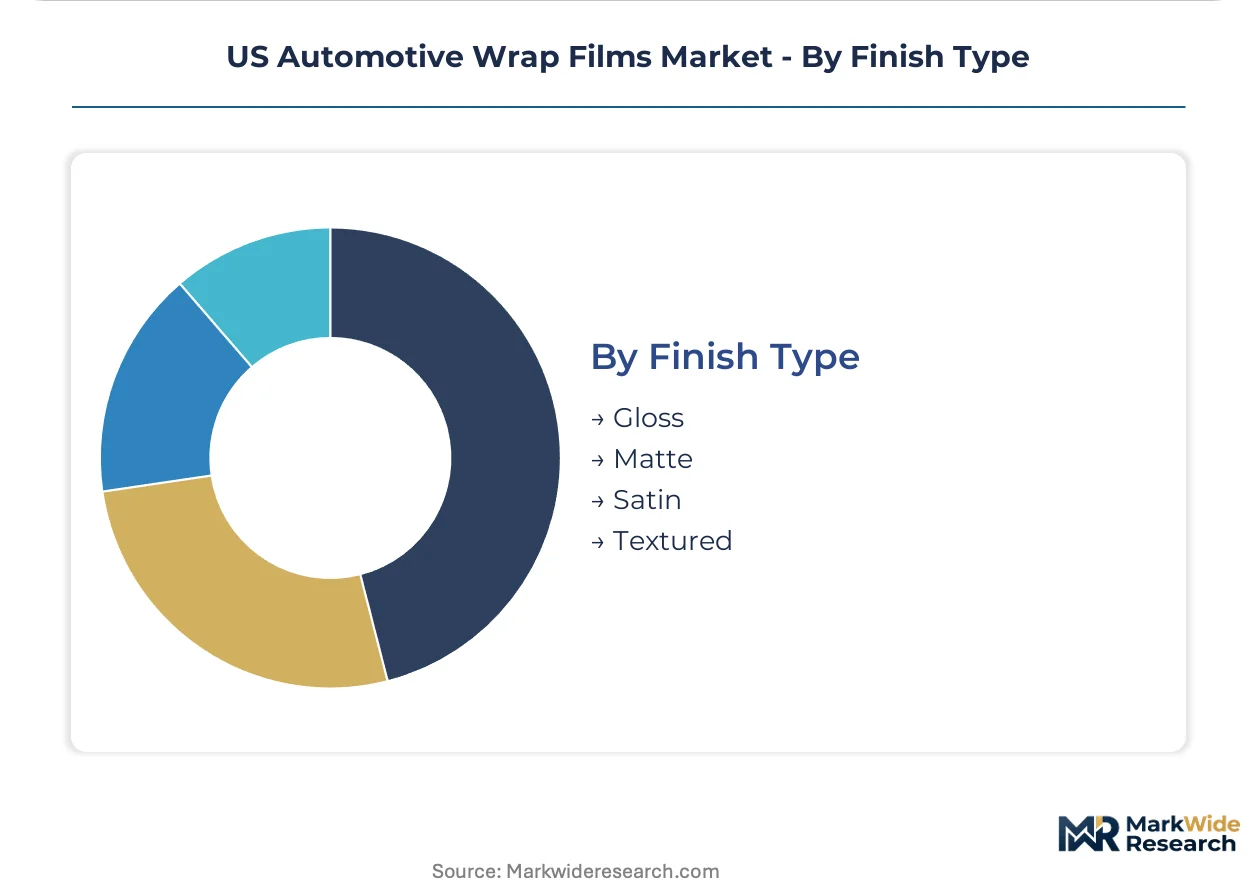
Segmentation in US automotive wrap films reveals how capital deployment, regulatory exposure, and installer skill requirements concentrate value across distinct product and service tiers. Understanding these divisions enables suppliers to align formulation investments with specific margin pools and compliance obligations.
Product Type:
Capital intensity varies sharply across substrate chemistries, with cast vinyl requiring specialized polymerization equipment and polyurethane demanding precision extrusion lines.
- Vinyl:Calendered and cast vinyl formulations dominate commercial fleet procurement due to conformability and removability. Texas and Florida fleet operators specify cast grades for long-haul durability under intense UV exposure.
- Polyurethane:Thermoplastic urethane substrates integrate with self-healing topcoats for paint protection film applications. California luxury vehicle owners drive adoption as dealer channel partnerships expand in Los Angeles and Orange County markets.
- PVC:Lower-cost alternative for short-term promotional wraps and event fleet graphics.
- Others:Emerging bio-based and recycled-content films targeting sustainability mandates in municipal procurement.
Cast vinyl absorbs the bulk of installed capacity; polyurethane is expanding most quickly.
Application:
Customer type determines warranty terms, volume scale, and color standardization requirements across the value chain.
- Fleet Owners:National branding contracts consolidate procurement under standardized color libraries and multi-year service agreements. Oilfield service operators across the Southwest corridor from Phoenix to Houston drive volume concentration.
- Aftermarket Providers:Independent installers serve consumer customization demand with shorter lead times and design flexibility. Secondary metropolitan markets in Texas and Florida exhibit rapid technician base expansion through simplified dry application training.
- OEMs:Factory-applied protective films for high-end vehicle deliveries.
- Dealerships:Add-on paint protection film packages integrated with new vehicle sales.
Fleet procurement absorbs the bulk of volume throughput; aftermarket channels are climbing the fastest.
Installation Method:
Technique selection shapes labor certification requirements, equipment investment, and geographic service radius.
- Wet Application:Slip solutions enable repositioning during installation for complex vehicle geometries. Professional channels retain volume leadership due to superior finish quality on concave surfaces.
- Dry Application:Pressure-sensitive adhesives with air-egress channels reduce training duration and expand qualified technician pools. Secondary markets across Florida and Texas adopt rapidly as labor scarcity constrains wet-method expansion.
- Spray Application:Liquid wrap systems for temporary color change without film substrate.
- Heat Activation:Thermal conforming techniques for compound curves on premium vehicle segments.
Wet methods retain the bulk of professional certification investment; dry application is gaining share fastest.
Finish Type:
Surface aesthetics command price premiums that stratify across consumer versus commercial end-uses.
- Gloss:Mirror-finish films replicate factory paint appearance for fleet color matching and consumer restoration projects. California commercial operators specify gloss grades for brand consistency under CARB-compliant low-VOC formulations.
- Matte:Non-reflective surfaces differentiate luxury vehicles and specialized commercial equipment. Texas custom automotive culture drives adoption for personal vehicle aesthetic distinction.
- Satin:Intermediate sheen bridging gloss and matte for transitional design preferences.
- Textured:Carbon fiber, brushed metal, and patterned finishes for accent applications.
Gloss finishes absorb the bulk of production volume; matte treatments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Los Angeles-Orange County corridor anchors US automotive wrap films demand through its density of commercial fleet operations and luxury vehicle customization culture. Installer networks concentrate along the I-5 corridor connecting Southern California to the Pacific Northwest.
California
California's commercial fleet operators drive premium cast vinyl consumption for brand consistency across dispersed logistics networks. CARB VOC regulations under SCAQMD Rule 1168 compel adhesive reformulation toward water-based chemistries. The Inland Empire distribution cluster east of Los Angeles processes high-volume fulfillment for Southwest installer networks.
Texas
Texas oilfield service fleets generate concentrated demand for durable wraps withstand harsh Permian Basin operating conditions. State environmental regulations align with federal EPA standards without additional VOC constraints. The Dallas-Fort Worth metroplex hosts expanding installer training facilities serving secondary markets across the Southwest corridor.
Florida
Florida's tourism and real estate fleet operators specify UV-resistant formulations for tropical climate exposure. State workplace safety standards incorporate OSHA solvent-exposure protocols without supplementary mandates. The Miami-Orlando-Tampa triangle supports rapid technician certification through streamlined dry application training programs.
Illinois
Illinois manufacturing clusters supply calendered vinyl substrates to national distribution networks. EPA Region 5 enforcement of Clean Air Act provisions shapes adhesive procurement for Midwest converter operations. The Chicago metropolitan area functions as a logistics hub consolidating Great Lakes region installer supply chains.
Ohio
Ohio-based polymer production facilities anchor domestic cast vinyl capacity for premium automotive applications. State environmental compliance programs mirror federal frameworks with additional reporting requirements for large emitters. The Akron-Cleveland corridor maintains specialized extrusion equipment serving paint protection film manufacturers.
US Automotive Wrap Films Market Key Industry Players
The competitive structure tilts toward materials science specialists with integrated adhesive formulation capabilities. Market concentration remains moderate, with tier-one suppliers commanding premium positioning through proprietary polymer platforms while regional converters compete on fulfillment speed. Two strategic archetypes dominate: diversified industrial conglomerates leveraging cross-sector R&D spillovers, and focused film specialists optimizing regional logistics. Capacity expansion and regulatory compliance upgrades constitute the primary competitive moves as VOC constraints tighten.
Among diversified materials conglomerates, Avery Dennison Corporation and 3M occupy positions exemplifying premium-tier competition through heritage pressure-sensitive adhesive expertise. ORAFOL Americas Inc. represents the regional specialist archetype, anchoring domestic manufacturing presence for rapid fulfillment. These three entities illustrate the competitive spectrum from global scale to regional responsiveness.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M |
| Arlon Graphics, LLC |
| ORAFOL Americas Inc. |
| Hexis S.A.S. |
| KPMF |
| Vvivid Vinyl |
| Fedrigoni S.P.A. |
| JMR Graphics |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up installer networks in Texas and Florida are consolidating regional service capacity, compressing distributor margins while enabling volume-based procurement leverage that reshapes upstream film pricing discipline.
Pricing Analysis
Throughput-based pricing anchors fleet procurement contracts, where cost-per-vehicle-wrapped supersedes roll-unit economics. Three-tier pricing structure across premium cast vinyl, standard calendered grades, and economy PVC separates warranty-backed performance tiers. Cost compression in standard grades is intensifying because petrochemical input volatility outpaces contract renegotiation cycles. Fleet procurement departments exhibit lowest price sensitivity due to national branding standardization requirements, while independent aftermarket installers face acute margin pressure from labor certification costs.
Supply Chain Analysis
Domestic-content preferences embedded in municipal fleet procurement guidelines are redirecting sourcing toward Ohio and Illinois manufacturing clusters. Raw material flows draw from Gulf Coast petrochemical complexes for vinyl resin, Great Lakes adhesive precursor facilities, and domestic release liner converters. Single-source vulnerability concentrates in specialized cast vinyl polymerization equipment held by limited domestic operators. Distribution runs through regional converter-distributor networks with manufacturer-direct platforms gaining share in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in US automotive wrap films is becoming a vertical-integration race, with adhesive formulation capability serving as the critical upstream lever separating premium suppliers from margin-challenged converters.
For Market Incumbents: To counter direct-to-installer platform disintermediation, anchor distributor relationships through exclusive color library licensing and captive supply of CARB-compliant water-based adhesives. Deepen backward integration into release liner production to insulate margins from specialty paper supply constraints. For New Entrants and Emerging Players: Specialized paint protection film applicators represent the most penetrable channel partner type for polyurethane substrate specialists seeking dealer network access. Target luxury vehicle service centers in Orange County and Dallas-Fort Worth where self-healing topcoat adoption outpaces certified technician supply. Pursue white-label partnerships with regional wrap film distributors lacking in-house formulation capabilities. For Investors and Strategic Acquirers: SCAQMD Rule 1168 enforcement acceleration is the leading indicator that water-based adhesive specialists will command acquisition premiums over solvent-dependent competitors. Position for five-to-ten-year holding periods where regulatory compliance moats widen. Monitor EPA Clean Air Act enforcement patterns as the signal for nationwide formulation upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Formulation Upgrade | CARB and SCAQMD compliance enables premium positioning in California fleet procurement. |
| Direct-to-Installer Platform Launch | Digital procurement channels bypass distributor markups in high-volume Southwest corridors. |
| Paint Protection Film Capacity Expansion | Polyurethane extrusion lines capture luxury dealer channel growth in Texas and Florida. |
| Certified Installer Network Development | Dry application training programs expand addressable technician pools in secondary markets. |
| Regional Manufacturing Footprint Addition | West Coast production sites reduce fulfillment bottlenecks for California installer networks. |
Research Approach
Multi-period observation of fleet procurement contract structures, installer certification timelines, and adhesive formulation patent filings anchored the trend analysis, supplemented by interviews with film manufacturing executives, regional distributor operations managers, fleet procurement directors, and certified installation technicians. Secondary validation drew from EPA enforcement records, CARB regulatory dockets, SEC filings of publicly traded materials conglomerates, and customs data on vinyl resin imports. Bottom-up volume estimates from installer network surveys triangulated against top-down film production capacity assessments.
Input-output matrices mapped substrate chemistry requirements to end-use application specifications across the projection horizon. Segmentation dimensions encompassed product type, customer category, installation technique, and surface finish tier, with regional regulatory cluster serving as an additional industry-specific modeling variable. CAGRs were derived from installed base growth rates and replacement cycle analysis, incorporating fleet vehicle registration data and luxury automotive sales patterns as demand-side forecast inputs.
Caveats apply where EPA enforcement intensity, petrochemical price spikes, or NHTSA visibility standard revisions could materially shift the outlook for adhesive-dependent product segments. Forecasts reflect documented assumptions regarding regulatory trajectory and fleet electrification impacts on vehicle surface geometries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market