
 Automotive Sunroof Market | 2026-2036
Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sunroof Market Analysis
Asset-light leasing structures for automotive tooling and module assembly are reshaping how sunroof suppliers secure OEM contracts. Webasto Group leverages its captive glass-forming capacity across European and Chinese plants to sustain margin control on panoramic assemblies. Inalfa Roof Systems Group B.V. anchors its competitive stance through dedicated engineering centers in the Netherlands and China that specialize in electric-slide mechanisms. Magna International Inc. competes by extending its seating and body systems footprint into integrated roof module programs.
An automotive sunroof is a transparent or opaque panel installed in a vehicle roof, typically constructed from tempered or laminated glass ranging from 3.8mm to 5.0mm in thickness, designed to admit light and air while maintaining structural integrity and rollover protection. Its primary commercial purpose is to enhance cabin ambiance and perceived vehicle premiumness, which drives configuration uptake in higher trim levels. Panoramic designs now dominate value pools as OEMs specify full-length multi-panel configurations that command material premiums over traditional spoiler-type units. Electric opening mechanisms are displacing manual alternatives across mid-size and above vehicle categories, while polycarbonate panels are gaining application in weight-sensitive performance variants where glass mass penalties conflict with efficiency targets.
The US NHTSA enforces FMVSS 216a roof crush resistance standards that directly constrain sunroof aperture dimensions and reinforcement strategies in vehicles sold domestically. Europe's ECE R43 and REACH frameworks govern glazing material composition and chemical safety, creating certification barriers for non-compliant suppliers. China's GB standards for motor vehicle safety, administered by SAMR, mandate specific performance criteria for movable roof panels in domestic production. Stakeholders must monitor how divergent crashworthiness and chemical compliance regimes across these three jurisdictions influence platform engineering decisions and supplier qualification timelines.
Market Dynamics
The automotive sunroof market is undergoing a fundamental reconfiguration as electric vehicle platforms demand larger glass apertures and lighter materials, forcing suppliers to retool forming processes and recalibrate structural reinforcement strategies.
Growth Catalysts
- Panoramic glass specifications:Chinese EV OEMs in Jiangsu and Zhejiang provinces are mandating full-length multi-panel designs that expand addressable content per vehicle.
- ECE R43 certification upgrades:Europe's tightening glazing safety standards are accelerating replacement cycles for non-compliant legacy tooling.
- Polycarbonate adoption:Weight-sensitive performance variants are specifying polymer panels to offset battery mass penalties without sacrificing cabin openness.
Market Restraints
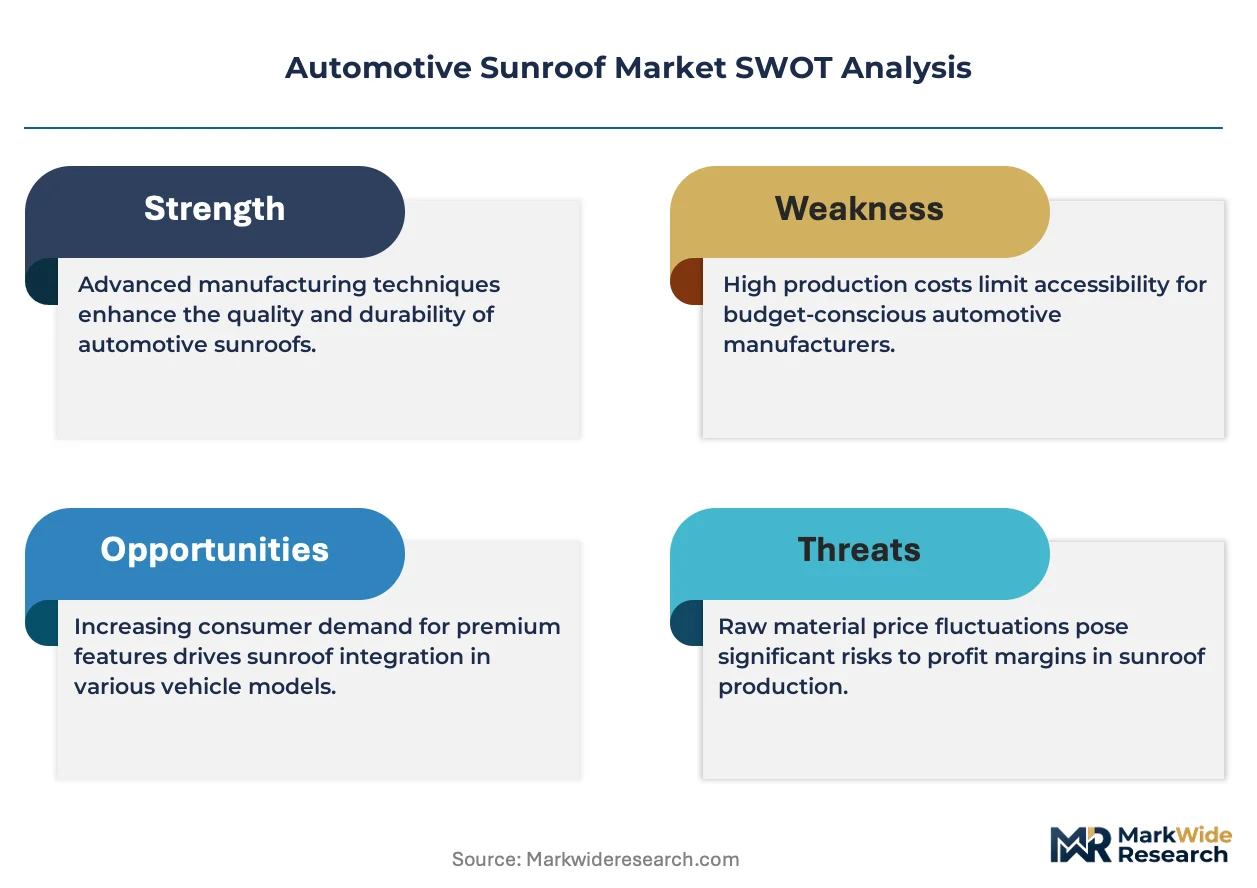
- High-purity soda-lime glass supply:Float glass capacity concentration in specific coastal Chinese provinces creates input cost volatility during energy rationing periods.
- FMVSS 216a structural requirements:NHTSA roof crush standards constrain aperture dimensions and add reinforcement mass that conflicts with efficiency targets.
- Manual mechanism obsolescence:Electric slide systems carry 3-4x the component cost of manual alternatives, compressing margins in entry trim configurations.
Strategic Opportunities
- India's premium SUV segment:Domestic OEMs are expanding sunroof fitment from top trims into mid-tier variants, opening volume tiers previously unserved.
- Solar-integrated glass:Photovoltaic cell embedding in panoramic panels creates energy-harvesting potential for auxiliary cabin systems.
- REACH compliance arbitrage:Suppliers with certified European chemical safety documentation can command premiums in markets adopting similar frameworks.
Industry Challenges
- Electric motor and sensor integration:The convergence of slide mechanisms with rain-sensing and pinch-detection electronics requires cross-functional engineering teams scarce in traditional glass-forming organizations.
- Multi-jurisdiction homologation:Simultaneous certification against GB standards, ECE R43, and FMVSS protocols extends program timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sunroof Market |
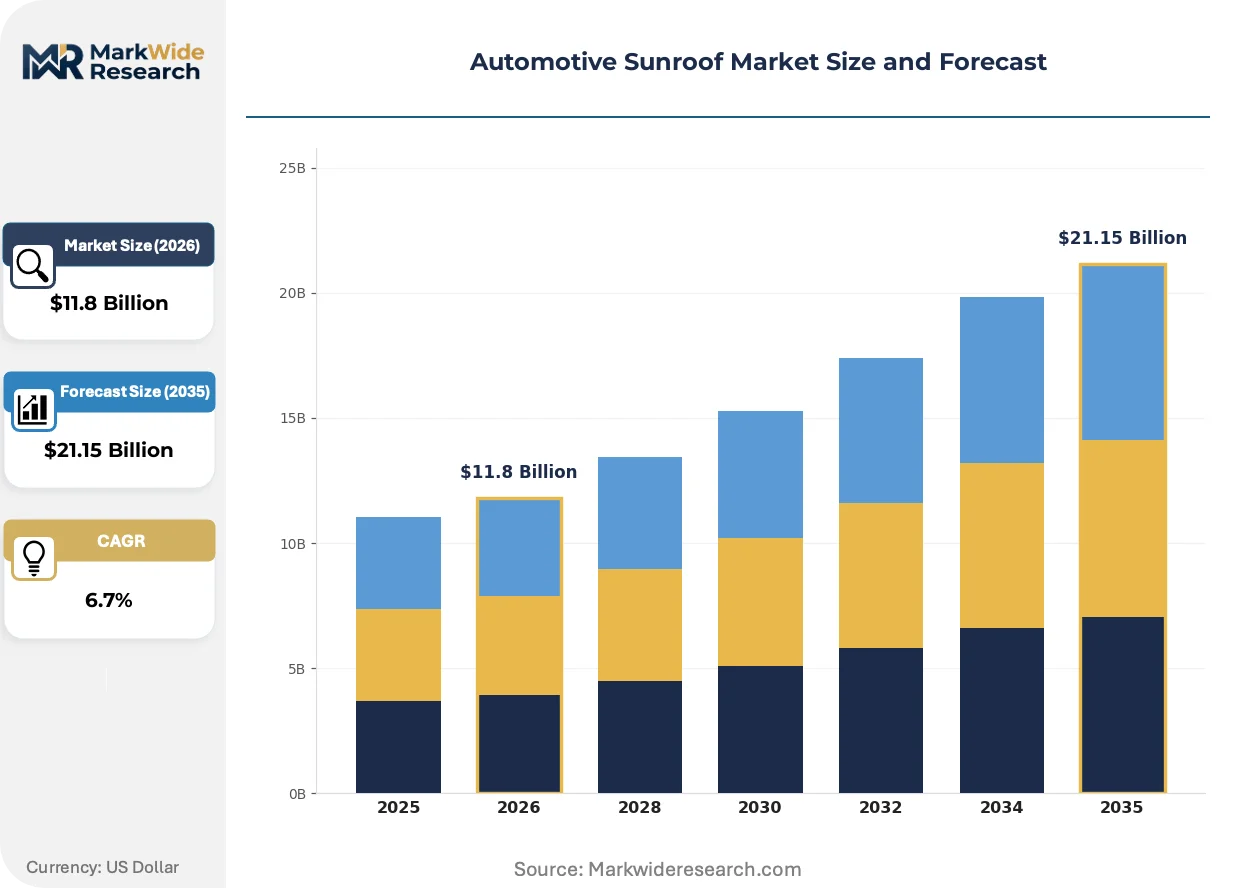
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic, Spoiler, Inbuilt, Removable Material: Glass, Acrylic, Polycarbonate, Aluminum Vehicle Type: SUVs, Sedans, Coupes, Hatchbacks Opening Mechanism: Manual, Electric, Semi-Automatic, Hydraulic |
| Companies Covered | Webasto Group, Inalfa Roof Systems Group B.V., Magna International Inc., Inteva Products LLC, Yachiyo Industry Co. Ltd, AISIN Corporation, CIE Automotive, BOS GmbH & Co. KG, Johnan America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sunroof Market Emerging Trajectories
Active material substitution and regulatory divergence are compressing traditional supplier hierarchies while creating entry points for specialized glass-forming and electronics integration capabilities.
Smart dimmable glass is migrating from fixed panoramic panels to operable sunroof configurations, enabling dynamic tint control without physical shades. Premium German and US OEMs are specifying electrochromic interlayers as standard equipment on flagship electric SUVs. This migration from passive to active glazing is compressing the traditional supply chain boundary between glass formers and cabin electronics integrators.
REACH Annex XVII restrictions on hazardous substance use in automotive glazing are forcing reformulation of interlayer adhesives and edge sealants. European suppliers with pre-certified material libraries are capturing specification share from competitors facing retrospective compliance costs. The regulation most directly affects panoramic multi-panel assemblies where adhesive surface area exceeds traditional spoiler-type units by 4-6x.
Fleet procurement of sunroof-equipped vehicles is fragmenting as ride-hailing operators specify fixed-glass panoramic units without opening mechanisms to reduce maintenance exposure. This specification divergence is creating parallel aftermarket channels for replacement motors and drainage systems in consumer-owned vehicles. The shift is most visible in China's eastern provinces where fleet penetration in premium EV segments exceeds 35 percent.
Automotive Sunroof Market Segmentation
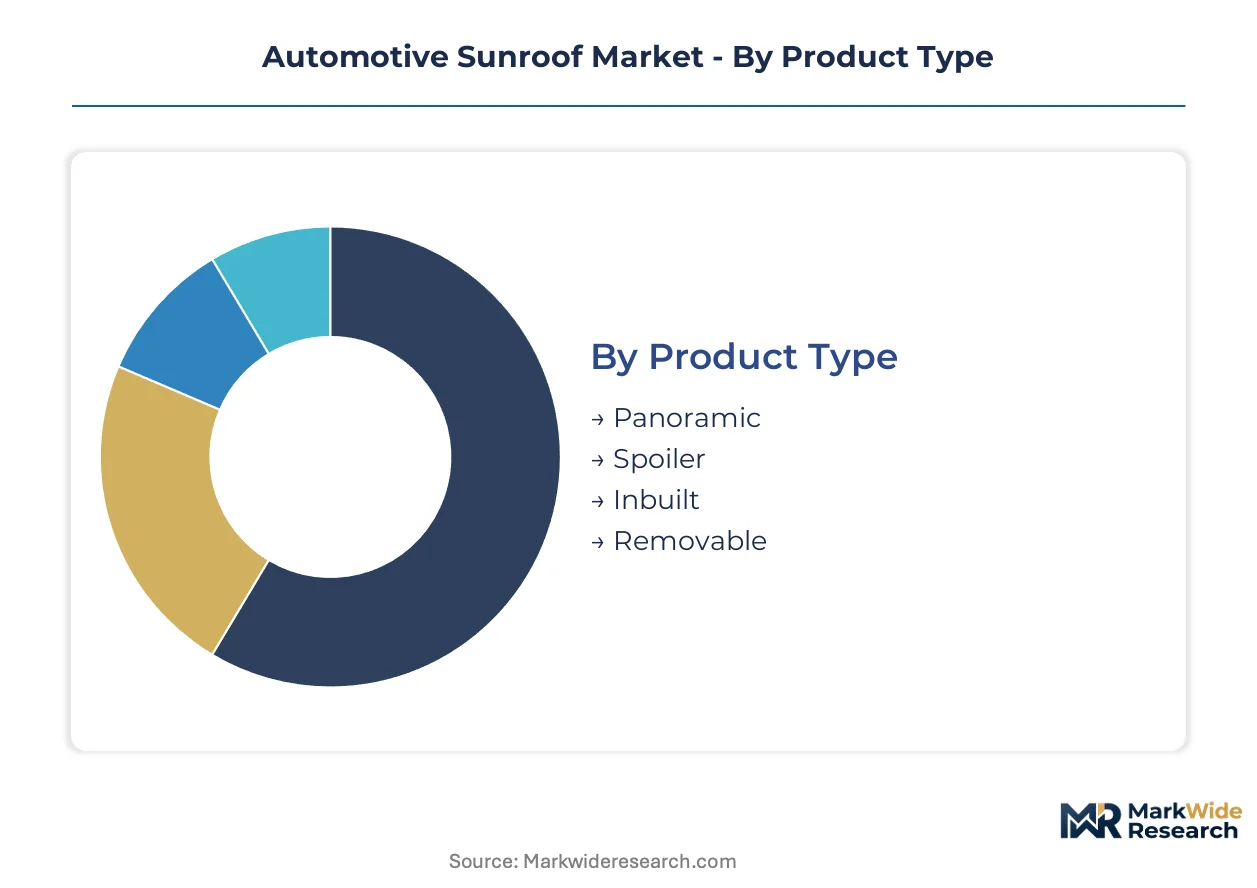
Sunroof procurement cycles vary dramatically across segment dimensions. Product type and material selection drive engineering lead times, while vehicle type and mechanism choices determine aftermarket turnover velocity and margin profiles.
Product Type:
Panoramic units carry 18-24 month design cycles versus 12-14 months for spoiler designs, creating divergent supplier capacity planning requirements.
- Panoramic:Multi-panel glass assemblies spanning front and rear seating zones, typically 3.8mm-5.0mm tempered or laminated construction. Chinese EV platforms in Jiangsu and Zhejiang provinces specify these for cabin spaciousness perception, though ECE R43 certification upgrades extend homologation timelines.
- Spoiler:Externally mounted units that pivot upward, historically dominant in European premium sedans. German OEMs retain this format for thermal efficiency in mild-hybrid architectures where glass mass conflicts with CO2 targets.
- Inbuilt:Flush-mounted designs integrated within roof sheet metal, common in Japanese compact sedans where aerodynamic drag coefficients drive specification.
- Removable:Detachable glass or metal panels, now confined to niche performance variants and aftermarket conversion specialists.
Spoiler configurations dominate installed base volumes. Panoramic designs are where expansion concentrates, climbing the fastest as EV platforms prioritize cabin ambiance differentiation.
Material:
Cost tier stratification separates commodity glass from engineered polymers, with aluminum occupying a narrow premium niche for structural reinforcement components.
- Glass:Soda-lime float glass with tempered or laminated processing, commanding 60-70% of material value pools. High-purity supply concentrates in coastal Chinese provinces, creating input volatility during energy rationing periods that affects tier-2 supplier margins.
- Polycarbonate:Lexan and Makrolon grades specified for weight-sensitive performance EVs where every kilogram offsets battery mass penalties. Bayer and SABIC resin supply chains anchor this segment's geographic concentration in Germany and China.
- Acrylic:PMMA alternatives for aftermarket replacement panels, constrained by UV degradation and scratch susceptibility that limits OEM adoption.
- Aluminum:Extruded frame and reinforcement elements, specified in rollover-critical applications where FMVSS 216a compliance demands additional structural mass.
Glass retains installed base dominance across all vehicle categories. Polycarbonate is where specification expansion concentrates, gaining share fastest in performance EV segments.
Vehicle Type:
Application-driven segmentation aligns sunroof aperture dimensions with platform architecture constraints, from full-length SUV installations to compact hatchback spoiler units.
- SUVs:Full-size and mid-size platforms accommodate the largest glass apertures, with US and Chinese OEMs mandating panoramic configurations on 70%+ of premium trims. Roof crush standards in both markets constrain opening dimensions despite consumer preference for maximum transparency.
- Sedans:Traditional three-box architectures favor inbuilt or spoiler mechanisms, particularly in Japanese and Korean domestic markets where aerodynamic efficiency priorities persist.
- Coupes:Low-roofline two-door vehicles specify compact spoiler units or fixed glass panels, with German luxury manufacturers leading specification rates.
- Hatchbacks:Compact European and Indian platforms increasingly delete sunroof options entirely, or specify smallest-aperture manual units to preserve headroom and structural rigidity.
Sedans retain the broadest installed base historically. SUVs are where volume expansion concentrates, with the steepest trajectory as premium segment penetration deepens across India and China.
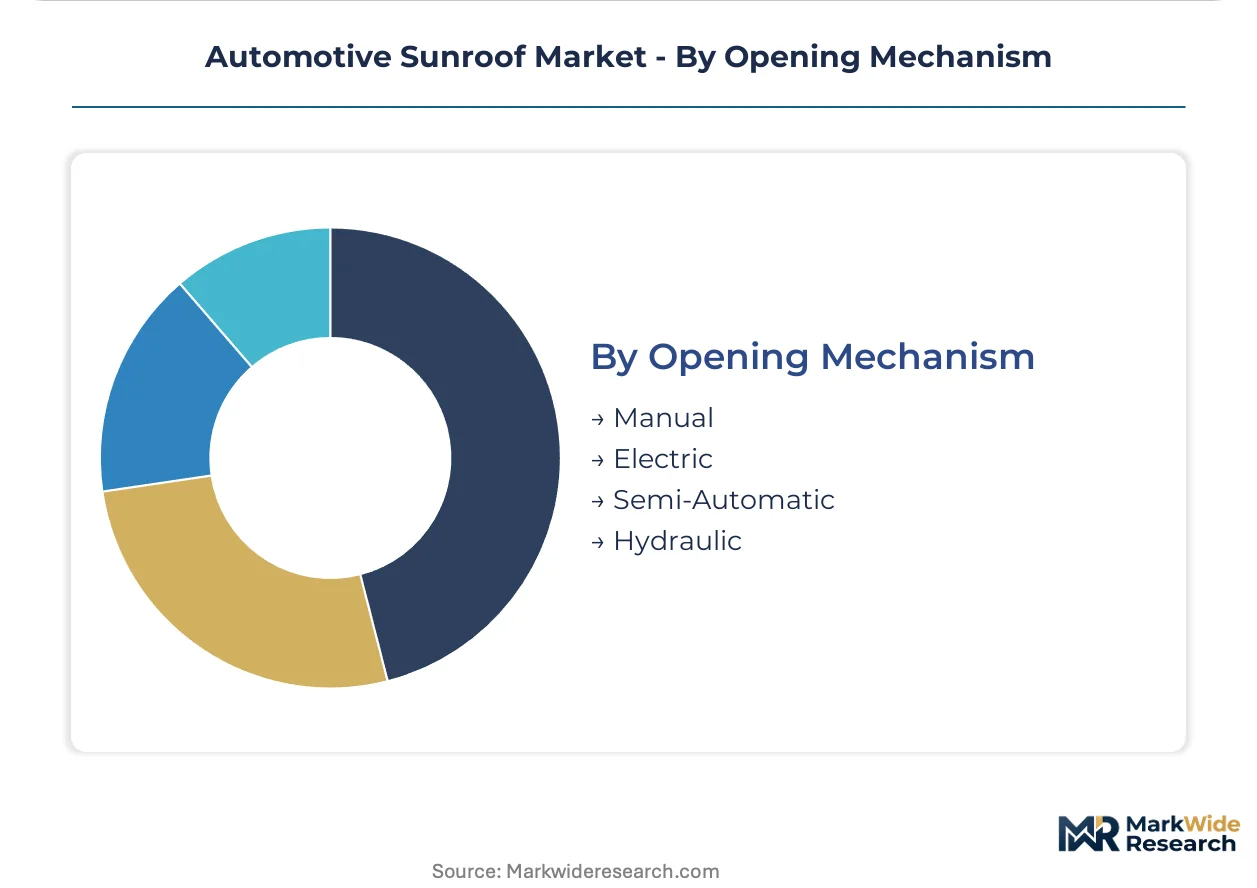
Opening Mechanism:
Customer type differentiation separates fleet procurement of fixed mechanisms from retail demand for full operability, with electric systems commanding 3-4x the component cost of manual alternatives.
- Electric:Motor-driven slide and tilt functions with rain-sensing and pinch-detection integration, now standard on mid-size and above vehicles. Chinese ride-hailing fleets increasingly delete this option to reduce maintenance exposure, creating specification divergence versus retail channels.
- Manual:Crank or lever-operated units, surviving only in entry-tier hatchbacks and emerging market variants where cost compression dominates procurement criteria.
- Semi-Automatic:Pop-up ventilation positions without full slide capability, common in European compact segments as a compromise between cost and perceived premiumness.
- Hydraulic:Heavy-duty actuation for oversized commercial or specialty vehicle applications, negligible in passenger car volumes.
Manual mechanisms dominate legacy installed base in emerging markets. Electric systems are where specification expansion concentrates, with the fastest adoption trajectory as sensor integration becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive sunroof systems tilt toward net-import dependence in Western markets, while Chinese coastal provinces generate surplus capacity serving both domestic OEMs and tier-1 suppliers abroad. Germany and the United States remain substantial importers of finished glass assemblies, whereas China's Jiangsu and Zhejiang manufacturing clusters anchor regional supply.
United States
Domestic OEMs in Detroit and the Southeast specify panoramic configurations on 70% of premium SUV trims, driving specification intensity. NHTSA's FMVSS 216a roof crush standards constrain aperture dimensions and mandate reinforcement mass that conflicts with EV efficiency targets. The Southeast manufacturing corridor, spanning Tennessee and South Carolina, hosts assembly plants where sunroof module integration occurs within body-in-white operations.
Germany
Premium manufacturers in Bavaria and Baden-Württemberg retain spoiler-type sunroofs for thermal efficiency in mild-hybrid architectures where glass mass penalties clash with CO2 compliance. ECE R43 certification upgrades for glazing materials are accelerating replacement cycles for non-compliant legacy tooling. The Stuttgart industrial region concentrates engineering centers specializing in electric-slide mechanisms for next-generation EV platforms.
China
Local OEMs in Jiangsu and Zhejiang provinces mandate full-length multi-panel panoramic designs for domestic electric vehicle platforms, expanding addressable content per vehicle. SAMR-administered GB standards for motor vehicle safety govern movable roof panel performance in domestic production. The Yangtze River Delta manufacturing belt generates surplus float glass capacity, though energy rationing periods in coastal provinces create input cost volatility.
Japan
Domestic compact sedan platforms favor inbuilt or spoiler mechanisms where aerodynamic drag coefficients drive specification decisions. METI industrial policy supports lightweight material research for automotive glazing applications. The Nagoya industrial corridor hosts suppliers integrating sunroof assemblies within just-in-time sequencing operations for Toyota and Honda production networks.
India
Domestic OEMs are expanding sunroof fitment from top trims into mid-tier SUV variants, opening volume tiers previously unserved in the premium segment. BIS safety standards for automotive glazing create compliance thresholds for imported components. The Pune-Nashik manufacturing cluster in Maharashtra is attracting module assembly investments as Maruti Suzuki and Mahindra deepen local content requirements.
Automotive Sunroof Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in glass-forming and mechanism supply. The vendor base stratifies across three functional layers: captive glass-forming operations, dedicated roof module assemblers, and diversified automotive suppliers extending adjacent body-systems expertise. Strategic moves concentrate on backward integration into high-purity glass supply and geographic co-location with high-volume OEM assembly plants.
Among diversified Tier-1 suppliers, Magna International Inc. occupies a position exemplifying platform integration breadth, while Webasto Group represents the specialized roof systems archetype with captive forming capacity. Inalfa Roof Systems Group B.V. anchors the dedicated engineering-center model with Netherlands and China-based technical facilities. These three entities illustrate how competitive positioning diverges between diversified automotive conglomerates and focused subsystem specialists.
| Leading Market Players |
|---|
| Webasto Group |
| Inalfa Roof Systems Group B.V. |
| Magna International Inc. |
| Inteva Products LLC |
| Yachiyo Industry Co. Ltd |
| AISIN Corporation |
| CIE Automotive |
| BOS GmbH & Co. KG |
| Johnan America Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Jiangsu and Zhejiang float glass corridors compresses spot pricing for high-purity soda-lime inputs while amplifying supplier desperation for long-term OEM offtake contracts. This utilization asymmetry grants multinational roof module assemblers outsized negotiating leverage on raw material pass-through clauses.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers. Price differentiation hinges on ECE R43 certification grade and volume scale commitments, with certified panoramic assemblies commanding material premiums. Cost compression in entry-tier electric mechanisms is intensifying because Chinese ride-hailing fleets delete opening functions to reduce maintenance exposure. Fleet procurement managers exhibit highest price sensitivity; premium German OEM platform engineers show lowest.
Supply Chain Analysis
Export-control restrictions on advanced glass-forming furnace technology limit capacity transfers to emerging manufacturing zones. Supply concentrates in China, Germany, and Japan for finished assemblies, with raw material dependencies on coastal Chinese float glass, Bayer and SABIC polycarbonate resins, and aluminum extrusions from European mills. Single-source vulnerability in Jiangsu province energy rationing creates input volatility. Distribution runs through Tier 1 module assemblers co-located with OEM body-in-white operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across EV architectures creates specialized supplier niches as OEMs diverge on panoramic aperture dimensions and smart glass integration requirements.
For Market Incumbents: Entrench position through captive glass-forming capacity additions in the Yangtze River Delta and pre-certification of interlayer adhesives against REACH Annex XVII upgrades. Polycarbonate substitution threats from weight-sensitive performance variants demand R&D investment in hybrid glass-polymer laminates to defend specification share.
For New Entrants and Emerging Players: India's Maharashtra and Tamil Nadu manufacturing corridors offer underpenetrated mid-tier SUV volume tiers where domestic OEMs expand sunroof fitment. Target fixed-glass panoramic units for fleet operators in China's eastern provinces; this segment tolerates simpler mechanism integration and shorter engineering qualification cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because supplier count exceeds sustainable economics as electric-slide mechanism complexity rises. Watch for inflection when ECE R43 certification upgrades force retrospective tooling replacement among European Tier 2 glass formers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Supply | Webasto's captive Jiangsu furnace capacity insulates margin control during energy rationing periods. |
| Electric-Slide Mechanism Engineering Center | Inalfa's Netherlands and China facilities specialize in rain-sensing and pinch-detection integration. |
| REACH-Compliant Adhesive Pre-Certification | European suppliers capture specification share from competitors facing retrospective interlayer reformulation costs. |
| Fleet-Focused Fixed-Glass Product Line | Module assemblers reduce maintenance exposure for Chinese ride-hailing operators deleting opening functions. |
| Multi-Jurisdiction Homologation Investment | Simultaneous GB, ECE R43, and FMVSS certification capability compresses OEM program timelines. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, automotive glazing technical directors, and aftermarket distribution heads provided ongoing calibration across the study period. Primary interview findings triangulated against vehicle production databases, IHS Markit registration data, customs and trade flow records, and regulatory filing repositories. Bottom-up volume builds from segment-level content-per-vehicle assumptions reconciled with top-down market value estimates.
Scenario bracketing anchored low-case assumptions on manual mechanism retention in emerging market entry tiers and high-case on polycarbonate penetration in performance EV segments. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-validation against OEM platform launch timelines and supplier capacity announcements.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified automotive conglomerates would shift outcomes. Material shifts in ECE R43 certification enforcement timelines or NHTSA FMVSS 216a structural requirement revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market