
 Car Door Latch Market | 2026-2036
Car Door Latch Market Size, Share, and Industry Trends Forecast 2026-2036
Car Door Latch Market Analysis
A shift from single-source to multi-source procurement is realigning how tier-one suppliers contract latch manufacturing across vehicle programs. Magna International leverages its vertical manufacturing footprint to retain OEM direct relationships. Kiekert AG anchors European premium programs through specialized electronic latch development. Strattec Security Corporation competes in North American truck and SUV platforms with mechanical-electronic hybrid systems.
A car door latch is a mechanical or electromechanical fastening device, typically fabricated from stamped steel or zinc die-cast housings with polymer overmolded components, designed to secure vehicle doors against inertial and intrusion forces while enabling controlled release. Its primary purpose spans occupant retention during collision events, theft deterrence through integrated locking, and seamless interface with central locking and keyless entry architectures. Interior latch and central locking system segments command the largest volume pools due to universal fitment across all vehicle classes, while child safety latch configurations carry premium pricing in family-oriented vehicle segments. Electric vehicle latch demand is outpacing conventional architectures as OEMs specify lighter aluminum and reinforced plastic variants to offset battery mass.
NHTSA Federal Motor Vehicle Safety Standards and the EU General Safety Regulation shape latch strength, durability cycle, and emergency egress requirements across respective markets. China's GB standards and MIIT homologation protocols enforce additional electromagnetic compatibility and cybersecurity criteria for electronic latches deployed in connected vehicles. Stakeholders must monitor divergence between regional electronic latch certification regimes when designing common global platforms.
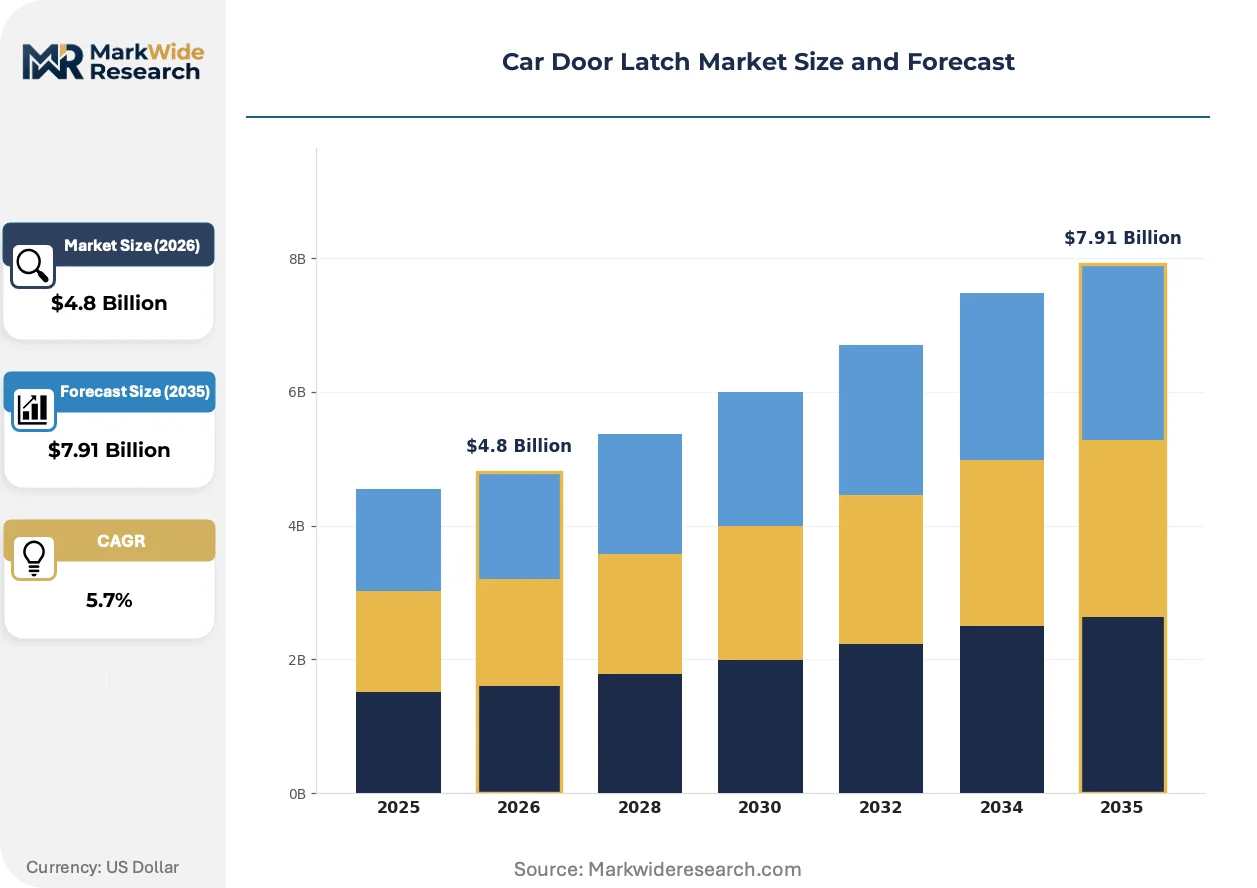
Market Dynamics
The car door latch market is experiencing structural pressure from the transition to electronic latching architectures, as electric vehicle platforms demand lighter, sensor-integrated systems that replace mechanical linkages with software-controlled actuation.
Growth Catalysts
- NHTSA Ejection-Mitigation Standards:US federal mandates for side-impact protection are compelling OEMs to redesign latches with redundant locking mechanisms and higher-strength materials, expanding specification volumes for advanced systems.
- Electronic Keyless Entry Convergence:Smartphone-based digital keys and UWB proximity detection are automating demand for motorized release latches with integrated antenna modules across premium and mass-market vehicle segments.
- China EV Procurement Localization:Domestic electric vehicle manufacturers are specifying smart latches with integrated sensors from local suppliers, creating concentrated demand pools in the world's largest automotive market.
Market Restraints
- Aluminum and Rare Earth Input Volatility:Electronic latch motors depend on neodymium magnet supply chains concentrated in Chinese processing facilities, exposing cost structures to export restriction risks.
- Homologation Fragmentation:Divergent electromagnetic compatibility certification requirements between NHTSA, EU General Safety Regulation, and China's GB standards force platform-specific engineering rather than global module commonality.
- Mechanical Latch Substitution:Simplified entry systems on commercial fleet vehicles retain pull-handle mechanical releases, capping electronic latch penetration in price-sensitive commercial segments.
Strategic Opportunities
- Software-Defined Vehicle Integration:Over-the-air update capability is enabling latch firmware monetization and predictive maintenance services, creating recurring revenue streams for tier-one suppliers.
- India PLI Scheme Automotive Incentives:Production-linked incentive programs for advanced automotive components are attracting electronic latch manufacturing investment to serve domestic OEMs and export markets.
- Cybersecurity Certification Services:UN R155 vehicle cybersecurity regulations are generating demand for penetration testing and secure boot architecture consulting as a bundled latch offering.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:ISO 26262 ASIL-rated latch development requires specialized systems engineers, with competition intensifying from autonomous driving and battery management sectors.
- Legacy Platform Integration Complexity:Retrofitting electronic latches onto existing vehicle architectures with 12V electrical systems and mechanical door modules demands custom harness and control unit redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Door Latch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Interior Latch, Exterior Latch, Child Safety Latch, Central Locking System Material: Steel, Zinc Alloy, Plastic, Aluminum Vehicle Type: SUV, Sedan, Hatchback, Electric Vehicle End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops |
| Companies Covered | Kiekert AG, Strattec Security Corporation, Magna International, Valeo SA, Denso Corporation, Aisin Corporation, Huf Hülsbeck & Fürst GmbH & Co. KG, Inteva Products LLC, Brose Fahrzeugteile GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Door Latch Market Emerging Trajectories
Actuation technology is converging with vehicle electrification architectures, replacing cable-pull mechanisms with compact motor-driven release systems that communicate over CAN-FD and Ethernet backbones.
Smart latch systems with integrated capacitive sensing and pinch-detection algorithms are automating door control logic, reducing the need for separate body control module processing. European premium OEMs are specifying these for frameless door applications where precise seal compression timing is critical. The technology is compressing mechanical component counts while expanding software validation scope.
REACH substance restrictions on hexavalent chromium plating are forcing suppliers to migrate to zinc-nickel alloy coatings and organic topcoats for corrosion protection. The regulation is raising surface treatment costs but enabling qualification for EU market access. Asian suppliers serving European export programs are accelerating coating line conversions to maintain contract eligibility.
Fleet operators and mobility service providers are unbundling after-sales service contracts from hardware procurement, creating preference for latch systems with modular actuator replacement and remote diagnostic capability. Subscription-based predictive maintenance is displacing traditional warranty coverage in North American commercial vehicle segments. This shift is most visible in last-mile delivery van specifications where uptime guarantees dominate purchasing criteria.
Car Door Latch Market Segmentation
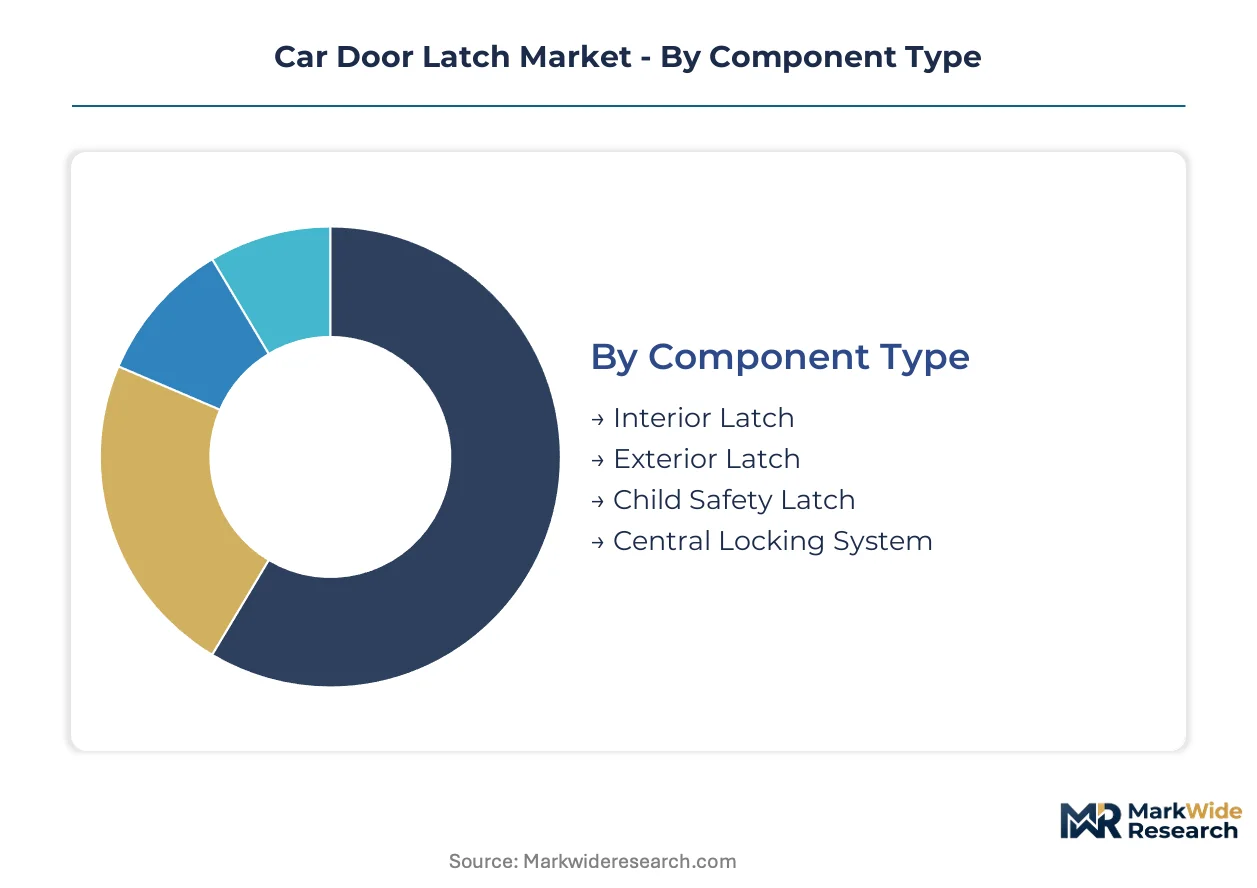
Latch specification varies sharply by integration depth—standalone mechanical units serve cost-driven segments while embedded electronic systems dominate electrified platforms. Material and vehicle electrification status now determine supplier margins more than traditional volume metrics.
Component Type:
Standalone latches operate as discrete mechanical units, while embedded variants integrate sensors and control logic within centralized body electronics architectures.
- Interior Latch:Fabricated from stamped steel housings with polymer overmolded handles, these mechanisms secure cabin entry points against inertial forces during collision events. Demand concentrates in mass-market sedans and hatchbacks across China and India where mechanical simplicity reduces warranty exposure.
- Central Locking System:Electromechanical assemblies integrating motorized actuators with CAN-FD communication protocols enable synchronized door control from remote key fobs or smartphone applications. Electric vehicle manufacturers in Germany and South Korea specify these for premium SUV platforms where keyless entry penetration approaches universality.
- Exterior Latch:Weather-sealed zinc die-cast housings with dual-stage locking mechanisms withstand cyclic corrosion testing under NHTSA durability protocols.
- Child Safety Latch:Redundant mechanical overrides with visual engagement indicators prevent rear door operation from interior handles.
Volume placements concentrate in Interior Latch; the faster expansion belongs to Central Locking System.
Material:
Cost tiers separate commodity metals from engineered alloys and composites, with electrification urgency accelerating lightweight material substitution.
- Steel:Cold-rolled high-strength grades stamped into load-bearing latch housings deliver baseline intrusion resistance at the lowest per-unit material cost. Full-size truck platforms in the United States and Brazil retain steel dominance where crashworthiness ratings prioritize structural integrity over mass reduction.
- Aluminum:Extruded and cast aluminum variants reduce component mass by 40-50 percent versus steel equivalents while maintaining yield strength requirements for side-impact compliance. Battery electric vehicle programs specify aluminum latches to offset battery pack mass, with procurement concentrating at Tesla, BYD, and Hyundai-Kia assembly plants.
- Zinc Alloy:Die-cast ZAMAK compositions enable complex geometries with tight dimensional tolerances for electronic latch motor integration.
- Plastic:Glass-fiber reinforced polyamide housings serve non-structural release mechanisms and cosmetic covers.
Steel commands current volume leadership; aluminum is climbing the fastest as electrification intensifies.
Vehicle Type:
Platform electrification status and door count configurations reshape latch specification intensity across passenger vehicle categories.
- Electric Vehicle:Dedicated battery electric platforms specify electronic latches with integrated capacitive sensing and UWB proximity detection, eliminating mechanical release cables entirely. Chinese domestic brands including NIO, XPeng, and Li Auto mandate locally sourced smart latches with predictive diagnostic capability.
- SUV:Higher door masses and frameless glass applications on premium European SUVs demand motorized latch systems with precise seal compression timing algorithms.
- Sedan:Conventional three-box architectures retain mechanical-electronic hybrid latches in mass-market segments.
- Hatchback:Compact five-door configurations prioritize cost-minimized mechanical latches for fleet and entry-level retail channels.
Current procurement volumes favor SUV platforms; electric vehicle segments show the steepest expansion trajectory.
End User:
Supply chain position determines specification authority—direct OEM relationships capture system integration value while aftermarket channels serve replacement demand.
- OEMs:Vehicle manufacturers with in-house body electronics engineering teams specify latch systems as part of centralized locking architectures, negotiating multi-year supply agreements with tier-one integrators. Volkswagen Group, Toyota, and Stellantis consolidate global latch procurement through platform standardization programs.
- Vehicle Assemblers:Contract manufacturers and joint venture operations execute build-to-print latch installation without design authority, serving regional market requirements.
- Aftermarket Providers:Independent distributors stock mechanical replacement latches for collision repair and theft damage restoration.
- Repair Shops:Service bay operations source individual latch components through wholesale parts networks.
OEM direct procurement concentrates specification value; aftermarket channels deliver replacement volume without design influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet processing facilities in China anchor the electronic latch motor supply chain, concentrating rare earth dependencies in a single geography while OEMs diversify final assembly across three continents.
United States
NHTSA ejection-mitigation standards drive specification of redundant locking mechanisms and higher-strength steel variants for side-impact compliance. Federal Motor Vehicle Safety Standard 206 mandates durability cycle testing that exceeds prior thresholds. Detroit-Windsor automotive corridor suppliers retool stamping lines to accommodate aluminum hybrid designs for electric truck platforms.
Germany
European premium SUV manufacturers specify motorized latch systems with precise seal compression timing for frameless door applications. EU General Safety Regulation enforces electromagnetic compatibility certification that diverges from US protocols. Stuttgart and Munich engineering clusters concentrate electronic latch firmware development for software-defined vehicle architectures.
China
Domestic EV brands NIO, XPeng, and Li Auto mandate locally sourced smart latches with integrated sensors and predictive diagnostic capability. MIIT homologation protocols enforce cybersecurity and electromagnetic compatibility criteria beyond baseline mechanical standards. Yangtze River Delta manufacturing hubs concentrate capacity expansion for aluminum and reinforced plastic latch variants.
Japan
Keiretsu supply relationships prioritize long-term supply agreements for electromechanical assemblies with CAN-FD integration. METI industrial policy supports lightweight material substitution in battery electric platforms. Toyota City and Nagoya industrial clusters maintain mechanical-electronic hybrid production for mass-market sedan and hatchback exports.
India
Production-linked incentive schemes for advanced automotive components attract electronic latch manufacturing investment to serve domestic OEMs and export markets. BIS certification requirements align with UN R155 vehicle cybersecurity regulations for connected vehicle deployment. Tamil Nadu and Gujarat automotive corridors host contract manufacturers executing build-to-print installations for regional vehicle programs.
Car Door Latch Market Vendor Landscape
Strategic partnerships dominate the current landscape as tier-one suppliers align with semiconductor and sensor specialists to deliver integrated electronic latch systems. The vendor base organizes around three archetypes: diversified global integrators with body electronics portfolios, specialized latch engineering houses with premium OEM relationships, and regional fabricators serving cost-sensitive vehicle programs. Consolidation pressure intensifies as software-defined vehicle architectures demand over-the-air update capabilities and predictive maintenance services.
Within the diversified integrator tier, Magna International and Valeo SA exemplify global-scale suppliers leveraging vertical manufacturing footprints to retain direct OEM relationships. Kiekert AG occupies a specialized position among European engineering-focused houses, while Strattec Security Corporation anchors North American mechanical-electronic hybrid supply for truck and SUV platforms.
| Leading Market Players |
|---|
| Kiekert AG |
| Strattec Security Corporation |
| Magna International |
| Valeo SA |
| Denso Corporation |
| Aisin Corporation |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| Inteva Products LLC |
| Brose Fahrzeugteile GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of electronic latch motors at Magna International and Valeo SA anchors supply positions while reinforcing pricing power against commodity mechanical suppliers. This integration pattern insulates tier-one integrators from rare earth magnet cost volatility while forcing smaller fabricators toward contract manufacturing arrangements with compressed margins.
Pricing Analysis
Warranty and predictive maintenance bundling now separates premium electronic latch offerings from unbundled mechanical replacement units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from OEM platform programs. Cost compression in economy mechanical tiers is intensifying because Chinese domestic suppliers are absorbing coating conversion expenses for EU market access. Fleet operators and mobility providers show highest price sensitivity through subscription-based service contracts, while European premium OEMs demonstrate lowest sensitivity for frameless door motorized systems with embedded firmware.
Supply Chain Analysis
Container freight rate volatility from Yangtze River Delta ports to European assembly plants is reshourcing decisions for aluminum die-cast housings. Neodymium magnet processing concentrates in China, with secondary capacity in Japan and Germany serving automotive qualification requirements. Electronic latch motors draw from rare earth supply chains concentrated in Chinese processing facilities, creating single-source vulnerability for Western tier-one suppliers. Distribution runs through just-in-sequence delivery contracts directly to OEM assembly lines, bypassing traditional warehousing for electronic architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic latch motor capacity expansion latches onto rare earth magnet supply constraints, propping pricing power for qualified suppliers through the forecast window. OEM platform standardization programs are concentrating procurement volumes with fewer tier-one integrators.
For Market Incumbents: Extend firmware development capabilities to capture predictive maintenance revenue streams from fleet operators and mobility service providers. Deepen backward integration into rare earth magnet sourcing through long-term offtake agreements with Chinese processors to defend against supply disruption. Secure ISO 26262 ASIL certification for electronic latch systems to maintain platform access as functional safety requirements tighten. For New Entrants and Emerging Players: The mid-market price gap between premium European electronic latches and economy Chinese mechanical units offers entry space for hybrid electromechanical systems. Target Indian domestic OEMs served by PLI scheme incentives, where electronic latch penetration remains below battery electric vehicle adoption curves. Pursue cybersecurity certification bundling under UN R155 regulations as a differentiated service wrapper for hardware procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified automotive electronics integrators seeking latch-specific engineering talent and OEM platform relationships. Five-to-ten year viability favors suppliers with software-defined vehicle update capabilities and predictive diagnostic IP portfolios. Watch for NHTSA rulemaking on autonomous vehicle door egress requirements as an inflection signal for electronic latch specification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors anchor motor cost structures against export restriction risks. |
| Software-Defined Vehicle Integration | Over-the-air firmware update capability enables recurring revenue from predictive maintenance services. |
| Functional Safety Certification Investment | ISO 26262 ASIL-rated development qualifies suppliers for autonomous vehicle platform access. |
| Geographic Manufacturing Footprint Expansion | India PLI scheme incentives attract capacity to serve domestic OEMs and Middle East export markets. |
| Cybersecurity Service Bundling | UN R155 penetration testing and secure boot architecture consulting differentiates electronic latch offerings. |
Methodological Framework
Independent corroboration across tier-one supplier procurement directors, OEM platform engineering leads, and aftermarket distributor operations underwrites the qualitative findings in this study. Primary interviews with body electronics engineering teams at Stellantis, Volkswagen Group, and Toyota were cross-referenced against secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS filings, and EU General Safety Regulation documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive component trade flows.
Comparable-period anchoring to historical vehicle production volumes and latch content-per-vehicle trends established the forecast baseline across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, material substitution intensity, electronic versus mechanical actuation type, and regional OEM procurement cluster. CAGRs were derived from regression analysis against battery electric vehicle penetration curves and regulatory compliance timelines. Key inputs included NHTSA side-impact standard implementation schedules and China MIIT homologation protocol adoption rates.
Inputs from tier-one supplier disclosures and OEM platform engineering documentation were available through the study window; gaps in proprietary firmware development cost structures introduce uncertainty bands around electronic latch margin projections. Forecasts reflect documented assumptions regarding rare earth magnet supply continuity and regulatory harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Cowl Panel Market