
 Europe Automotive Seat Market | 2026-2036
Europe Automotive Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Seat Market Foresight
A shift from single-source to multi-source seat sourcing is rebalancing procurement dynamics across European vehicle programs. Adient PLC leverages its pan-European manufacturing footprint to sustain just-in-sequence delivery contracts with German OEMs. Lear Corporation anchors its position through in-house foam production and metal forming capabilities. Forvia SE competes on integrated cockpit-electronics convergence, combining seating with thermal and lighting systems.
Europe automotive seats are occupant support structures engineered with steel or magnesium frames, polyurethane foam cushioning, and trim materials meeting ECE R14 and R16 safety standards for head restraint and seatbelt anchorage integrity. Their primary commercial purpose is to integrate crash protection, ergonomic positioning, and climate comfort within vehicle cabin architectures. Bucket seats dominate premium and performance vehicle lines where lateral support and weight reduction command margin premiums. Heated and ventilated technology segments are expanding fastest as OEMs bundle thermal comfort into electric vehicle packages to offset range anxiety with occupant satisfaction. Memory foam material adoption is accelerating in luxury configurations, though leather remains the margin pool anchor due to consumer willingness to pay for full-grain and Nappa finishes.
EMA chemical safety assessments, REACH substance restrictions, and the EU Green Deal carbon-border adjustments are tightening foam formulation and leather tanning compliance costs for seat suppliers. ECE R129 child restraint protocols and CE marking requirements under the EU General Product Safety Directive shape market access criteria for aftermarket and OEM-installed seating. Stakeholders must monitor evolving ECHA SVHC candidate list expansions and battery-electric platform weight targets that trade foam density against thermal management system integration.
Market Dynamics
The EU Green Deal carbon-border adjustments and ECHA SVHC candidate list expansions are forcing seat suppliers to reformulate polyurethane foams and leather tanning processes, compressing margins while accelerating material substitution timelines.
Growth Catalysts
- Electric vehicle platform proliferation:Premium EV architectures bundle ventilated and massaging seat technologies to differentiate cabin experience and offset range anxiety with occupant comfort.
- REACH compliance innovation:Chemical substitution mandates under ECHA restrictions are pushing foam suppliers toward bio-based polyols and waterborne adhesives that meet emission standards.
- German OEM just-in-sequence contracts:Pan-European manufacturing clusters anchored in Stuttgart, Wolfsburg, and Munich sustain high-volume seat assembly programs with synchronized logistics.
Market Restraints
- Magnesium frame cost volatility:Raw material price swings for lightweight alloys constrain margin stability in performance seat configurations targeting weight reduction targets.
- Leather tanning input concentration:Chromium-free processing chemical suppliers cluster in Northern Italy, creating single-source vulnerability for premium trim operations.
- Foam density-thermal tradeoff:Battery-electric platform weight budgets force compression of cushioning specifications against integrated heating and cooling system mass.
Strategic Opportunities
- Italian luxury aftermarket:Nappa leather refurbishment and memory foam retrofit services remain underdeveloped in Modena and Maranello performance vehicle service networks.
- Cockpit-electronics convergence:Integration of seat thermal management with ambient lighting and HMI controls creates bundled system procurement pathways.
- French circular economy mandates:Extended producer responsibility frameworks under national environmental regulations incentivize foam recycling and trim material recovery programs.
Industry Challenges
- Polyurethane chemist talent scarcity:Formulation expertise for low-VOC foam systems remains concentrated among retiring specialists at legacy suppliers.
- ECE R129 certification timelines:Child restraint protocol testing backlog at notified bodies delays aftermarket seat program launches by six to nine months.
- Legacy platform integration friction:Thermal comfort electronics from EV-native architectures require substantial redesign to interface with internal combustion vehicle electrical systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Seat Market |
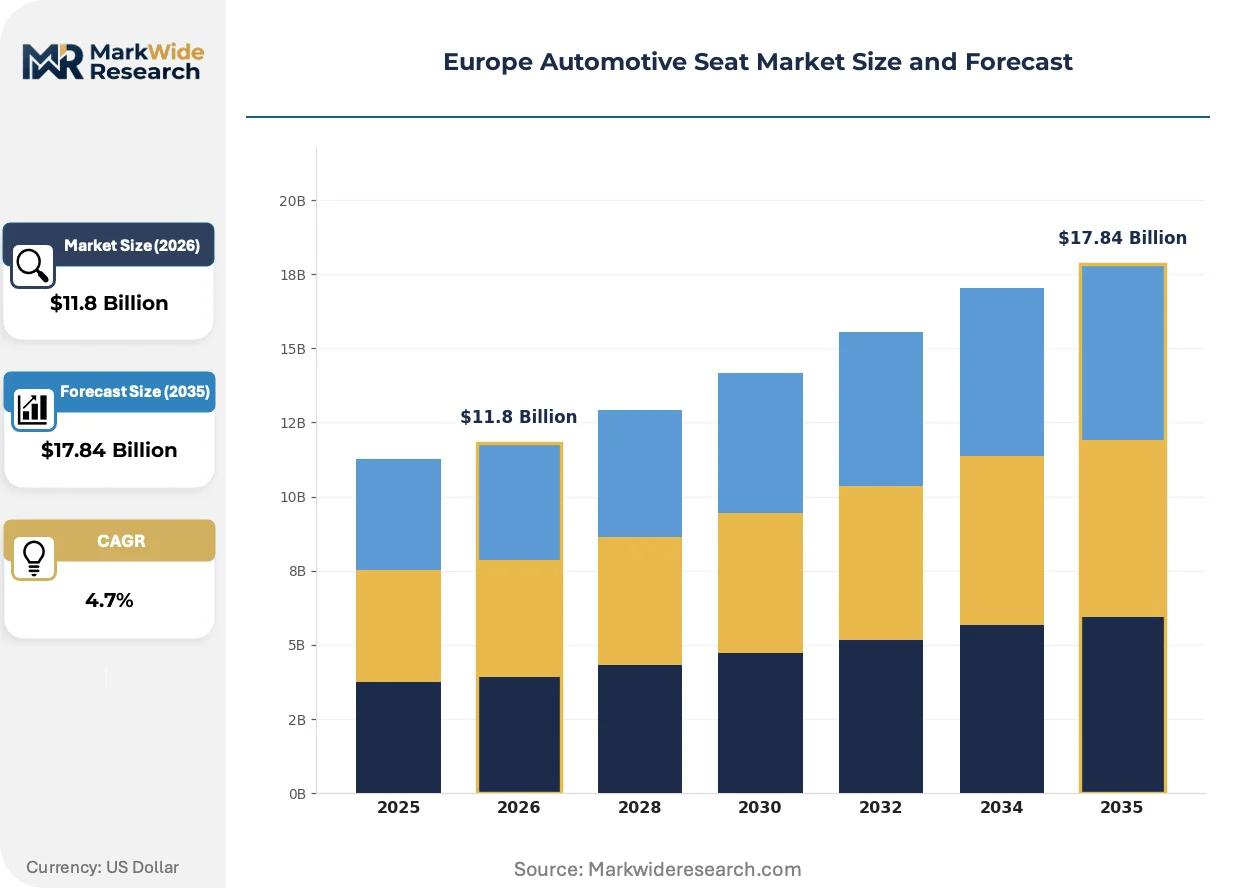
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Seat, Bench Seat, Recliner Seat, Racing Seat Material: Leather, Fabric, Vinyl, Memory Foam Technology: Heated Seat, Ventilated Seat, Adjustable Seat, Massaging Seat End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Adient PLC, Lear Corporation, Forvia SE, Groclin S.A, RECARO Automotive Italy S.r.l., Brose Fahrzeugteile GmbH & Co. KG, Sparco SpA, Britax, Magna International Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Seat Market Shifts & Advancements
Active materials and digital manufacturing processes are redrawing competitive boundaries between traditional seat assemblers and technology-integrated tier-1 suppliers.
3D-knitted textile surfaces are decentralizing trim material supply chains by enabling localized production of seamless seat covers with integrated heating elements. Premium EV manufacturers in Germany and Sweden are adopting these structures to reduce leather dependency while maintaining tactile quality. This technology is decentralizing finishing operations from tannery clusters to regional assembly plants, compressing logistics lead times.
The EU Green Deal carbon-border adjustment mechanism is tightening cost accountability for imported foam precursors and leather hides from non-EU suppliers. Seat manufacturers must now document embedded emissions across upstream chemical processes or face tariff penalties at European ports. Suppliers sourcing from tanning operations in Eastern Europe and North Africa are accelerating supply chain auditing and supplier transition programs.
Fleet procurement managers for European ride-hailing and corporate leasing operations are unbundling seat durability specifications from standard vehicle trim packages. These buyers now negotiate separate service contracts for high-wear seat component replacement, bypassing traditional dealer networks. France and the Netherlands show the strongest concentration of this behavior, where fleet operators represent above-average shares of new vehicle registrations.
Europe Automotive Seat Market Segmentation
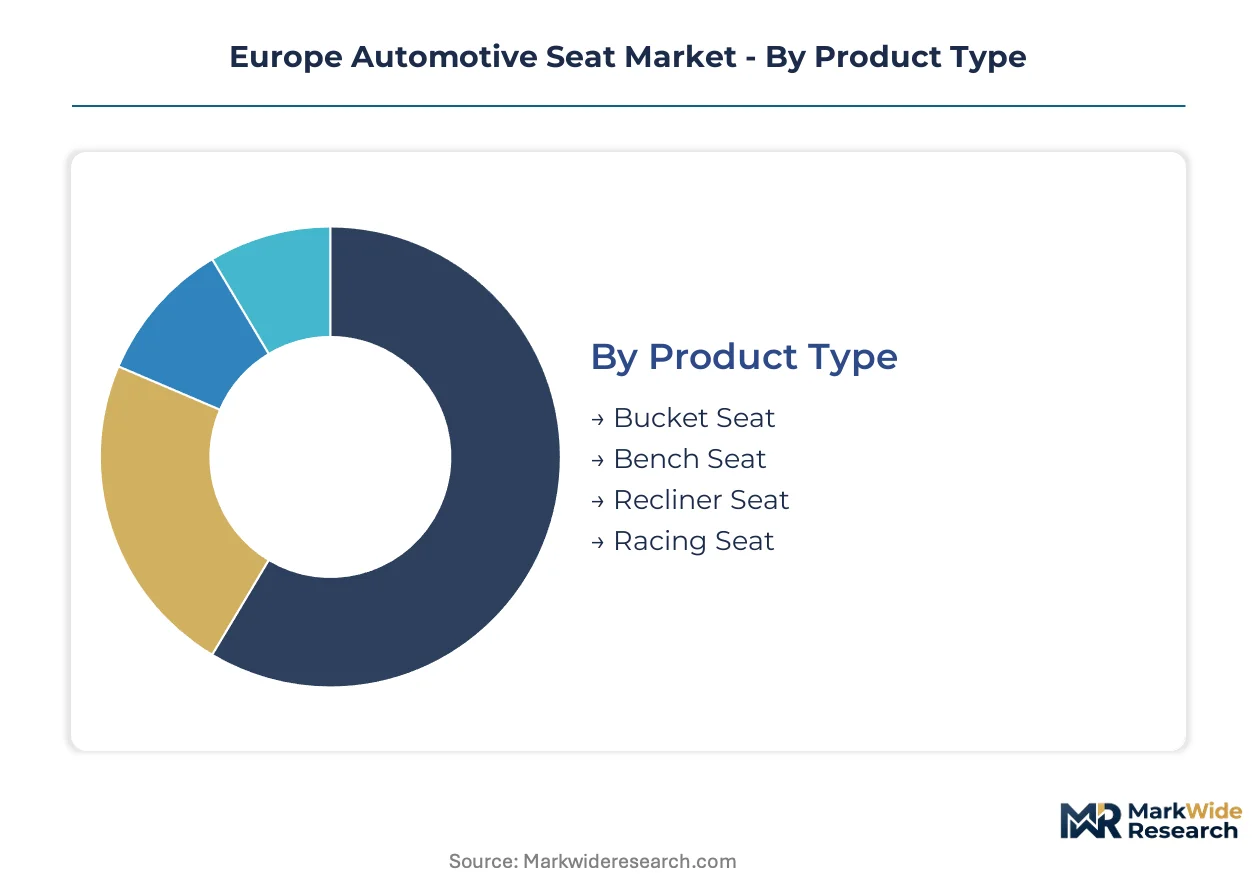
Seat segmentation in Europe tracks divergent certification burdens across safety-critical and comfort-driven configurations. ECE R14 and R16 standards apply universally, yet child restraint protocols and thermal system integration create tiered compliance costs that reshape supplier economics.
Product Type:
ECE R14 head restraint and R16 seatbelt anchorage standards govern all structural seat categories, with additional UN R129 certification mandatory for integrated child restraint positions in family vehicle configurations.
- Bucket Seat:Individual occupant shells with pronounced side bolsters and integrated head restraints dominate premium German and Italian performance vehicle lines. Stuttgart and Munich OEMs specify magnesium frame variants to meet battery-electric platform weight targets.
- Bench Seat:Continuous three-position structures with folding center sections anchor mass-market family vehicles produced at Wolfsburg and Paris-region assembly plants. ECE R129 child restraint anchor integration adds certification complexity not required for front-row-only configurations.
- Recliner Seat:Adjustable backrest mechanisms with independent thigh support serve long-wheelbase luxury sedans.
- Racing Seat:FIA-homologated shells with six-point harness anchorage meet motorsport safety standards beyond road-vehicle ECE requirements.
Leading the category by volume: Bench Seat. Growing fastest: Bucket Seat.
Material:
REACH substance restrictions and ECHA SVHC candidate list expansions impose formulation reformulation costs that concentrate differentially across natural and synthetic material streams.
- Leather:Full-grain and Nappa finishes from Northern Italian tanneries command margin premiums in luxury configurations, though chromium-free tanning chemical supply concentration creates single-source vulnerability. Carbon-border adjustment documentation requirements now apply to hide imports from non-EU suppliers.
- Memory Foam:Viscoelastic polyurethane formulations with open-cell structures adapt to occupant contours in long-distance driving configurations. German OEMs specify density-optimized variants that trade cushioning depth against integrated heating element mass.
- Fabric:Woven polyester and wool blends serve fleet vehicle procurement managers negotiating separate durability service contracts.
- Vinyl:PVC-based synthetic surfaces meet cost-constrained commercial vehicle specifications.
Highest margin concentration: Leather. Steepest expansion trajectory: Memory Foam.
Technology:
Thermal comfort system integration creates electrical load management challenges unique to battery-electric platforms, with CE marking under the EU General Product Safety Directive governing aftermarket retrofit installations.
- Ventilated Seat:Perforated trim surfaces with integrated blower modules draw cabin air through foam layers to manage occupant thermal comfort without increasing HVAC electrical draw. Swedish and German premium EV manufacturers bundle this technology to offset range anxiety with cabin experience differentiation.
- Massaging Seat:Pneumatic bladder arrays with programmable pressure sequences serve executive vehicle rear-seat configurations. Italian luxury marques specify multi-zone systems that integrate with ambient lighting controllers.
- Heated Seat:Resistive wire or positive temperature coefficient elements provide baseline thermal comfort across climate zones.
- Adjustable Seat:Electric motor-driven track, height, and recline mechanisms with memory positioning.
Widest OEM bundling: Heated Seat. Gaining share fastest: Ventilated Seat.
End User:
Procurement authority fragmentation across vehicle program lifecycle stages creates divergent specification authority and contract structures.
- OEMs:Volkswagen Group, Stellantis, and BMW hold direct sourcing authority for seat system design, with just-in-sequence delivery contracts awarded to pan-European manufacturing footprint suppliers. These buyers specify frame architecture, foam density, and trim material in integrated cockpit-electronics convergence programs.
- Aftermarket Providers:Independent distributors and specialist installers serve Nappa leather refurbishment and memory foam retrofit demand concentrated in Modena and Maranello performance vehicle service networks. ECE R129 certification testing backlog at notified bodies delays program launches.
- Tier-1 Suppliers:Adient, Lear, and Forvia intermediate seat assembly for OEM vehicle programs.
- Vehicle Assemblers:Contract manufacturers and niche vehicle builders procure complete seat modules.
Dominating specification authority: OEMs. Expanding most quickly: Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian tannery clusters in Solofra and Arzignano supply chromium-free processing chemicals that anchor premium leather trim sourcing for European OEMs. German magnesium foundries near Stuttgart and Munich cast lightweight seat frames for battery-electric platforms. French foam formulation expertise concentrated around Lyon supports REACH-compliant polyurethane supply chains.
Germany
Volkswagen Group and BMW procurement offices in Wolfsburg and Munich drive just-in-sequence seat assembly contracts. KBA type-approval requirements govern ECE R14 and R16 certification for structural components. Stuttgart manufacturing corridors host Adient and Lear production facilities synchronized to Mercedes-Benz and Porsche assembly lines.
Italy
Ferrari and Lamborghini specification authority in Modena and Sant'Agata Bolognese sustains demand for Nappa leather and carbon-fiber racing shells. ECHA SVHC restrictions on chromium compounds are accelerating tanning chemical substitution in Arzignano tannery networks. Maranello service specialists perform memory foam retrofit work on collector vehicles.
France
Stellantis seat sourcing decisions at Poissy and Sochaux manufacturing complexes shape tier-1 supplier allocation. Extended producer responsibility mandates under national circular economy regulations incentivize foam recycling infrastructure near Lyon chemical parks. Forvia SE integrates thermal management with ambient lighting controllers at its Paris-region electronics facilities.
United Kingdom
Jaguar Land Rover and Aston Martin engineering centers in Gaydon and Warwickshire specify performance seat architectures. CE marking under the EU General Product Safety Directive governs aftermarket retrofit installations. Midlands manufacturing clusters near Birmingham host metal forming operations for seat track mechanisms.
Spain
SEAT production at Martorell and Volkswagen Navarra assembly in Pamplona sustain high-volume bench seat programs. REACH substance restrictions apply to foam precursors imported from North African tanning operations. Barcelona-region logistics hubs coordinate pan-European distribution of trim materials.
Europe Automotive Seat Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers reposition manufacturing footprints to serve EV-native platform launches. The vendor base concentrates around three pan-European manufacturing specialists with synchronized logistics capabilities. Strategic archetypes include integrated cockpit-electronics convergers, in-house foam and metal formers, and just-in-sequence logistics specialists. M&A activity and geographic consolidation represent the dominant competitive moves as suppliers acquire regional trim specialists and relocate production to carbon-border-adjustment-compliant zones.
Among the integrated tier-1 assemblers, Adient PLC exemplifies the just-in-sequence logistics archetype through its manufacturing footprint positioning. Lear Corporation occupies a position representing in-house material production capabilities. Forvia SE anchors the cockpit-electronics convergence vector, integrating seating with adjacent cabin systems. Groclin S.A and RECARO Automotive Italy S.r.l. sit within specialized performance and luxury trim segments where certification depth creates differentiation.
| Leading Market Players |
|---|
| Adient PLC |
| Lear Corporation |
| Forvia SE |
| Groclin S.A |
| RECARO Automotive Italy S.r.l. |
| Brose Fahrzeugteile GmbH & Co. KG |
| Sparco SpA |
| Britax |
| Magna International Inc |
| Others |
Supply & Pricing Matrix
Magnesium alloy spot prices on the London Metal Exchange cascade through European seat manufacturing tiers, compressing margins on lightweight frame configurations while concentrating pricing power among German and Italian suppliers with captive foundry operations. REACH compliance costs for bio-based polyol formulations and carbon-border adjustment documentation for non-EU leather hides now stratify procurement economics across premium, fleet, and commercial vehicle programs.
Pricing Analysis
Warranty and durability service bundling separates fleet procurement contracts from standard OEM trim packages, with French and Dutch leasing operators negotiating standalone replacement schedules for high-wear components. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and foam density specifications, with Nappa leather finishes commanding substantial premiums over vinyl-based commercial configurations. Cost compression in memory foam formulations is intensifying because ECHA SVHC restrictions force rapid chemical substitution timelines. Fleet vehicle procurement managers exhibit highest price sensitivity, while Italian luxury marques demonstrate lowest sensitivity due to specification authority concentrated in Modena and Sant'Agata Bolognese engineering centers.
Supply Chain Analysis
French circular economy mandates and extended producer responsibility frameworks are reshaping sourcing patterns, requiring domestic-content compliance for foam recycling infrastructure near Lyon chemical parks. Supply concentration centers on Germany for magnesium frame casting, Italy for chromium-free tanning chemicals, and France for REACH-compliant polyurethane formulation. Raw material dependencies include polyurethane precursors from petrochemical complexes, full-grain hides from Northern Italian tanneries, and lightweight alloy ingots from Stuttgart-region foundries. Single-source vulnerability in Arzignano tanning chemical networks creates structural risk for premium trim operations. Distribution runs through just-in-sequence logistics corridors synchronized to Wolfsburg, Munich, and Stuttgart assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European automotive seat manufacturing is consolidating around suppliers with pan-European manufacturing footprints and in-house material production capabilities, as ECHA chemical restrictions and carbon-border adjustments force sub-scale foam and leather specialists into acquisition or exit.
For Market Incumbents: Anchor just-in-sequence delivery contracts through synchronized logistics investments in Stuttgart and Munich manufacturing corridors, while accelerating backward integration into bio-based polyol formulation to offset REACH compliance cost compression. Threat from cockpit-electronics convergers integrating thermal management with ambient lighting systems demands defensive R&D in seat-integrated HMI controllers. Priority lever: captive supply of chromium-free tanning chemicals through Northern Italian tannery network partnerships. For New Entrants and Emerging Players: EU Green Deal carbon-border adjustments in Europe open a window for regional foam recycling specialists to capture extended producer responsibility mandates in France and circular economy procurement preferences. White-space targets include Nappa leather refurbishment services in Modena and Maranello performance vehicle networks, plus memory foam retrofit programs for collector vehicles. Go-to-market angle: ECE R129 certification expertise to bypass testing backlog delays plaguing independent aftermarket distributors. For Investors and Strategic Acquirers: The window for entry favors mid-cap foam formulation specialists with REACH-compliant chemical expertise and regional manufacturing footprints in carbon-border-adjustment-compliant zones. Long-term viability hinges on five-to-ten year platform standardization cycles as battery-electric architectures consolidate seat thermal management with adjacent cabin systems. Acquisition target archetype: Italian luxury trim specialists with FIA homologation depth and carbon-fiber racing shell capabilities. Signal to watch: notified body certification timeline compression for child restraint protocols as aftermarket testing backlog clears.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates seat architectures across Volkswagen Group and Stellantis EV programs to reduce tooling duplication. |
| Backward Integration into Foam Formulation | Captures REACH compliance margins and secures bio-based polyol supply for Adient and Lear production networks. |
| Geographic Manufacturing Footprint Relocation | Positions assembly plants in carbon-border-adjustment-compliant zones to avoid tariff penalties on non-EU hide imports. |
| Cockpit-Electronics Convergence Investment | Integrates Forvia SE thermal management with ambient lighting controllers for bundled OEM procurement pathways. |
| Extended Producer Responsibility Compliance | Aligns French and Dutch operations with national circular economy mandates for foam recycling infrastructure. |
Research Methodology
Vehicle production databases, IHS Markit registration data, and ECHA substance restriction filings formed the secondary backbone, supplemented by customs records tracking polyurethane precursor and leather hide import flows. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled segment-level volume estimates with aggregate market sizing derived from European vehicle assembly forecasts.
Bottom-up modeling anchored projections across the analysis window to vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-specific growth trajectories weighted by OEM platform launch timelines and thermal comfort technology bundling rates. Industry-specific forecast inputs included battery-electric platform weight targets compressing foam density specifications, plus ECE R129 certification penetration rates in family vehicle configurations.
The model assumes a particular technology adoption path; alternative pathways for ventilated seat blower integration would alter the outlook if HVAC electrical load management priorities shift. Forecasts reflect assumptions regarding REACH substance restriction enforcement timelines, carbon-border adjustment documentation compliance rates, and magnesium alloy price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market