
 Africa and Middle East Automotive Sunroof Market | 2026-2036
Africa and Middle East Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Automotive Sunroof Market Outlook
Fleet procurement across Gulf-based premium mobility providers is broadening the addressable customer base beyond traditional retail channels. Webasto Group leverages its regional assembly footprint to serve both OEM and aftermarket channels. Inalfa Roof Systems Group BV anchors its position through dedicated R&D for high-ambient-temperature sealing solutions. Magna International competes on manufacturing scale across multiple vehicle platforms.
An automotive sunroof is an operable or fixed glazed or opaque panel installed in a vehicle roof structure, typically constructed from tempered glass with UV-filtering interlayers and reinforced perimeter frames to manage torsional rigidity loads. It provides cabin ventilation, natural lighting, and perceived interior spaciousness while requiring integration with drainage channels and rollover protection structures. Panoramic sunroof configurations command the strongest margin pools due to complexity and material intensity, while glass material specifications dominate OEM fitment because of optical clarity and thermal management demands. Spoiler sunroof variants sustain niche volume in sport-oriented coupe segments where aerodynamic profiles constrain larger aperture designs.
Saudi Arabia's SASO and the UAE's Emirates Authority for Standardization and Metrology enforce vehicle glazing and occupant protection standards that directly shape sunroof structural requirements and homologation pathways. South Africa's NRCS applies UN ECE-equivalent regulations for transparent roof materials, creating compliance obligations for imported assemblies. Stakeholders must monitor evolving thermal performance mandates and local content incentives as Gulf states deepen automotive manufacturing ambitions.
Market Dynamics
Fleet procurement by Gulf-based premium mobility providers is redirecting volume toward large-aperture panoramic configurations, compressing traditional retail channel dominance and forcing suppliers to reconfigure assembly priorities.
Growth Catalysts
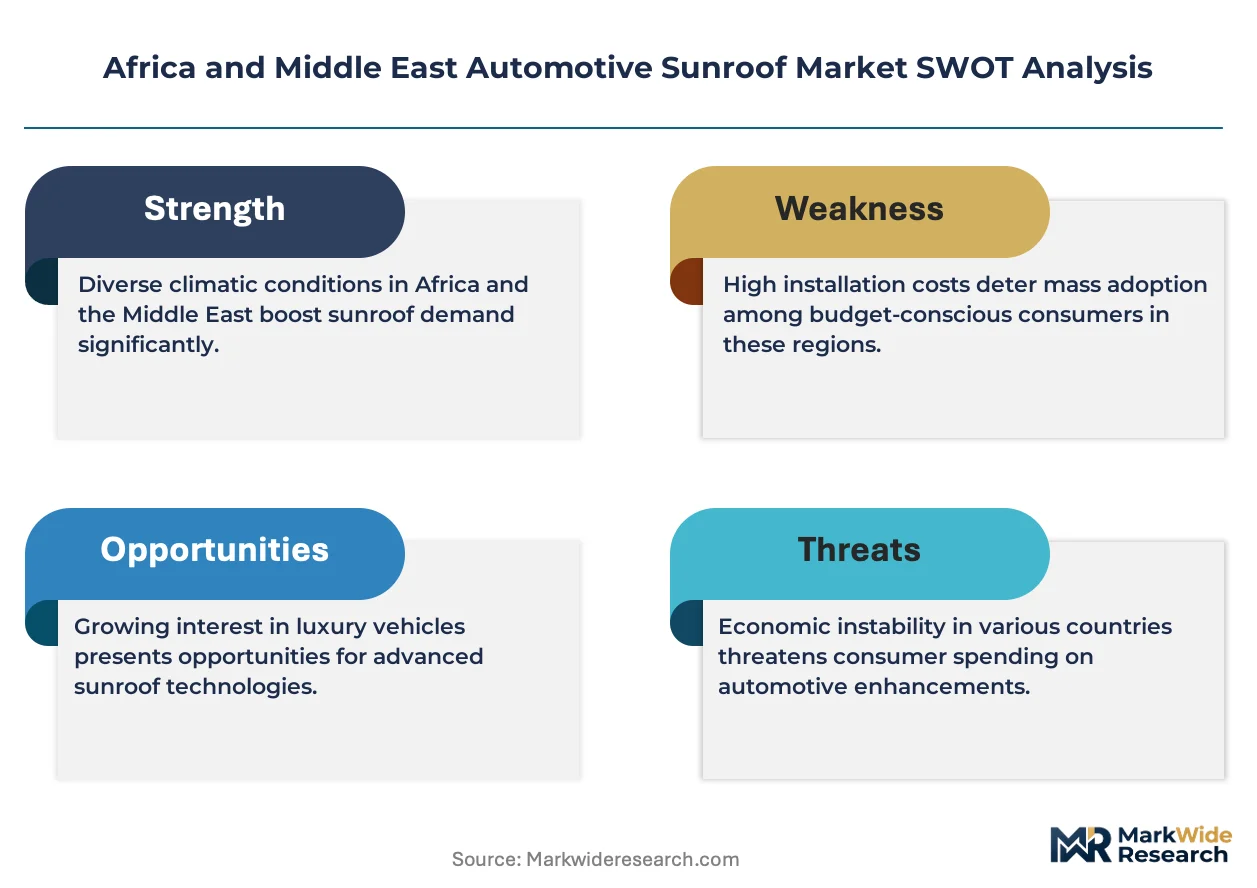
- SASO rollover integrity mandates:Saudi Arabia's safety standards for glazed roof panels are accelerating structural reinforcement investments across supplier portfolios.
- Luxury SUV fleet expansion:Rental and limousine services across the United Arab Emirates are standardizing sunroof fitment as a competitive amenity.
- High-ambient-temperature sealing R&D:Specialized materials development for desert climates is opening performance differentiation pathways for regional suppliers.
Market Restraints
- Tempered glass supply concentration:Regional dependence on imported glass substrates exposes assemblers to freight cost volatility and currency fluctuation risks.
- Drainage channel corrosion:Sand particulate infiltration in Gulf climates accelerates component degradation, elevating warranty exposure for fixed-glass installations.
- Emirates Authority homologation timelines:Extended certification cycles for transparent roof materials delay product refresh cycles by six to twelve months.
Strategic Opportunities
- South African aftermarket customization:NRCS-equivalent UN ECE regulations enable compliant import pathways for specialized sunroof retrofits in premium vehicle segments.
- UV-filtering interlayer convergence:Integration of photovoltaic film technologies with traditional glazing creates energy-harvesting roof propositions for electric vehicle platforms.
- Saudi automotive manufacturing incentives:Local content requirements under Vision 2030 industrial policy are incentivizing assembly footprint expansion for regional supply security.
Industry Challenges
- Sealing engineering talent scarcity:Specialized polymer chemists capable of formulating elastomer compounds for 50°C+ operating environments command premium compensation.
- Roll-forming equipment capex intensity:Perimeter frame production requires continuous investment in high-tonnage press lines and automated welding cells.
- Multi-regulator compliance parallelism:Simultaneous adherence to SASO, ESMA, and NRCS testing protocols fragments engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Automotive Sunroof Market |
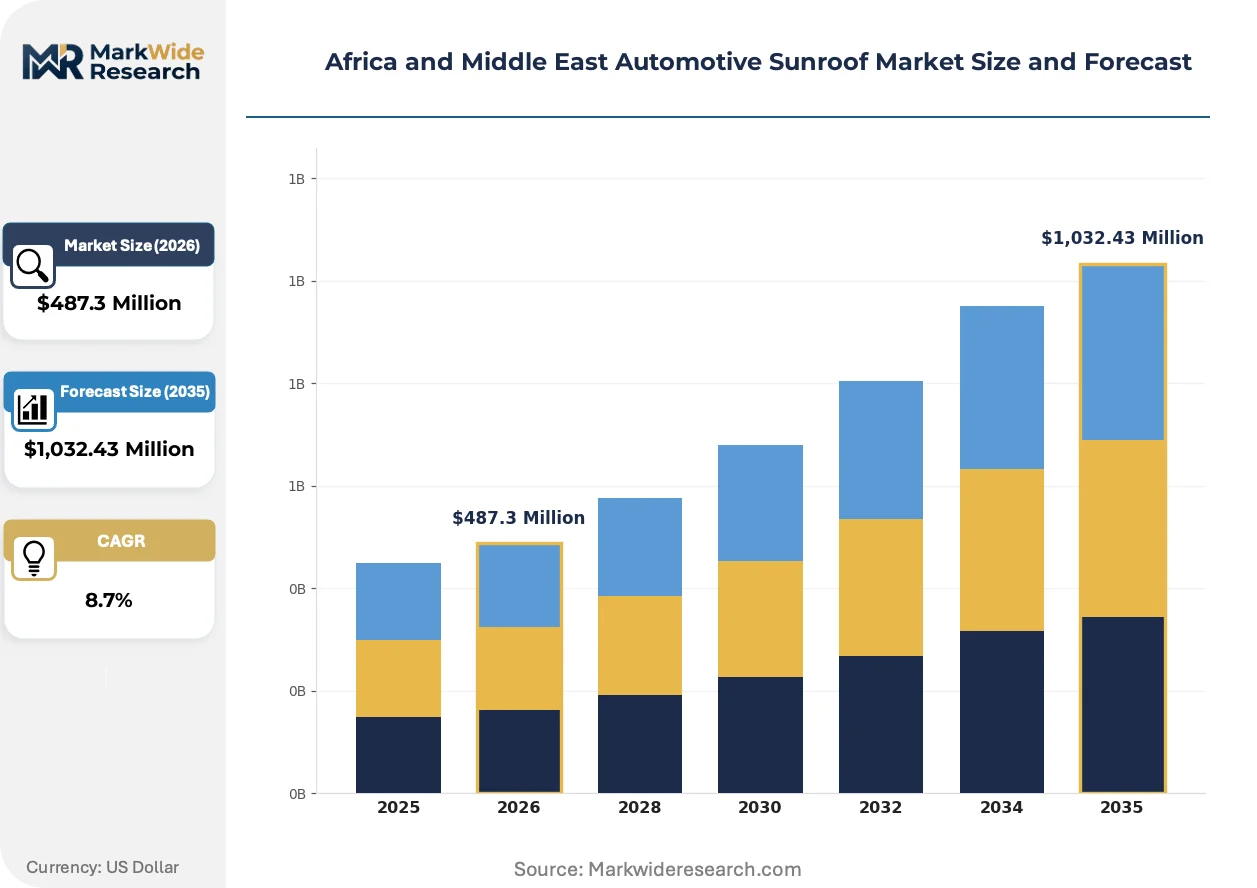
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Moonroof, Pop-Up Sunroof, Panoramic Sunroof, Spoiler Sunroof Material: Glass, Metal, Plastic, Composite Market Player: OEMs, Aftermarket Suppliers, Modifiers, Tier-1 Manufacturers Vehicle Type: SUV, Sedan, Hatchback, Coupe |
| Companies Covered | Webasto Group, Inalfa Roof Systems Group BV, Inteva Products LLC, Aisin Seiki Co Ltd, Yachiyo Industry Co Ltd, Magna International, CIE Automotive, Mitsuba Corporation, Valmet Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Automotive Sunroof Market Strategic Shifts
Electrochromic dimming technology and frameless architectural designs are converging to redefine cabin atmosphere control, while regulatory pressure on thermal performance accelerates material substitution cycles.
Polymer-dispersed liquid crystal (PDLC) glazing is overtaking conventional mechanical shade systems in executive limousine configurations. Fleet operators across Dubai and Abu Dhabi are specifying switchable opacity panels for privacy-on-demand functionality. This transition is compressing mechanical component supplier margins while elevating electronics integration capabilities among tier-one assemblers.
ESMA thermal transmittance standards for vehicle glazing are mandating upgraded interlayer specifications across all new vehicle registrations in the United Arab Emirates. Manufacturers must now certify U-value performance for panoramic roof assemblies previously exempt from full-enclosure testing. Premium SUV segments are responding with vacuum-insulated glass prototypes, though cost curves currently constrain mass-market penetration.
Limousine fleet operators are consolidating procurement through direct supplier relationships, bypassing traditional aftermarket distributors for volume maintenance contracts. Webasto Group and Inalfa Roof Systems are establishing dedicated service networks for high-mileage commercial vehicles. This channel compression is most pronounced in Saudi Arabia's eastern province, where corporate transport contracts specify ten-year glazing integrity guarantees.
Africa and Middle East Automotive Sunroof Market Segmentation
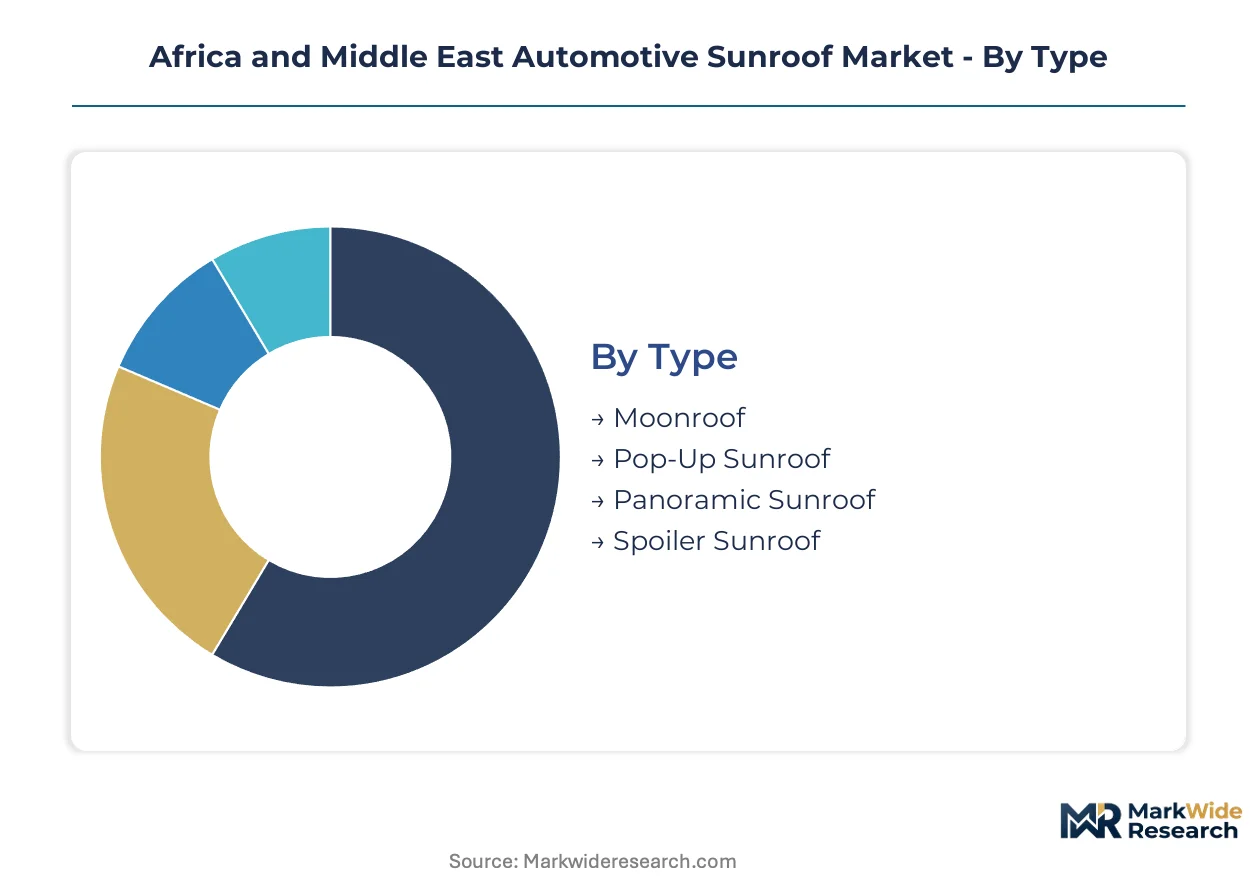
Segmentation in the Africa and Middle East Automotive Sunroof Market reveals divergent profit pools between mass-volume glass installations and premium panoramic configurations. Fleet procurement patterns across Gulf Cooperation Council states concentrate demand in specific type and material combinations, while South African aftermarket channels sustain distinct vehicle-type preferences.
Type:
Panoramic sunroofs command the premium tier by aperture size and structural complexity, while spoiler variants occupy a narrow performance niche.
- Panoramic Sunroof:Multi-panel glazed assemblies spanning front and rear cabin sections with reinforced perimeter frames managing torsional loads. Limousine fleets across Dubai and Abu Dhabi specify these as standard amenities, with SASO rollover integrity mandates accelerating structural reinforcement investments across supplier portfolios. Today's leader: Panoramic Sunroof. Tomorrow's challenger: Moonroof.
- Spoiler Sunroof:Compact externally-hinged panels optimized for aerodynamic profiles in sport-oriented vehicle architectures. Coupe segments in Saudi Arabia's eastern province sustain niche volume where larger apertures compromise roofline aesthetics. Procurement concentrates through direct supplier relationships bypassing traditional aftermarket distributors.
- Moonroof:Inward-opening glazed panels with integrated wind deflectors and drainage channels. UAE premium SUV retail channels favor this configuration for perceived reliability in high-ambient-temperature operating environments.
- Pop-Up Sunroof:Manually or electrically tilted panels with limited translation travel. South African aftermarket customization channels sustain residual demand for budget-conscious retrofit applications in older vehicle platforms.
Panoramic configurations dominate fleet procurement economics. Moonroof simplicity gains traction in retail warranty-sensitive segments.
Material:
Glass substrates anchor OEM fitment by optical clarity demands, while composite alternatives emerge under thermal performance pressure.
- Glass:Tempered or laminated constructions with UV-filtering interlayers and reinforced perimeter frames. ESMA thermal transmittance standards for vehicle glazing now mandate upgraded interlayer specifications across all new UAE vehicle registrations, elevating vacuum-insulated prototypes in premium SUV development pipelines. Glass maintains volume leadership through optical clarity and thermal management performance.
- Composite:Fiber-reinforced polymer matrices offering weight reduction and design flexibility. Saudi automotive manufacturing incentives under Vision 2030 industrial policy are incentivizing local assembly footprint expansion for regional supply security of non-glass alternatives.
- Metal:Aluminum or steel opaque panels with painted or anodized finishes. Niche retention in economy vehicle segments where cost minimization supersedes cabin lighting preferences.
- Plastic:Polycarbonate or acrylic formulations with scratch-resistant coatings. Limited penetration due to thermal expansion coefficient mismatches in 50°C+ Gulf operating environments.
Glass commands current fitment economics. Composites represent the steepest expansion trajectory under regulatory thermal performance pressure.
Market Player:
Channel structure bifurcates between OEM captive supply and independent aftermarket networks serving distinct warranty and customization requirements.
- OEMs:Vehicle manufacturers integrating sunroof assemblies during original production with full warranty coverage. Gulf-based premium mobility providers are consolidating procurement through direct supplier relationships, bypassing traditional aftermarket distributors for volume maintenance contracts.
- Aftermarket Suppliers:Independent distributors serving retail customization and replacement demand. South African NRCS-equivalent UN ECE regulations enable compliant import pathways for specialized sunroof retrofits in premium vehicle segments.
- Modifiers:Specialized conversion workshops executing non-factory installations. Concentrated in UAE free zones serving limousine fleet operators with bespoke privacy and lighting configurations.
- Tier-1 Manufacturers:Dedicated sunroof system assemblers supplying both OEM and aftermarket channels. Regional assembly footprints leverage proximity to Gulf fleet procurement centers.
OEM channels dominate volume economics. Aftermarket suppliers capture margin from customization latency.
Vehicle Type:
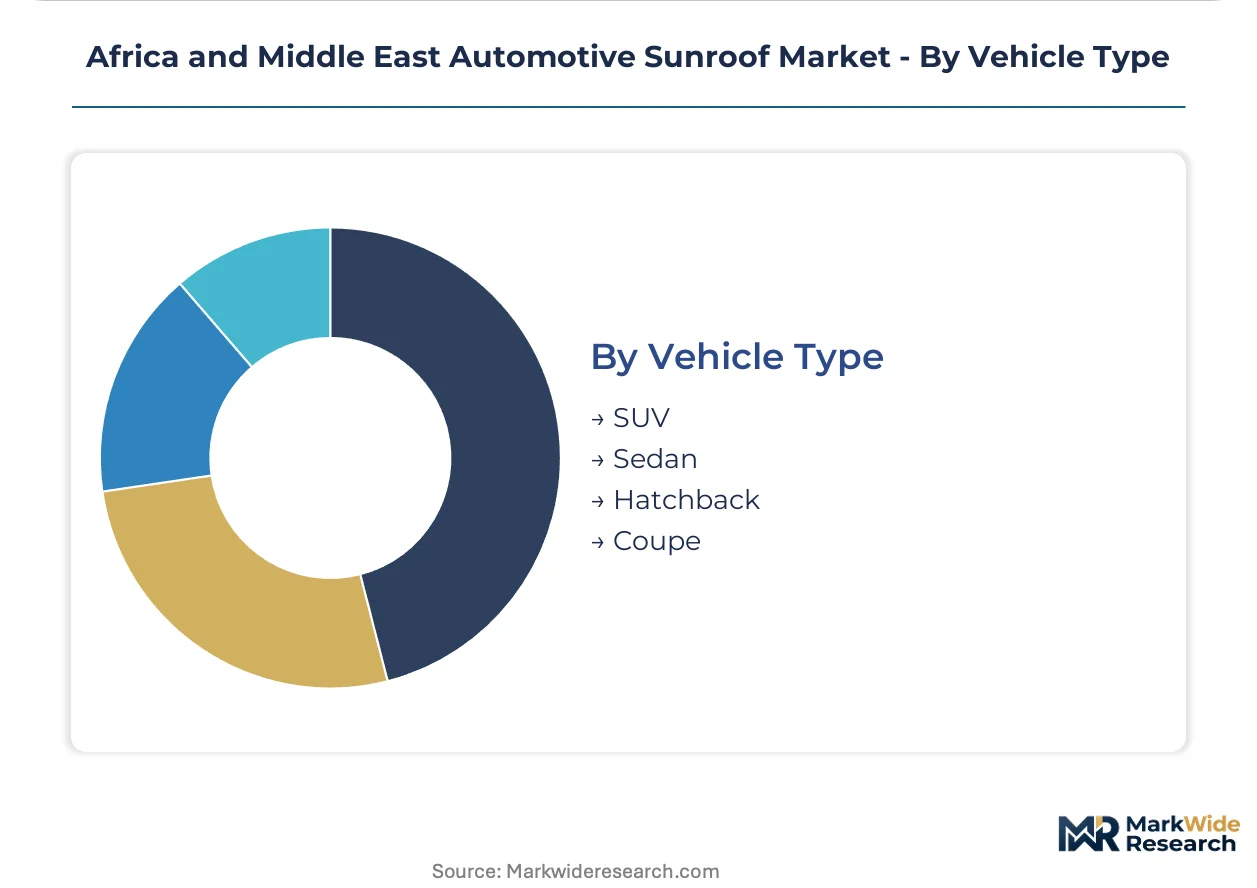
SUV architectures generate the dominant share of sunroof fitment by cabin height and premium positioning alignment.
- SUV:High-roof architectures accommodating large-aperture panoramic configurations without headroom compromise. Luxury SUV fleets across Gulf Cooperation Council rental and limousine services are expanding sunroof fitment rates as competitive amenities.
- Sedan:Three-box designs with integrated trunk volumes sustaining moonroof and pop-up configurations. Saudi retail channels show preference for fixed-glass options minimizing drainage channel corrosion exposure.
- Hatchback:Compact two-box architectures with limited roof structural depth constraining sunroof size specifications. Economy positioning limits penetration to entry-level glass or metal panel offerings.
- Coupe:Sport-oriented two-door profiles where aerodynamic constraints favor spoiler sunroof variants. Saudi Arabia's eastern province corporate transport contracts specify extended glazing integrity guarantees for high-mileage commercial deployments.
SUV platforms anchor current demand concentration. Sedan segments offer challenger volume from fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Arab Emirates generates higher sunroof penetration rates than Saudi Arabia due to concentrated premium vehicle sales and aftermarket customization demand, while both markets operate under distinct regulatory frameworks governing glazed roof assemblies.
United Arab Emirates
Limousine and premium rental fleets across Dubai and Abu Dhabi standardize panoramic sunroofs as competitive amenities. ESMA thermal transmittance standards mandate upgraded interlayer specifications for all new vehicle registrations. Jebel Ali free zones concentrate modifier workshops executing bespoke privacy and lighting configurations for commercial operators.
Saudi Arabia
Luxury SUV procurement by corporate transport providers redirects volume toward large-aperture configurations. SASO rollover integrity testing requirements accelerate structural reinforcement investments across supplier portfolios. Eastern Province corporate contracts specify extended glazing integrity guarantees for high-mileage commercial deployments.
South Africa
Aftermarket customization channels sustain demand for specialized sunroof retrofits in premium vehicle segments. NRCS applies UN ECE-equivalent regulations for transparent roof materials, enabling compliant import pathways. Gauteng province hosts the dominant concentration of conversion workshops serving retail customization demand.
Qatar
Premium mobility providers in Doha consolidate procurement through direct supplier relationships for fleet maintenance contracts. The country's national standardization body enforces vehicle glazing standards aligned with Gulf Cooperation Council technical regulations. Lusail development zone attracts modifier operations serving luxury hospitality transport segments.
Kuwait
High-ambient-temperature operating environments drive demand for specialized sealing solutions in sunroof assemblies. The national quality and metrology authority oversees vehicle component homologation consistent with regional Gulf standards. Kuwait City metropolitan area concentrates retail channels for premium SUV sales with factory-installed glass roof options.
Africa and Middle East Automotive Sunroof Market Competitive Environment
German and Japanese producers anchor one tier; North American and European specialists hold differentiated positions through manufacturing scale and regional assembly proximity. The supplier base concentrates around dedicated sunroof system assemblers with dual OEM-aftermarket channel presence. Three archetypes dominate: integrated automotive suppliers with multi-platform capabilities, specialized roof system engineers with climate-specific R&D focus, and regional assembly operators serving Gulf fleet procurement centers. Competitive moves center on capacity expansion near demand clusters and strategic partnerships with premium mobility fleet operators.
Within the specialized engineering tier, Webasto Group and Inalfa Roof Systems Group BV exemplify suppliers with dedicated regional assembly footprints and high-temperature sealing development capabilities. Magna International occupies a position representing integrated automotive suppliers competing on manufacturing scale across multiple vehicle platforms. These three entities collectively illustrate the competitive structure spanning climate-adapted specialization and broad manufacturing capacity.
| Leading Market Players |
|---|
| Webasto Group |
| Inalfa Roof Systems Group BV |
| Inteva Products LLC |
| Aisin Seiki Co Ltd |
| Yachiyo Industry Co Ltd |
| Magna International |
| CIE Automotive |
| Mitsuba Corporation |
| Valmet Oyj |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap sealing specialists across Germany and Japan anchor component supply, translating concentrated ownership discipline into stable contract pricing and limited spot-market volatility for Gulf fleet procurement.
Pricing Analysis
Capacity additions in Turkey and Morocco are reshaping price floors for perimeter frame assemblies, compressing margins on standardized glass installations. Three-tier pricing structure across premium panoramic, standard moonroof, and economy fixed-glass levels stratifies by thermal certification grade and volume commitment scale. Pricing pressure stems from ESMA-mandated interlayer upgrades elevating input costs for UAE-bound production. Fleet operators exhibit lowest price sensitivity due to ten-year glazing integrity guarantees, while South African aftermarket retail channels demand aggressive unit economics.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Dammam operate hub-and-spoke patterns feeding modifier workshops and OEM assembly lines. Manufacturing concentrates in Germany, Japan, and China for tempered glass substrates, frame roll-forming equipment, and electrochromic film technologies. The chain rests on imported UV-filtering interlayers, high-temperature elastomer compounds, and vacuum-insulated glass prototypes. Single-source vulnerability runs through German-engineered sealing polymer formulations. Distribution runs through Tier-1 manufacturer direct contracts with Gulf mobility providers, bypassing traditional aftermarket wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where panoramic specification rates in limousine fleets now exceed retail penetration, rewarding suppliers with climate-adapted R&D capabilities.
For Market Incumbents: Acquire specialized polymer chemistry talent pools capable of formulating 50°C+ operating compounds. Consolidate regional assembly footprints in Saudi Arabia's emerging automotive zones to capture Vision 2030 local content incentives. Defend against spoiler sunroof displacement in coupe segments by embedding electrochromic dimming as standard equipment.
For New Entrants and Emerging Players: Limousine fleet modifiers in Dubai free zones represent the most penetrable channel partner type for aftermarket service network establishment. Target South African NRCS-compliant import pathways for specialized retrofit configurations in premium SUV segments. Enter through direct procurement relationships with corporate transport contracts specifying extended glazing integrity coverage.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional assembly operators with Gulf proximity but limited climate-specific IP portfolios. Five-to-ten-year viability hinges on electrochromic and photovoltaic glazing convergence for electric vehicle platforms. Watch for SASO thermal performance mandate expansion as the inflection signal for vacuum-insulated glass adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Ambient-Temperature Sealing R&D Investment | Webasto Group and Inalfa Roof Systems differentiate through dedicated polymer chemistry for Gulf climates. |
| Regional Assembly Footprint Expansion | Saudi Vision 2030 incentives are attracting Tier-1 manufacturers to eastern province industrial zones. |
| Electrochromic Technology Integration | PDLC glazing adoption in Dubai limousine fleets compresses mechanical shade supplier margins. |
| Fleet Direct Procurement Relationships | Gulf mobility providers bypass aftermarket distributors for volume maintenance contracts. |
| Photovoltaic Glazing Convergence | Energy-harvesting roof propositions align with UAE electric vehicle platform development pipelines. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and limousine fleet operations managers grounded qualitative assessment. Secondary validation drew from vehicle production databases, IHS Markit registration data, SASO technical bulletins, and ESMA thermal transmittance standards. Bottom-up and top-down triangulation reconciled assembly volume estimates with fleet procurement contract disclosures.
Bottom-up modeling aggregated content-per-vehicle assumptions across SUV, sedan, and coupe segments by propulsion architecture and regional production cluster. Top-down verification cross-checked against Gulf Cooperation Council vehicle sales projections and premium fleet expansion timelines. CAGRs derived from segment-level volume trajectories incorporating SASO rollover integrity mandate compliance costs and ESMA thermal performance upgrade requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi automotive manufacturing incentive expansion and electrochromic technology cost curve trajectories. Outputs reflect documented assumptions around fleet procurement concentration and regulatory harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Drawer Slides Market