
 Automotive Lighting Market | 2026-2036
Automotive Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lighting Market Analysis
LED and matrix beam specification-tier upgrades is reorganizing competitive dynamics across the automotive lighting value chain. Koito Manufacturing leverages its captive LED chip partnerships to sustain technology leadership in premium headlamp assemblies. HELLA GmbH & Co. KGaA anchors its position through deep specialization in adaptive front-lighting systems for European OEM platforms. Stanley Electric Co., Ltd competes aggressively on manufacturing scale across Japanese and North American assembly plants.
Automotive lighting encompasses electroluminescent and discharge-based illumination systems engineered to meet precise photometric, colorimetric, and thermal specifications for exterior and interior vehicle applications. These systems integrate optical lenses, thermal management substrates, and driver electronics to deliver regulated luminous intensity distributions that ensure occupant safety and pedestrian visibility under dynamic operating conditions. LED product types now command dominant share due to their efficacy advantages and declining unit costs, while OLED segments occupy niche positions in premium taillight differentiation. Matrix lighting technology leads growth trajectories as regulatory frameworks in multiple jurisdictions permit partial high-beam automation without glare to oncoming traffic. OEM end users concentrate procurement volumes with tier-1 suppliers capable of delivering module-level integration.
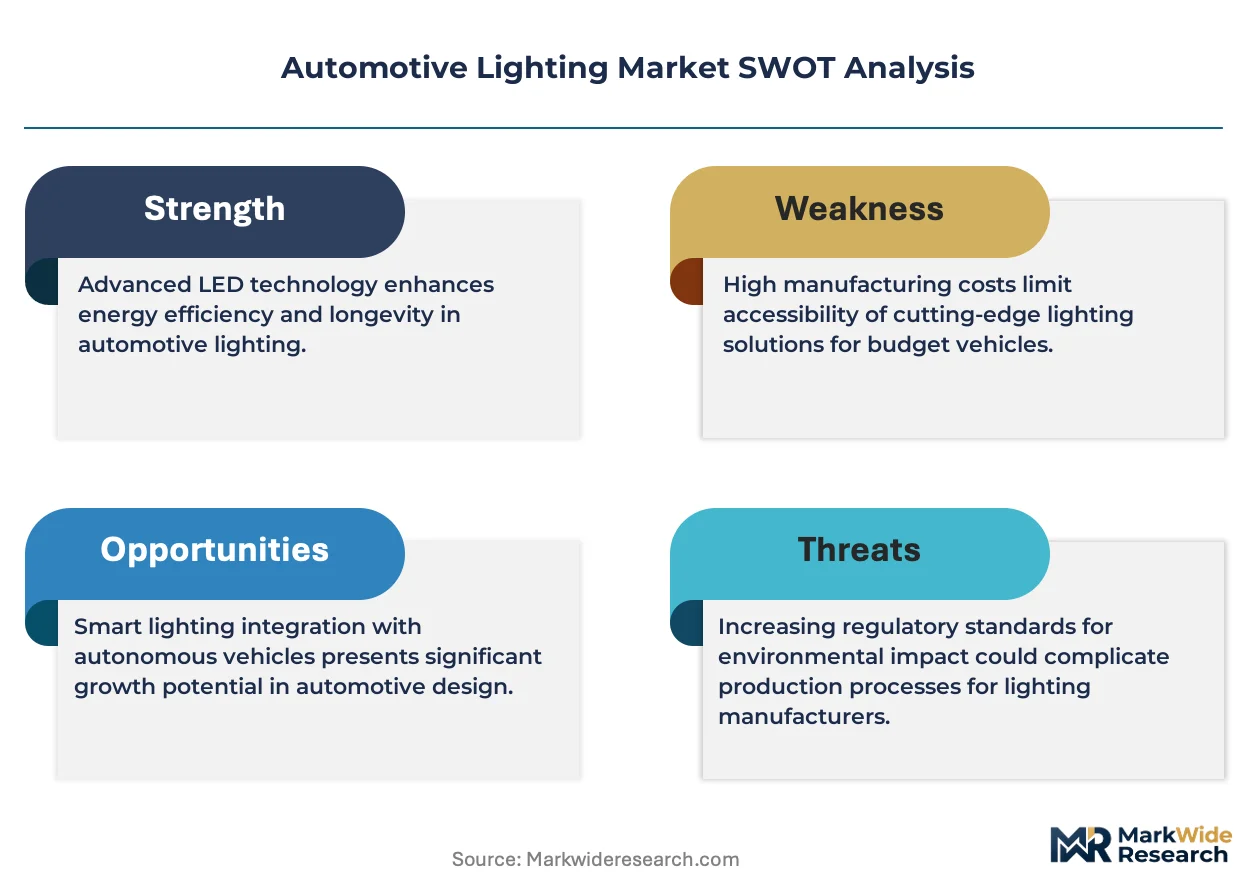
Europe's ECE R48 and R123 regulations govern vehicle lighting installation and performance, while the EU Green Deal's embodied carbon directives pressure suppliers to reduce manufacturing energy intensity. The US NHTSA maintains distinct Federal Motor Vehicle Safety Standard 108 requirements that create compliance fragmentation for multinational suppliers. Japan's METI coordinates domestic standards through JIS frameworks that often anticipate harmonized international protocols. Stakeholders must monitor regulatory divergence on adaptive beam approval timelines and carbon border adjustment mechanisms to optimize regional production footprints.
Market Dynamics
LED module standardization is compressing supplier margins while accelerating platform consolidation across passenger vehicle and commercial truck segments.
Growth Catalysts
- EU Green Deal embodied carbon directives:OEM procurement mandates now prioritize suppliers with verified low-carbon manufacturing footprints, redirecting contract volumes toward LED foundries with renewable energy sourcing.
- Matrix beam regulatory liberalization:ECE R123 amendments permitting partial high-beam automation without glare are unlocking specification upgrades across German and Swedish premium vehicle platforms.
- Vehicle electrification intensity:Battery electric architectures demand lighting systems with 40% lower power draw, forcing halogen-to-LED conversion timelines forward by entire model cycles.
Market Restraints
- Silicon carbide substrate cost volatility:LED epitaxy wafer prices fluctuate with power semiconductor demand cycles, squeezing module assembler margins during automotive contract renegotiations.
- East Asian LED chip concentration:Over 70% of high-brightness die production sits within Taiwan and South Korean foundry networks, creating single-source vulnerability for European headlamp integrators.
- Thermal management complexity ceiling:Power densities above 3W per square millimeter in compact headlamp housings exceed passive cooling limits without active fan integration, adding cost and failure modes.
Strategic Opportunities
- Indian passenger vehicle LED penetration gap:Domestic OEMs still specify halogen for 60% of subcompact entries, creating retrofit and first-fit upgrade potential as BIS lighting efficiency mandates tighten.
- LiDAR-optical convergence:Headlamp modules integrating emitter and sensor functions into shared apertures are capturing prototype contracts from autonomous vehicle development programs.
- Digital light projection:Micro-LED arrays enabling ground-symbol projection and pedestrian communication are securing specification wins on luxury electric SUV launches.
Industry Challenges
- Photonic simulation talent scarcity:Optical design for adaptive beam patterns requires combined expertise in ray-tracing software and thermal finite-element analysis that automotive suppliers struggle to recruit.
- Homologation timeline compression:Parallel ECE and NHTSA approval pathways for matrix functions demand duplicate test fleets and documentation, extending program launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lighting Market |
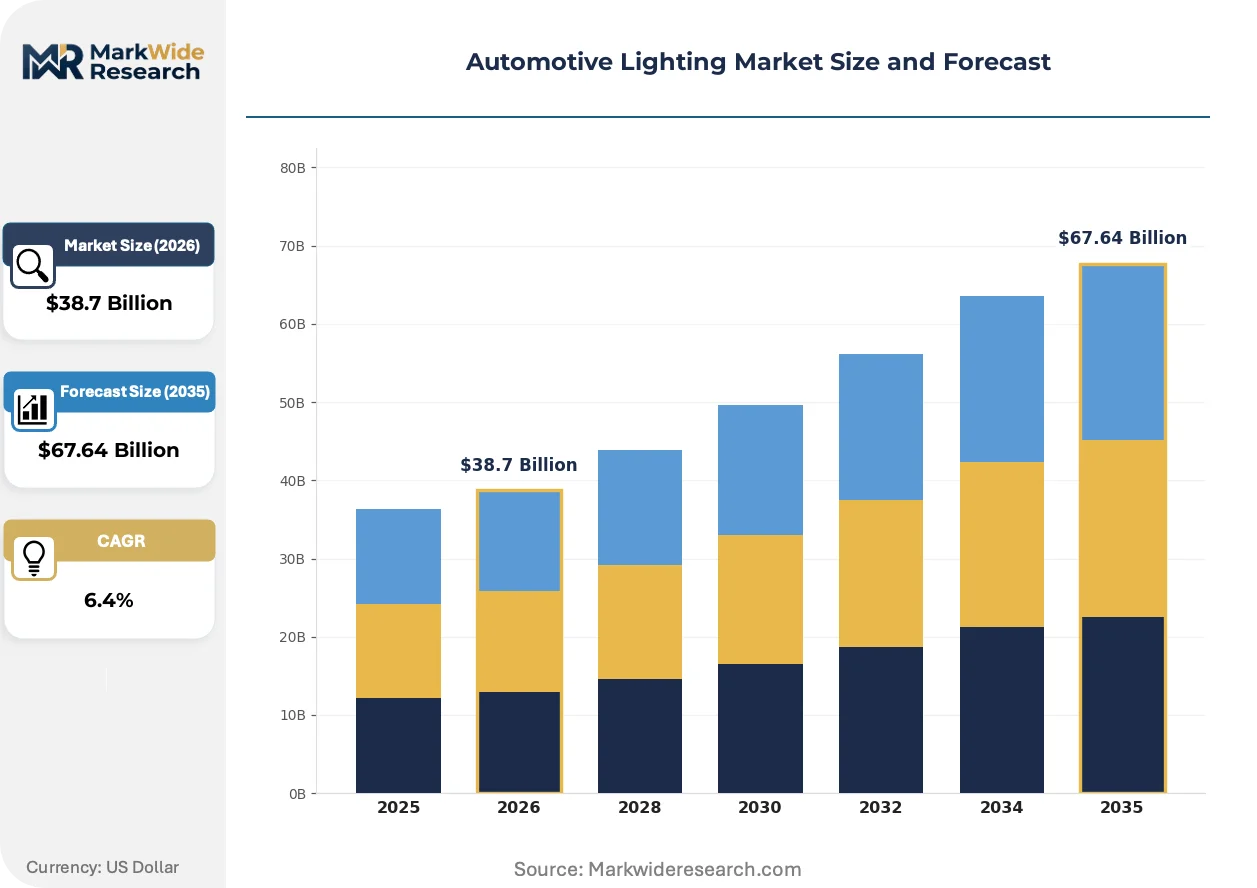
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, Xenon, LED, OLED Application: Headlights, Taillights, Interior Lights, Indicator Lights Technology: Adaptive Lighting, Matrix Lighting, Laser Lighting, Smart Lighting End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Koito Manufacturing Co., Ltd, HELLA GmbH & Co. KGaA, Stanley Electric Co., Ltd, Valeo, Magneti Marelli, Osram GmbH, Hyundai Mobis, ZKW Group, SL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lighting Market Emerging Trajectories
Automotive lighting is undergoing platform-level integration with sensor and communication architectures, eroding the historical separation between illumination and electronics supply chains.
Micro-LED cluster arrays for signature lighting and dynamic turn indicators are miniaturizing optical package dimensions while multiplying addressable pixel counts. Tier-1 suppliers in Germany and Japan are adopting these devices for 2026-2027 model year premium vehicles. The technology is miniaturizing control electronics into headlamp housings previously reserved for passive reflector assemblies, compressing supplier tier structures.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of optical coatings and gasket materials used in exterior lamp sealing. European compounders must certify replacement chemistries by 2026 to maintain component approval status. German headlamp manufacturers are accelerating validation timelines to secure supply continuity ahead of enforcement windows.
Fleet procurement for rental and mobility services is consolidating lighting specification decisions into central technical centers, displacing traditional dealer-channel aftermarket influence. Large fleet operators in the United States now mandate LED across all vehicle classes to reduce maintenance downtime and insurance liability exposure. This concentration is visible in annual volume contracts from national rental networks that now exceed individual OEM dealer program purchases.
Automotive Lighting Market Segmentation
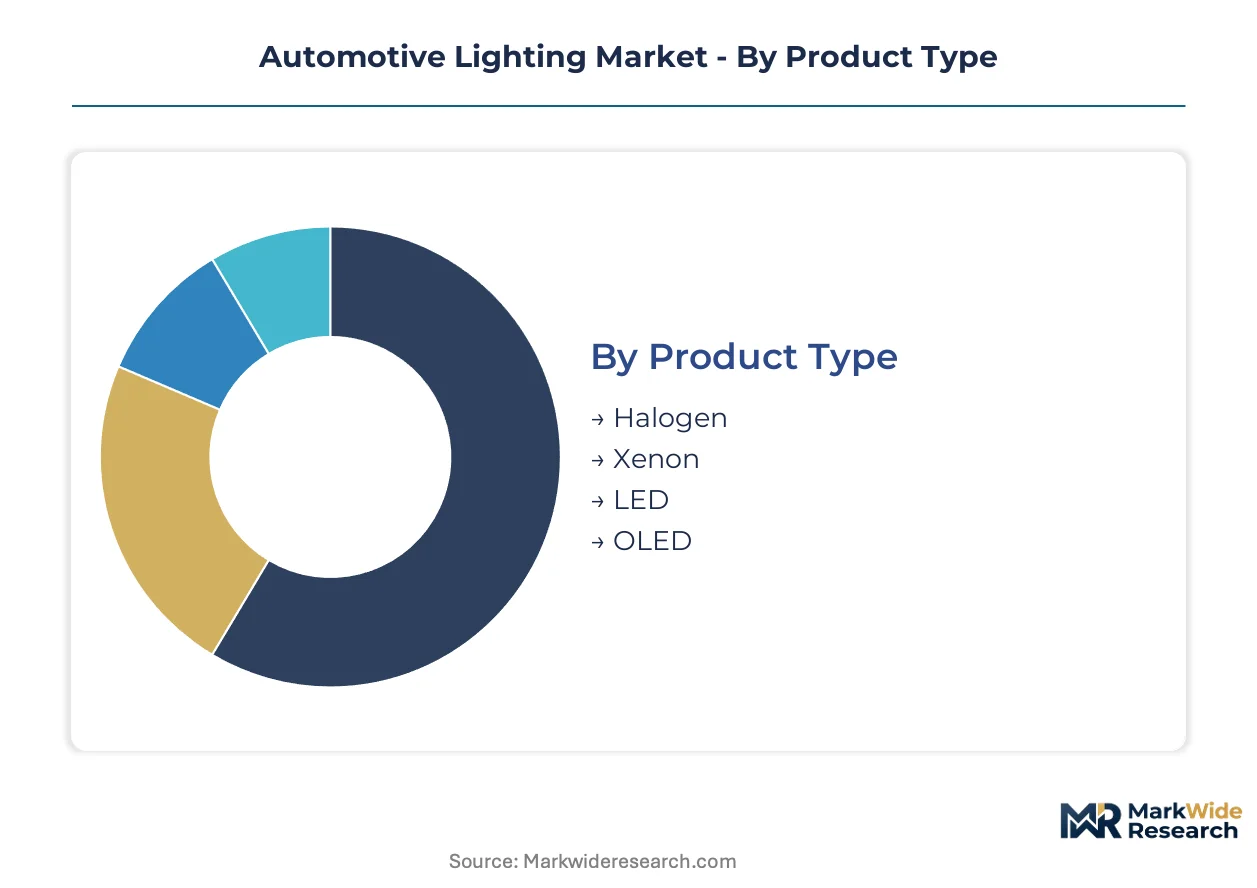
Segmentation in automotive lighting reveals how technology transitions and procurement hierarchies redistribute value across the supply chain. Understanding these divisions exposes where specification upgrades concentrate and which customer channels command pricing power.
Product Type:
Margin pools cluster around solid-state technologies where thermal management and optical design create differentiation barriers.
- LED:Semiconductor-based solid-state emitters deliver efficacy above 100 lumens per watt with 50,000-hour operational lifespans. Battery electric vehicle programs in Germany and Japan specify LED exclusively to reduce electrical system load and extend driving range. The technology commands premium positioning across all vehicle classes as halogen replacement accelerates.
- OLED:Organic electroluminescent panels enable uniform surface illumination without reflector assemblies, enabling distinctive taillight signatures on premium European SUVs. Limited to exterior accent applications due to brightness constraints and moisture sensitivity. Niche positioning sustains higher per-unit margins despite lower volumes.
- Halogen:Tungsten-halogen incandescent technology dominates entry-level vehicle segments in India and Southeast Asia where cost minimization overrides efficiency mandates.
- Xenon:High-intensity discharge systems using metal-halide arc tubes retain presence in mid-range vehicle refreshes where LED retrofit costs exceed program budgets.
The dominant share belongs to LED, while OLED is closing the gap fastest through premium exterior differentiation programs.
Application:
Specification intensity varies sharply by mounting position, with forward-facing systems absorbing the majority of R&D investment and regulatory scrutiny.
- Headlights:Forward illumination modules integrate adaptive beam shaping, thermal management, and driver assistance sensor mounting. ECE R123 compliance requirements in Europe and NHTSA FMVSS 108 in the United States create dual homologation burdens that favor suppliers with established regulatory engineering capabilities.
- Taillights:Rear signaling and braking illumination functions serve as primary brand differentiation surfaces through sequential animation and OLED panel integration. European OEMs specify dynamic turn indicators as standard across premium segments.
- Interior Lights:Cabin ambient and task lighting systems prioritize color tunability and low power draw for electric vehicle range preservation.
- Indicator Lights:Turn signal and hazard warning functions face standardization pressure from UN ECE regulations limiting design variation for safety recognition.
Headlights capture the largest revenue concentration, though interior lighting is expanding most quickly through ambient personalization features.
Technology:
Intellectual property density separates commodity illumination from value-added systems, with software-controlled beam management creating recurring engineering service opportunities.
- Matrix Lighting:Addressable LED arrays enable selective high-beam masking to prevent glare while maintaining road illumination. ECE regulatory amendments permitting partial automation have unlocked specification upgrades across German premium platforms.
- Adaptive Lighting:Steerable headlamp modules pivot in response to vehicle dynamics and navigation data, improving cornering visibility. Standard fitment on mid-range vehicles in Japan and European markets.
- Laser Lighting:Blue laser diodes with phosphor conversion achieve extreme throw distances for highway driving modes. Restricted to top-tier performance vehicles due to cost and eye safety certification complexity.
- Smart Lighting:Connected systems integrating V2X communication and ground projection functions for pedestrian warning and parking assistance.
Matrix lighting holds the technology leadership position, while smart lighting is gaining share fastest through autonomous vehicle development contracts.
End User:
Procurement authority concentration determines contract structure, with direct OEM relationships commanding module-level integration responsibilities that aftermarket channels cannot replicate.
- OEMs:Original equipment manufacturers specify complete lighting systems through platform engineering agreements, retaining control over exterior design language and regulatory compliance. German and Japanese OEMs consolidate volumes with tier-1 suppliers capable of global manufacturing footprint alignment.
- Tier-1 Suppliers:Module integrators such as headlamp assemblers and LED module manufacturers serve as primary procurement interfaces, managing sub-tier component qualification and quality assurance.
- Vehicle Assemblers:Contract manufacturing operations for emerging electric vehicle brands source lighting through specification buy agreements rather than in-house design.
- Aftermarket Providers:Replacement lamp distributors and retrofit specialists serve collision repair and customization demand, constrained by homologation requirements for street-legal illumination.
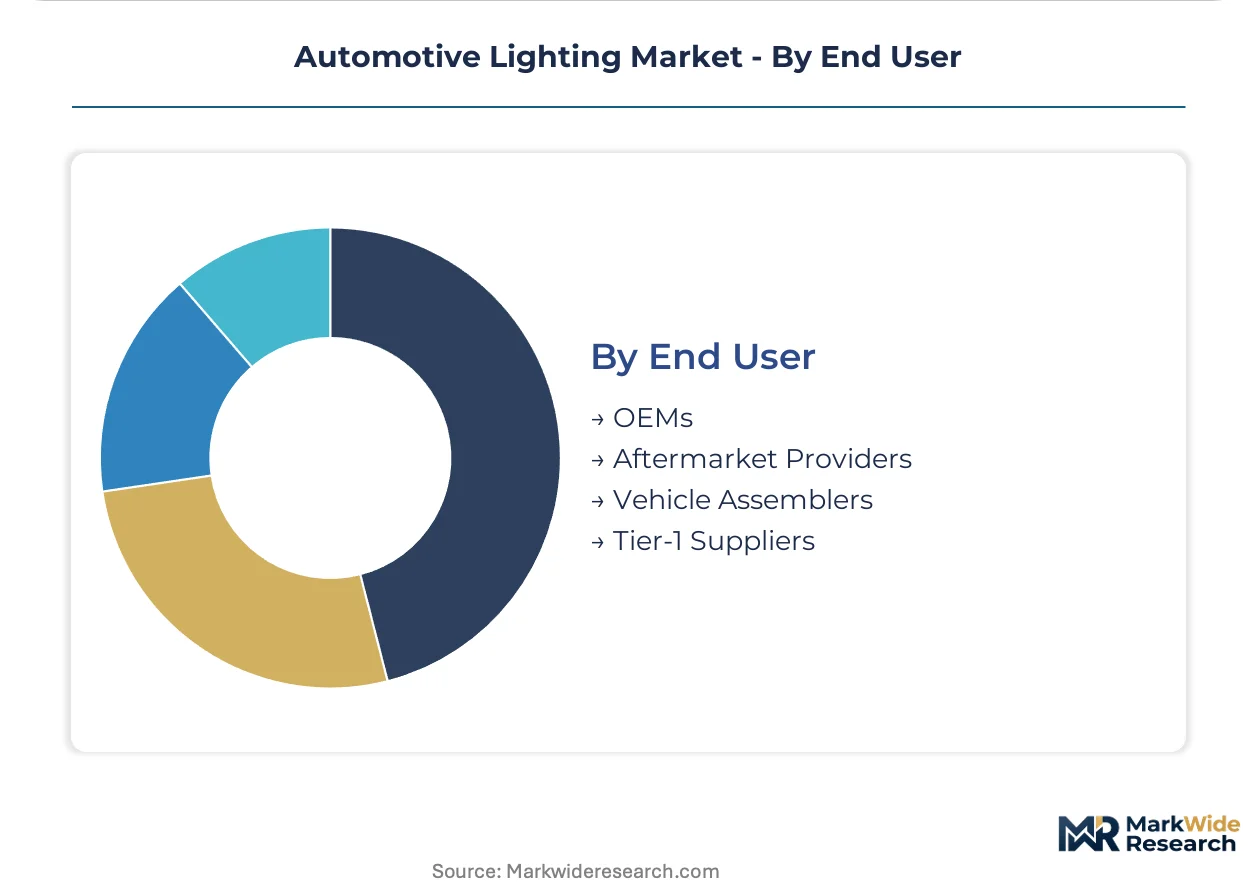
OEMs dominate procurement volume, though tier-1 suppliers are capturing margin expansion fastest through design-to-cost engineering services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia remain acutely price-sensitive, specifying halogen for most subcompact entries, while German and Japanese OEMs absorb LED and matrix premiums without volume elasticity. This demand bifurcation shapes where suppliers locate module assembly versus die sourcing.
United States
NHTSA FMVSS 108 compliance creates distinct homologation pathways separate from European ECE frameworks, forcing dual test protocols for matrix beam introductions. Fleet procurement concentration among national rental networks now mandates LED specifications across all vehicle classes to reduce maintenance downtime. Detroit-area engineering centers coordinate specification decisions for domestic OEM platform launches.
Germany
ECE R123 amendments permitting partial high-beam automation without glare have accelerated matrix lighting adoption across premium vehicle platforms. EU Green Deal embodied carbon directives pressure suppliers to verify renewable energy sourcing in LED foundry partnerships. Stuttgart and Munich host the dominant concentration of adaptive front-lighting development centers for European OEMs.
China
Domestic battery electric vehicle programs specify LED exclusively to reduce electrical system load and extend driving range, compressing halogen replacement timelines. MIIT coordinates national standards that increasingly anticipate harmonized international protocols for smart lighting functions. Yangtze River Delta manufacturing clusters concentrate module assembly capacity serving both domestic OEMs and export programs.
Japan
METI coordinates domestic lighting standards through JIS frameworks that often prefigure broader international regulatory convergence. Hybrid and electric vehicle platforms from domestic OEMs drive specification intensity for low-power-draw interior and exterior systems. Nagoya-area production facilities anchor manufacturing scale for North American and Asian assembly plant supply.
India
BIS lighting efficiency mandates are tightening procurement specifications, though halogen still dominates 60% of subcompact entries where cost minimization overrides efficiency targets. Domestic OEMs face retrofit and first-fit upgrade pressure as regulatory timelines accelerate. Tamil Nadu and Gujarat automotive clusters concentrate tier-1 supplier module assembly operations for both domestic and export vehicle programs.
Automotive Lighting Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium module integrators compete on optical design while scale manufacturers compete on unit economics. The market consolidates around three strategic archetypes: LED die specialists with captive chip partnerships, adaptive system integrators with regulatory engineering depth, and manufacturing-scale assemblers serving high-volume platforms. Dominant competitive moves include backward integration into LED epitaxy capacity and geographic expansion through platform engineering agreements with emerging electric vehicle brands.
Among Japanese and German manufacturers, Koito Manufacturing Co., Ltd and HELLA GmbH & Co. KGaA occupy positions exemplifying the premium-tier archetype through deep specialization in complex headlamp assemblies, while Stanley Electric Co., Ltd represents the scale-driven competitive vector with manufacturing footprint concentration across multiple continents.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd |
| HELLA GmbH & Co. KGaA |
| Stanley Electric Co., Ltd |
| Valeo |
| Magneti Marelli |
| Osram GmbH |
| Hyundai Mobis |
| ZKW Group |
| SL Corporation |
| Others |
Supply Flow & Price Mechanics
Wafer fabrication scale economies in Taiwan and South Korea compress LED die costs while concentrating pricing power among foundry operators, forcing module assemblers to absorb margin pressure or consolidate procurement volumes. This concentration dynamic shapes tier-1 supplier negotiations with German and Japanese OEMs, where long-term platform contracts lock in price floors that smaller competitors cannot match.
Pricing Analysis
ECE R123 dictates the pricing tier structure across European headlamp procurement, with matrix beam certification creating premium positioning against standard LED assemblies. Pricing stratifies across premium matrix-certified, standard adaptive, and economy halogen tiers, with quality grade and volume scale driving differentiation. Cost compression in standard LED modules intensifies as platform standardization spreads, squeezing Tier-2 assemblers most acutely. Indian subcompact OEMs exhibit highest price sensitivity, while German premium vehicle programs absorb specification premiums without volume elasticity.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for high-brightness LED epitaxy, while China and Germany concentrate module assembly and optical system integration. The supply chain draws from silicon carbide substrates, phosphor conversion materials, and precision optical polymers. Single-source vulnerability in East Asian die production exposes European headlamp integrators to supply disruption. Distribution runs through tier-1 module suppliers holding direct OEM platform engineering agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive lighting is recovering from cyclical compression as vehicle electrification accelerates LED specification intensity across all vehicle classes. Battery electric platform launches drive content-per-vehicle expansion that offsets unit volume softness in traditional powertrain segments.
For Market Incumbents: Fortify captive LED chip partnerships through long-term offtake agreements with Taiwanese and South Korean foundries, insulating against substrate cost volatility. Deepen regulatory engineering capabilities in ECE and NHTSA dual homologation to defend against emerging Chinese competitors with domestic standard advantages. Prioritize thermal management IP accumulation as power density requirements exceed passive cooling limits.
For New Entrants and Emerging Players: Anchor in Indian subcompact LED retrofit demand as BIS efficiency mandates tighten halogen replacement timelines. Target fleet procurement centralization in United States rental networks mandating LED specifications across vehicle classes. Pursue LiDAR-optical convergence prototypes with autonomous vehicle development programs as a specification entry point.
For Investors and Strategic Acquirers: Tier-1 suppliers with matrix lighting regulatory approval and established OEM platform relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on software-controlled beam management capabilities expanding addressable content per vehicle. Watch ECE R123 amendment adoption rates in additional jurisdictions as inflection indicator for matrix specification penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Epitaxy | Captive wafer supply from Taiwanese foundries secures cost position against substrate volatility. |
| Matrix Beam Regulatory Engineering Investment | ECE R123 approval capability unlocks premium German OEM platform specifications. |
| LiDAR-Optical Module Convergence | Shared aperture designs capture prototype contracts from autonomous vehicle programs. |
| Indian Manufacturing Footprint Expansion | Tamil Nadu assembly proximity serves domestic OEM retrofit demand and export programs. |
| Digital Light Projection Capability Buildout | Micro-LED ground-symbol functions secure specification wins on luxury electric SUVs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs records, and SEC filings from tier-1 suppliers. Interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations validated specification trends and procurement patterns. Bottom-up modeling of LED content per vehicle by propulsion architecture triangulates against top-down market value reconstruction.
Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from vehicle production forecasts weighted by lighting specification intensity and technology transition timelines. Industry-specific inputs incorporate battery electric vehicle penetration curves and regulatory approval timelines for matrix beam functions.
Material uncertainties — ECE R123 adoption acceleration, silicon carbide substrate supply disruptions, and carbon border adjustment implementation — sit outside the modeled envelope. Forecasts reflect assumptions on OEM platform standardization rates and foundry capacity expansion. Recalibration cycles align with material shifts in regulatory approval timelines and electrification policy intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Rear-View Mirror Market