
 Asia-Pacific Automotive Interior Materials Market | 2026-2036
Asia-Pacific Automotive Interior Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Interior Materials Market Analytics
Aftermarket refurbishment revenue is narrowing as OEMs extend warranty-linked interior refresh programs. Toyota Boshoku Corporation anchors Japan's supply base through captive seating and headliner production for Toyota Group. Yanfeng Automotive Interiors dominates China's passenger car cockpit module integration, leveraging joint-venture scale across Shanghai and Wuhan. Hyundai Mobis Co. Limited sustains Korean OEM captive demand while competing for independent EV platform contracts.
Asia-Pacific automotive interior materials encompass surface and structural components—including leather hides, woven textiles, polyurethane foam cores, and thermoplastic olefin skins—that provide occupant interfaces, acoustic management, and crash energy absorption in passenger and commercial vehicles. Dashboard substrates typically combine talc-filled polypropylene with soft-touch slush-molded skins to meet head-impact criteria under ECE R21. Upholstery and foam segments lead current value generation, as seat systems represent the largest material mass per vehicle; vinyl and fabric applications in door panels and headliners are accelerating fastest, driven by cost-sensitive compact EV programs across Southeast Asia.
China's MIIT enforces GB standards for interior emissions and flame retardancy, while India's BIS mandates AIS-099 for seat strength and head restraint performance; REACH-equivalent substance restrictions in South Korea's MFDS framework shape import eligibility for European suppliers. Japan's METI circular economy guidelines are pressuring suppliers to validate recycled content ratios in dashboard and door panel substrates. Stakeholders must monitor regulatory divergence between China's GB evolution and India's AIS harmonization timeline to avoid dual-certification cost burdens.
Market Dynamics
China's dual carbon goals are compressing material certification timelines across the Asia-Pacific region, forcing suppliers to validate recycled content ratios in dashboard substrates and door panels before GB standards tighten further.
Growth Catalysts
- MIIT Emissions Mandates:China's GB standards for interior VOC emissions and flame retardancy are accelerating reformulation of polyurethane foam cores and slush-molded skins in passenger vehicle programs.
- Premium EV Cabin Demand:Battery-electric vehicle OEMs in the Yangtze River Delta are specifying sustainable upholstery and acoustic foam systems that exceed legacy combustion-era specifications.
- Tamil Nadu Manufacturing Corridor:India's concentrated automotive assembly footprint is pulling localized textile weaving and foam molding capacity to serve Maruti Suzuki and Hyundai Motor India programs.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyurethane precursor costs swing with naphtha and MDI pricing, compressing margin visibility for dashboard substrate and foam core suppliers.
- Captive Supply Concentration:Toyota Boshoku's captive seating production and Yanfeng's cockpit module dominance lock independent material suppliers out of high-volume Japanese and Chinese OEM programs.
- Technical Limitation in Recycling:Multi-material bonding in headliners and door panels prevents closed-loop recovery, blocking compliance with Japan's METI circular economy validation requirements.
Strategic Opportunities
- Vietnam and Indonesia Assembly Expansion:Emerging compact EV programs in Southeast Asia lack established interior supply bases, creating first-mover positioning for foam and textile suppliers with BIS-equivalent certification capability.
- Bio-Based Polyurethane Development:Castor oil and soy-derived polyol formulations are reaching commercial scale, aligning with South Korea's MFDS substance restrictions and China's carbon intensity targets.
- Direct OEM Platform Contracts:Independent EV architectures from NIO, BYD, and Ola Electric are bypassing traditional Tier 1 integrators, opening specification influence for material suppliers with acoustic and haptic validation labs.
Industry Challenges
- Cross-Border Certification Complexity:Suppliers must simultaneously track China's evolving GB standards, India's AIS-099 harmonization timeline, and South Korea's MFDS REACH-equivalent restrictions, multiplying compliance engineering headcount.
- Legacy Combustion Tooling Stranding:Existing slush-molding and injection equipment optimized for petroleum-based TPO skins requires capital-intensive retooling to process bio-based and recycled-content alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Interior Materials Market |
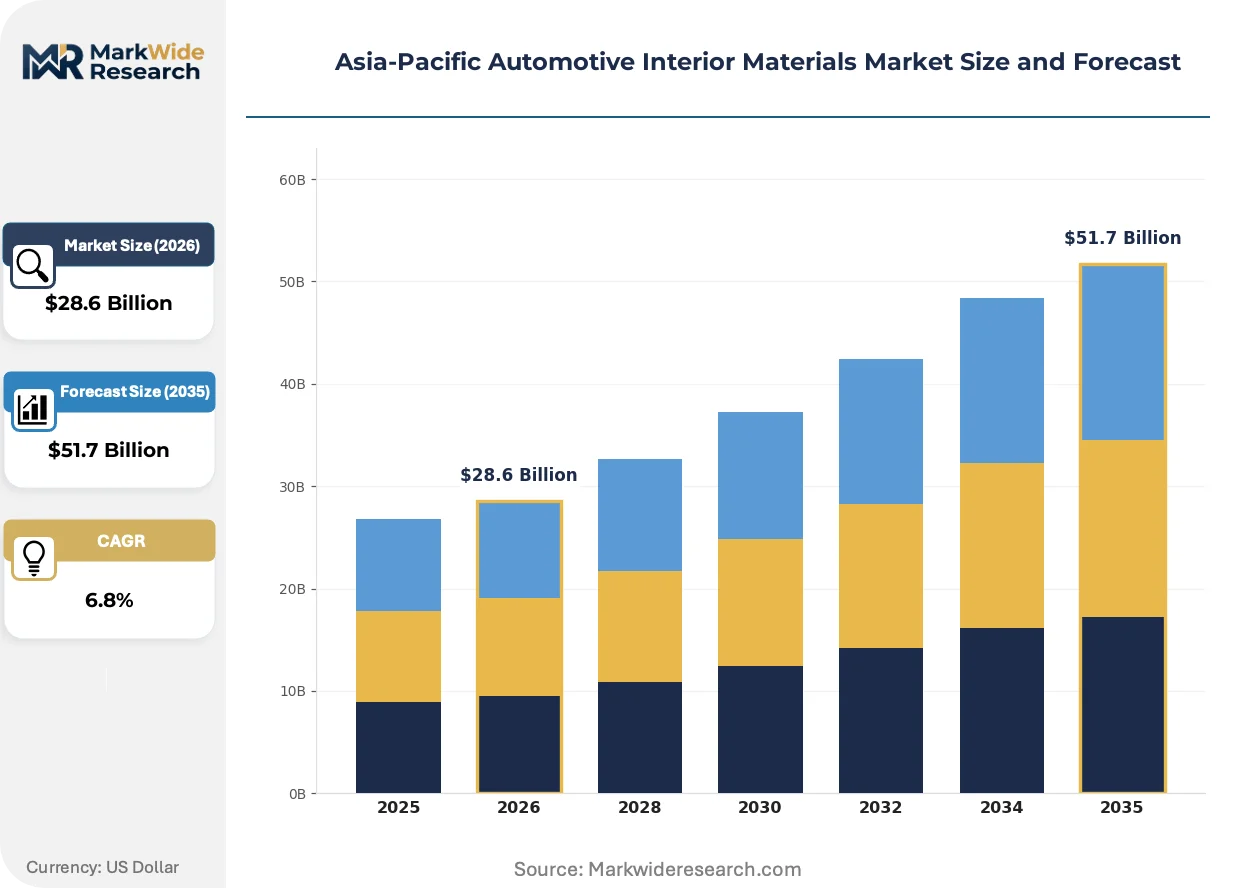
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upholstery, Dashboard, Headliner, Door Panels Material: Leather, Fabric, Vinyl, Foam Feature: Durability, Aesthetics, Comfort, Safety End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Toyota Boshoku Corporation, Toyoda Gosei Co., Ltd., Hyundai Mobis Co. Limited, Lear Corporation, Adient plc, Grupo Antolin, Continental AG, Asahi Kasei Corporation, Yanfeng Automotive Interiors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Interior Materials Market Evolving Landscape
Digital manufacturing and regulatory chemistry constraints are converging to reshape how interior materials are specified, validated, and produced across the Asia-Pacific supply base.
Digital twin simulation is digitizing acoustic foam density mapping and slush-molded skin thickness distribution before physical tooling commitment. Tier 1 integrators in Shanghai and Wuhan are deploying these platforms to compress development cycles for new EV platform launches. The technology is digitizing traditional cut-and-sew prototyping workflows that previously required six-month physical iteration loops.
China's MIIT is accelerating GB standard updates for interior air quality and flame retardancy beyond European REACH-equivalent baselines. The regulatory pressure is forcing reformulation of plasticizer systems in PVC skins and halogen-free flame retardants in PU foams. Dashboard substrate suppliers serving the Yangtze River Delta cluster are rebuilding compound libraries to maintain import eligibility under tightening substance restrictions.
Fleet operators and ride-hailing platforms are compressing interior replacement cycles from seven-year ownership spans to eighteen-month service intervals. This consumption-pattern shift is pulling demand toward modular seat architectures and replaceable wear surfaces in Southeast Asian compact EV programs. Procurement teams at Grab and Gojek are specifying material grades that prioritize stain resistance and rapid swap-out over legacy durability metrics.
Asia-Pacific Automotive Interior Materials Market Segmentation
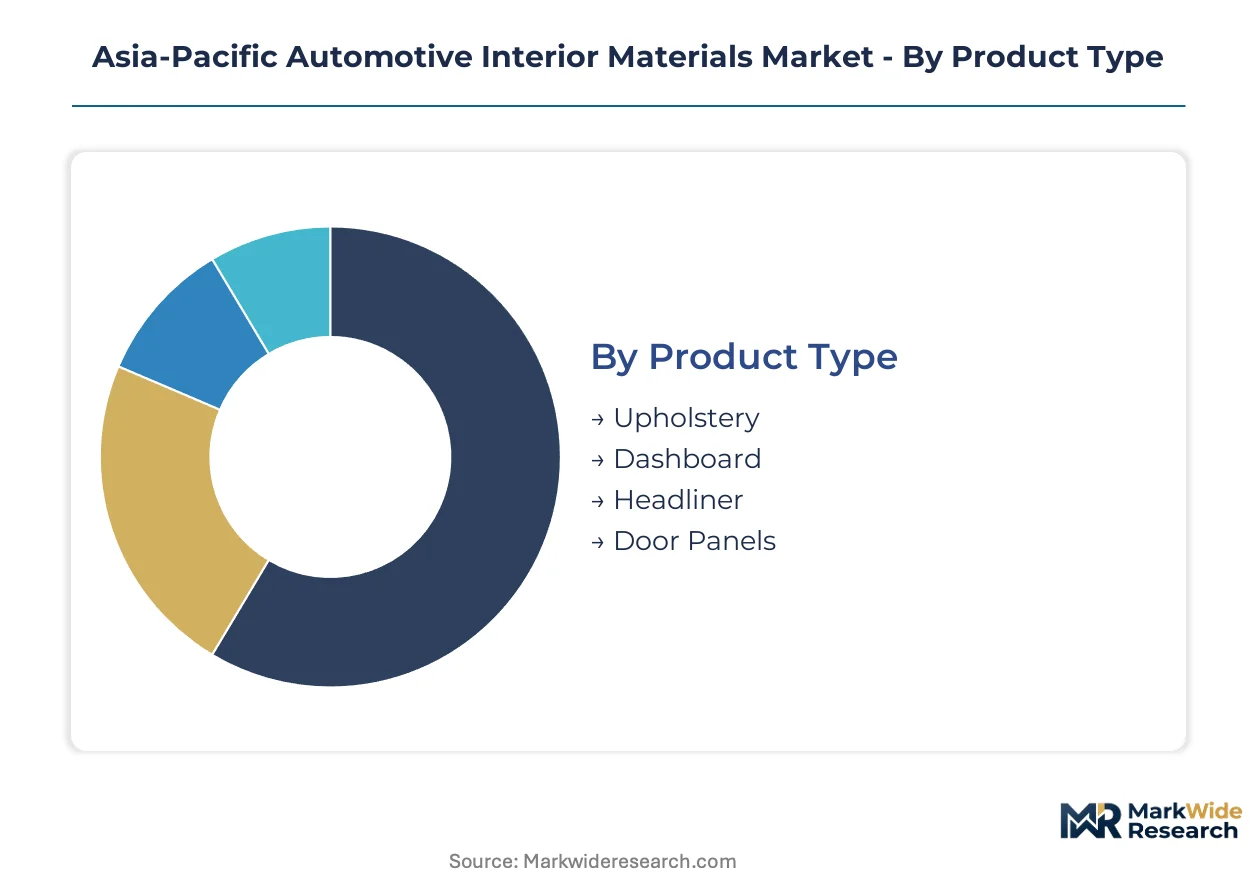
Interior material selection in the Asia-Pacific automotive sector hinges on replacement-cycle economics and service-interval intensity. Fleet operators and ride-hailing platforms are compressing refurbishment timelines from seven-year ownership spans to eighteen-month intervals, reshaping procurement priorities across every segment tier.
Product Type:
After-sales-service intensity varies dramatically by cabin zone, with high-wear surfaces demanding more frequent intervention than structural substrates.
- Upholstery:Seat covers and bolsters combine woven textiles, leather hides, or vinyl skins over polyurethane foam cores to provide occupant contact surfaces and crash energy management. Grab and Gojek procurement teams in Southeast Asia prioritize stain-resistant grades with rapid swap-out capability over legacy durability metrics for their compact EV fleets.
- Dashboard:Talc-filled polypropylene substrates bonded to soft-touch slush-molded skins meet ECE R21 head-impact criteria while housing instrument clusters and HVAC interfaces. Yangtze River Delta OEMs are validating recycled-content compounds ahead of MIIT's tightening GB standards for interior emissions.
- Headliner:Multi-layer fabric-foam composites with acoustic absorption properties span the cabin roof; Toyota Boshoku's captive production locks independent suppliers out of high-volume Japanese programs.
- Door Panels:Armrest inserts and trim surfaces integrate TPO skins over PP structural backers; vinyl applications here are accelerating fastest across cost-sensitive Southeast Asian compact EV launches.
Upholstery holds the largest share; momentum sits with door panels as modular architectures enable faster field replacement.
Material:
Cost tier stratification separates premium cabin specifications from mass-market compliance-grade alternatives.
- Leather:Full-grain and corrected-grain hides from tanneries in Tamil Nadu serve Maruti Suzuki and Hyundai Motor India premium programs; BIS safety standards tighten flame-retardancy specifications for seat applications.
- Fabric:Polyester and nylon woven textiles dominate entry-level seating and headliner applications across Vietnam and Indonesia assembly plants lacking established local supply bases.
- Vinyl:PVC skins with reformulated plasticizer systems face MIIT pressure on substance restrictions; suppliers are rebuilding compound libraries to maintain import eligibility under evolving GB standards.
- Foam:Polyurethane cores with castor oil and soy-derived polyol formulations reach commercial scale, aligning with South Korea's MFDS restrictions and China's carbon intensity targets.
Foam commands the greatest material mass per vehicle; bio-based polyurethane formulations are expanding most quickly.
Feature:
Application context determines which performance attribute takes procurement priority across passenger versus commercial vehicle programs.
- Durability:Abrasion resistance and colorfastness specifications tighten for fleet-operated vehicles with compressed replacement cycles; modular seat architectures enable rapid wear-surface exchange.
- Aesthetics:Haptic quality and visual grain consistency differentiate premium EV cabins in China's Yangtze River Delta cluster; digital twin simulation now validates slush-molded skin thickness distribution before tooling commitment.
- Comfort:Acoustic foam density mapping and pressure-distribution engineering target NVH reduction in battery-electric platforms where powertrain silence exposes road and wind noise.
- Safety:Head-impact compliance under ECE R21 and India's AIS-099 for seat strength drive substrate specification; flame-retardant formulations face halogen-free transitions under regulatory pressure.
Safety anchors regulatory compliance; comfort specifications are gaining share fastest as EV cabin refinement becomes a competitive battleground.
End User:
Supply concentration and margin structure diverge sharply between captive integrators and independent material suppliers.
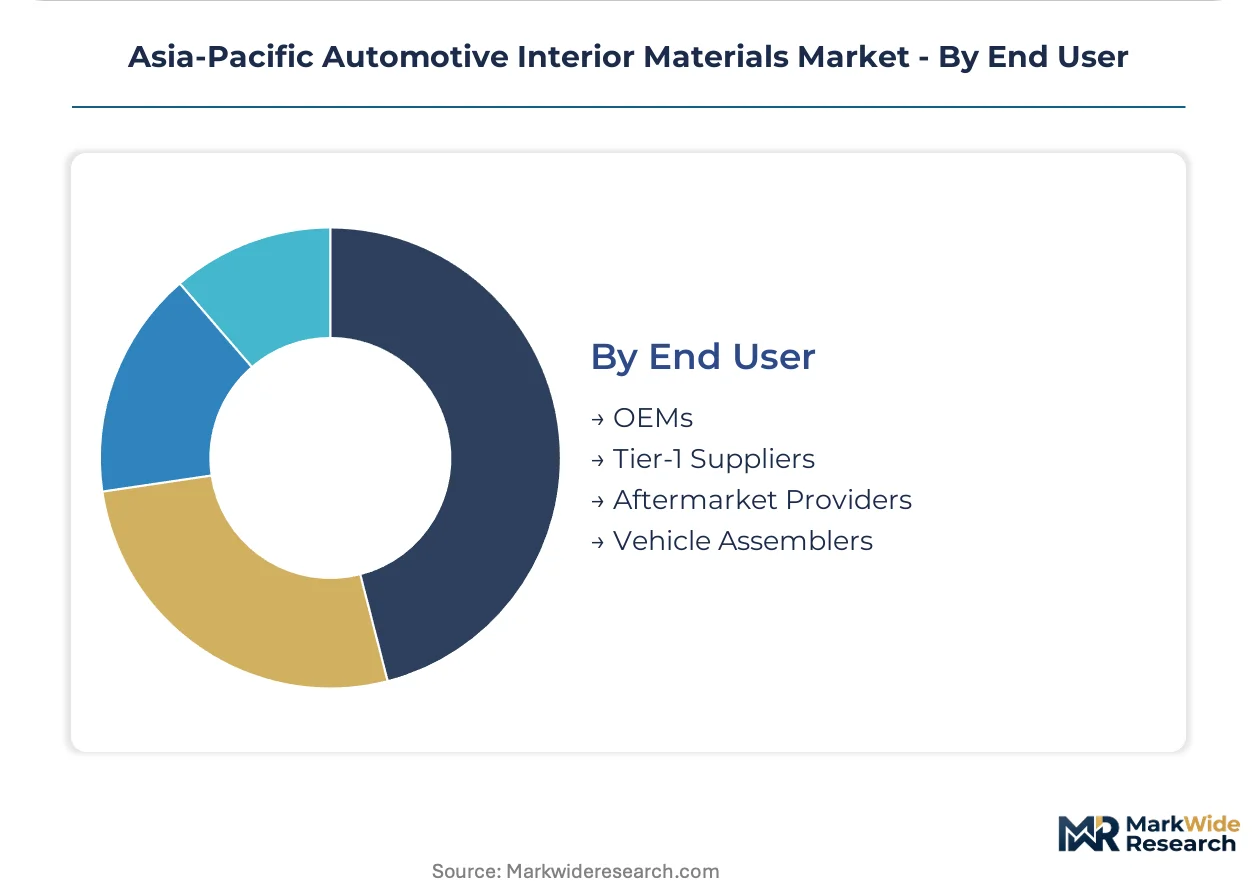
- OEMs:NIO, BYD, and Ola Electric are bypassing traditional Tier 1 integrators for direct platform contracts, opening specification influence for suppliers with acoustic and haptic validation labs.
- Tier-1 Suppliers:Yanfeng Automotive Interiors dominates cockpit module integration across Shanghai and Wuhan; Hyundai Mobis sustains Korean OEM captive demand while competing for independent EV platform contracts.
- Aftermarket Providers:Revenue is narrowing as OEMs extend warranty-linked interior refresh programs; refurbishment specialists must pivot toward fleet-operator modular swap-out services.
- Vehicle Assemblers:Tamil Nadu's concentrated automotive footprint pulls localized textile weaving and foam molding capacity to serve Maruti Suzuki and Hyundai Motor India production lines.
Tier-1 integrators retain volume dominance; direct OEM contracts are climbing the fastest as independent EV architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific region diverge sharply: China's Yangtze River Delta cluster prioritizes sustainable upholstery for premium EV cabins, while India's Tamil Nadu corridor emphasizes cost-optimized foam systems for mass-market combustion platforms. Southeast Asian assembly plants lack established local supply bases, pulling imported material grades from established production hubs.
China
Premium electric vehicle OEMs in the Yangtze River Delta are specifying acoustic foam systems and sustainable upholstery that exceed legacy combustion-era benchmarks. MIIT enforces GB standards for interior VOC emissions and flame retardancy, accelerating reformulation of polyurethane cores and slush-molded skins. Shanghai and Wuhan host concentrated cockpit module integration capacity serving domestic EV platforms.
Japan
Toyota Boshoku Corporation anchors domestic supply through captive seating and headliner production for Toyota Group vehicle programs. METI circular economy guidelines pressure suppliers to validate recycled content ratios in dashboard and door panel substrates. The Kanto region around Tokyo maintains R&D concentration for haptic quality and acoustic engineering.
India
Tamil Nadu's automotive manufacturing corridor pulls localized textile weaving and foam molding capacity to serve Maruti Suzuki and Hyundai Motor India production lines. BIS mandates AIS-099 for seat strength and head restraint performance, tightening material specifications for upholstery applications. Maharashtra and Gujarat clusters are emerging as secondary sourcing points for dashboard substrates.
South Korea
Hyundai Mobis sustains captive demand from Hyundai Motor Group while competing for independent EV platform contracts. MFDS REACH-equivalent substance restrictions shape import eligibility for European material suppliers. The Seoul Capital Area concentrates acoustic validation labs and digital twin simulation capacity for next-generation cabin development.
Vietnam
Emerging compact EV programs in northern industrial provinces lack established interior supply bases, creating positioning opportunities for foam and textile suppliers with BIS-equivalent certification capability. The country's national automotive regulator is harmonizing safety standards with ASEAN frameworks. Ho Chi Minh City and Hanoi corridors are attracting first-mover tooling investments from regional Tier 1 integrators.
Asia-Pacific Automotive Interior Materials Market Competitive Landscape
Capability concentration sits with specialized material developers possessing acoustic and haptic validation infrastructure; scale advantage sits with integrated cockpit module producers leveraging joint-venture manufacturing footprints. The market structures around three archetypes: captive suppliers serving single OEM families, independent Tier 1 integrators with multi-brand portfolios, and raw material specialists supplying compound formulations. Dominant competitive moves include direct OEM platform contracting that bypasses traditional integrators, and geographic expansion into Southeast Asian assembly corridors lacking established supply bases.
Among Japan-based suppliers, Toyota Boshoku Corporation and Toyoda Gosei Co., Ltd. exemplify the captive supply archetype through their structural ties to Toyota Group vehicle programs. Yanfeng Automotive Interiors occupies a position representing the independent integrator model with concentrated cockpit module capacity across Chinese industrial clusters. Hyundai Mobis Co. Limited sits within the Korean captive tier while simultaneously competing for external EV platform business, illustrating hybrid positioning between dependent and independent supply structures.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Toyoda Gosei Co., Ltd. |
| Hyundai Mobis Co. Limited |
| Lear Corporation |
| Adient plc |
| Grupo Antolin |
| Continental AG |
| Asahi Kasei Corporation |
| Yanfeng Automotive Interiors |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion drives freight cost volatility that feeds directly into material pricing tiers and supplier consolidation decisions across dashboard substrate and acoustic foam procurement.
Pricing Analysis
Long-term offtake contracts dominate premium upholstery and foam core supply to Yangtze River Delta EV OEMs, while spot purchasing persists for standardized vinyl skins serving Southeast Asian compact EV programs. Price differentiation rests on GB standard compliance tier and volume scale, with MIIT-certified low-VOC compounds commanding substantial premiums over baseline formulations. Cost compression in entry-level fabric seating is intensifying because Indonesian and Vietnamese assemblers lack localized weaving capacity. Fleet operators at Grab and Gojek exhibit the highest price sensitivity, prioritizing rapid swap-out economics over durability premiums.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk planning for polyurethane precursor flows serving the Asia-Pacific region. Raw material production draws from China's Sichuan basin for MDI, Japan's Kanto region for specialty polyols, and India's Tamil Nadu corridor for woven textile feedstock. Multi-material bonding in headliners creates single-source vulnerability for closed-loop recycling compliance under Japan's METI guidelines. Distribution runs through captive Tier 1 integrator networks in Shanghai and Wuhan, with independent suppliers serving aftermarket refurbishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's dual carbon goals and MIIT's accelerating GB standard updates constitute a regulatory-technology inflection that will compress material certification timelines and reshape competitive positioning across the Asia-Pacific region.
For Market Incumbents: Entrench acoustic and haptic validation capabilities through backward integration into polyurethane foam formulation, defending against independent EV platforms that bypass traditional Tier 1 integrators. Prioritize recycled-content compound libraries ahead of METI circular economy enforcement timelines to maintain import eligibility into Japanese OEM programs. For New Entrants and Emerging Players: Build out BIS-equivalent certification capability to capture first-mover positioning in Vietnam and Indonesia compact EV assembly corridors lacking established interior supply bases. Target fleet-operator modular seat architectures with stain-resistant, rapid-swap-out material grades that prioritize eighteen-month service intervals over legacy durability metrics. For Investors and Strategic Acquirers: Independent material suppliers with acoustic validation labs and direct OEM platform contracts represent the most attractive acquisition archetype for exposure to NIO, BYD, and Ola Electric specification influence. Monitor GB standard evolution velocity as the critical signal for timing recycled-content validation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Formulation | Captive MDI and polyol sourcing secures margin control against petrochemical feedstock volatility from Sichuan suppliers. |
| GB Standard Pre-Certification Investment | Early validation of low-VOC compounds maintains import eligibility under MIIT's tightening interior emissions mandates. |
| Southeast Asian Manufacturing Footprint | Localized foam molding and textile weaving capacity captures demand from Vietnam and Indonesia compact EV programs. |
| Digital Twin Simulation Deployment | Shanghai and Wuhan labs compress development cycles for acoustic foam density mapping before physical tooling commitment. |
| Fleet-Operator Direct Contracting | Grab and Gojek procurement relationships bypass traditional aftermarket channels with modular seat architecture specifications. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, polyurethane formulation chemists, and aftermarket refurbishment specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, customs and trade flow records, MIIT GB standard filings, and IHS Markit registration data. Bottom-up segmentation modeling triangulated against top-down regional production cluster assessments.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from modeled unit shipments and value-per-vehicle trajectories, incorporating feedstock cost indices for polypropylene and MDI, GB standard compliance tier premiums, and fleet-operator replacement cycle compression factors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed material compounders or accelerated AIS-099 harmonization by India's BIS would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive Grill Guard Market