
 Automotive Door Handle Sensors Market | 2026-2036
Automotive Door Handle Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Handle Sensors Market Analysis
Software-defined access features bundled with subscription-based vehicle connectivity packages is rebalancing how door handle sensors generate lifetime value for suppliers. Continental AG leverages its broad electronics portfolio to anchor integrated sensor-gateway solutions across European OEM programs. Valeo SA specializes in capacitive proximity modules that dominate premium platform specifications. Robert Bosch GmbH extends its semiconductor competency into sensor fusion architectures for multi-modal entry authentication.
Automotive door handle sensors are electromechanical detection devices, typically employing capacitive or infrared sensing elements with operating ranges of 30-80 millimeters, designed to detect human proximity or touch and trigger door release mechanisms without mechanical key insertion. Their primary commercial purpose is to enable keyless entry and passive access functions while supporting vehicle security and pedestrian alert systems. Passive sensors occupy the largest volume share as baseline equipment across mass-market vehicle lines, while biometric sensors represent the fastest-expanding category as fingerprint and palm-vein authentication migrate from luxury to mid-tier platforms. Capacitive technology leads the technology dimension due to its reliability in adverse weather conditions and lower electromagnetic interference susceptibility compared to ultrasonic alternatives.
NHTSA mandates on pedestrian warning systems for quiet electric vehicles and UNECE WP.29 cybersecurity regulations are compelling sensor suppliers to embed tamper-detection firmware and acoustic alert modules directly into door handle assemblies. ISO 26262 functional safety standards further shape development roadmaps by requiring ASIL-rated proximity detection pathways for autonomous valet and summon functions. Stakeholders must monitor how regional homologation timelines for biometric data protection create divergent product certification burdens across target markets.
Market Dynamics
Passive entry systems are displacing mechanical key cylinders across vehicle architectures, forcing sensor suppliers to reengineer detection pathways for electromagnetic compatibility with 5G vehicle-to-everything antennas and high-voltage electric powertrains.
Growth Catalysts
- NHTSA Quiet Car Rule:Mandates for pedestrian alert systems on electric vehicles require acoustic modules integrated into door handle assemblies, expanding sensor functionality beyond entry detection.
- Biometric authentication protocols:Fingerprint and palm-vein recognition modules are migrating from luxury flagships to mid-tier electric platforms, creating new sensor fusion requirements.
- Germany's automotive engineering cluster:Premium OEM development centers in Stuttgart and Munich are accelerating validation cycles for capacitive proximity systems.
Market Restraints
- Semiconductor supply concentration:Capacitive sensing ICs depend on fabrication capacity concentrated in Taiwan and South Korea, exposing programs to allocation volatility.
- UNECE WP.29 cybersecurity compliance:Tamper-detection firmware requirements add non-recurring engineering costs that compress margins on mass-market sensor variants.
- Ultrasonic substitution threat:Time-of-flight modules from industrial automation suppliers are encroaching on entry-system specifications with lower electromagnetic susceptibility.
Strategic Opportunities
- India's electric vehicle subsidy schemes:PLI scheme incentives for domestic manufacturing are drawing sensor suppliers to establish assembly operations near Chennai and Pune.
- Autonomous valet parking:ASIL-rated proximity detection for summon functions requires redundant sensor pathways, expanding content per vehicle.
- Subscription-based feature activation:Over-the-air unlock for heated handles and welcome lighting creates recurring revenue streams from hardware already installed.
Industry Challenges
- ISO 26262 functional safety certification:ASIL-B pathway validation for autonomous entry functions extends development timelines by 8-14 months.
- Legacy vehicle electrical architectures:Controller area network bandwidth constraints in 2015-2020 model-year platforms complicate retrofit of multi-modal authentication systems.
- Electromagnetic interference mitigation:Shielding capacitive sensors from 77 GHz radar and 5G millimeter-wave antennas requires iterative hardware-software co-design cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Handle Sensors Market |
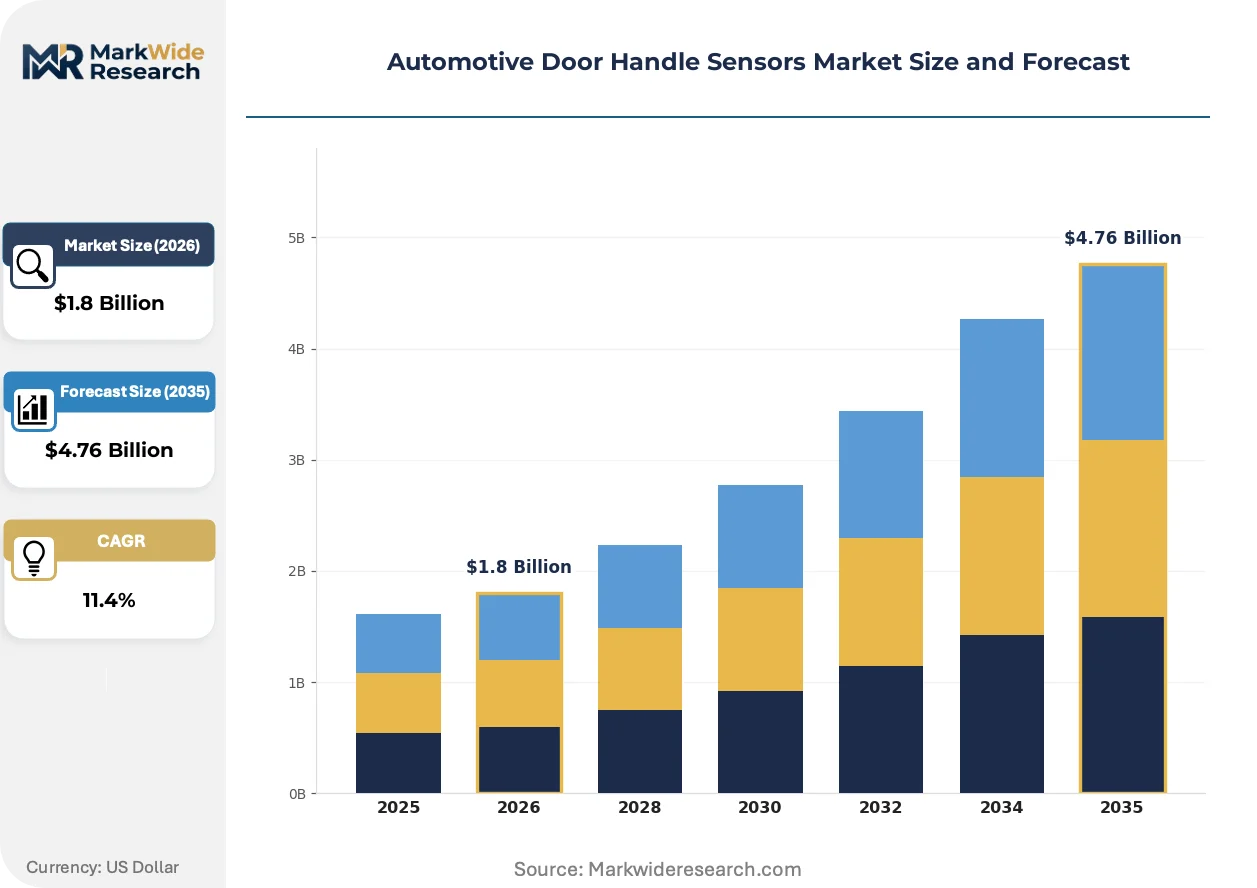
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Sensors, Active Sensors, Biometric Sensors, Proximity Sensors Technology: Infrared, Capacitive, Ultrasonic, Bluetooth End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Integrated, Retrofit, Custom Solutions, Standardized Kits |
| Companies Covered | Valeo SA, Hella GmbH & Co. KGaA, Continental AG, Aisin Seiki Co., Ltd., U-Shin Ltd., Robert Bosch GmbH, Magna International Inc., NXP Semiconductors, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Handle Sensors Market Emerging Trajectories
Sensor architectures are converging with domain controllers and vehicle connectivity stacks, compressing the traditional boundary between entry systems and central computing platforms.
Capacitive proximity detection is consolidating around multi-electrode designs that combine entry authentication, intrusion detection, and pedestrian alert functions within single housing units. Tier 1 suppliers are integrating these modules into zonal electronic control units to reduce wiring harness complexity. This consolidation is compressing the addressable market for discrete sensor suppliers while expanding lifetime value for integrated system vendors.
EU AI Act classification of biometric authentication systems as high-risk AI is mandating conformity assessments for fingerprint and palm-vein modules before CE marking. German KBA type-approval processes now require documented algorithmic bias testing for skin-tone detection accuracy. European premium OEMs are responding by pre-qualifying suppliers with established functional safety management systems.
Fleet operators and mobility service providers are unbundling after-sales sensor calibration from warranty packages, treating door handle modules as consumable components with predictive replacement schedules. Subscription platforms for commercial vehicle pools are capturing this service revenue directly. This shift is most visible in Germany's corporate fleet segment and Japan's taxi-hailing operator networks.
Automotive Door Handle Sensors Market Segmentation
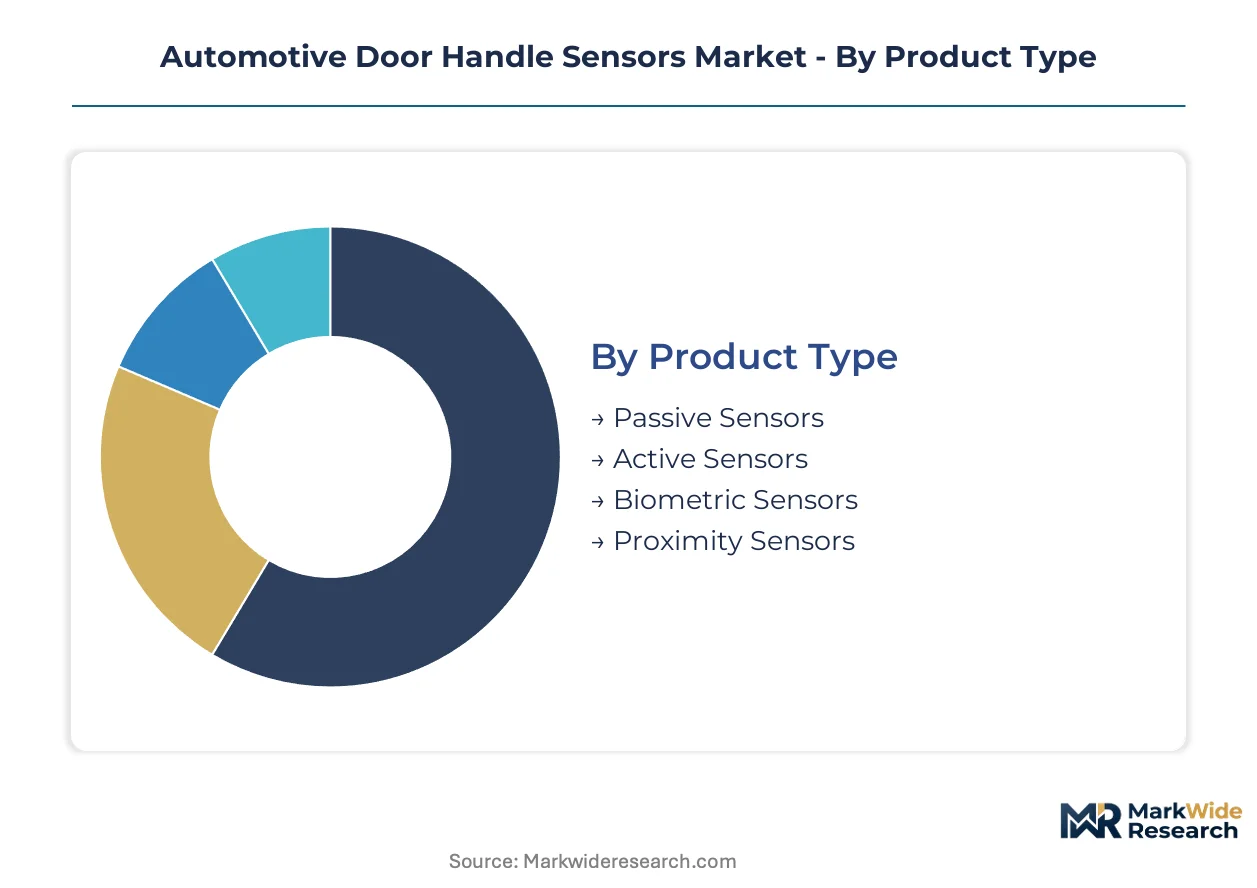
Door handle sensor architectures fragment across detection modalities, supply chain tiers, and integration depth. Each segmentation dimension carries distinct margin profiles and certification burdens that reshape supplier positioning.
Product Type:
Volume concentration sits with baseline passive detection modules, while premium platforms drive biometric authentication adoption.
- Passive Sensors:Electromechanical proximity modules detect key fob presence through low-frequency field generation without driver initiation. These dominate mass-market electric vehicle programs across Germany, Japan, and the United States as baseline equipment where NHTSA pedestrian alert mandates expand functionality per unit.
- Biometric Sensors:Fingerprint and palm-vein authentication modules integrate capacitive imaging or infrared vascular pattern recognition. Demand concentrates in Stuttgart and Munich engineering centers as premium OEMs validate multi-factor entry protocols ahead of EU AI Act conformity assessments.
- Active Sensors:Driver-initiated touch detection systems requiring deliberate physical contact for activation.
- Proximity Sensors:Extended-range detection modules for hands-free entry triggering at 50-80 millimeter distances.
Today's leader: Passive Sensors. Tomorrow's challenger: Biometric Sensors.
Technology:
Cost tier stratification separates field-proven capacitive designs from emerging ultrasonic alternatives with superior electromagnetic immunity.
- Capacitive:Electrode-based field disturbance detection operates reliably across temperature extremes and moisture exposure. This technology anchors European premium platform specifications where Valeo SA and Continental AG supply integrated modules for Stuttgart-based OEM programs.
- Infrared:Time-of-flight and reflectance-based proximity detection using near-infrared emitters and photodiode receivers. These modules serve Japanese OEM flagship lines where METI energy efficiency guidelines favor low-power standby architectures.
- Ultrasonic:Piezoelectric transducer systems measuring acoustic echo return times for distance calculation.
- Bluetooth:Received signal strength indication leveraging smartphone presence for entry authorization.
Capacitive technology commands current volume. Ultrasonic alternatives are gaining specification traction fastest.
End User:
Supply concentration flows through vehicle assemblers and their captive Tier-1 networks, constraining aftermarket access to calibration-dependent replacement cycles.
- OEMs:Original equipment manufacturers specifying sensor architectures during platform development and controlling firmware update distribution. German premium brands in Munich and Stuttgart integrate door handle modules into zonal ECU strategies that compress discrete supplier margins.
- Tier-1 Suppliers:System integrators such as Continental AG, Valeo SA, and Robert Bosch GmbH managing electromechanical assembly, software validation, and OEM program execution across multiple vehicle lines simultaneously.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities executing build-to-print sensor installation.
- Aftermarket Providers:Independent distributors serving collision repair and fleet maintenance channels with replacement modules.
Margin capture concentrates with Tier-1 Suppliers. Aftermarket Providers face firmware lockout constraints.
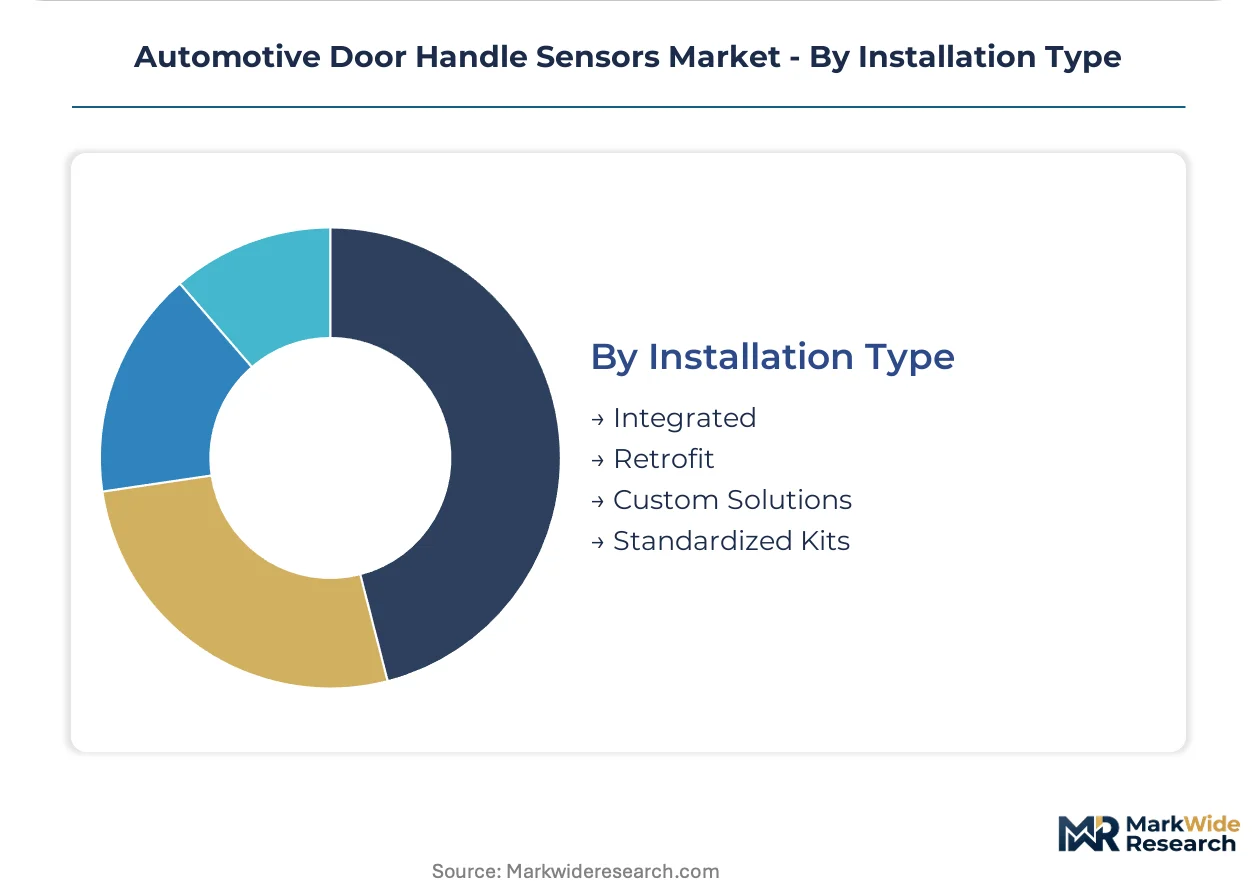
Installation Type:
Maturity gradient separates factory-integrated architectures from retrofit solutions limited by legacy CAN bandwidth constraints.
- Integrated:Door handle sensors designed into vehicle electrical architectures during platform development with dedicated wiring harness routing and domain controller connectivity. This approach dominates United States electric vehicle programs where NHTSA mandates require acoustic alert module co-location.
- Retrofit:Post-manufacture installation kits for vehicle modification and fleet conversion applications.
- Custom Solutions:Bespoke sensor configurations for limited-production vehicles and commercial specialty applications.
- Standardized Kits:Universal-fit modules targeting aftermarket replacement and regional homologation flexibility.
Integrated installations define current revenue. Retrofit solutions confront 2015-2020 platform compatibility barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium platform engineering while the United States drives regulatory-mandated acoustic integration, creating divergent certification pathways for door handle sensor suppliers across both markets.
United States
NHTSA Quiet Car Rule mandates anchor acoustic module demand for electric vehicle door handle assemblies. Detroit-based OEM development centers prioritize integrated sensor-gateway architectures that compress discrete supplier margins. California's zero-emission vehicle fleet requirements accelerate passive entry standardization across mass-market electric platforms.
Germany
EU AI Act conformity assessments reshape biometric authentication supplier qualification timelines. Stuttgart and Munich engineering clusters validate multi-factor entry protocols for premium OEM flagship lines. KBA type-approval processes now require documented algorithmic bias testing for skin-tone detection accuracy in fingerprint modules.
Japan
METI energy efficiency guidelines favor low-power standby architectures for infrared-based proximity detection. Toyota City and Nagoya supplier networks specialize in capacitive imaging modules for palm-vein authentication systems. Domestic OEMs integrate door handle sensors into zonal ECU strategies that reduce wiring harness complexity.
China
MIIT new energy vehicle subsidy schemes accelerate domestic sensor assembly capacity expansion near Shanghai and Shenzhen. GB standards for electromagnetic compatibility constrain capacitive sensor designs operating alongside 77 GHz radar systems. Yangtze River Delta fabrication clusters concentrate capacitive sensing IC backend packaging operations.
India
PLI scheme incentives for domestic manufacturing draw sensor suppliers to establish assembly operations near Chennai and Pune. BIS certification requirements for automotive electronics create homologation bottlenecks for imported modules. Tamil Nadu's electric vehicle manufacturing corridor anchors validation programs for tropical climate sensor durability testing.
Automotive Door Handle Sensors Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors capturing margin expansion from zonal ECU consolidation while discrete sensor suppliers confront pricing pressure. The supplier base organizes around three archetypes: diversified electronics conglomerates with semiconductor competencies, dedicated automotive sensor specialists with OEM captive relationships, and contract manufacturers executing build-to-print assembly. Dominant competitive moves include backward integration into sensing IC design and strategic partnerships with domain controller suppliers to anchor gateway positions.
Within the diversified electronics tier, Continental AG and Robert Bosch GmbH exemplify integrated system vendors leveraging broad semiconductor portfolios to capture zonal ECU consolidation benefits. Valeo SA represents the dedicated sensor specialist archetype, occupying a position anchored in capacitive proximity module supply relationships with European premium OEMs. These three companies sit within distinct strategic postures regarding vertical integration depth and software-defined feature monetization.
| Leading Market Players |
|---|
| Valeo SA |
| Hella GmbH & Co. KGaA |
| Continental AG |
| Aisin Seiki Co., Ltd. |
| U-Shin Ltd. |
| Robert Bosch GmbH |
| Magna International Inc. |
| NXP Semiconductors |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Capacitive sensing IC fabrication migration toward 200-millimeter wafer processes simultaneously compresses per-unit die costs and concentrates backend packaging operations in Taiwan and South Korea, reshaping how sensor suppliers negotiate volume commitments with automotive OEMs.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for capacitive sensing modules as foundry competition intensifies. Three-tier pricing structure across premium biometric, standard passive entry, and economy active-touch levels stratifies by ASIL certification grade and firmware customization depth. Pricing pressure stems from ultrasonic time-of-flight alternatives gaining specification traction in electromagnetic-sensitive electric vehicle architectures. Mass-market OEMs exhibit highest price sensitivity, while premium brands in Stuttgart and Munich absorb biometric authentication premiums.
Supply Chain Analysis
Capacitive electrode substrates rest on Japanese specialty chemical producers for high-purity copper foil and German engineering centers for precision stamping tooling. Raw material dependencies include silicon wafers, rare-earth magnets for acoustic alert modules, and fluoropolymer coatings for moisture resistance. Single-source vulnerability concentrates in Taiwan-based foundry capacity for proximity detection ASICs. Distribution runs through captive Tier-1 supplier networks with OEM-controlled firmware update channels limiting aftermarket access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive door handle sensors offer margin expansion as zonal ECU consolidation raises content per vehicle and subscription-based feature activation extends revenue recognition timelines beyond hardware shipment.
For Market Incumbents: Anticipate ultrasonic substitution threats by anchoring capacitive designs in ASIL-B certification pathways that time-of-flight modules cannot yet satisfy. Deepen backward integration into sensing IC design to secure allocation priority during foundry constraints. Pre-qualify biometric firmware against EU AI Act conformity assessments before KBA type-approval timelines tighten. For New Entrants and Emerging Players: Ultrasonic sensor fusion for multi-modal entry authentication offers a technology-first wedge into mid-tier electric vehicle programs where electromagnetic interference mitigation commands specification priority. Target India's PLI scheme manufacturing corridors near Chennai and Pune for assembly cost advantages. Pursue fleet operator direct relationships for predictive replacement service contracts bypassing OEM captive networks. For Investors and Strategic Acquirers: Valuations sit cheapest among discrete sensor suppliers confronting zonal ECU margin compression, while integrated system vendors with semiconductor competencies capture gateway positioning premiums. Long-term viability favors suppliers with established functional safety management systems and biometric algorithm portfolios. Watch NHTSA pedestrian alert rule expansion to hybrid vehicle segments as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Certification | EU AI Act conformity assessments for fingerprint modules secure KBA type-approval priority in Stuttgart engineering centers. |
| Zonal ECU Integration | Domain controller partnerships with German premium OEMs compress discrete supplier margins while expanding lifetime value capture. |
| Foundry Capacity Securement | Long-term supply agreements with Taiwan-based fabrication facilities mitigate allocation volatility for capacitive sensing ICs. |
| Subscription Feature Activation | Over-the-air unlock capabilities for heated handles generate recurring revenue from hardware already installed across vehicle fleets. |
| Tropical Climate Validation | Tamil Nadu durability testing programs establish qualification credentials for India's expanding electric vehicle manufacturing corridor. |
Methodological Framework
Coverage spans Germany, Japan, the United States, China, and India, with primary inputs from each market cluster. The analysis combines structured interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA rulemaking dockets, and KBA type-approval records. Bottom-up sensor shipment modeling triangulates against top-down electric vehicle production forecasts.
Rate-of-change decomposition separates volume growth from content-per-vehicle expansion across the projection horizon. The analytical framework models segmentation dimensions including detection modality, technology type, vehicle class, propulsion architecture, and regional production cluster. CAGRs derive from fitted growth curves applied to OEM platform rollout schedules and regulatory mandate phase-in timelines. Industry-specific inputs include NHTSA Quiet Car Rule compliance deadlines and EU AI Act implementation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation shifts, UNECE WP.29 cybersecurity rule expansion, and ultrasonic technology specification gains. Forecasts reflect documented assumptions about electric vehicle penetration rates and premium platform biometric adoption curves. A small set of named triggers—including semiconductor supply disruption, regional biometric data protection rule divergence, and autonomous valet parking regulatory clearance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market